
 Spain Dental Devices Market | 2026-2036
Spain Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Dental Devices Market Analytics
EU MDR implementation is consolidating the cost-of-entry calculus for dental device manufacturers seeking Spanish market authorization. Dentsply Sirona leverages its broad imaging and treatment center portfolio to sustain multi-channel presence across Iberian dental schools and clinic chains. Straumann Group anchors its position through intensive R&D in implant surface technologies and digital workflow integration. Henry Schein competes on distribution density, controlling supply routes into Spain's fragmented clinic base.
Dental devices encompass precision-engineered instruments, prosthetics, and diagnostic equipment manufactured from biocompatible alloys, ceramics, and polymers to restore oral function and aesthetics. CAD/CAM milling units achieve micron-level accuracy in crown fabrication, while 3D printing enables patient-specific surgical guides and denture bases. Implantology generates the deepest margin pools due to recurring component sales and maintenance protocols. CAD/CAM technology represents the fastest-expanding technology segment as Spanish laboratories retire analog workflows. Cosmetic dentistry applications command premium positioning among private-pay patients in urban centers.
Spain's national pharmaceutical regulator, AEMPS, enforces EU MDR conformity assessment for all active implantable and Class IIb dental devices, extending approval timelines and documentation burdens. BSI Group and TÜV SÜD operate as notified bodies processing Spanish manufacturer certifications under tightened MDR capacity constraints. The EU AI Act introduces forthcoming algorithmic transparency requirements for AI-assisted imaging diagnostics deployed in Spanish hospitals. Stakeholders must monitor notified body capacity bottlenecks and preemptive compliance investments in software validation to preserve market access velocity.
Market Dynamics
EU MDR alignment is compressing market access timelines for dental device manufacturers while simultaneously accelerating consolidation among notified body-dependent suppliers. Spanish laboratories face binary choices between costly compliance investments and exit.
Growth Catalysts
- Digital workflow penetration:CAD/CAM systems replace analog crown fabrication across Catalonia's laboratory network, reducing turnaround from weeks to hours.
- AEMPS vigilance expansion:Spain's national pharmaceutical regulator enforces post-market surveillance mandates that favor established suppliers with robust quality management systems.
- Implantology protocol standardization:Recurring maintenance revenue from osseointegrated fixtures creates predictable aftermarket income streams for specialized clinics.
Market Restraints
- Titanium alloy cost volatility:Implant-grade Ti-6Al-4V feedstock price swings compress margin predictability for domestic manufacturers.
- Notified body capacity bottleneck:BSI Group and TÜV SÜD processing queues extend Spanish manufacturer certification timelines by 8-14 months.
- Intraoral scanner substitution:Chairside digital impressions displace traditional alginate and silicone materials in restorative workflows.
Strategic Opportunities
- Andalusian clinic network expansion:Underpenetrated southern provinces present whitespace for implantology-focused service models.
- AI-assisted radiography convergence:Machine learning diagnostic tools paired with cone-beam CT systems enable treatment planning automation.
- Direct-to-laboratory distribution:E-procurement platforms bypass traditional dental supply intermediaries in Madrid and Barcelona metropolitan zones.
Industry Challenges
- CAD/CAM technician scarcity:Digital design competencies lag hardware deployment across Spanish dental technology programs.
- EU AI Act software validation:Algorithmic transparency documentation requirements for diagnostic imaging tools demand preemptive compliance engineering.
- Legacy analog integration friction:Hybrid workflows combining conventional and digital methods create quality control inconsistencies in crown fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Dental Devices Market |
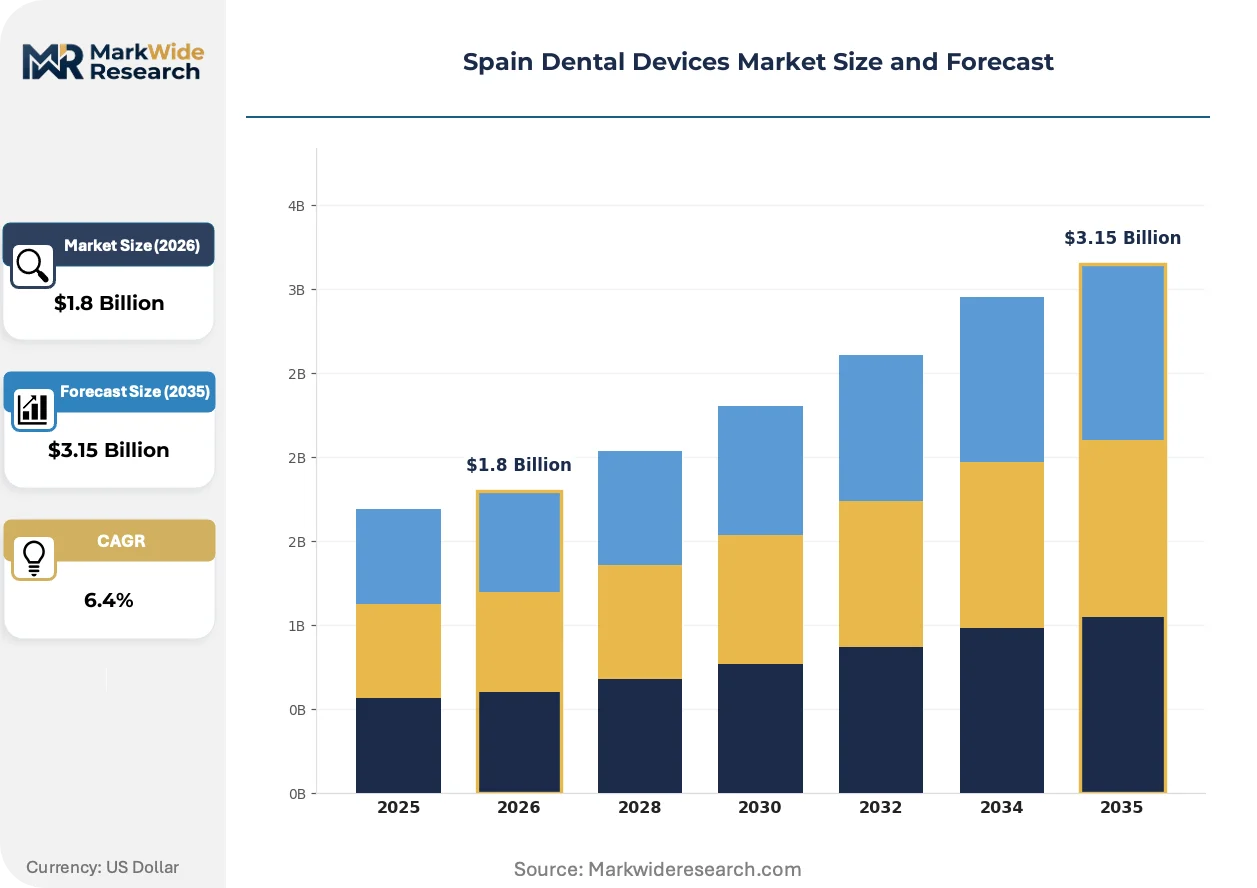
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodontics, Implants, Crowns, Bridges Technology: CAD/CAM, Laser, 3D Printing, Imaging Systems End User: Dental Clinics, Hospitals, Research Institutions, Laboratories Application: Cosmetic Dentistry, Restorative Dentistry, Periodontics, Endodontics |
| Companies Covered | Dentsply Sirona, Straumann Group, 3M, Envista Holdings, Henry Schein, Zimmer Biomet, Ivoclar Vivadent, Align Technology, Klockner Implant System, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Dental Devices Market Evolving Landscape
Chairside manufacturing capabilities are collapsing the traditional laboratory-clinic boundary. Spanish providers now capture value previously outsourced to prosthetic technicians.
Intraoral scanning hardware is electrifying diagnostic workflows across Madrid's private clinic clusters. Single-visit crown fabrication eliminates temporary prosthesis stages and second-appointment logistics. Ceramic milling units operating at micron tolerances compress treatment timelines from two weeks to under two hours.
EU MDR technical documentation requirements are restructuring supplier economics across Iberian markets. Extended conformity assessment timelines favor manufacturers with pre-existing quality management certifications under the previous directive. Class IIb active devices face the steepest documentation burden increases, forcing portfolio rationalization among mid-tier competitors.
Patient preference for same-day dentistry is redirecting procurement priorities among Spanish clinic chains. Capital allocation shifts from laboratory outsourcing contracts toward in-house milling and sintering equipment. Urban private-pay segments in Barcelona and Valencia demonstrate the strongest concentration of chairside adoption, with reimbursement-independent pricing enabling rapid payback on digital infrastructure investments.
Spain Dental Devices Market Segmentation
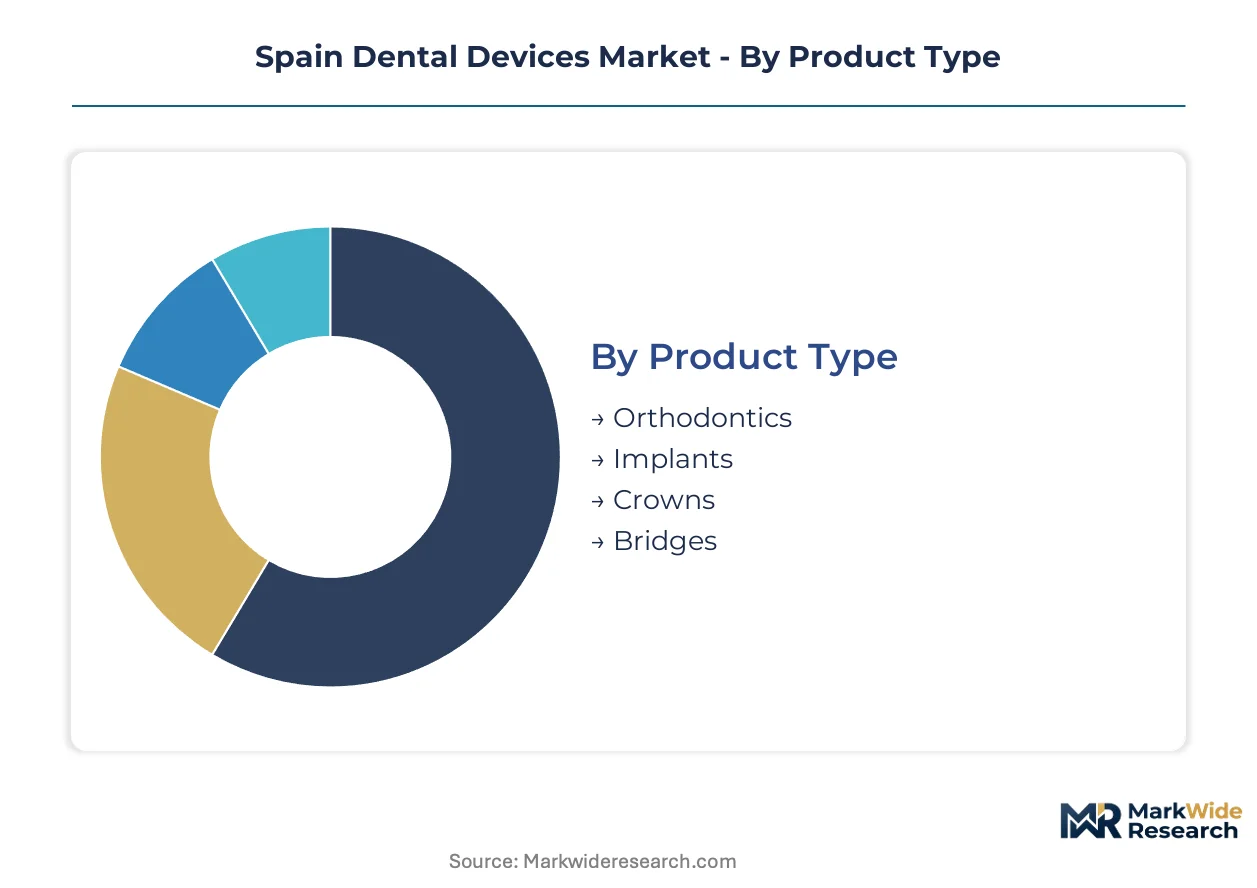
Segmentation reveals how EU MDR certification burdens concentrate differently across product categories, with active implantable devices facing steeper conformity assessment timelines than passive prosthetics. Understanding these tiered compliance pathways enables manufacturers to prioritize portfolio investments and anticipate notified body capacity bottlenecks.
Product Type:
Implants and active orthodontic systems carry Class IIb and Class III designations under EU MDR, demanding extended technical documentation and clinical evidence portfolios from AEMPS and notified bodies including BSI Group and TÜV SÜD.
- Orthodontics:Clear aligner systems and fixed bracket appliances fabricated from medical-grade polymers and stainless steel alloys. Demand clusters in Madrid's adolescent patient segments and adult cosmetic correction markets, with digital treatment planning software reducing chairside adjustment frequency.
- Implants:Titanium alloy root-form fixtures and abutment components engineered for osseointegration, requiring biocompatibility testing under ISO 10993 and extended MDR clinical evaluation. Catalonia's dense specialist clinic network generates recurring aftermarket revenue from maintenance protocols and component replacement cycles.
- Crowns:Zirconia and lithium disilicate restorations milled to micron tolerances, with Class IIa certification pathways shorter than implantable categories.
- Bridges:Multi-unit fixed prostheses spanning edentulous spans, fabricated through either conventional casting or CAD/CAM sintering methods.
Leading the category by volume: Crowns. Expanding most quickly: Implants.
Technology:
Cost tier stratification separates capital-intensive chairside systems from consumable-focused workflows, with milling units and cone-beam CT hardware commanding premium positioning against disposable surgical guide materials.
- CAD/CAM:Computer-aided design and manufacturing systems encompassing intraoral scanners, chairside milling units, and laboratory-grade sintering furnaces. Barcelona's private clinic chains drive hardware procurement as same-day crown fabrication eliminates laboratory outsourcing fees and second-appointment logistics.
- Laser:Soft-tissue surgical and teeth-whitening systems operating at specific wavelengths for precise ablation, with Class IIb active device classification extending approval timelines.
- 3D Printing:Photopolymer and metal powder bed fusion systems producing surgical guides, denture bases, and temporary restorations at point-of-care.
- Imaging Systems:Digital radiography sensors and cone-beam CT scanners enabling three-dimensional treatment planning for complex implantology cases.
Hardware concentration: CAD/CAM systems. Steepest expansion trajectory: 3D Printing.
End User:
Customer type determines procurement channel structure, with fragmented clinic bases favoring distributor intermediaries while consolidated hospital systems negotiate direct manufacturer contracts.
- Dental Clinics:Private practices and clinic chains across Madrid, Barcelona, and Valencia metropolitan zones, representing the primary volume channel for restorative and cosmetic device procurement.
- Hospitals:Maxillofacial surgery departments and dental units within Spain's public health system, requiring tender-based procurement and extended validation protocols.
- Research Institutions:University dental schools and biomedical engineering centers conducting clinical trials and post-market surveillance under AEMPS oversight.
- Laboratories:Prosthetic technicians and dental technology centers transitioning from analog wax-and-cast methods to digital design workflows.
Volume leadership: Dental Clinics. Fastest channel growth: Laboratories.
Application:
Margin structure varies by reimbursement dependency, with private-pay cosmetic procedures commanding premium pricing against partially covered restorative interventions.
- Cosmetic Dentistry:Veneer, whitening, and aesthetic alignment procedures targeting private-pay patients in urban centers, with pricing independent of public reimbursement schedules.
- Restorative Dentistry:Crown, bridge, and implant reconstruction of damaged dentition, representing the foundational revenue base across Spanish general practices.
- Periodontics:Surgical and non-surgical management of supporting tissue structures, with specialized instrument kits and regenerative membrane products.
- Endodontics:Root canal treatment systems including nickel-titanium rotary files and obturation materials for pulp therapy.
Revenue concentration: Restorative Dentistry. Gaining share fastest: Cosmetic Dentistry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's dental devices market concentrates in autonomous communities with dense private clinic networks and advanced healthcare infrastructure. Regional disparities in digital adoption and reimbursement frameworks create tiered opportunity landscapes across the Iberian Peninsula.
Catalonia
Barcelona anchors Spain's highest CAD/CAM penetration rates among private dental laboratories. The Catalan Health Service maintains selective reimbursement for implantology procedures, channeling demand toward premium restorative workflows. Girona and Tarragona clinic clusters are expanding chairside milling capabilities to capture same-day crown revenue.
Madrid
The capital region generates concentrated demand for cosmetic dentistry among private-pay urban patients. AEMPS maintains its headquarters here, accelerating regulatory consultation access for device manufacturers seeking EU MDR conformity. Pozuelo de Alarcón and Majadahonda clinic chains are deploying intraoral scanner networks across suburban locations.
Andalusia
Seville and Málaga present underpenetrated whitespace for implantology service models targeting medical tourism segments. The Andalusian Regional Ministry of Health operates tender-based procurement for public hospital dental units, extending validation timelines for new device categories. Cádiz and Granada are emerging as cost-competitive laboratory outsourcing destinations.
Basque Country
Bilbao's industrial base supports precision machining subcontractors serving dental implant manufacturers. The Basque Health Service (Osakidetza) enforces stringent post-market surveillance protocols that favor established suppliers with robust quality management systems. San Sebastián dental schools are integrating digital workflow training into prosthetic technology curricula.
Valencia
The Valencia metropolitan zone demonstrates accelerating clear aligner demand among adult cosmetic correction segments. The regional health ministry's medical device vigilance unit coordinates with AEMPS on adverse event reporting for active orthodontic devices. Alicante's private clinic density is expanding through franchise models replicating Madrid's digital dentistry portfolios.
Spain Dental Devices Market Competitive Landscape
Swiss and German producers anchor the premium implantology tier; North American distributors hold procurement channel control across Spain's fragmented clinic base. The market structure consolidates around three strategic archetypes: full-solution manufacturers with imaging-to-restoration portfolios, specialized implant surface technology developers, and supply chain intermediaries with dense logistics networks. M&A activity targets digital workflow software capabilities, while geographic expansion concentrates on southern Spanish provinces.
Among Switzerland-based implant specialists, Straumann Group exemplifies the R&D-intensive archetype through intensive development in osseointegration surface technologies. Dentsply Sirona occupies a position spanning imaging hardware and treatment center integration across Iberian dental schools. Henry Schein anchors the distribution-focused tier, controlling supply routes into Spain's fragmented clinic base through multi-channel procurement relationships.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Straumann Group |
| 3M |
| Envista Holdings |
| Henry Schein |
| Zimmer Biomet |
| Ivoclar Vivadent |
| Align Technology |
| Klockner Implant System |
| Others |
Value Network & Pricing Analysis
EU MDR certification tiers split Spain's dental device market into parallel pricing tracks, with Class IIb and III implantable systems commanding premium positioning against Class IIa prosthetics while simultaneously demanding extended notified body queues that reshape supplier inventory strategies and working capital requirements.
Pricing Analysis
Volume concentration in crowns and bridges runs against margin depth in implantology, creating divergent profitability profiles across product categories. Three-tier pricing structure across premium, standard, and economy levels separates Swiss and German implant manufacturers from mid-tier Asian suppliers and domestic Spanish laboratories. Pricing pressure stems from titanium alloy feedstock volatility compressing margin predictability for domestic manufacturers. Public hospital procurement committees exhibit highest price sensitivity, while private cosmetic dentistry patients in Madrid and Barcelona demonstrate lowest elasticity.
Supply Chain Analysis
Freight cost differentials between air and sea lanes determine inventory positioning for Spanish distributors managing just-in-time clinic replenishment. Manufacturing concentration centers on Switzerland, Germany, and the United States for precision implant systems, while zirconia blanks and milling burs draw from Japanese and Chinese ceramic suppliers. Single-source vulnerability runs through titanium sponge processing for implant-grade Ti-6Al-4V. Distribution runs through Henry Schein's Iberian logistics network and regional dental supply cooperatives serving fragmented clinic bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's dental device sector occupies a technology-transition phase where intraoral scanning and chairside milling displace alginate impressions and laboratory outsourcing contracts.
For Market Incumbents: Deploy backward integration into zirconia blank manufacturing to defend margin position against Asian ceramic suppliers. Lock long-term service contracts with Catalonia's dense specialist clinic network to secure recurring aftermarket revenue from implant maintenance protocols. Preempt EU AI Act compliance engineering for diagnostic imaging software to preserve market access velocity against regulatory delay. For New Entrants and Emerging Players: AI-assisted radiography tools offer the most penetrable wedge for software-first entrants lacking hardware manufacturing scale. Target Andalusia's underpenetrated southern provinces where medical tourism demand outpaces local implantology capacity. Pursue direct-to-laboratory e-procurement distribution to bypass entrenched supply intermediaries in Madrid and Barcelona metropolitan zones. For Investors and Strategic Acquirers: Exit pathways concentrate in digital workflow software acquisitions by full-solution manufacturers seeking imaging-to-restoration integration. Five-to-ten year viability hinges on notified body capacity expansion resolving MDR certification bottlenecks. Monitor BSI Group and TÜV SÜD queue length disclosures as inflection indicator for Spanish manufacturer market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Accelerated EU MDR conformity assessment preserves Spanish market access against notified body bottlenecks. |
| Chairside Milling Deployment | Same-day crown fabrication captures laboratory outsourcing value previously lost to external technicians. |
| Implant Surface Technology R&D | Osseointegration performance differentiation sustains premium positioning against commoditized fixture competition. |
| Hospital System Partnership | Direct procurement relationships with Madrid's maxillofacial surgery departments secure tender-based volume commitments. |
| Software Companion Development | AI-assisted treatment planning tools paired with cone-beam CT systems enable diagnostic workflow automation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dental clinic owners, prosthetic laboratory technicians, biomedical engineers at Spanish dental schools, and GPO contracts managers informed demand-side validation. AEMPS device registration databases, EU MDR technical documentation disclosures, and Spanish customs import records supplied supply-side triangulation. Bottom-up clinic procurement modeling and top-down manufacturer shipment analysis were reconciled to derive market estimates.
Data-stream reconciliation across shipment volumes, clinic capital expenditure surveys, and laboratory technology adoption metrics produced segmentation-level outputs. Product type, technology platform, end-user channel, and application use-case dimensions were modeled across the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical adoption rates of comparable medical device categories. Titanium alloy price indices and notified body capacity constraints were incorporated as scenario variables.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended MDR certification timelines or accelerated AI Act implementation. Forecasts reflect assumptions regarding digital workflow penetration rates and southern Spanish clinic network expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental CAD/CAM Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Glenoid Fossa Prosthesis Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Dental Fittings Market