
 Digital Facebow Market | 2026-2036
Digital Facebow Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Facebow Market Insights
Aftermarket service revenue from calibration and software updates is reshaping profit pools in the digital facebow landscape. 3Shape leverages its open-platform architecture to sustain recurring revenue from dental lab networks across Scandinavia. Amann Girrbach anchors its position through in-house production of optical measurement modules, controlling component quality from source to device. Zebris Medical competes on specialized infrared tracking systems for orthodontic applications, differentiating against broader-platform rivals.
A digital facebow is an electronic instrument that captures the spatial relationship between a patient's maxilla and cranial reference points using optical measurement or infrared sensors, transmitting data via Bluetooth or wireless communication to CAD/CAM systems for prosthetic fabrication. The device eliminates manual transfer errors inherent in mechanical facebows, enabling precise articulator mounting for crown, bridge, and implant restorations. Electronic facebow systems command premium positioning due to their integration with chairside milling units, while 3D facebow adoption accelerates among dental labs seeking batch-processing efficiency for complex aesthetic dentistry cases. Prosthodontics represents the most mature application segment, though orthodontic practices are expanding fastest as clear aligner therapy drives demand for accurate maxillary position recording.
FDA 510(k) pathways govern digital dental device clearance in the United States, requiring manufacturers to demonstrate substantial equivalence for optical measurement accuracy claims, while the EU MDR and CE marking framework mandate clinical performance documentation for wireless-enabled instruments sold in Europe. Japan's PMDA imposes additional electromagnetic compatibility standards on Bluetooth-equipped medical devices, creating regional compliance divergence that shapes product development roadmaps. Stakeholders must monitor evolving software-as-a-service regulations that could reclassify cloud-connected calibration tools as regulated medical device accessories.
Market Dynamics
Calibration and software update revenue streams are restructuring profit distribution across the digital facebow landscape, compelling manufacturers to prioritize recurring service architectures over one-time hardware sales.
Growth Catalysts
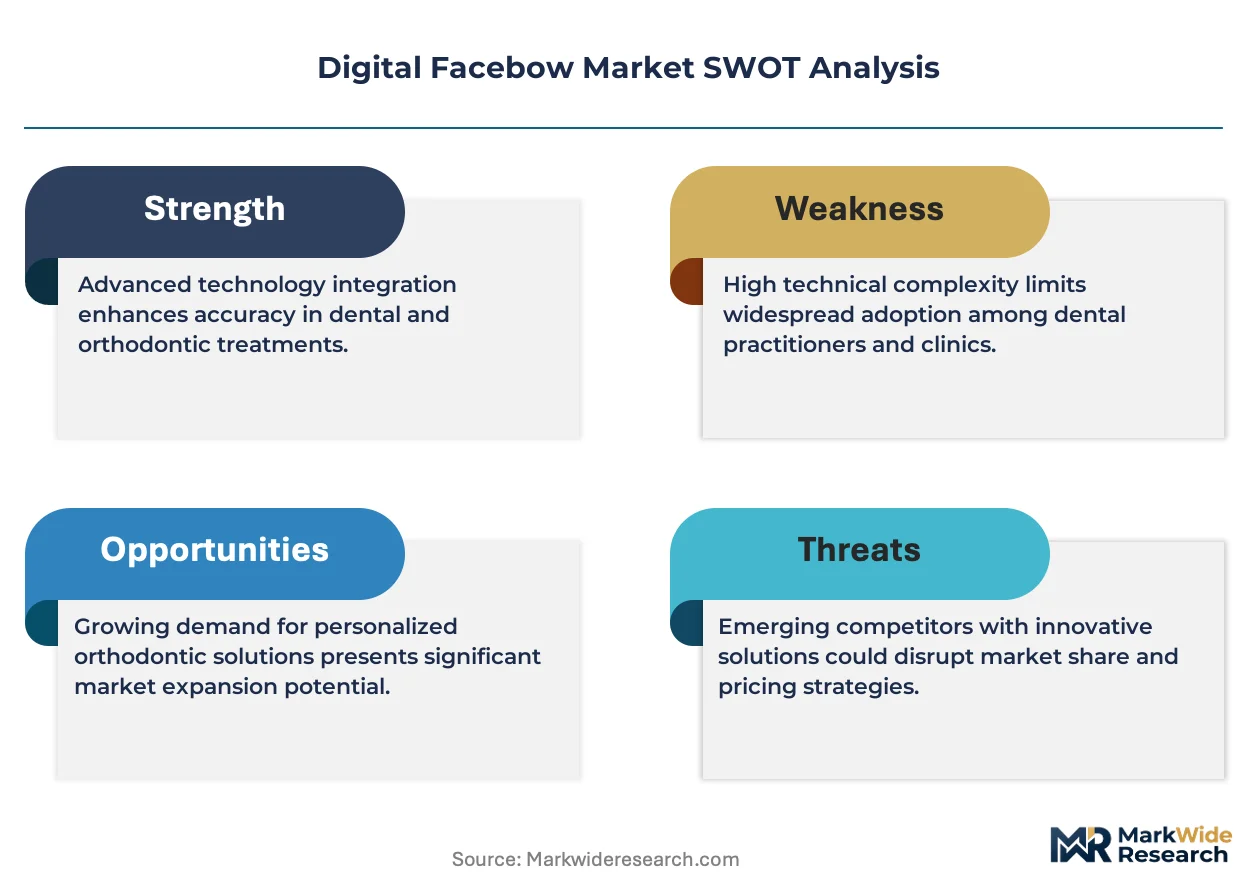
- EU MDR compliance mandates:Tightened documentation requirements for optical measurement accuracy under the Medical Device Regulation are forcing laboratories to upgrade from mechanical to validated electronic systems.
- Clear aligner therapy expansion:Orthodontic practices recording maxillary position for aligner fabrication are driving demand for infrared-enabled facebow systems with Bluetooth transmission capabilities.
- CAD/CAM integration imperatives:Dental laboratories in Germany and the United States are procuring 3D facebow platforms to eliminate manual transfer errors in crown and bridge workflows.
Market Restraints
- Optical module supply concentration:Infrared sensor production concentrates among specialized component suppliers, creating vulnerability for device manufacturers dependent on external sourcing.
- FDA 510(k) pathway duration:Substantial equivalence demonstrations for wireless-enabled instruments extend clearance timelines, delaying product commercialization in the United States.
- Mechanical facebow cost anchoring:Legacy analog systems retain price positioning below one-fifth of electronic alternatives, constraining upgrade conversion in cost-sensitive practices.
Strategic Opportunities
- Japan orthodontic penetration:PMDA electromagnetic compatibility standards have limited competitor entry, creating protected expansion terrain for compliant Bluetooth-equipped systems.
- Cloud-connected calibration services:Software-as-a-service regulations under development may reclassify remote calibration tools as regulated accessories, opening recurring revenue channels.
- Batch-processing dental laboratory consolidation:Multi-station 3D facebow installations enable centralized aesthetic dentistry production hubs serving regional clinic networks.
Industry Challenges
- Optical measurement technician scarcity:Prosthodontic practices lack personnel trained in spatial relationship capture protocols for electronic articulator mounting.
- Legacy articulator integration complexity:Existing mechanical articulator fleets in established laboratories resist seamless data transfer from digital facebow outputs.
- Cross-border calibration certification:Service technicians require jurisdiction-specific medical device servicing credentials, fragmenting aftermarket support networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Facebow Market |
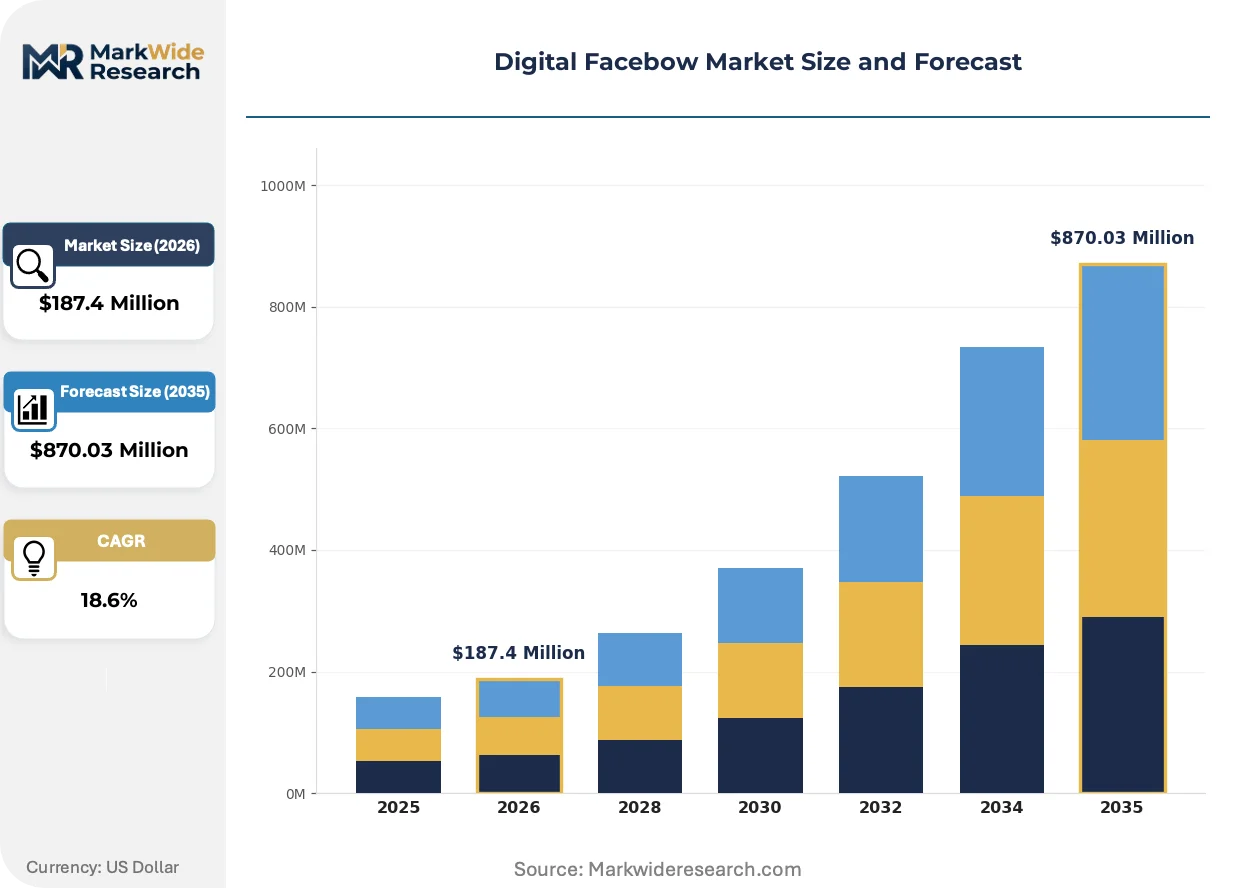
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Facebow, Electronic Facebow, Digital Denture, Imaging Facebow Application: Orthodontics, Prosthodontics, Oral Surgery, Aesthetic Dentistry End User: Dentists, Orthodontists, Dental Labs, Research Institutions Technology: Bluetooth, Infrared, Optical Measurement, Wireless Communication |
| Companies Covered | AxioPrisa, Amann Girrbach, zebris Medical, exocad, 3Shape, Zirkonzahn, Hangzhou DTC Medical Apparatus, Sicat, theratecc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Facebow Market Trends and Innovations
Wireless transmission protocols and optical sensor miniaturization are compressing device form factors while expanding compatibility with chairside milling ecosystems.
Infrared tracking arrays with sub-millimeter spatial resolution are digitizing maxillary position capture for orthodontic applications. Clear aligner therapy providers in Japan and Germany are adopting these systems at accelerating pace to replace plaster-based transfer methods. The technology is digitizing workflow standardization across previously fragmented laboratory networks.
Japan's PMDA electromagnetic compatibility standards for Bluetooth-equipped medical devices are creating regulatory divergence from FDA and EU MDR pathways. Manufacturers must maintain separate product variants or hardware configurations to satisfy distinct testing protocols. Orthodontic-focused device categories bear the heaviest compliance burden as transmission frequency specifications tighten.
Aftermarket service unbundling is separating hardware procurement from calibration and software update contracts. Dental laboratory networks in Scandinavia and the United States are negotiating standalone service agreements with multi-year terms. Germany exhibits the most advanced unbundling penetration, with laboratories treating calibration as a discrete budget line item distinct from capital equipment acquisition.
Digital Facebow Market Segmentation
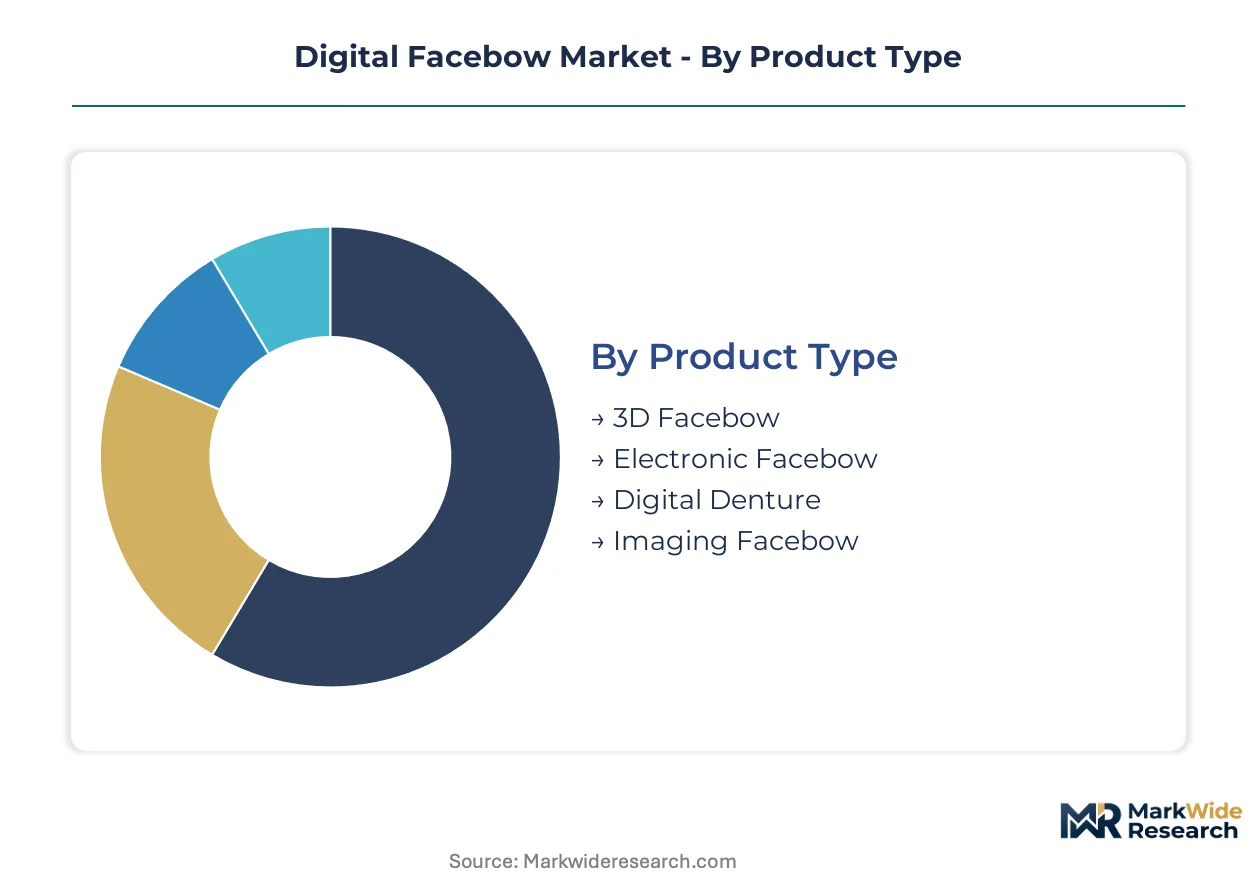
Segmentation in the digital facebow market exposes divergent replacement cycles across product tiers, with electronic systems commanding extended depreciation schedules against rapidly refreshed imaging platforms. Understanding these temporal patterns enables manufacturers to align service revenue models with hardware turnover rhythms.
Product Type:
Electronic facebow systems exhibit the longest replacement cycles at seven to ten years, while imaging facebow platforms turn over every three to four years as sensor resolution standards advance.
- Electronic Facebow:These instruments integrate optical measurement modules with chairside milling units through proprietary data protocols. Demand concentrates among German dental laboratories seeking validated articulator mounting for crown and bridge workflows under tightened EU MDR documentation requirements.
- 3D Facebow:Multi-station platforms enable batch processing of maxillary position data across centralized laboratory networks. Adoption accelerates in United States aesthetic dentistry hubs where laboratory consolidation drives procurement of high-throughput systems.
- Imaging Facebow:Compact sensor arrays prioritize portability for orthodontic practices with clear aligner therapy workflows.
- Digital Denture:Specialized variants optimize edentulous arch capture protocols for removable prosthodontics.
Electronic facebow dominates installed base. 3D facebow is where expansion concentrates.
Application:
Prosthodontics commands premium pricing tiers, while orthodontics generates volume through aligner therapy expansion.
- Prosthodontics:Mature application segment requiring precise maxillary-to-cranial reference capture for implant-supported restorations. United States practices drive replacement demand as legacy mechanical facebow fleets age beyond calibration viability.
- Orthodontics:Clear aligner therapy providers in Japan and Germany are displacing plaster-based transfer methods with infrared-enabled digital systems. PMDA electromagnetic compatibility standards limit competitor entry, protecting compliant Bluetooth-equipped device manufacturers.
- Aesthetic Dentistry:High-visibility cases demand sub-millimeter accuracy for anterior restoration matching.
- Oral Surgery:Specialized applications in orthognathic planning require integration with cone-beam computed tomography workflows.
Prosthodontics anchors revenue per unit. Orthodontics is climbing the fastest.
End User:
Dental laboratories amortize capital across high case volumes, while individual practitioners prioritize single-unit integration flexibility.
- Dental Labs:Multi-station installations in Germany and Scandinavia sustain aftermarket service contracts for calibration and software updates. Unbundled procurement treats calibration as discrete budget line items distinct from hardware acquisition.
- Orthodontists:Clear aligner therapy practices in Japan drive demand for portable infrared systems with Bluetooth transmission capabilities. PMDA testing protocols create protected terrain for compliant manufacturers.
- Dentists:Chairside integration requirements favor electronic facebow compatibility with existing milling ecosystems.
- Research Institutions:Academic prosthodontics programs validate optical measurement accuracy claims for regulatory submission packages.
Dental Labs dominate procurement volume. Orthodontists are gaining share fastest.
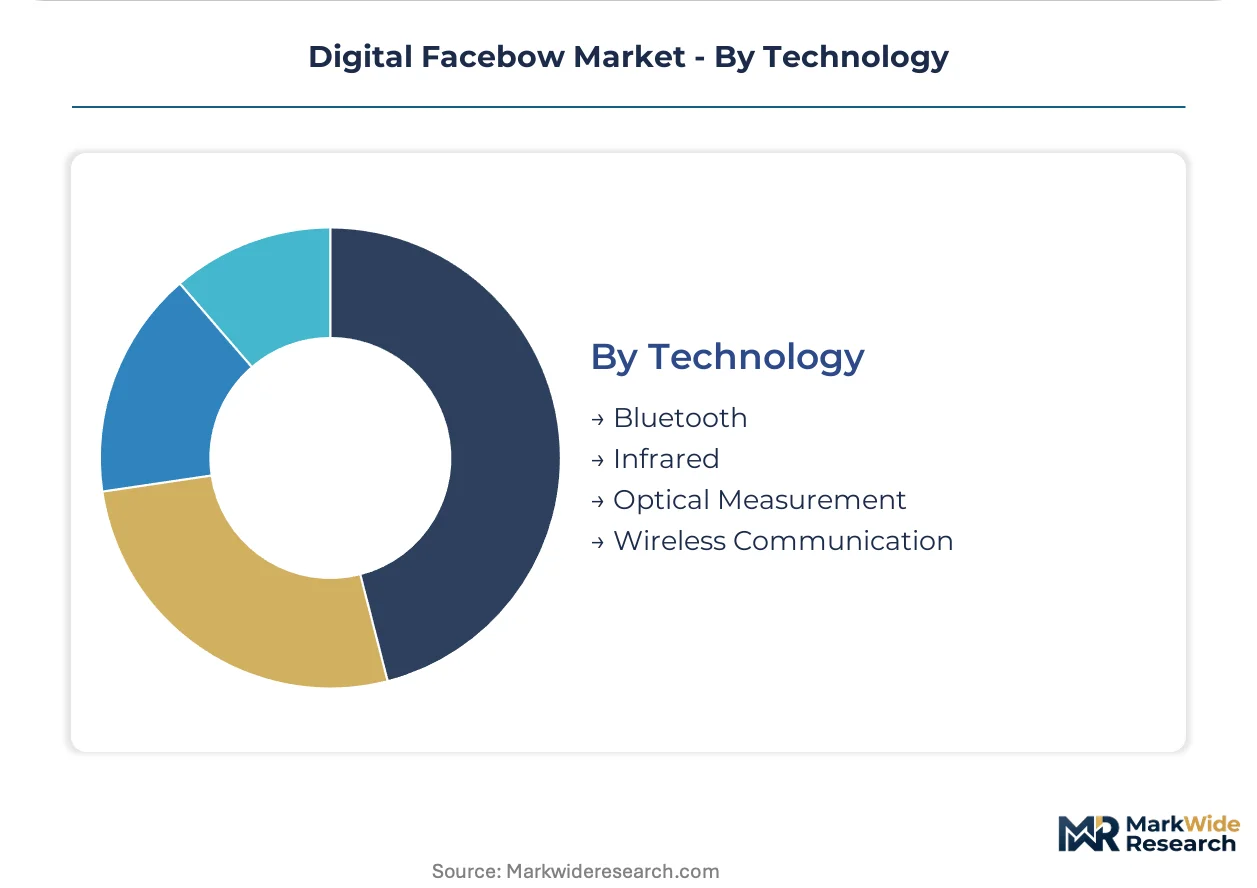
Technology:
Wireless communication protocols compress form factors, while optical measurement modules concentrate supply risk among specialized component vendors.
- Optical Measurement:Sub-millimeter spatial resolution arrays anchor accuracy claims for FDA 510(k) substantial equivalence demonstrations. Amann Girrbach controls component quality through in-house production of measurement modules.
- Bluetooth:Wireless transmission enables chairside data transfer to CAD/CAM systems. Japan's PMDA imposes electromagnetic compatibility standards that diverge from FDA and EU MDR pathways, forcing separate product variants.
- Infrared:Specialized tracking systems differentiate orthodontic-focused competitors against broader-platform rivals.
- Wireless Communication:Protocol standardization pressures proprietary data formats toward interoperability.
Optical Measurement dominates technical specifications. Bluetooth is where regulatory differentiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments across procurement tiers: dental laboratories absorb premium electronic systems as capital investments, while individual orthodontic practices in cost-sensitive markets delay upgrades from mechanical alternatives. Demand elasticity tightens where reimbursement rates constrain equipment budgets.
United States
FDA 510(k) clearance pathways for wireless-enabled dental devices extend commercialization timelines, compelling manufacturers to front-load substantial equivalence documentation. Prosthodontic practices in California and New York Metro drive replacement cycles as legacy mechanical facebow fleets age beyond calibration viability. Dental laboratory consolidation across the Midwest creates procurement scale for multi-station 3D installations.
Germany
EU MDR documentation requirements for optical measurement accuracy force laboratories to validate electronic systems over mechanical alternatives. Bavarian and North Rhine-Westphalia dental hubs anchor procurement volume for crown and bridge workflow integration. Aftermarket service unbundling treats calibration as discrete budget line items distinct from hardware acquisition.
Japan
PMDA electromagnetic compatibility standards for Bluetooth-equipped medical devices limit competitor entry, protecting compliant manufacturers in orthodontic segments. Clear aligner therapy expansion in Tokyo and Osaka drives infrared-enabled system adoption. Regional regulatory divergence forces separate product variants from FDA and EU MDR configurations.
China
Domestic equipment manufacturers in Zhejiang and Guangdong provinces compress pricing for entry-level electronic facebow systems. NMPA medical device registration pathways prioritize electromagnetic compatibility testing for wireless transmission modules. Dental laboratory networks in Shanghai and Beijing pilot batch-processing 3D platforms for aesthetic dentistry export production.
Scandinavia
Open-platform architecture preferences among Swedish and Danish dental lab networks sustain recurring software update revenue streams. National procurement frameworks emphasize interoperability standards over proprietary data protocols. Copenhagen and Stockholm clusters lead aftermarket service contract negotiation for multi-year calibration agreements.
Digital Facebow Market Competitive Landscape
Capability concentration sits with optical measurement specialists; scale advantage sits with platform-integrated multinationals. The vendor base stratifies across three tiers: in-house component producers controlling upstream quality, open-architecture software platforms capturing recurring service revenue, and orthodontic-focused infrared specialists differentiating on transmission precision. Dominant competitive moves include backward integration into sensor module production and geographic expansion through jurisdiction-specific regulatory compliance.
Among German-origin fabricators, Amann Girrbach occupies a position exemplifying captive supply chain control, while Zebris Medical represents specialized infrared tracking differentiation. 3Shape anchors the open-platform tier with recurring revenue architectures. Hangzhou DTC Medical Apparatus sits within the cost-optimized manufacturing segment serving price-sensitive procurement tiers.
| Leading Market Players |
|---|
| AxioPrisa |
| Amann Girrbach |
| zebris Medical |
| exocad |
| 3Shape |
| Zirkonzahn |
| Hangzhou DTC Medical Apparatus |
| Sicat |
| theratecc |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province's domestic manufacturing clusters compress entry-level electronic facebow pricing, forcing German and Japanese incumbents to defend premium tiers through after-sales bundling and calibration service contracts. This geographic cost asymmetry reshapes procurement patterns across dental laboratory networks seeking validated optical measurement systems.
Pricing Analysis
Aftermarket service revenue from calibration and software updates drives lifetime value capture, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA 510(k) certification tier and optical measurement module provenance. Cost compression in economy tiers intensifies because Zhejiang manufacturers bypass in-house sensor production. Dental laboratories exhibit lowest price sensitivity due to capital amortization across high case volumes, while individual orthodontic practices in cost-sensitive markets resist upgrades from mechanical alternatives.
Supply Chain Analysis
Export-control regimes limiting infrared sensor technology flows constrain supply diversification for specialized optical measurement arrays. Component manufacturing concentrates in Germany, Japan, and China. Production draws from gallium arsenide substrates, precision optical lenses, and Bluetooth transmission modules. Single-source vulnerability concentrates in infrared sensor fabrication. Distribution runs through dental equipment distributors with jurisdiction-specific regulatory certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against legacy mechanical facebow persistence, where cost anchoring below one-fifth of electronic alternatives threatens upgrade conversion economics.
For Market Incumbents: Entrench recurring revenue architectures by unbundling calibration contracts from hardware procurement, mirroring Scandinavian laboratory network models. Prioritize backward integration into optical measurement module production to control component quality and defend margin position against Zhejiang cost competitors. FDA 510(k) pathway expertise serves as the priority lever for United States market protection. For New Entrants and Emerging Players: Build out specialized infrared tracking capabilities for orthodontic applications in Japan, where PMDA electromagnetic compatibility standards limit incumbent entry. Target clear aligner therapy providers in Tokyo and Osaka seeking Bluetooth-enabled maxillary position capture. Pursue hospital system partnership go-to-market angles through academic prosthodontics programs validating optical measurement accuracy claims. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-integrated specialists with captive supply chain control over pure-platform software players. Long-term viability hinges on regulatory compliance diversification across FDA, EU MDR, and PMDA pathways. Acquisition target archetype: German-origin fabricators with in-house optical module production. Watch software-as-a-service reclassification signals as inflection indicators for recurring revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR documentation requirements force electronic system upgrades across German laboratory networks. |
| Backward Integration | In-house optical module production shields Amann Girrbach from infrared sensor supply concentration risks. |
| Hospital System Partnership | Academic prosthodontics programs validate accuracy claims for FDA 510(k) substantial equivalence submissions. |
| Software Companion Development | Cloud-connected calibration tools may trigger reclassification as regulated medical device accessories. |
| Reimbursement Strategy | Aftermarket service unbundling in Germany treats calibration as discrete budget line items. |
Research Methodology
The analysis maps electronic facebow, 3D facebow, imaging facebow, and digital denture sub-sectors, each validated through prosthodontic clinicians, dental laboratory procurement managers, biomedical engineers, and GPO contracts managers. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, PMDA electromagnetic compatibility test reports, and hospital procurement databases. Bottom-up installation base estimates triangulated against top-down market sizing.
Assumptions held fixed include regulatory pathway durations for wireless-enabled devices and optical measurement accuracy standards; variables tested include orthodontic practice adoption rates and dental laboratory consolidation velocity. Segmentation dimensions modeled encompass product type, application, end user, and technology protocol across the projection horizon. CAGRs derived from replacement cycle analysis and procurement scale elasticities, with inputs from clear aligner therapy expansion trajectories and CAD/CAM integration penetration.
Stress conditions across PMDA electromagnetic compatibility standard revisions, EU MDR enforcement intensity, and optical module supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory timeline stability and component cost trajectories. Material shifts in software-as-a-service reclassification or infrared sensor export controls would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental Implants Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Dental Radiometer Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Dental Fittings Market
Dental Devices
Dental Contouring Market