
 Dental Whitening Lamps Market | 2026-2036
Dental Whitening Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Whitening Lamps Market Outlook
LED diode arrays is decoupling lamp economics from legacy halogen thermal management costs. Royal Philips N.V. leverages its optoelectronics heritage to dominate high-intensity cold-light platforms. Beijing Nubway S&T Development anchors its position through cost-engineered units targeting emerging clinic networks. WHITE Smile GmbH differentiates via German-engineered precision optics for premium cosmetic dentistry.
Dental whitening lamps are chair-side irradiation devices that emit calibrated visible-spectrum energy, typically 450-490 nanometers at 600-2000 milliwatts, to catalyze hydrogen peroxide gel breakdown and accelerate enamel bleaching. LED product type leads installed base due to minimal heat generation and ten-thousand-hour operational lifespans, while halogen retains residual share in budget-sensitive replacement cycles. Cold light technology captures margin pools in professional settings where tissue safety commands priority, whereas ultraviolet configurations face structural decline from regulatory restrictions on ionizing exposure.
FDA 510(k) clearance requirements shape United States market access timelines for novel lamp designs, while EU MDR and CE marking enforce electromagnetic compatibility and biocompatibility standards across European distribution. Germany's KBA-equivalent medical device surveillance and South Korea's MFDS radiation safety protocols add compliance layers for multi-jurisdiction suppliers. Stakeholders must monitor divergence between FDA's device-centric framework and emerging EU AI Act implications for software-controlled irradiation dosing systems.
Market Dynamics
LED diode arrays is modularizing lamp architecture and severing the historical link between whitening performance and halogen thermal management infrastructure. This technological rupture is compressing supplier margins for legacy incumbents while opening entry paths for optoelectronics specialists.
Growth Catalysts
- EU MDR compliance deadlines:Dental clinics across Germany and France are accelerating replacement of uncertified halogen units ahead of enforcement windows, creating concentrated equipment refresh cycles.
- Cosmetic dentistry chains:Brazilian and Mexican clinic networks are standardizing chair-side whitening as a core revenue procedure, driving bulk procurement of cold-light platforms.
- 450-490 nanometer LED precision:Advances in blue-spectrum diode calibration are improving peroxide activation efficiency and shortening single-session treatment durations.
Market Restraints
- Halogen lamp residual stock:Budget-constrained clinics in secondary markets continue deploying thermal-based units, delaying full technology transition and fragmenting replacement demand.
- UV configuration obsolescence:Ionizing radiation restrictions under MFDS protocols in South Korea and emerging FDA guidance are structurally eliminating an entire product category.
- Optics supply concentration:Precision lens and reflector manufacturing clusters in southern Germany create geographic chokepoints for high-performance cold-light assemblies.
Strategic Opportunities
- Software-controlled dosing systems:Integration of irradiation timing algorithms is creating premium tiers where AI Act compliance becomes a competitive differentiator in EU markets.
- Mobile/portable lamp formats:Compact LED arrays are enabling non-clinical deployment models, with South Korean aesthetic chains piloting spa and retail channel expansion.
- Extended operational lifespans:Ten-thousand-hour diode durability is shifting revenue models from replacement cycles toward service contracts and gel consumable bundling.
Industry Challenges
- Biocompatibility certification timelines:FDA 510(k) clearance for novel lamp geometries averages fourteen to eighteen months, compressing product launch windows against faster-moving competitors.
- Legacy system integration:Chair-side software platforms in established United States dental networks require proprietary API compatibility, raising engineering overhead for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Whitening Lamps Market |
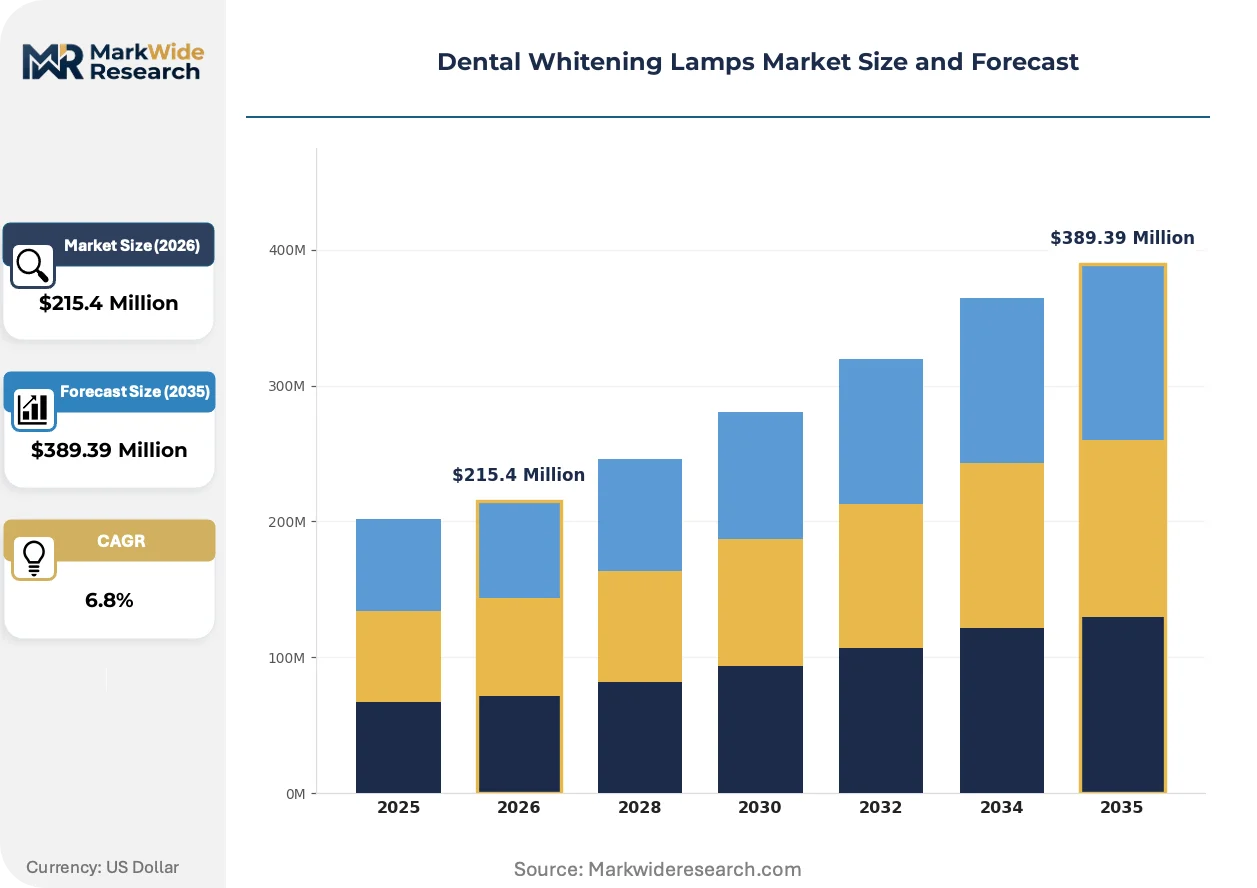
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Laser End User: Dental Clinics, Hospitals, Personal Use, Cosmetic Chains Technology: Cold Light, Ultraviolet, Light-Activated, Chemical Activation Application: Teeth Whitening, Stain Removal, Cosmetic Dentistry, Whitening Treatments |
| Companies Covered | BMS Dental, Royal Philips N.V., Beaming White LLC, DaVinci Teeth Whitening, WHITE Smile GmbH, Beijing Nubway S&T Development, Ajax Medical Group, APOZA Enterprise Co.Ltd., BG LIGHT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Whitening Lamps Market Strategic Shifts
Active recalibration of hardware-software boundaries is reshaping how whitening efficacy gets delivered, measured, and monetized. The convergence of solid-state lighting with embedded sensing is generating new performance verification protocols and procurement criteria.
Multi-diode LED engine architecture is modularizing the physical lamp unit into swappable irradiation modules. Premium cosmetic dentistry chains in South Korea are adopting this format to enable same-day wavelength reconfiguration for varying gel chemistries. The structural consequence is compressing capital expenditure recovery timelines while fragmenting supplier power across component rather than system vendors.
EU AI Act provisions for software-controlled medical devices are imposing algorithmic transparency requirements on automated irradiation dosing systems. Manufacturers must now document decision logic for intensity modulation and session termination protocols. German-engineered platforms with embedded compliance documentation are capturing preference share among risk-averse clinic procurement committees.
After-sales service unbundling is accelerating as clinic buyers separate hardware acquisition from maintenance and gel supply agreements. United States dental service organizations are negotiating direct relationships with peroxide manufacturers, bypassing traditional distributor markups on consumables. This pattern concentrates price pressure on lamp hardware margins while shifting profit pools toward recurring chemistry revenue.
Dental Whitening Lamps Market Segmentation
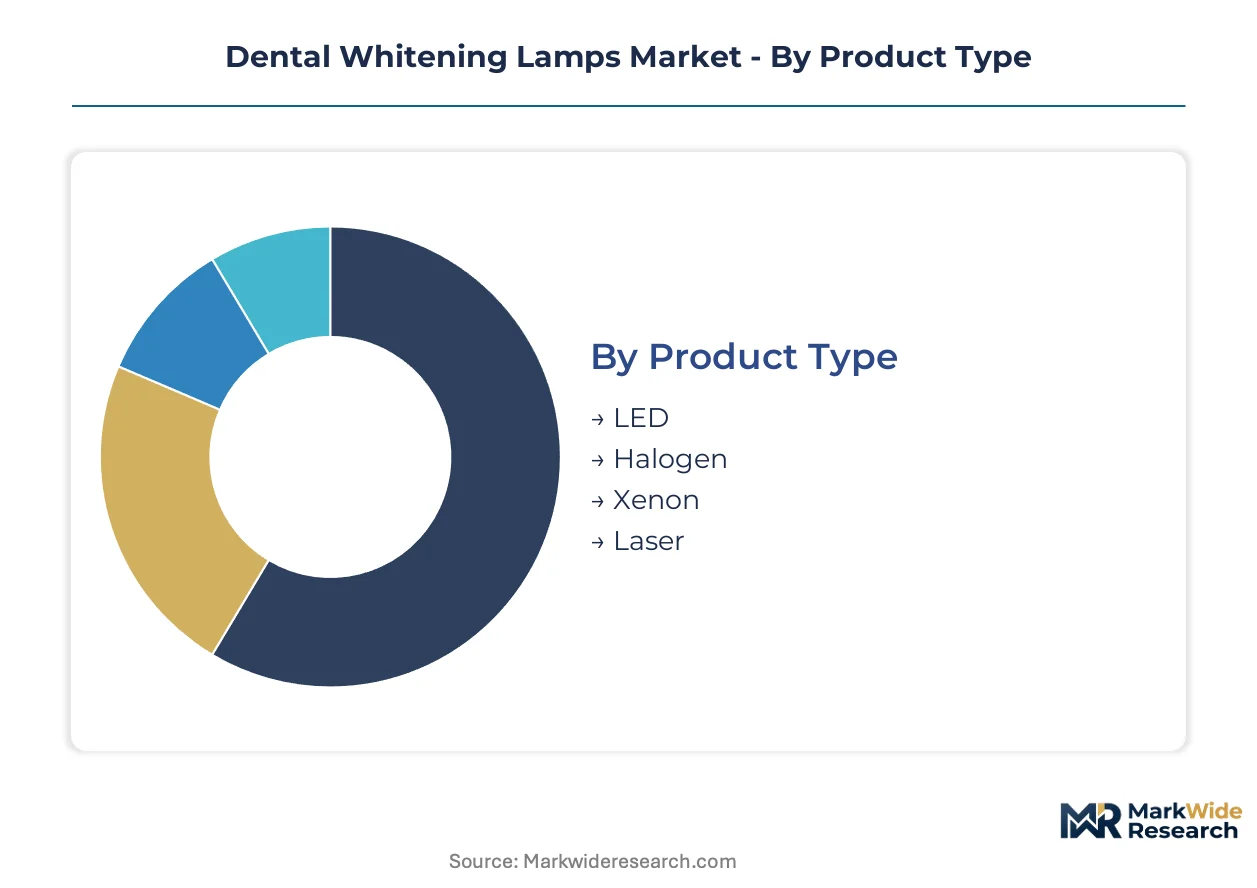
Segmentation in dental whitening lamps reveals how capital deployment, clinical workflow integration, and regulatory compliance reshape procurement decisions across professional and consumer channels. Equipment buyers prioritize thermal safety profiles and wavelength precision over raw irradiation power, fragmenting supplier strategies across technology tiers.
Product Type:
Capital intensity varies sharply across light-source technologies, with thermal management infrastructure driving the largest upfront differentials.
- LED:Solid-state diode arrays eliminate active cooling systems and halve electrical infrastructure requirements versus legacy platforms. Dental clinics in the United States and Germany concentrate procurement here, prioritizing ten-thousand-hour operational lifespans and minimal tissue heating during extended chair-side sessions.
- Halogen:Thermal-based tungsten-filament units demand dedicated ventilation ducts and higher-wattage electrical circuits, elevating total installation costs. Budget-constrained replacement cycles in secondary Brazilian and Mexican markets sustain residual demand despite accelerating LED displacement.
- Xenon:High-intensity discharge lamps occupy a narrowing niche in premium cosmetic dentistry suites requiring rapid multi-patient throughput.
- Laser:Coherent light sources command the steepest capital outlays due to precision optics and specialized operator certification requirements.
LED absorbs the bulk of installed capacity; laser is expanding most quickly in high-margin cosmetic chains.
End User:
Customer-type segmentation tracks diverging procurement authority structures, from centralized hospital purchasing to individual consumer decision-making.
- Dental Clinics:Independent and group practices dominate volume, with Brazilian and Mexican clinic networks standardizing chair-side whitening as core revenue procedures. Bulk procurement contracts favor cold-light platforms with modular diode architectures.
- Cosmetic Chains:South Korean aesthetic chains pilot spa and retail channel expansion using compact portable LED formats, bypassing traditional clinical infrastructure entirely.
- Hospitals:Academic medical centers integrate whitening lamps into broader dental surgery suites, prioritizing FDA 510(k) clearance documentation and electromagnetic compatibility certifications.
- Personal Use:Consumer-direct devices face structural limitations from peroxide concentration regulations and liability exposure, constraining addressable market development.
Dental clinics absorb the bulk of installed capacity; cosmetic chains are gaining share fastest through channel expansion.
Technology:
Technology segmentation isolates how irradiation mechanisms align with tissue safety protocols and gel chemistry requirements.
- Cold Light:LED-based visible-spectrum systems operating at 450-490 nanometers minimize thermal transfer to gingival tissue. Professional settings in Germany and South Korea command priority allocation where MFDS radiation safety protocols and EU MDR compliance enforce non-ionizing exposure standards.
- Light-Activated:Broader wavelength platforms accommodate varying hydrogen peroxide gel formulations, enabling same-day reconfiguration for multi-chemistry workflows.
- Ultraviolet:Ionizing radiation configurations face structural decline from South Korean MFDS restrictions and emerging FDA guidance, eliminating entire product lines from compliant procurement.
- Chemical Activation:Self-activating gel systems reduce hardware dependency but limit treatment acceleration versus photo-catalyzed alternatives.
Cold light absorbs the bulk of installed capacity; light-activated configurations are climbing the fastest through chemistry flexibility.
Application:
Application segmentation maps how clinical outcomes and reimbursement structures shape equipment specification requirements.
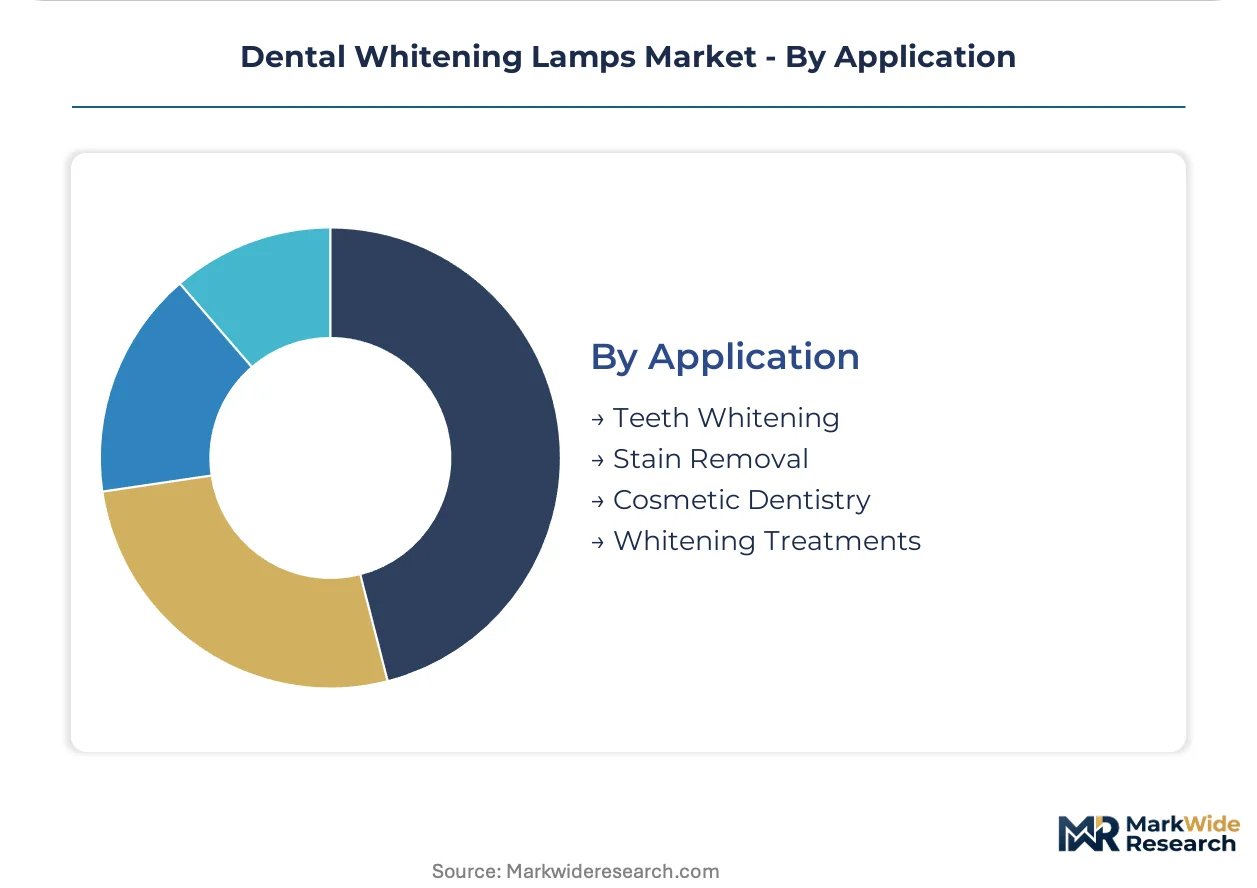
- Teeth Whitening:Core enamel bleaching procedures drive baseline demand, with 450-490 nanometer LED precision shortening single-session treatment durations in high-volume United States practices.
- Cosmetic Dentistry:Premium aesthetic outcomes command highest equipment specifications, with German-engineered precision optics capturing preference among risk-averse procurement committees.
- Stain Removal:Targeted extrinsic discoloration treatments require lower irradiation intensity, enabling cost-engineered unit deployment.
- Whitening Treatments:Generalized procedure categories encompass maintenance protocols and combination therapies with less stringent hardware requirements.
Teeth whitening absorbs the bulk of installed capacity; cosmetic dentistry is gaining share fastest through premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and bonded warehouse districts near Frankfurt Airport concentrate component sourcing for LED whitening lamp assembly. These logistics hubs enable rapid customs clearance for precision optics and diode arrays destined for dental equipment manufacturers.
United States
Cosmetic dentistry chains in Florida and Texas drive equipment refresh cycles ahead of FDA 510(k) enforcement windows. The FDA's device-centric clearance framework mandates electromagnetic compatibility documentation for software-controlled irradiation systems. Dallas-Fort Worth hosts distribution centers serving independent dental practices across the Southwest with modular cold-light platforms.
Germany
Academic medical centers in Munich and Heidelberg prioritize EU MDR-compliant cold-light systems for hospital-integrated dental surgery suites. Germany's KBA-equivalent medical device surveillance enforces biocompatibility standards that exceed baseline CE marking requirements. Precision optics manufacturing clusters in southern Baden-Württemberg supply high-performance reflector assemblies to premium lamp assemblers.
South Korea
Aesthetic chains in Seoul and Busan pilot spa-channel deployment of compact portable LED formats outside traditional clinical settings. MFDS radiation safety protocols structurally prohibit ultraviolet configurations, accelerating cold-light platform standardization. The Daejeon-Sejong corridor hosts testing laboratories certifying diode array output stability for export markets.
Brazil
Clinic networks in São Paulo and Rio de Janeiro standardize chair-side whitening as core revenue procedures, driving bulk procurement of cost-engineered units. ANVISA medical device registration timelines shape import planning for Asian-manufactured equipment. Campinas anchors assembly operations for regional distribution across Mercosur markets.
Mexico
Border-state dental tourism corridors in Baja California and Nuevo León demand rapid-treatment platforms for same-day cosmetic procedures. COFEPRIS regulatory alignment with FDA standards streamlines cross-border equipment certification for US-manufactured systems. Monterrey hosts warehousing facilities serving expanding clinic networks throughout northern Mexico.
Dental Whitening Lamps Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with optoelectronics heritage determining positioning in premium cold-light tiers versus cost-engineered volume plays. The supplier base organizes around three strategic archetypes: diversified health technology conglomerates leveraging lighting divisions, precision optics specialists anchored in German engineering clusters, and emerging-market fabricators optimizing for emerging clinic procurement budgets. Competitive maneuvering concentrates on M&A activity targeting diode calibration capabilities and strategic partnerships with peroxide gel manufacturers for consumable bundling arrangements.
Among European-headquartered specialists, WHITE Smile GmbH exemplifies the precision-engineering archetype through its German GmbH structure and optics-focused market positioning. Royal Philips N.V. represents the diversified health technology model, leveraging its Netherlands-based corporate heritage and established medical device distribution infrastructure. Beijing Nubway S&T Development occupies the cost-optimization tier, with its Beijing-based Co., Ltd. structure signaling emerging-market manufacturing scale. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| BMS Dental |
| Royal Philips N.V. |
| Beaming White LLC |
| DaVinci Teeth Whitening |
| WHITE Smile GmbH |
| Beijing Nubway S&T Development |
| Ajax Medical Group |
| APOZA Enterprise Co.Ltd. |
| BG LIGHT |
| Others |
Value Chain & Pricing Dynamics
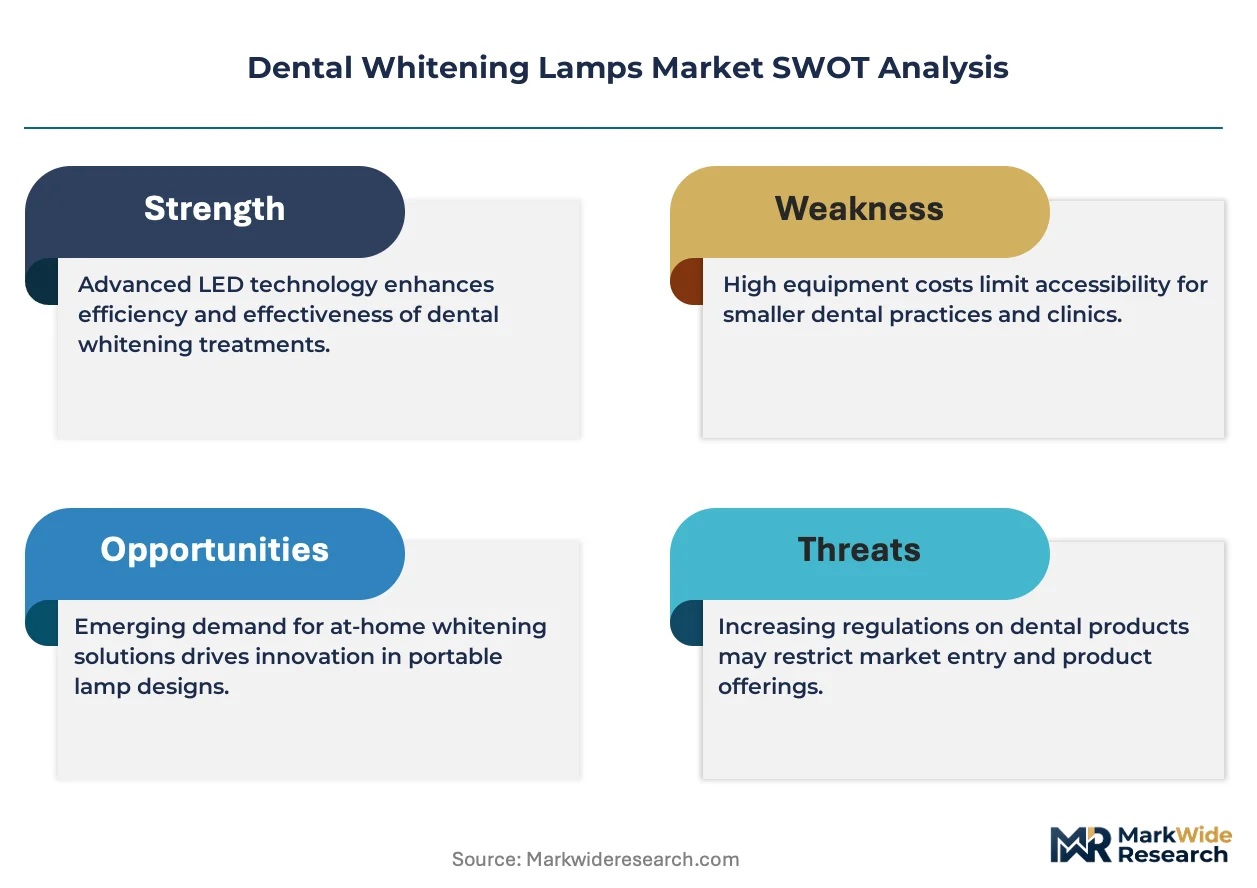
LED-halogen performance divergence splits procurement budgets between premium cold-light platforms and thermal-based legacy units, with FDA 510(k) certification tiers amplifying price spreads and concentrating component sourcing in optoelectronics clusters across South Korea and southern Germany.
Pricing Analysis
Volume capture concentrates in cost-engineered LED units while margin pools accrue to precision-calibrated cold-light systems with embedded EU AI Act documentation. Price differentiation hinges on FDA clearance tier and after-sales service bundling. Cost compression in halogen replacement segments intensifies as Brazilian clinic networks negotiate bulk procurement. Dental service organizations in the United States exhibit highest price sensitivity; German academic medical centers prioritize certification grade over unit economics.
Supply Chain Analysis
Freight costs for precision optics from Baden-Württemberg and diode arrays from Seoul elevate landed costs for North American assemblers. Manufacturing concentrates in China, South Korea, and Germany. Component sourcing draws from gallium nitride substrates, polymer lens housings, and thermal management alloys. Single-source vulnerability runs through southern German reflector clusters. Distribution runs through dental equipment distributors and direct-to-clinic service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance deadlines erect a cost-of-compliance barrier that favors incumbents with established CE marking infrastructure and documented biocompatibility testing, structurally disadvantaging rapid entrants lacking regulatory affairs depth.
For Market Incumbents: Cement position by acquiring diode calibration specialists in the Daejeon-Sejong corridor to secure wavelength precision capabilities. Deepen backward integration into gallium nitride substrate sourcing to defend margins against raw material volatility. Prioritize EU AI Act algorithmic transparency documentation as emerging entrant protection.
For New Entrants and Emerging Players: Peroxide gel manufacturers present the most accessible partnership pathway for hardware co-development and consumable bundling. Target Mexican border-state dental tourism corridors where COFEPRIS-FDA alignment streamlines cross-border certification. Deploy compact portable LED formats through South Korean aesthetic spa channels as beachhead positioning.
For Investors and Strategic Acquirers: Re-rating potential sits with optoelectronics specialists possessing FDA 510(k) clearance track records given accelerating halogen replacement cycles. Long-term viability centers on service-contract revenue models displacing hardware replacement cycles. Monitor MFDS radiation safety protocol expansion as inflection signal for ultraviolet configuration obsolescence acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | CE marking with biocompatibility documentation unlocks German hospital procurement committees. |
| Diode Calibration Specialist Acquisition | Wavelength precision capabilities differentiate premium cold-light platforms in South Korean cosmetic chains. |
| Peroxide Gel Manufacturer Partnership | Consumable bundling shifts revenue models from hardware cycles toward recurring chemistry streams. |
| Portable LED Format Development | Spa-channel deployment in Seoul and Busan bypasses traditional clinical infrastructure requirements. |
| Algorithmic Transparency Documentation | EU AI Act compliance becomes competitive moat for software-controlled dosing systems in risk-averse markets. |
Study Parameters
Multi-period observation of FDA 510(k) clearance timelines, EU MDR enforcement windows, and clinic procurement patterns anchored the trend analysis, supplemented by interviews with dental equipment distributors, biomedical engineers at academic medical centers, GPO contracts managers, and cosmetic chain procurement leads. Secondary validation drew from FDA device databases, EUDAMED registration records, ANVISA import filings, and customs trade data. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-weighting across light-source technology, end-user channel, and geographic regulatory cluster shaped the analytical framework across the projection horizon. CAGRs derived from installed base evolution, replacement cycle compression, and penetration rate trajectories in emerging clinic networks. Industry-specific inputs included peroxide gel chemistry adoption curves and MFDS radiation safety protocol expansion scenarios.
Caveats apply where FDA guidance divergence on software-controlled dosing, EU AI Act enforcement intensity, or Brazilian ANVISA registration delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Dental Scalers Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
China Dental Devices Market
Dental Devices
Dental Articulators Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
India Dental Devices Market
Dental Devices
Dental Needle Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Europe Dental Implants Market
Dental Devices
North America Dental Implants and Prosthetics Market