
 Global Digital Dentistry Market | 2026-2036
Global Digital Dentistry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Dentistry Market Foresight
Direct-to-laboratory digital workflows are reshaping how restorative and orthodontic products reach end users. Dentsply Sirona leverages its integrated scanner-milling ecosystem to control hardware-software compatibility across chairside and lab environments. Align Technology anchors clear aligner production through proprietary intraoral scanning networks that lock in recurring consumable revenue. 3Shape A/S specializes in open-architecture CAD software that competes against closed systems by enabling multi-vendor hardware interoperability.
Digital dentistry encompasses the digitization of dental diagnosis, treatment planning, and fabrication through optical imaging, computer-aided design, and additive or subtractive manufacturing, typically achieving micron-level accuracy for crown, bridge, and aligner production. Intraoral scanners lead product type revenue due to their position as the entry point for digital workflow adoption in private clinics and dental laboratories. Artificial Intelligence within the technology dimension is gaining fastest as FDA-cleared algorithms for radiographic caries detection and orthodontic outcome simulation expand reimbursable use cases.
The FDA's 510(k) premarket notification framework governs device safety and efficacy for intraoral scanners and cone beam CT systems in the United States, while the EU Medical Device Regulation (MDR) and CE marking requirements enforce clinical evidence standards for digital radiography equipment across European member states. Japan's PMDA applies Japan Industrial Standards for optical imaging devices, creating a separate conformity assessment path that shapes product localization strategies for Asian market entry. Stakeholders must monitor how divergent software-as-a-medical-device classifications across the FDA, EMA, and PMDA affect AI-enabled diagnostic modules that span multiple regulatory jurisdictions.
Market Dynamics
Chairside CAD/CAM adoption is compressing turnaround times for same-day restorations, forcing dental laboratories to reposition toward complex prosthetics and orthodontic appliances that resist point-of-care fabrication.
Growth Catalysts
- FDA 510(k) Pathway:The streamlined premarket notification framework accelerates clearance timelines for intraoral scanners and AI-assisted diagnostic modules, reducing regulatory friction for US market entry.
- Optical Scanning Networks:Proprietary intraoral scanning ecosystems lock dental clinics into recurring consumable revenue streams through cloud-connected treatment planning platforms.
- German Manufacturing Clusters:Concentrated precision engineering capabilities around Straumann Group and Dentsply Sirona facilities create supplier density that reduces component lead times for European distribution.
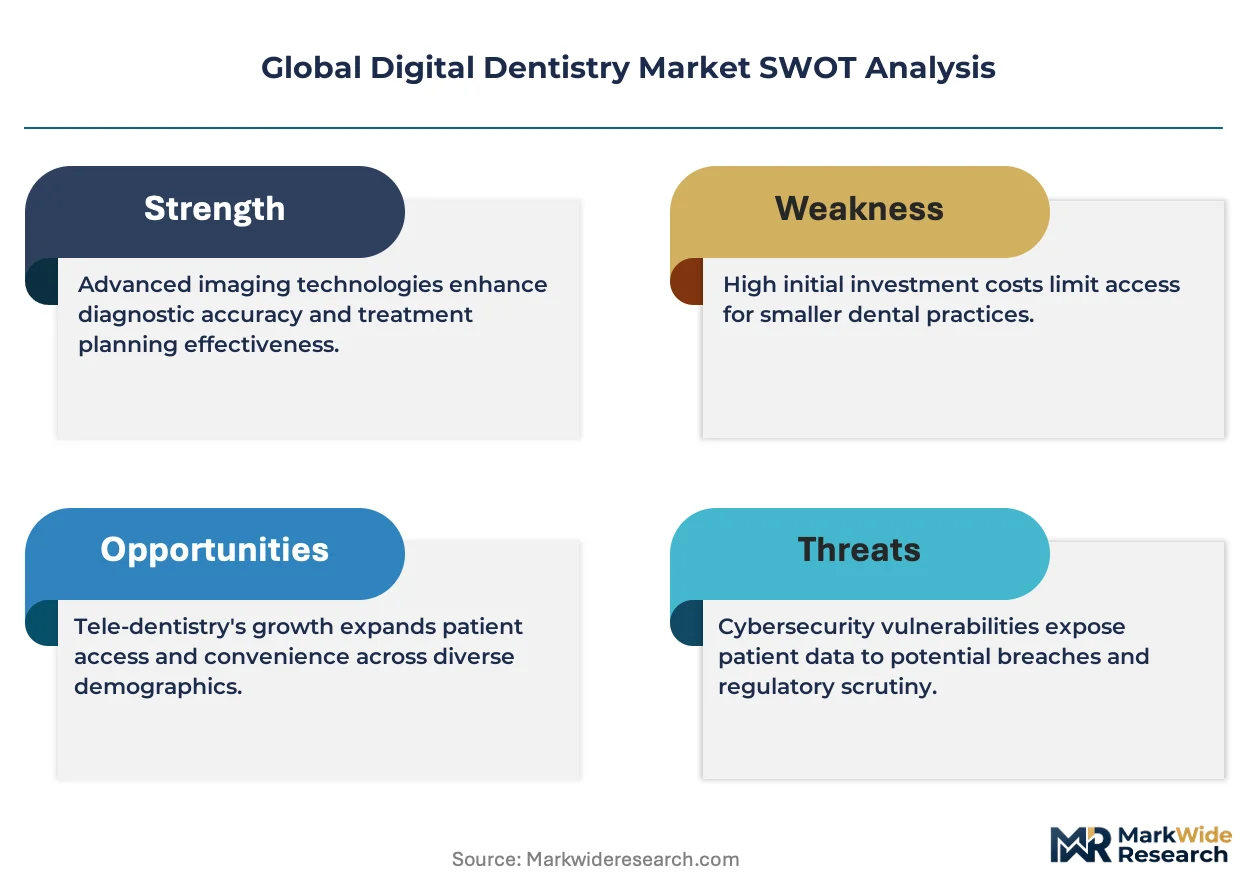
Market Restraints
- Capital Intensity:Chairside milling units and cone beam CT systems require six-figure equipment investments that strain independent dental practice balance sheets.
- Raw Material Concentration:Zirconia blank supply chains concentrate in East Asian ceramic foundries, exposing European and North American labs to freight cost volatility and customs processing delays.
- Software Interoperability Gaps:Closed-architecture CAD/CAM ecosystems from dominant hardware vendors fragment digital workflows and lock laboratories into single-source consumable contracts.
Strategic Opportunities
- AI-Enabled Diagnostics:FDA-cleared algorithms for radiographic caries detection and orthodontic outcome simulation expand reimbursable use cases beyond traditional mechanical restoration.
- India's Dental Infrastructure:Underpenetrated private clinic networks and government health digitization initiatives create whitespace for affordable intraoral scanner deployment.
- Subscription-Based Software:Cloud-native CAD platforms displace perpetual-license models, enabling recurring revenue capture from mid-sized laboratories previously priced out of enterprise-tier tools.
Industry Challenges
- Digital Workflow Training:Laboratory technicians require cross-functional competency in optical imaging, CAD design, and additive manufacturing—skill sets that outpace vocational curriculum refresh cycles.
- Legacy Equipment Integration:Analog impression workflows persist in institutional dental settings, forcing hybrid infrastructure investments that complicate inventory and quality management.
- CE Marking Under MDR:The EU Medical Device Regulation's enhanced clinical evidence requirements extend certification timelines for digital radiography equipment, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Dentistry Market |
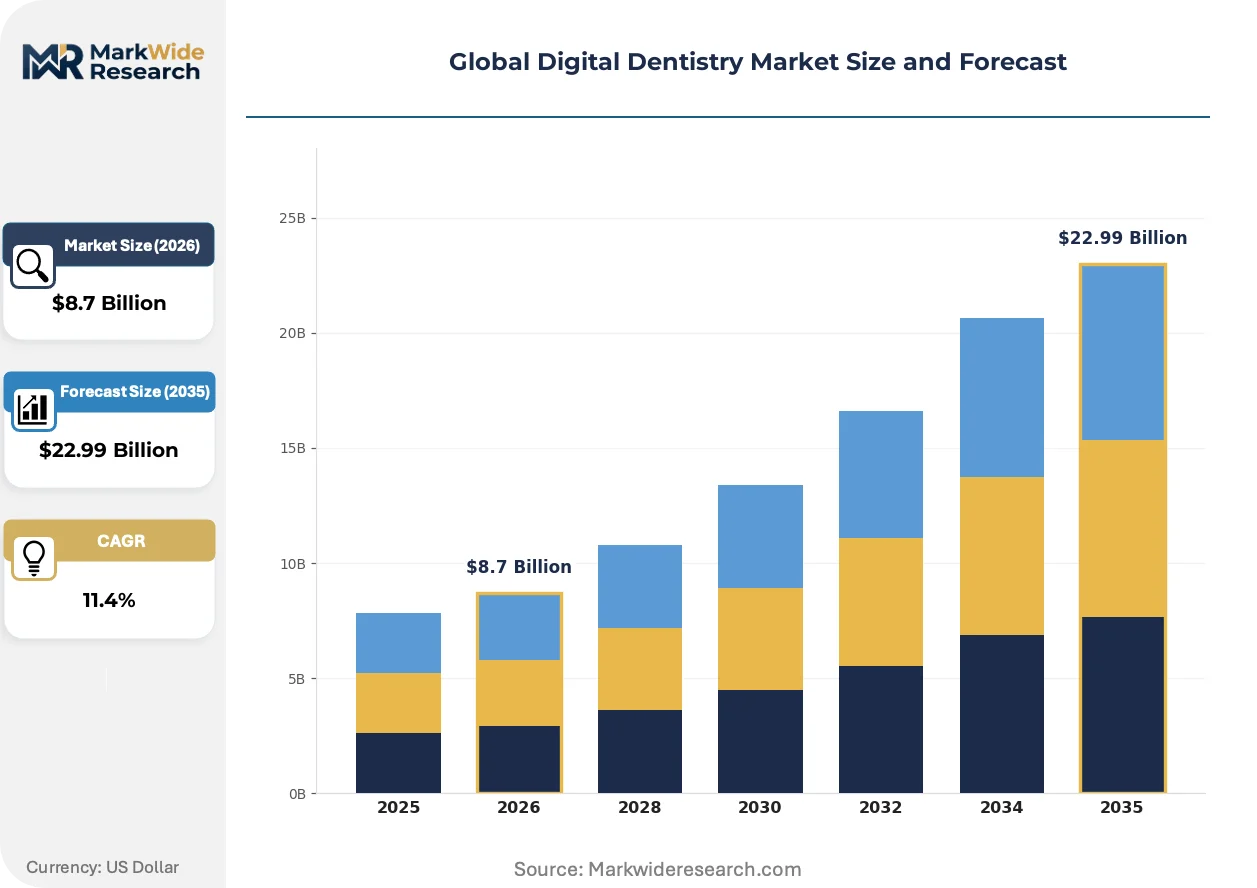
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Scanners, Dental CAD Software, Milling Machines, 3D Printers, Cone Beam CT, Digital X-Ray Systems Technology: Optical Imaging, Computer-Aided Design, Computer-Aided Manufacturing, 3D Printing, Digital Radiography, Artificial Intelligence Application: Restorative Procedures, Orthodontics, Implantology, Prosthodontics, Periodontal Treatments, Cosmetic Dentistry End User: Dental Laboratories, Specialized Clinics, Academic Institutes, Dental Research Centers, Private Clinics, Public Health Facilities |
| Companies Covered | Dentsply Sirona, Align Technology, 3Shape A/S, Straumann Group, Planmeca Oy, Ivoclar Vivadent, Envista Holdings Corporation, Carestream Dental, 3D Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Dentistry Market Shifts & Advancements
Photorealistic intraoral scanning is collapsing the distinction between diagnostic imaging and treatment simulation, enabling chairside patient communication tools that accelerate case acceptance rates.
Intraoral scanners equipped with real-time AI feedback are collapsing traditional impression-taking workflows by flagging scan quality deficits during image capture rather than post-processing. Private clinics in Germany and the United States deploy these systems to eliminate retake appointments and same-day remakes. The compression of chair time per restoration unit is forcing laboratories to compete on speed-to-delivery rather than unit economics alone.
The EU Medical Device Regulation's software-as-a-medical-device classification is collapsing the historical separation between hardware clearance and algorithmic diagnostic tools. Manufacturers must now submit clinical evidence packages for AI-enabled radiographic analysis modules that previously operated under general wellness exemptions. European dental imaging vendors are responding by consolidating regulatory affairs functions and pre-submission engagement with notified bodies.
Patient-facing treatment visualization tools are collapsing the traditional dentist-as-intermediary model for orthodontic and cosmetic procedure selection. Direct-to-consumer scanning networks in urban Japan and South Korea enable preliminary treatment simulations before clinical consultation, shifting diagnostic burden onto laboratory-based remote review services. This channel bypass is most visible in clear aligner workflows where proprietary scanning apps feed directly into centralized manufacturing queues.
Global Digital Dentistry Market Segmentation
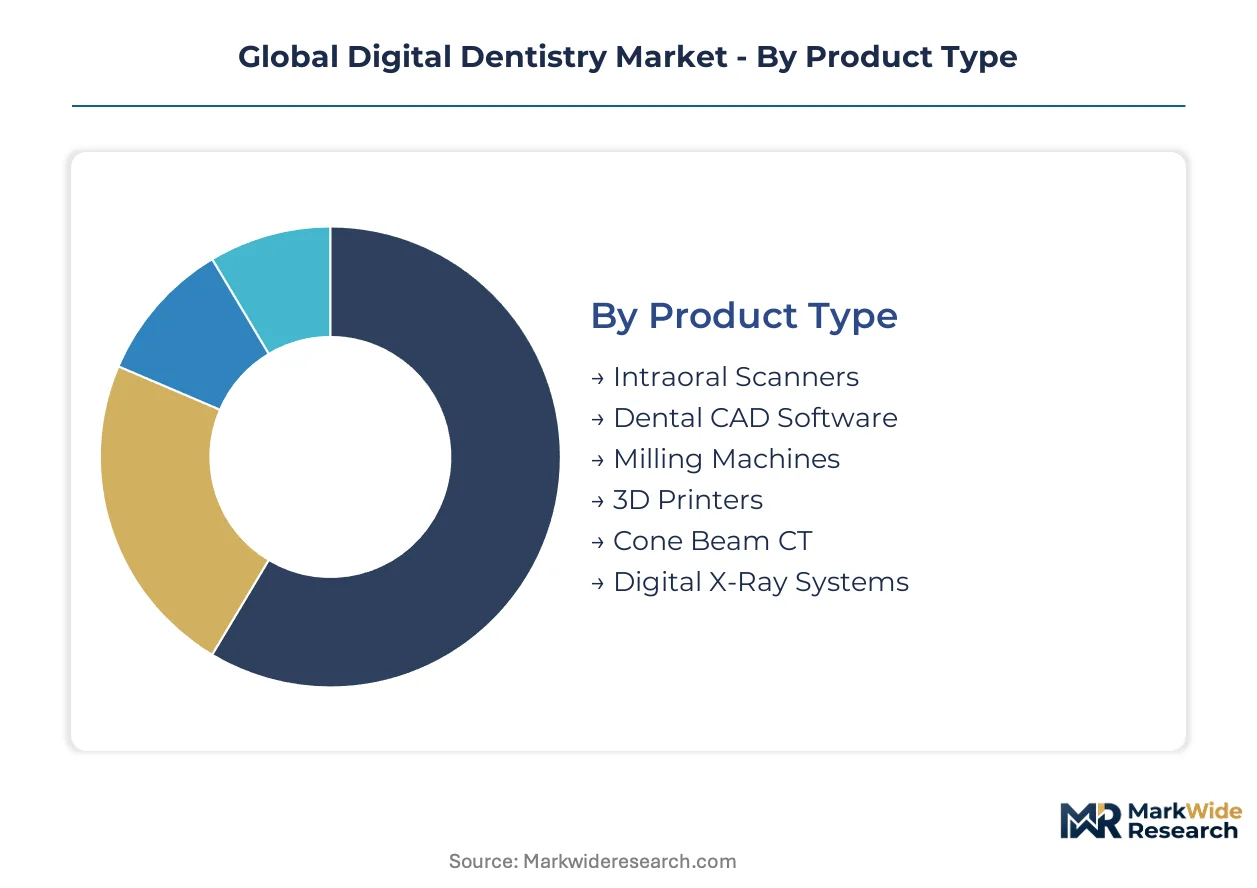
Digital dentistry workflows cascade through distinct hardware, software, and service layers that determine capital allocation priorities for clinics and laboratories. Segmentation reveals where procurement budgets concentrate and which technology transitions face the steepest adoption curves.
Product Type:
The use-case spectrum spans point-of-care capture devices through centralized production equipment, with each tier demanding different technical specifications and integration depth.
- Intraoral Scanners:Handheld optical devices capture sub-10-micron accuracy surface data for crown, bridge, and aligner fabrication. Private clinics in Germany and the United States deploy these systems to eliminate alginate impressions and accelerate case acceptance through chairside visualization.
- Dental CAD Software:Design platforms translate scan data into machine-ready fabrication files, with open-architecture systems competing against closed ecosystems by enabling multi-vendor hardware interoperability. Laboratories in Switzerland and Japan prioritize subscription-based cloud deployments to reduce upfront licensing costs.
- Milling Machines:Subtractive systems machine zirconia, lithium disilicate, and PMMA blanks into final restorations.
- 3D Printers:Additive systems fabricate surgical guides, temporary crowns, and orthodontic models from photopolymer resins.
- Cone Beam CT:Volumetric imaging systems provide sub-millimeter bone structure data for implant planning.
- Digital X-Ray Systems:Intraoral and panoramic sensors replace analog film with immediate image acquisition.
The dominant share belongs to Intraoral Scanners, while Artificial Intelligence modules are closing the gap fastest through expanding reimbursable diagnostic applications.
Technology:
Cost tier differentiation separates capital-intensive hardware installations from software-enabled service layers that scale with patient volume.
- Optical Imaging:Structured light and confocal microscopy systems generate surface topography data without ionizing radiation. German and Japanese manufacturers dominate component supply for high-speed scanning heads.
- Computer-Aided Design:Parametric modeling tools automate restoration geometry based on biogeneric tooth libraries. Laboratories in the United States and Switzerland drive demand for AI-assisted design suggestions that reduce technician labor per unit.
- Computer-Aided Manufacturing:Automated milling and grinding workflows execute CAD files with minimal human intervention.
- 3D Printing:Vat photopolymerization and material jetting processes build objects layer-by-layer from liquid resins.
- Digital Radiography:Solid-state sensors and phosphor plate systems capture diagnostic images with reduced radiation exposure.
- Artificial Intelligence:Machine learning algorithms analyze radiographic and optical data for caries detection, treatment outcome prediction, and quality control.
Optical Imaging commands the largest installed base, though Artificial Intelligence is expanding most quickly as FDA-cleared algorithms enter reimbursable workflows.
Application:
Volume concentration tracks procedure reimbursement rates and patient out-of-pocket willingness across elective and therapeutic categories.
- Restorative Procedures:Crown, bridge, and inlay fabrication represents the foundational digital workflow entry point. Private clinics in Germany and the United States deploy chairside systems for same-day delivery of single-unit restorations.
- Orthodontics:Clear aligner therapy depends on precise archform capture and staging algorithms for tooth movement. Align Technology's proprietary scanning networks lock clinics into recurring consumable revenue through centralized manufacturing queues.
- Implantology:Surgical guide fabrication and prosthetic-driven planning require integration of optical and radiographic datasets.
- Prosthodontics:Complex multi-unit restorations and removable appliances demand laboratory-grade precision.
- Periodontal Treatments:Soft tissue assessment and regenerative procedure planning utilize optical scanning for baseline documentation.
- Cosmetic Dentistry:Veneer design and smile simulation leverage real-time visualization for patient communication.
Restorative Procedures maintain the deepest penetration, while Orthodontics is gaining share fastest through direct-to-consumer scanning networks in Japan and South Korea.
End User:
Customer type determines procurement authority, with independent laboratories and consolidated clinic chains following diverging equipment acquisition strategies.
- Dental Laboratories:Centralized production facilities process digital impressions from multiple referring clinics, requiring multi-format import compatibility and high-throughput manufacturing capacity. German laboratories anchor European demand for open-architecture CAD platforms.
- Private Clinics:Independent practices balance chairside capability against laboratory outsourcing economics. Clinics in the United States prioritize FDA-cleared AI diagnostic modules to differentiate service offerings and justify fee premiums.
- Specialized Clinics:Orthodontic and implant-focused practices concentrate advanced imaging and manufacturing equipment.
- Academic Institutes:Training programs require vendor-agnostic platforms to expose students to multiple technology ecosystems.
- Dental Research Centers:Validation studies and clinical trials drive demand for metrology-grade measurement systems.
- Public Health Facilities:Government-funded clinics face capital constraints that favor refurbished equipment and extended depreciation schedules.
Dental Laboratories capture the highest equipment spend per site, while Private Clinics are deploying fastest as intraoral scanner prices compress into five-figure ranges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dental laboratories command premium pricing for precision-manufactured prosthetics, while Indian clinics absorb cost-sensitive scanner deployments at entry-tier price points. This asymmetry shapes diverging equipment specifications and service models across developed and emerging markets.
United States
Private dental clinics drive scanner procurement through FDA 510(k) cleared chairside systems that enable same-day restoration delivery. The FDA's streamlined premarket notification framework accelerates clearance timelines for AI-assisted diagnostic modules. Greater Boston and the Pacific Northwest host concentrated digital dentistry research clusters where academic medical centers validate optical imaging protocols.
Germany
Dental laboratories in Bavaria and Baden-Württemberg anchor European demand for open-architecture CAD platforms that enable multi-vendor hardware interoperability. The EU Medical Device Regulation enforces enhanced clinical evidence standards for digital radiography equipment, extending certification timelines. Stuttgart's precision engineering corridor supplies high-speed scanning head components to intraoral scanner manufacturers.
Japan
Direct-to-consumer orthodontic scanning networks in Tokyo and Osaka bypass traditional dentist intermediaries for preliminary treatment simulations. Japan's PMDA applies Japan Industrial Standards for optical imaging devices, creating a separate conformity assessment path. The Kansai region's dental technology institutes train technicians in hybrid analog-digital workflows that persist in institutional settings.
China
Domestic scanner manufacturers compete on cost efficiency for mid-tier clinic procurement in Shanghai and Guangzhou. The National Medical Products Administration governs device safety classifications for cone beam CT and intraoral imaging systems. The Yangtze River Delta concentrates ceramic foundry capacity for zirconia blank production that supplies global milling machine feedstock.
India
Government health digitization initiatives and underpenetrated private clinic networks create whitespace for affordable intraoral scanner deployment in Maharashtra and Karnataka. The Central Drugs Standard Control Organization regulates import and manufacturing standards for dental imaging equipment. Mumbai's dental laboratory clusters adopt subscription-based cloud CAD platforms to reduce upfront licensing barriers.
Global Digital Dentistry Market Competitive Landscape
Integrated hardware-software ecosystems and specialized component suppliers split the market into distinct competitive spheres. The vendor base concentrates around precision imaging equipment, with tiered differentiation between closed-architecture platforms and open-system alternatives. Two strategic archetypes dominate: diversified dental conglomerates controlling end-to-end workflows, and focused software specialists enabling multi-vendor interoperability. Competitive moves center on regulatory pre-clearance strategies for AI-enabled modules and cloud-native subscription transitions that displace perpetual licensing.
Among diversified dental technology conglomerates, Dentsply Sirona and Straumann Group exemplify integrated ecosystem control spanning scanner hardware through fabrication equipment. Within the specialized software tier, 3Shape A/S occupies a position representing open-architecture alternatives that compete against closed systems. These three anchors illustrate the structural tension between proprietary workflow lock-in and interoperability-driven procurement preferences across laboratory and clinic end users.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Align Technology |
| 3Shape A/S |
| Straumann Group |
| Planmeca Oy |
| Ivoclar Vivadent |
| Envista Holdings Corporation |
| Carestream Dental |
| 3D Systems |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta freight corridor connects East Asian ceramic foundries to European milling machine operators, with container rate volatility transmitting directly into zirconia blank procurement costs and forcing tiered pricing separation between FDA-cleared premium scanners and entry-tier optical devices for cost-sensitive Indian clinics.
Pricing Analysis
The customization-premium spread separates configured-to-order intraoral scanners with embedded AI diagnostic modules from standard hardware-only configurations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with FDA 510(k) clearance commanding substantial premiums over CE-marked equivalents. Pricing pressure stems from domestic Chinese manufacturers compressing mid-tier scanner margins through cost-efficient Shanghai and Guangzhou production. Independent dental laboratories exhibit highest price sensitivity due to capital constraints, while consolidated clinic chains absorb premium tiers for ecosystem lock-in.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for digital dentistry equipment. Component sourcing concentrates in Germany, Japan, and China, with high-speed scanning heads from Stuttgart's precision engineering corridor, optical sensors from Japanese manufacturers, and zirconia blanks from Yangtze River Delta ceramic foundries. Raw material dependencies span lithium disilicate glass ceramics, photopolymer resins, and rare-earth optical coatings. Distribution runs through specialized dental equipment distributors with regional service capabilities, though direct manufacturer-to-laboratory cloud platform subscriptions are displacing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated dental service organizations that negotiate enterprise-tier pricing for multi-clinic scanner deployments, fragmenting procurement authority previously held by independent practitioners.
For Market Incumbents: Insulate proprietary ecosystem margins by deepening backward integration into optical sensor production and accelerating FDA pre-submission pathways for AI-enabled diagnostic modules. Closed-architecture CAD/CAM systems face substitution threat from open-platform competitors; channel control through cloud-connected treatment planning platforms remains the critical defensive lever. For New Entrants and Emerging Players: Pursue whitespace in India's underpenetrated private clinic networks where government health digitization initiatives reduce upfront adoption friction. Subscription-based cloud CAD platforms for mid-sized laboratories offer the most penetrable entry point, with a direct-to-laboratory sales model bypassing established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized software vendors with open-architecture interoperability credentials over hardware-locked incumbents facing margin compression. Long-term viability hinges on regulatory pre-clearance velocity for AI diagnostic modules across FDA, EMA, and PMDA jurisdictions. Watch for inflection in reimbursement policy for radiographic caries detection algorithms as signal of platform value capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-Submission Engagement | Accelerated clearance timelines for AI-assisted diagnostic modules reduce competitive lag in United States market entry. |
| Cloud-Native CAD Platform Migration | Subscription revenue capture from mid-sized laboratories displaces perpetual-license pricing models. |
| Open-Architecture Interoperability Certification | Multi-vendor hardware compatibility attracts procurement preference from German laboratory clusters. |
| Direct-to-Consumer Scanning Network Expansion | Patient-facing treatment visualization in Japan and South Korea bypasses traditional dentist intermediaries. |
| Backward Integration into Optical Components | Captive supply of high-speed scanning heads insulates margins from Stuttgart supplier concentration. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with dental laboratory directors, intraoral scanner procurement officers at clinic chains, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, CE marking databases under EU MDR, PMDA submission records, and hospital procurement contract aggregators. Bottom-up equipment installation counts triangulated against top-down manufacturer revenue disclosures.
Forecast inputs considered technology adoption curves across optical imaging, CAD software, and AI diagnostic modules over the projection horizon. Segmentation dimensions modeled include product type tiers, deployment scale, regulatory certification pathway, and regional reimbursement environment. CAGRs derived from equipment replacement cycles, software subscription renewal rates, and procedural volume elasticity to scanner penetration. Industry-specific inputs incorporated FDA clearance velocity for AI algorithms and EU MDR clinical evidence requirements.
Macroeconomic conditions sit as an overlay; deviation in freight cost indices, dental procedure reimbursement rates, or ceramic raw material pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway efficiency and laboratory technician training pipeline capacity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
North America Dental Lab Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Dental Impression System Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
China Dental Implants Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Dental Chair Market
Dental Devices
Dental Units Market