
 Gingivitis Treatment Market | 2026-2036
Gingivitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Gingivitis Treatment Market Foresight
Microbiome-targeted formulation science is fragmenting traditional antimicrobial development pipelines across oral care. Colgate-Palmolive leverages its therapeutic toothpaste portfolio to anchor professional channel relationships in North America. GlaxoSmithKline competes through prescription-strength chlorhexidine formulations that dominate dental office dispensing. Johnson & Johnson sustains consumer-pull brand equity for its daily-use rinse and floss systems.
Gingivitis treatment encompasses pharmacological and mechanical interventions designed to disrupt supragingival plaque biofilm, reduce inflammatory mediators, and restore gingival tissue homeostasis, with active ingredients ranging from cetylpyridinium chloride to essential oil formulations dosed at precise concentrations for regulatory compliance. Antimicrobial mouthwash and therapeutic toothpaste command the largest revenue pools, reflecting their dual presence in professional protocols and daily home regimens. Dental clinics represent the fastest-growing end-user channel as chairside prophylaxis and prescription dispensing deepen clinician control over treatment adherence.
The FDA regulates over-the-counter oral antiseptics under monograph standards that mandate clinical substantiation of plaque and gingivitis reduction claims, while the EPA oversees environmental discharge limits for manufacturing facilities producing chlorhexidine and other biocidal actives. The EU Medical Device Regulation and REACH chemical registration requirements impose additional compliance burdens on suppliers accessing European dental markets. Stakeholders must monitor evolving antimicrobial resistance designations that could reclassify longstanding active ingredients and trigger reformulation investments.
Market Dynamics
The FDA's tightening efficacy substantiation requirements for antimicrobial rinse formulations are restructuring competitive positioning across oral care, forcing manufacturers to invest in clinical validation infrastructure that smaller players cannot sustain.
Growth Catalysts
- Insured preventive dental protocols:The United States dental reimbursement framework incentivizes recurring professional prophylaxis visits, generating sustained prescription-strength product demand through chairside dispensing channels.
- Professional channel expansion:Dental clinics are deepening adoption of standardized prophylaxis protocols, creating captive demand for therapeutic toothpaste and antimicrobial rinse formulations validated under FDA monograph standards.
- Microbiome science maturation:Advances in biofilm disruption mechanisms are enabling next-generation formulations that target specific periodontal pathogens without broad-spectrum biocidal resistance risks.
Market Restraints
- Chlorhexidine supply concentration:Active pharmaceutical ingredient production for prescription-strength rinses concentrates among limited European and Asian contract manufacturers, exposing formulators to input cost volatility and qualification delays.
- Antimicrobial resistance reclassification risk:The EPA's evolving biocidal active substance review process threatens to redesignate longstanding ingredients like cetylpyridinium chloride, triggering forced reformulation investments.
- Generic substitution pressure:Patent-expired chlorhexidine gluconate formulations face commoditization as compounding pharmacies and private-label distributors enter dental office procurement.
Strategic Opportunities
- Direct-to-consumer subscription channels:Telehealth-integrated oral care platforms are emerging as viable distribution paths for prescription-strength maintenance regimens, bypassing traditional dental office gatekeepers.
- EU Medical Device Regulation tailwinds:MDR certification requirements for antimicrobial devices create competitive moats for manufacturers with established quality management systems and notified body relationships.
- Salivary diagnostics convergence:Integration of point-of-care periodontal pathogen testing with personalized rinse protocols represents an emerging application white space in preventive dentistry.
Industry Challenges
- Clinical trial talent scarcity:The specialized workforce required for FDA-compliant plaque and gingivitis reduction studies is concentrated among a handful of contract research organizations, extending study timelines.
- Legacy manufacturing system integration:Real-time release testing for microbiome-targeted formulations demands retrofitting of existing oral care production lines with advanced analytical equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gingivitis Treatment Market |
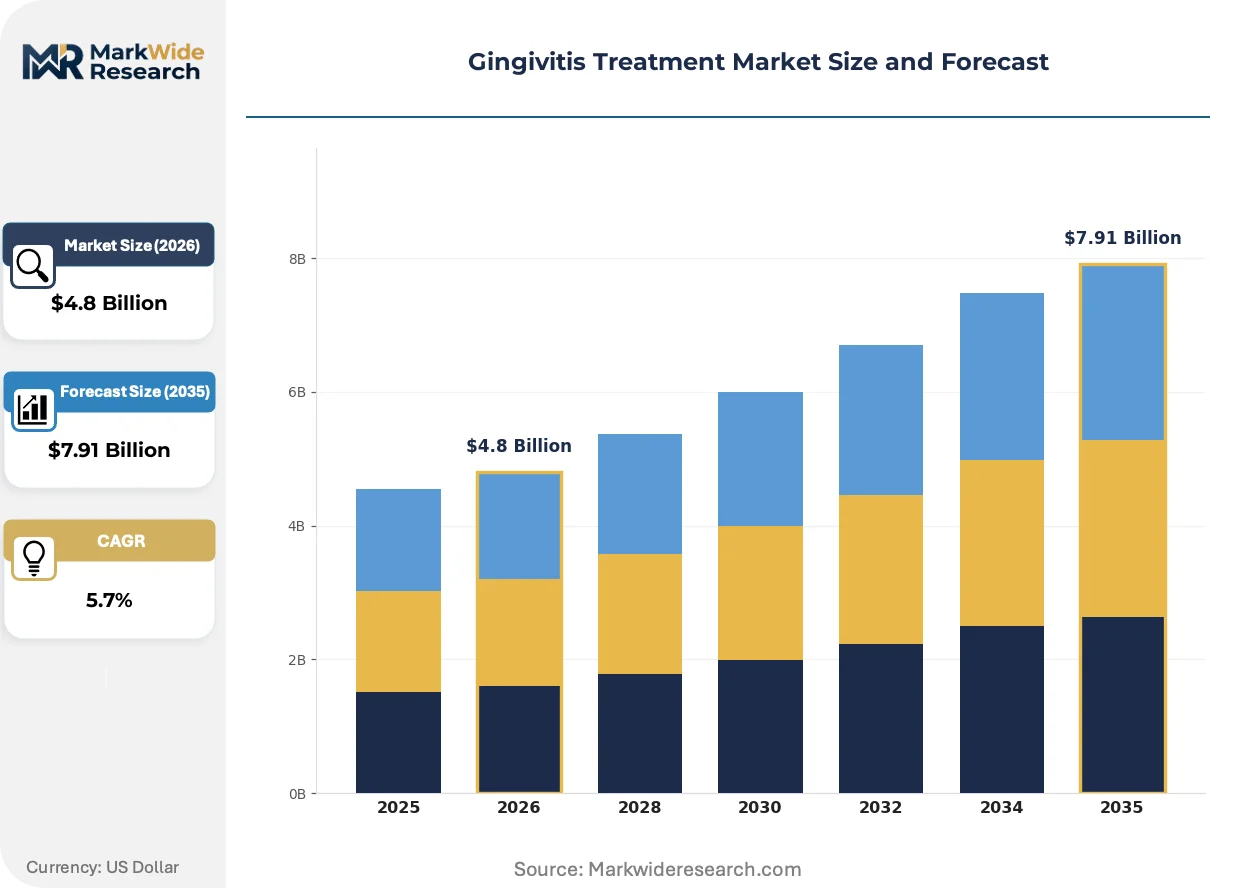
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial Mouthwash, Toothpaste, Dental Floss, Oral Gel, Chewing Gum Therapy Area: Mild Gingivitis, Moderate Gingivitis, Chronic Gingivitis, Pregnancy Gingivitis, Drug-Induced Gingivitis End User: Dental Clinics, Dental Hospitals, Dental Hygienists, Oral Care Centers, Home Care Distribution Channel: Pharmacies, Online Retailers, Supermarkets, Dental Professionals, Specialty Stores |
| Companies Covered | Colgate-Palmolive, Johnson & Johnson, GlaxoSmithKline, Procter & Gamble, Dentsply Sirona, Henry Schein, Straumann Group, Envista Holdings Corporation, Perioe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gingivitis Treatment Market Shifts & Advancements
Formulation science is fragmenting traditional antimicrobial development pipelines as microbiome-targeted approaches gain professional credibility. Three distinct shifts are reshaping how therapeutic oral care products reach end users.
Essential oil-based formulations are hybridizing with precision-delivery systems to achieve biofilm penetration depths previously limited to chlorhexidine. Dental hygienists in premium clinic networks are adopting these protocols for maintenance-phase patients with established gingivitis. The technology is compressing market share for alcohol-based rinses by delivering comparable efficacy without tissue irritation or staining liabilities.
REACH chemical registration requirements in Europe are forcing reformulation of cetylpyridinium chloride concentrations across export-bound product lines. Manufacturers serving EU dental markets must now submit extended toxicity dossiers that extend registration timelines by 18-24 months. Smaller oral care suppliers are responding by withdrawing from European distribution rather than absorbing compliance costs.
Subscription-based replenishment models are displacing retail-driven trial purchases for daily-use therapeutic rinses. Direct-to-consumer platforms are capturing patient adherence data that dental offices previously controlled, shifting influence over regimen selection. This pattern is most visible in United States metropolitan markets where insured patients face high deductible barriers to frequent professional visits.
Gingivitis Treatment Market Segmentation
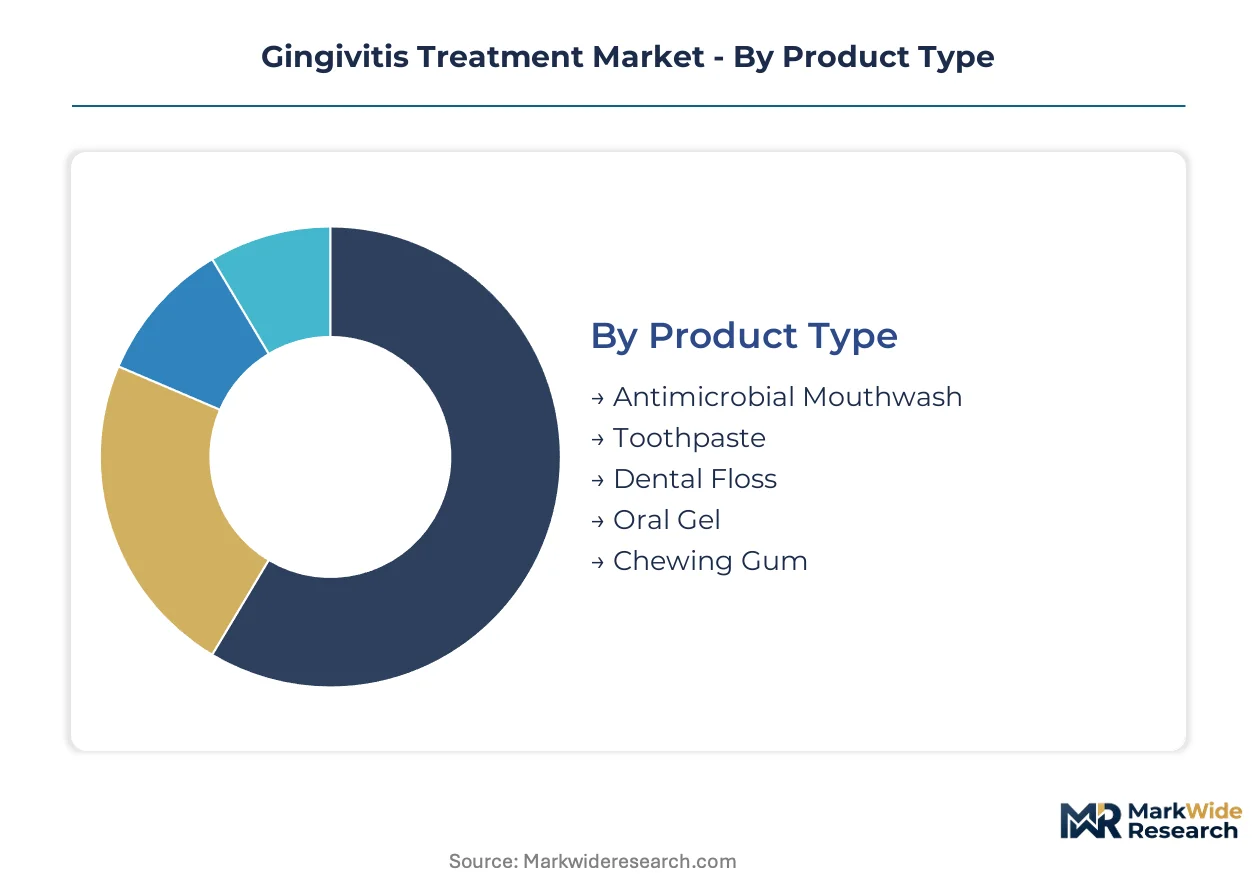
Gingivitis treatment segmentation reflects the dual-channel reality of oral care, where professional protocols and daily home regimens generate distinct demand profiles. Therapeutic efficacy requirements vary sharply across these boundaries, forcing manufacturers to maintain parallel formulation portfolios.
Product Type:
Mature rinse and paste categories coexist with emerging delivery formats that target adherence gaps in maintenance-phase patients.
- Antimicrobial Mouthwash:Formulations range from essential oil blends to prescription-strength chlorhexidine gluconate at concentrations requiring FDA monograph compliance. Dental clinics in the United States drive recurring demand through chairside dispensing of therapeutic rinses validated for plaque reduction claims.
- Toothpaste:Therapeutic variants incorporate stannous fluoride, zinc citrate, or triclosan alternatives at precise concentrations for anti-gingivitis labeling. Professional channel expansion in metropolitan United States markets concentrates demand for prescription-strength formulations dispensed post-prophylaxis.
- Dental Floss:Coated and tape variants deliver interdental plaque disruption with expanding adoption among home care regimens.
- Oral Gel:Targeted delivery systems for localized gingival inflammation are gaining traction in specialty periodontal protocols.
- Chewing Gum:Xylitol and antimicrobial-infused formats address on-the-go biofilm management in consumer-driven segments.
Antimicrobial mouthwash retains volume leadership; oral gel holds the steepest expansion curve.
Therapy Area:
Severity-based stratification determines whether treatment protocols rely on over-the-counter maintenance or prescription intervention.
- Mild Gingivitis:Characterized by localized inflammation without attachment loss, this segment responds to daily mechanical disruption and OTC antimicrobial rinses. United States insured populations generate sustained volume through preventive dental visit protocols that catch disease at this stage.
- Moderate Gingivitis:Widespread erythema and bleeding on probing demand stepped-up intervention with prescription-strength formulations. Dental hygienists in premium United States clinic networks concentrate dispensing authority for maintenance-phase patients at this severity threshold.
- Chronic Gingivitis:Persistent inflammation despite standard care requires specialized periodontal referral pathways in hospital settings.
- Pregnancy Gingivitis:Hormonally-mediated vascular changes create temporary demand for alcohol-free, pregnancy-safe formulations.
- Drug-Induced Gingivitis:Calcium channel blocker and anticonvulsant side effects necessitate co-management with prescribing physicians.
Mild gingivitis captures the largest addressable base; pregnancy gingivitis is climbing the fastest as prenatal oral health protocols expand.
End User:
Clinical settings extract premium pricing for supervised protocols while home care segments prioritize convenience and cost.
- Dental Clinics:Chairside prophylaxis and prescription dispensing create captive demand for therapeutic formulations validated under FDA standards. United States reimbursement frameworks incentivize recurring professional visits that sustain this channel's expansion trajectory.
- Dental Hospitals:Complex cases requiring periodontal specialty intervention concentrate in academic medical centers with integrated oral medicine departments.
- Dental Hygienists:Independent practice authority in select United States states enables direct dispensing of maintenance-phase products.
- Oral Care Centers:Retail-clinical hybrid formats are emerging in suburban United States markets with high deductible insurance penetration.
- Home Care:Daily-use regimens dominate volume but face adherence attrition without professional oversight mechanisms.
Home care dominates absolute volume; dental clinics are gaining share fastest as prophylaxis protocols standardize.
Distribution Channel:
Channel selection directly determines whether patients encounter therapeutic products through professional recommendation or self-directed purchase.
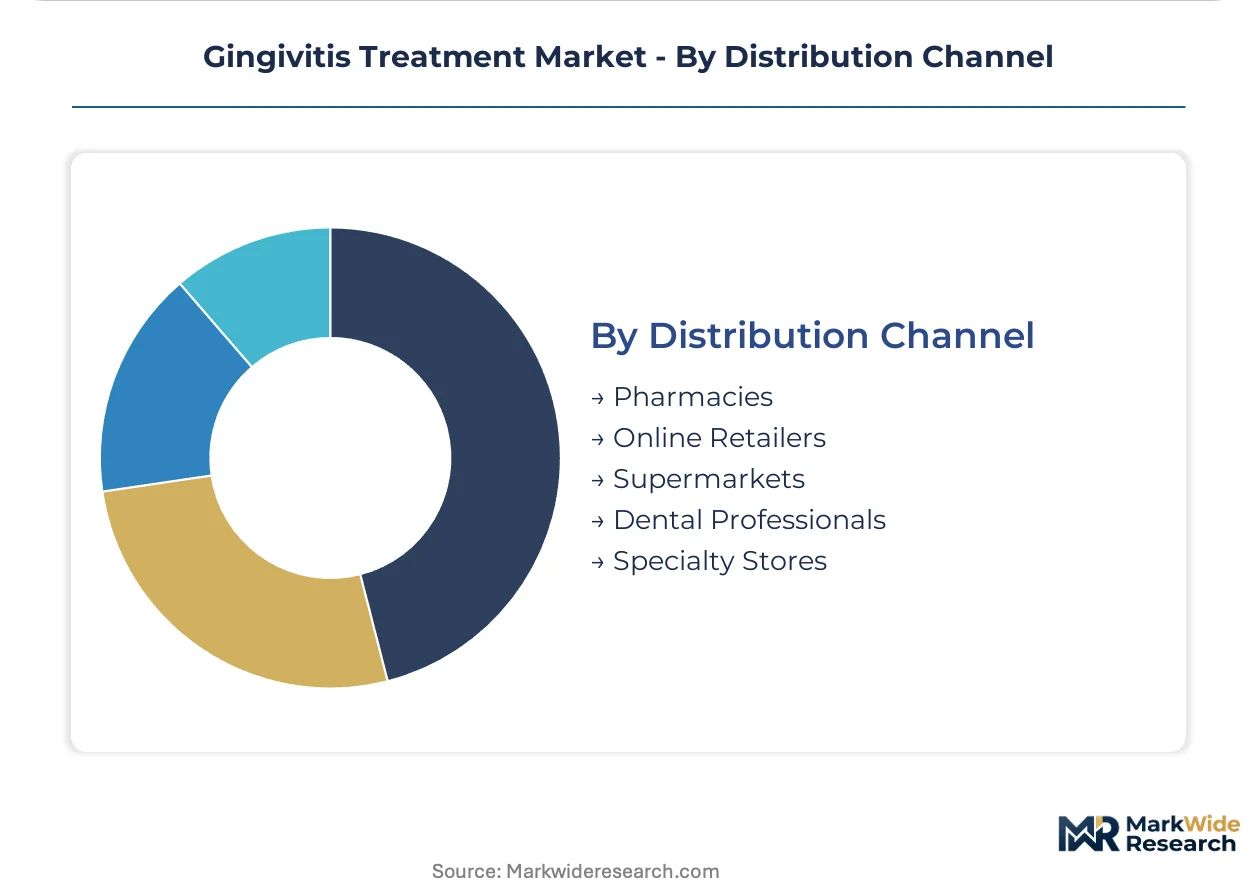
- Pharmacies:Brick-and-mortar and mail-order channels handle prescription-strength rinse fulfillment with insurance adjudication. United States retail pharmacy chains maintain dedicated oral care sections with pharmacist counseling for therapeutic product selection.
- Online Retailers:Subscription-based replenishment models capture adherence data and displace retail trial purchases in metropolitan United States markets. Direct-to-consumer platforms integrate telehealth screening to qualify patients for prescription-strength maintenance regimens.
- Supermarkets:Mass-market toothpaste and rinse SKUs compete on shelf space and promotional pricing for undifferentiated consumers.
- Dental Professionals:Chairside dispensing and sample distribution maintain clinician control over regimen initiation and adherence.
- Specialty Stores:Premium oral care boutiques cater to aesthetic-conscious consumers seeking natural or microbiome-targeted formulations.
Pharmacies retain the largest transaction volume; online retailers show the steepest expansion trajectory as subscription models displace episodic purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based manufacturers export professional-grade prophylaxis formulations to dental networks across Canada, Mexico, and select European markets. This trade corridor concentrates value-added therapeutic products while sourcing active pharmaceutical ingredients from contract manufacturers in India and China.
United States
Insured preventive dental visits and chairside dispensing protocols generate recurring demand for prescription-strength chlorhexidine and therapeutic toothpaste. FDA monograph compliance requirements under 21 CFR 355 and 356 govern antimicrobial rinse efficacy claims, mandating clinical substantiation for plaque reduction labeling. Metropolitan dental clinic networks in New York, Los Angeles, and Chicago anchor professional channel expansion for standardized prophylaxis regimens.
Germany
Precision manufacturing capabilities and dental technology clusters sustain export-oriented production of professional-grade oral care devices and formulations. REACH chemical registration through ECHA imposes extended toxicity dossier requirements on cetylpyridinium chloride concentrations, extending market entry timelines by 18-24 months. The Baden-Württemberg and Bavaria regions concentrate formulation R&D facilities serving EU dental markets.
China
Domestic demand for preventive oral care rises alongside urban middle-class expansion and private dental clinic proliferation. NMPA oversight of therapeutic toothpaste and antimicrobial rinse registrations requires local clinical trials, creating barriers for imported formulations. Shanghai and Guangzhou dental supply hubs concentrate distribution infrastructure for professional channel products.
India
Contract manufacturing of chlorhexidine gluconate active pharmaceutical ingredients supplies formulators in North America and Europe. CDSCO regulation of antiseptic oral preparations under the Drugs and Cosmetics Act mandates manufacturing facility inspections and quality documentation. Hyderabad and Mumbai pharmaceutical clusters dominate API production for export markets.
Japan
Aging demographics and elevated periodontal disease awareness sustain demand for maintenance-phase therapeutic products. PMDA quasi-drug classification for medicated toothpaste requires efficacy documentation distinct from cosmetic oral care claims. The Kanto region around Tokyo concentrates dental product distribution and professional education networks.
Gingivitis Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational consumer health conglomerates with therapeutic toothpaste portfolios, pharmaceutical specialists with prescription-strength antimicrobial formulations, and dental equipment distributors expanding into consumable product lines. The dominant competitive moves involve professional channel partnerships with clinic networks and regulatory-driven portfolio diversification to address FDA monograph and REACH compliance requirements.
Within the multinational consumer health tier, Colgate-Palmolive and Johnson & Johnson occupy positions anchored by daily-use rinse and therapeutic toothpaste brand equity. GlaxoSmithKline represents the prescription-strength formulation archetype through chlorhexidine-based dental office dispensing. These three companies exemplify divergent strategic paths: consumer-pull brand building versus professional channel control versus pharmaceutical-grade clinical validation.
| Leading Market Players |
|---|
| Colgate-Palmolive |
| Johnson & Johnson |
| GlaxoSmithKline |
| Procter & Gamble |
| Dentsply Sirona |
| Henry Schein |
| Straumann Group |
| Envista Holdings Corporation |
| Perioe |
| Others |
Supply & Pricing Matrix
The Shanghai-Long Beach maritime corridor governs freight cost dynamics for chlorhexidine active pharmaceutical ingredient shipments, compressing margins for North American formulators while amplifying price differentiation between prescription-grade and maintenance-phase product tiers.
Pricing Analysis
Next-generation microbiome-targeted formulations command substantial premiums over legacy chlorhexidine gluconate and essential oil benchmarks, with price stratification across premium, standard, and economy tiers driven by FDA monograph certification status and clinical validation depth. Cost compression in generic chlorhexidine segments intensifies as Indian and Chinese API suppliers expand volume quotas. Dental clinics exhibit the lowest price sensitivity due to insurance reimbursement capture, while direct-to-consumer subscription buyers demonstrate acute responsiveness to out-of-pocket cost exposure.
Supply Chain Analysis
Extended payment terms from European contract manufacturers now stretch to 90-120 days for qualified buyers, reshaping working capital requirements across formulation tiers. Chlorhexidine gluconate API production concentrates in India, China, and select Italian pharmaceutical clusters, drawing from naphtha-derived chemical precursors and specialized fermentation feedstocks. Single-source vulnerability pervades prescription-strength rinse manufacturing where FDA facility qualification creates switching costs. Distribution runs through dental supply distributors and direct-to-consumer platforms in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized clinical trial infrastructure for FDA-compliant plaque reduction studies represents the scarcest capability layer, constraining how quickly formulation science advances can reach commercial validation.
For Market Incumbents: Entrench professional channel control through exclusive dispensing partnerships with metropolitan dental clinic networks, while accelerating backward integration into chlorhexidine API production to offset Indian and Chinese supplier pricing volatility. FDA monograph compliance investments create defensive moats against generic substitution pressure from compounding pharmacies. For New Entrants and Emerging Players: Telehealth-integrated subscription platforms for maintenance-phase patients in high-deductible United States insurance markets represent the most penetrable entry point, bypassing traditional dental office gatekeepers through direct-to-consumer qualification protocols. Salivary diagnostic integration with personalized rinse formulations offers a differentiated go-to-market angle. For Investors and Strategic Acquirers: Regional dental supply distributors with established clinic network relationships and quality management systems pre-qualified for EU MDR certification represent the highest-conviction acquisition archetype. Long-term viability hinges on antimicrobial resistance designation risk rather than cyclical demand fluctuation. Watch EPA biocidal active substance review timelines as the critical inflection signal for forced reformulation exposure across portfolio holdings.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Infrastructure Investment | Builds FDA monograph submission capacity that smaller competitors cannot replicate. |
| Professional Channel Partnership Expansion | Secures chairside dispensing access through exclusive clinic network agreements. |
| Microbiome-Targeted Formulation Pipeline | Addresses antimicrobial resistance risks while commanding premium pricing tiers. |
| EU MDR Certification Acceleration | Creates competitive moats as REACH compliance costs force smaller suppliers to exit. |
| Direct-to-Consumer Platform Integration | Captures patient adherence data and subscription revenue outside dental office control. |
Research Methodology
The analysis maps antimicrobial mouthwash, therapeutic toothpaste, oral gel, and dental floss segments, each validated through dental hygienists, clinic procurement managers, pharmaceutical regulatory affairs leads, and contract research organization directors. Primary interview findings triangulate against FDA 510(k) filings, EPA antimicrobial pesticide registration data, CDSCO manufacturing facility inspection records, and EU MDR notified body certification databases. Bottom-up volume estimates from product-level dispensing data reconcile with top-down market sizing derived from dental reimbursement claims patterns.
Assumptions held fixed across the projection horizon include sustained United States preventive dental visit reimbursement rates and stable EPA biocidal active substance designations for chlorhexidine and cetylpyridinium chloride. The analytical framework models therapy area severity, end-user channel, and distribution format segmentation dimensions. CAGRs derive from regression analysis of historical dispensing volume trends against insured population growth and professional protocol adoption curves. Input variables incorporate API pricing indices from Indian pharmaceutical export data and dental clinic network expansion rates in metropolitan United States markets.
Stress conditions across antimicrobial resistance reclassification probability, chlorhexidine API supply disruption scenarios, and telehealth platform regulatory scrutiny were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
India Dental Devices Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
United States Dental Implants Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
Dental Laboratories Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Dental Contouring Market
Dental Devices
Dental Laboratory Handpiece Market
Dental Devices
North America Dental Lab Market