
 Italy Ophthalmic Devices Market | 2026-2036
Italy Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Ophthalmic Devices Market Foresight
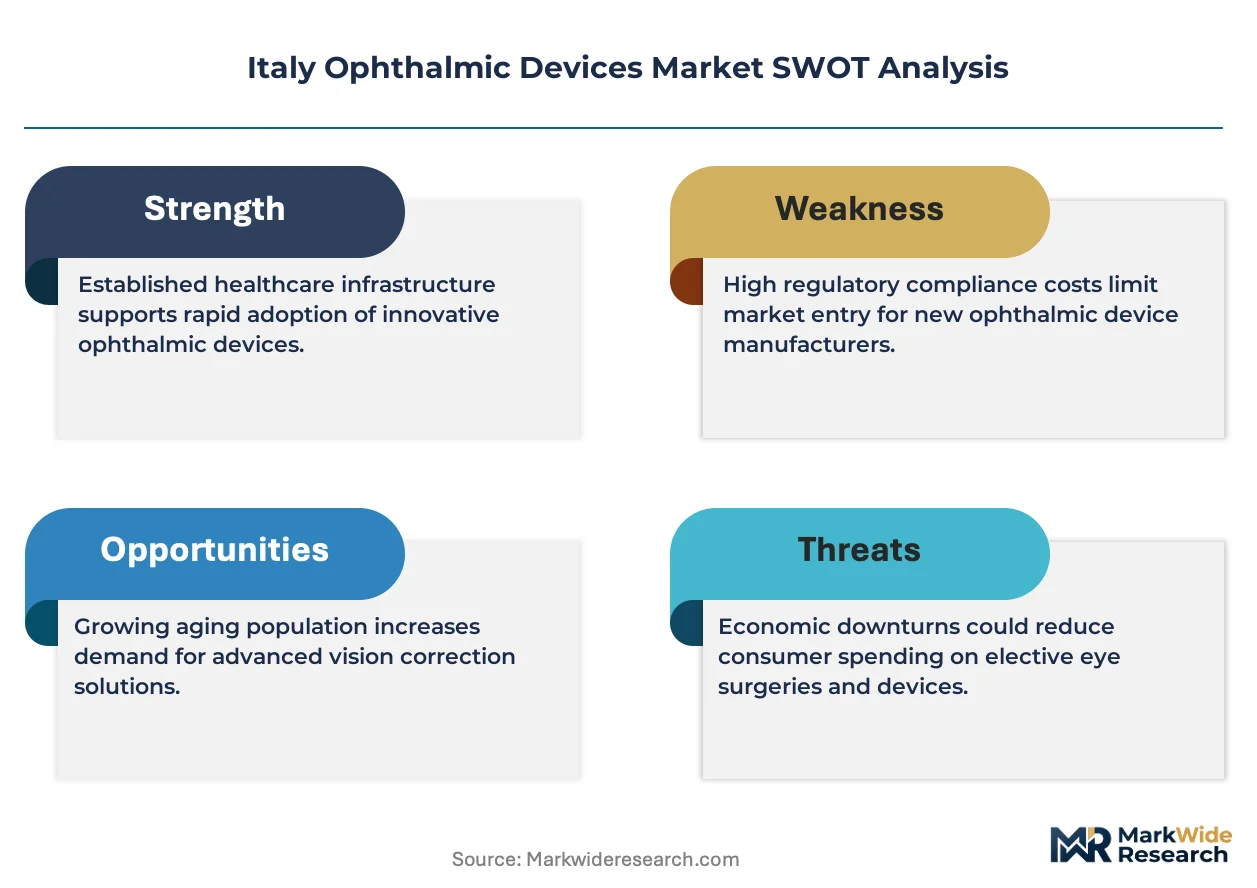
Ophthalmologist workforce scarcity in southern regions is bifurcating the Italy ophthalmic devices market into high-automation north and labor-dependent south. Alcon Inc leverages its phacoemulsification platform to dominate cataract workflow automation. Carl Zeiss Meditec AG anchors premium diagnostic positioning through OCT technology leadership. Johnson & Johnson Vision competes across refractive and surgical segments with integrated consumable-device bundles.
Ophthalmic devices encompass precision instruments, implants, and diagnostic systems engineered to optical tolerances measured in micrometers, designed for the diagnosis, surgical intervention, and management of ocular disease. These systems integrate laser sources, ultrasound transducers, or optical coherence interferometry to restore or preserve visual function in clinical settings. Diagnostic Equipment commands the largest revenue pool due to recurring software upgrades and service contracts, while Laser Surgery represents the fastest-expanding technology segment driven by femtosecond platform adoption. Intraocular Lenses sustain above-average margins through toric and multifocal premium variants, whereas Contact Lenses face volume pressure from refractive surgery alternatives.
Italy's Ministry of Health enforces EU MDR conformity requirements through notified body oversight, extending certification timelines and elevating clinical evidence burdens for device manufacturers. The National Health Service reimbursement framework shapes hospital capital expenditure cycles, with regional health authorities determining technology adoption speed. Stakeholders must monitor how EU AI Act classification rules will affect automated diagnostic algorithms embedded in next-generation fundus imaging platforms.
Market Dynamics
Italy's National Health Service procurement cycles are compressing capital equipment replacement timelines as regional health authorities compete for surgical throughput capacity. This structural acceleration favors automated phacoemulsification platforms over manual alternatives.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation is forcing hospital systems to refresh diagnostic equipment inventories ahead of certification expiry dates.
- Lombardy surgical volume concentration:Milan's ophthalmology cluster generates equipment demand density that sustains premium technology uptake.
- Femtosecond laser platforms:Refractive surgery centers are upgrading excimer systems to all-laser workflows for corneal flap creation.
Market Restraints
- Notified body capacity constraints:EU MDR certification bottlenecks are extending product registration timelines by 12-18 months for Class III devices.
- Silicon photonics input dependency:OCT system manufacturers face concentrated supply risk from Asian wafer foundries.
- Refractive surgery substitution:LASIK and SMILE procedures are eroding contact lens replacement volume in urban centers.
Strategic Opportunities
- Sicily and Calabria underpenetration:Southern regions exhibit ophthalmologist density gaps that telemedicine-linked diagnostic platforms could address.
- EU AI Act algorithm classification:Automated fundus screening tools may qualify for expedited regulatory pathways if clinical validation thresholds are met.
- Integrated consumable-device bundles:Refractive surgery chains are consolidating supplier relationships around single-vendor workflow ecosystems.
Industry Challenges
- Vitreoretinal surgeon training pipelines:Fellowship program capacity constraints limit adoption of complex surgical platforms in peripheral hospitals.
- Legacy EMR integration:Diagnostic imaging systems require costly middleware development to connect with heterogeneous hospital information architectures.
- CE mark renewal documentation:Post-market clinical follow-up studies impose recurring evidence generation burdens on mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Ophthalmic Devices Market |
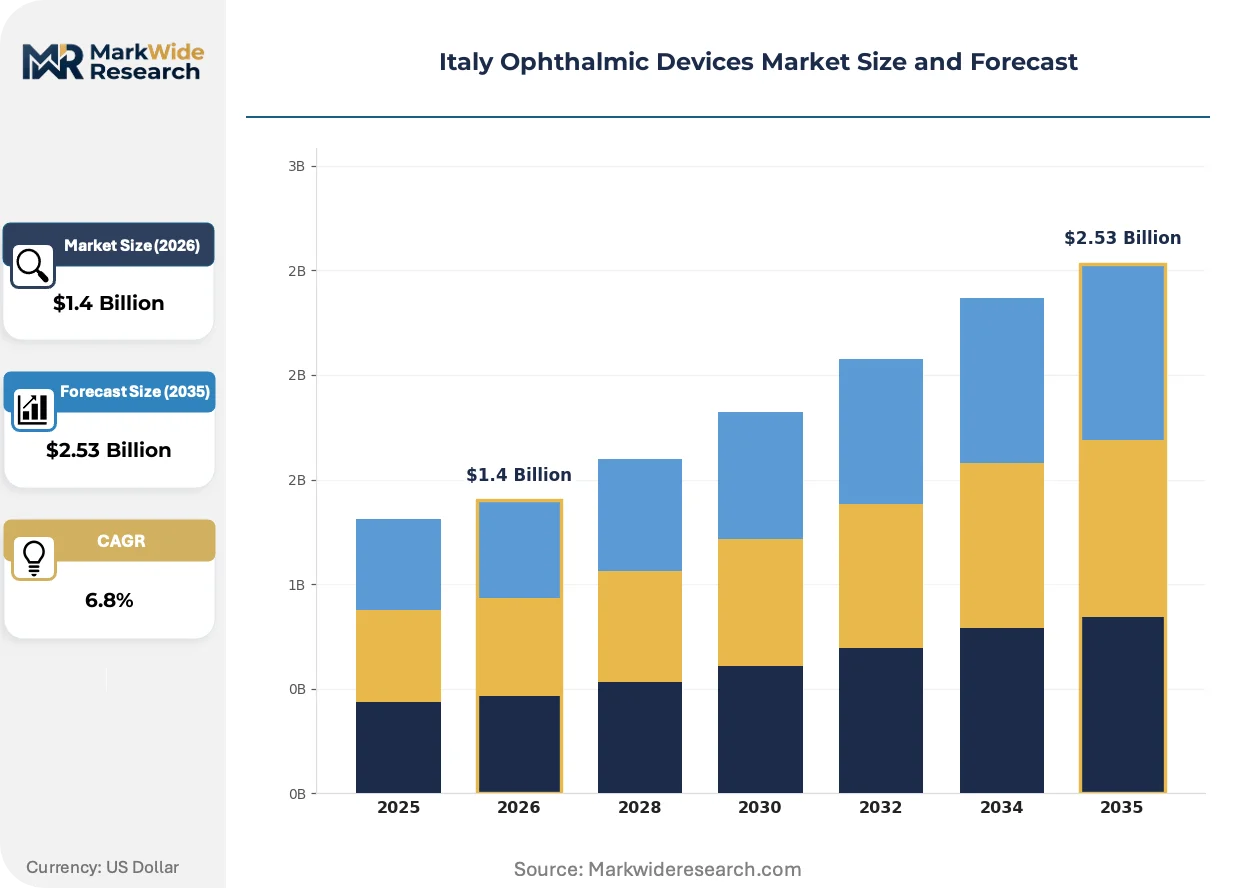
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Lenses, Intraocular Lenses, Surgical Instruments, Diagnostic Equipment End User: Hospitals, Clinics, Optical Retailers, Research Institutes Technology: Laser Surgery, Virtual Reality, OCT, Phacoemulsification Application: Cataract Surgery, Refractive Surgery, Glaucoma Management, Fundus Imaging |
| Companies Covered | Alcon Inc, Carl Zeiss Meditec AG, Johnson & Johnson Vision, Bausch + Lomb Corp., EssilorLuxottica S.A., Topcon Corp., Nidek Co. Ltd., Hoya Corp., HAAG-Streit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Ophthalmic Devices Market Shifts & Advancements
Femtosecond laser technology is fragmenting traditional cataract surgery workflows into discrete automated steps. This decomposition is reshaping capital allocation patterns across Italy's regional health systems.
Optical coherence tomography angiography is decomposing fluorescein-based retinal imaging into non-invasive, repeatable diagnostic protocols. Academic medical centers in Milan and Bologna are adopting these systems at replacement-cycle velocity. The technology is compressing dye-dependent procedure volumes and redirecting service revenue toward software-enabled analytics subscriptions.
Italy's Ministry of Health is enforcing EU MDR transition timelines through regional notified body oversight. Device manufacturers face parallel clinical evidence requirements for legacy product line renewals. Premium intraocular lens segments are absorbing compliance costs through toric and extended-depth-of-focus pricing premiums.
Hospital procurement committees are consolidating vendor relationships around full-service cataract workflow contracts. Independent surgery centers in Veneto and Emilia-Romagna are migrating from capital purchase models toward per-procedure leasing arrangements. This shift is most visible in phacoemulsification system deployments where utilization guarantees determine equipment access terms.
Italy Ophthalmic Devices Market Segmentation
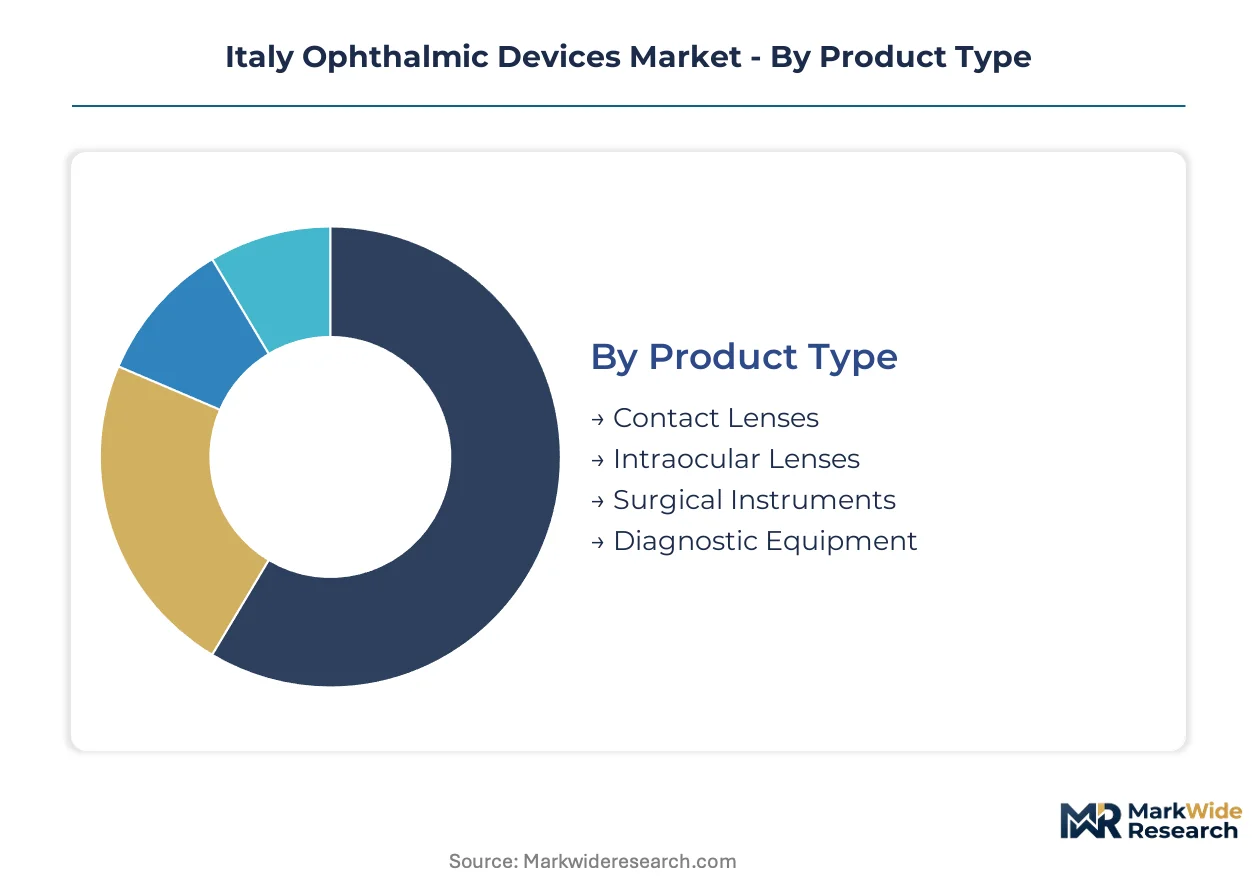
Segmentation in Italy's ophthalmic devices market reveals how reimbursement patterns and surgical volume concentration reshape equipment procurement across distinct customer channels. Understanding these divides exposes where substitution pressures and technology upgrade cycles create divergent growth trajectories.
Product Type:
Substitution pressure from refractive surgery alternatives is compressing volume in vision correction segments while surgical intervention categories capture displaced spending.
- Diagnostic Equipment:Systems integrating optical coherence tomography and fundus imaging generate recurring revenue through software subscriptions and service contracts. Lombardy's academic medical centers in Milan and Bologna drive replacement-cycle demand for angiography-capable platforms.
- Intraocular Lenses:Premium toric and extended-depth-of-focus variants command pricing premiums that absorb EU MDR compliance costs. Regional health authorities in Veneto and Emilia-Romagna prioritize these implants to reduce spectacle dependence post-cataract surgery.
- Surgical Instruments:Phacoemulsification handpieces and vitrectomy probes face per-procedure leasing pressure from integrated platform vendors.
- Contact Lenses:Daily disposable and silicone hydrogel formats confront volume erosion as SMILE and LASIK procedures expand in urban centers.
Diagnostic Equipment anchors the volume base while Intraocular Lenses gains share at the steepest rate.
End User:
Procurement authority concentration determines which customer channels control technology adoption speed and pricing leverage.
- Hospitals:Italy's National Health Service regional authorities consolidate capital expenditure decisions for phacoemulsification and femtosecond laser platforms. Lombardy and Veneto health systems compress replacement timelines to compete for surgical throughput.
- Clinics:Independent ophthalmology centers in Milan's cluster migrate toward per-procedure equipment leasing models with utilization guarantees. These facilities prioritize diagnostic imaging systems with automated analysis capabilities.
- Optical Retailers:Contact lens dispensing faces margin pressure from e-commerce channels and refractive surgery marketing.
- Research Institutes:Academic medical centers in Bologna and Rome drive early adoption of OCT angiography and AI-embedded screening tools.
Hospitals dominate capital equipment procurement while Clinics expand most quickly through leasing model adoption.
Technology:
Margin structure across technology segments reflects regulatory burden intensity and supply chain input concentration.
- OCT:Optical coherence tomography systems depend on silicon photonics components from concentrated Asian wafer foundries, creating supply vulnerability. Italian academic centers adopt angiography modules to displace fluorescein-based protocols.
- Phacoemulsification:Ultrasound-based cataract extraction platforms anchor hospital surgical workflow automation. Alcon's integrated systems dominate procurement committees seeking full-service contracts.
- Laser Surgery:Femtosecond platforms for corneal flap creation command premium positioning in refractive surgery chains.
- Virtual Reality:Vision therapy and surgical training applications remain nascent in Italian clinical adoption.
Phacoemulsification generates the largest installed base revenue while OCT climbs the fastest on diagnostic protocol conversion.
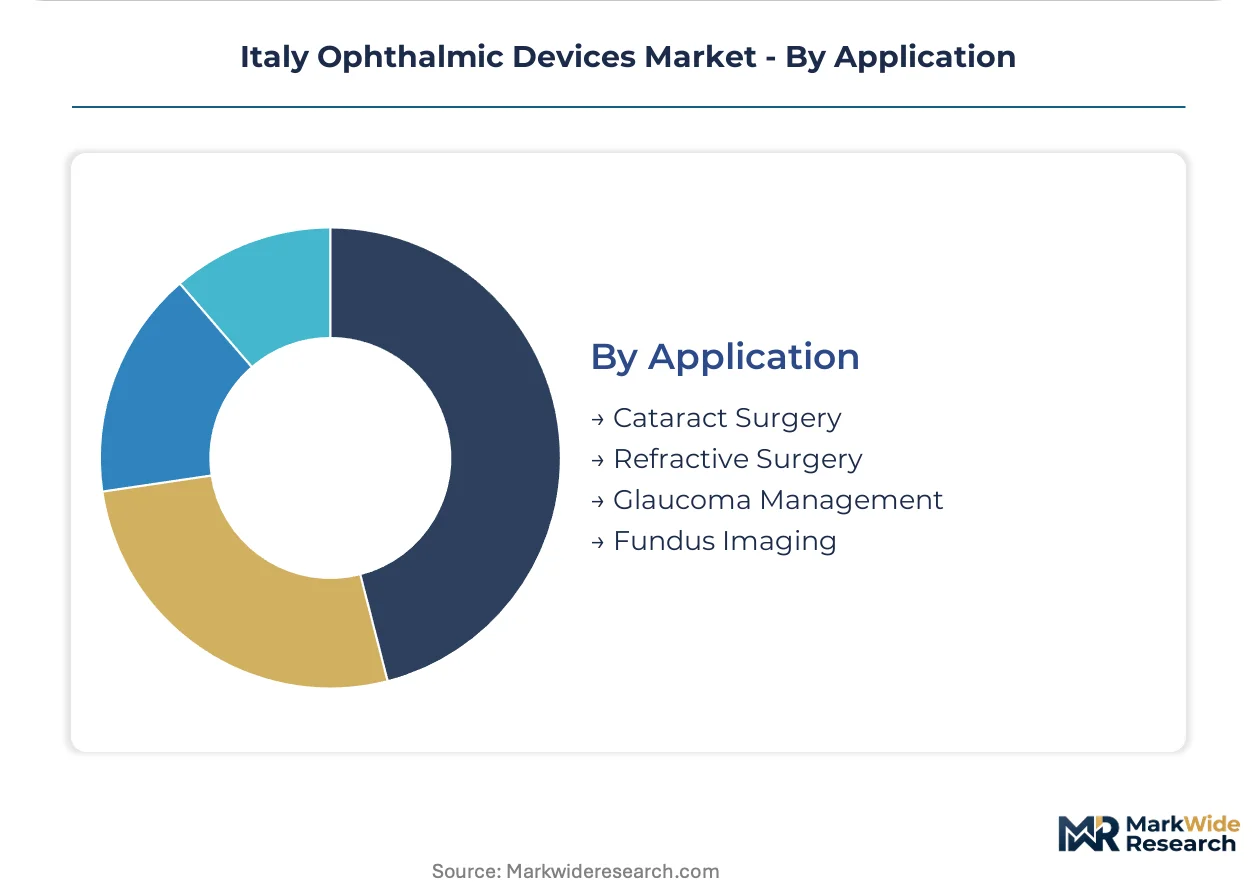
Application:
Procedure volume distribution across applications mirrors Italy's demographic aging patterns and regional surgeon density disparities.
- Cataract Surgery:Italy's aging population sustains procedure volume growth, with femtosecond laser adoption fragmenting traditional workflows into automated steps. Regional health authorities prioritize throughput capacity in Lombardy and Emilia-Romagna.
- Refractive Surgery:LASIK and SMILE procedures erode contact lens demand in urban centers while expanding independent surgery center equipment needs.
- Glaucoma Management:Minimally invasive surgical devices and sustained-release drug delivery systems face adoption constraints from ophthalmologist training pipeline limitations in southern regions.
- Fundus Imaging:AI-embedded screening tools for diabetic retinopathy detection confront EU AI Act classification uncertainty.
Cataract Surgery commands the largest procedure volume while Refractive Surgery shows the steepest expansion trajectory among elective interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Ministry of Health enforces EU MDR conformity requirements through notified body oversight, extending certification timelines and elevating clinical evidence burdens for device manufacturers across the peninsula.
Lombardy
Milan's ophthalmology cluster generates equipment demand density that sustains premium technology uptake. Regional health authorities compress replacement timelines to compete for surgical throughput capacity. The concentration of academic medical centers in Milan and Bologna drives replacement-cycle demand for angiography-capable diagnostic platforms.
Veneto
Independent surgery centers in Veneto migrate toward per-procedure equipment leasing models with utilization guarantees. Regional health authorities prioritize premium toric and extended-depth-of-focus intraocular lenses to reduce spectacle dependence post-cataract surgery. Procurement committees consolidate vendor relationships around full-service cataract workflow contracts in Padua and Verona.
Emilia-Romagna
Regional health authorities in Emilia-Romagna prioritize throughput capacity for cataract procedures as Italy's aging population sustains volume growth. The National Health Service reimbursement framework shapes hospital capital expenditure cycles. Bologna's academic medical centers drive early adoption of OCT angiography and AI-embedded screening tools.
Lazio
Rome's research institutes confront EU AI Act classification uncertainty for automated fundus screening tools. The Ministry of Health enforcement of EU MDR transition timelines extends product registration timelines for Class III devices. Peripheral hospitals in the region face vitreoretinal surgeon training pipeline constraints that limit adoption of complex surgical platforms.
Sicily
Ophthalmologist workforce scarcity in Sicily creates underpenetration gaps that telemedicine-linked diagnostic platforms could address. Southern regions exhibit bifurcation from the high-automation north, remaining labor-dependent in surgical workflows. Catania and Palermo health systems lag in femtosecond laser platform adoption compared to northern counterparts.
Italy Ophthalmic Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around full-service workflow providers and precision diagnostic platforms. Alcon Inc leverages its phacoemulsification platform to dominate cataract workflow automation, while Carl Zeiss Meditec AG anchors premium diagnostic positioning through OCT technology leadership. Johnson & Johnson Vision competes across refractive and surgical segments with integrated consumable-device bundles. Strategic moves concentrate on M&A for technology integration and per-procedure leasing arrangements that lock in utilization guarantees.
Within the integrated platform tier, Alcon Inc and Johnson & Johnson Vision exemplify the shift toward bundled consumable-device ecosystems that consolidate supplier relationships. Carl Zeiss Meditec AG occupies a position representing premium diagnostic specialization through optical coherence technology leadership. These three companies anchor the competitive structure, with Alcon Inc representing Swiss-American surgical automation, Carl Zeiss Meditec AG exemplifying German precision optics heritage, and Johnson & Johnson Vision sitting within the diversified healthcare conglomerate archetype.
| Leading Market Players |
|---|
| Alcon Inc |
| Carl Zeiss Meditec AG |
| Johnson & Johnson Vision |
| Bausch + Lomb Corp. |
| EssilorLuxottica S.A. |
| Topcon Corp. |
| Nidek Co. Ltd. |
| Hoya Corp. |
| HAAG-Streit |
| Others |
Supply & Pricing Matrix
Per-procedure leasing contracts with utilization guarantees lock in supply access for Italian ophthalmic surgery centers while anchoring price visibility across multi-year equipment deployments. These arrangements tether capital expenditure cycles to patient throughput metrics, compressing pricing negotiation leverage for independent clinics in Veneto and Emilia-Romagna.
Pricing Analysis
Long-term offtake arrangements dominate premium phacoemulsification and femtosecond laser platforms, with pricing stratifying across premium, standard, and economy tiers based on automation level and after-sales service bundling. CE marking tier and regional health authority volume commitments drive price differentiation between Lombardy academic centers and southern labor-dependent facilities. Cost compression in standard-tier diagnostic equipment intensifies as EU MDR compliance costs flow through to mid-tier manufacturers. Public hospital procurement committees exhibit highest price sensitivity, while Milan's private refractive surgery chains absorb premium positioning for workflow automation.
Supply Chain Analysis
Strategic stockpiling of silicon photonics components characterizes OCT system manufacturing, offsetting just-in-time fragility in optical coherence tomography supply chains. German and Swiss precision optics houses anchor upstream supply for diagnostic platforms, while Asian wafer foundries in Taiwan and South Korea feed silicon photonics dependencies. Single-source vulnerability concentrates in femtosecond laser crystal sourcing from specialized German suppliers. Distribution runs through authorized service networks with regional spare parts depots in Milan and Bologna.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Italy's National Health Service regional procurement consolidation, compressing vendor negotiation leverage as hospital systems aggregate equipment contracts.
For Market Incumbents: Consolidate service network density in Lombardy and Veneto to defend against emerging platform competitors offering remote diagnostics integration. Lock in GPO contracts with extended-depth-of-focus lens portfolios before EU MDR renewal waves disrupt incumbent positioning. Prioritize backward integration into consumable manufacturing to capture per-procedure revenue streams.
For New Entrants and Emerging Players: Lead with telemedicine-linked diagnostic platforms targeting Sicily and Calabria ophthalmologist scarcity gaps. The southern underpenetration corridor offers lowest competitive density for AI-embedded fundus screening tools. Partner with regional health authorities on outcome-based reimbursement pilots to bypass capital purchase committee bottlenecks.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier diagnostic specialists with EU MDR transition readiness and software-enabled analytics capabilities. Long-term viability hinges on algorithm classification clarity under EU AI Act implementation timelines. Watch for notified body capacity expansion signals as inflection indicators for registration timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements reshape product registration timelines for Class III ophthalmic devices. |
| Hospital System Partnership | Full-service cataract workflow contracts consolidate vendor relationships around Alcon and Johnson & Johnson Vision platforms. |
| Software Companion Development | AI-embedded fundus screening tools face EU AI Act classification uncertainty affecting automated diagnostic algorithm deployment. |
| Reimbursement Strategy | Regional health authority pricing negotiations determine premium intraocular lens adoption speed across Italy's National Health Service. |
| Backward Integration | Captive supply of phacoemulsification consumables locks in per-procedure revenue streams for integrated platform vendors. |
Research Methodology
Desk research of EU MDR regulatory filings, Italian Ministry of Health procurement databases, and GPO contract disclosures preceded structured interviews with hospital purchasing committee chairs, biomedical engineers, ophthalmology department heads, and regional health authority technology assessment officers. Primary fieldwork combined with secondary validation against notified body certification records and academic medical center capital expenditure reports. Bottom-up equipment deployment tracking triangulated against top-down National Health Service reimbursement framework analysis.
Variance decomposition across product type, end user channel, technology platform, and application segments shaped analytical framework construction over the projection horizon. CAGRs derived from surgical volume elasticity modeling against demographic aging curves and refractive surgery substitution rates. Forecast inputs incorporated EU AI Act implementation trajectory uncertainty and silicon photonics supply chain concentration metrics.
Forecasts assume regulatory continuity in EU MDR and EU AI Act regimes; material policy shifts would require re-modeling certification timeline assumptions and algorithm classification thresholds. Revision becomes warranted when notified body capacity utilization crosses sustained backlog thresholds or when femtosecond laser platform adoption rates in southern regions diverge materially from northern benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Cough Assist Devices Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Global Hernia Repair Devices and Consumables Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Global Nasal Cannula Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Pipette Controllers Market
Medical Devices
Slit Lamps Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Orthodontic Retainers Market
Medical Devices
Transcutaneous Oximetry Systems Market