
 Artificial Eye Market | 2026-2036
Artificial Eye Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Eye Market Intelligence
A shift from purely cosmetic replacements toward functional vision restoration is reorganizing the core customer base from general clinics to specialized hospitals. Second Sight Medical Products, Inc. leads in the development of advanced retinal implants for severe vision impairment. Advanced Artificial Eyes specializes in custom-fit cosmetic prostheses for a global clientele. Ocular Prosthetics, Inc. leverages its network of clinics to serve regional patient needs across the United States.
An artificial eye, or ocular prosthesis, is a medical device designed to replace a natural eye following enucleation, evisceration, or orbital exenteration. These devices are typically crafted from medical-grade acrylics like PMMA and are custom-painted to match the patient's existing eye for cosmetic symmetry. While cosmetic enhancement applications using artificial lenses remain the largest segment by volume, retinal implants represent the fastest-growing technology category. Demand from hospitals and research institutions is concentrated in these higher-margin, technology-intensive implantable products.
Medical device regulations, such as those from the US FDA and the EU's MDR, govern the approval and marketing of implantable artificial eyes. In China, the NMPA sets stringent standards for biocompatible materials used in all ocular prosthetics, impacting market access. The key decision for manufacturers is whether to invest in high-cost bionic eye research or focus on scaling production of high-volume cosmetic prosthetics.
Market Dynamics
The market's central tension lies in the bifurcation between high-volume, aesthetically focused cosmetic prosthetics and capital-intensive, low-volume bionic eyes aimed at functional vision restoration. This divergence shapes investment strategies, supply chains, and regulatory engagement across the industry.
Growth Catalysts
- Biocompatible Material Innovation:Advances in medical-grade acrylics like PMMA enable the creation of more realistic and durable prostheses, improving patient satisfaction and reducing the need for frequent replacements.
- Research Institution Demand:A significant pull for advanced bionic eye models comes from universities and specialized research hospitals investigating neural interfaces and treatments for severe retinal diseases.
- Specialized Clinical Infrastructure:The high concentration of dedicated ocularist clinics and ophthalmology centers in the United States provides a robust distribution and service network for custom prosthetics.
Market Restraints
- High R&D Investment:The development of functional retinal implants requires substantial, high-risk capital investment in microelectronics, software, and clinical trials with no guarantee of commercial success.
- Stringent Regulatory Hurdles:Implantable devices face rigorous and lengthy approval processes from agencies like the US FDA and under the EU's MDR, delaying market entry and increasing costs.
- Limited Functional Restoration:Current bionic eye technologies provide a rudimentary form of vision, such as perceiving light and shapes, which can fall short of patient expectations for full sight recovery.
Strategic Opportunities
- Technology Convergence:Integrating machine learning algorithms with retinal implant processors offers a pathway to improve signal interpretation, potentially enhancing the quality of artificial vision for users.
- Pediatric Prosthetics Development:Designing prostheses specifically for children, addressing needs for frequent resizing and using materials suited for a developing orbital structure, represents an underserved market segment.
- Geographic Expansion:Establishing service networks for custom-fit cosmetic prosthetics in large, medically advancing markets like Brazil, which are regulated by bodies such as ANVISA, presents a clear growth vector.
Industry Challenges
- Ocularist Skill Scarcity:A persistent shortage of trained ocularists, who must possess a unique blend of technical precision and artistic skill for custom fitting and painting, limits service capacity.
- Reimbursement Inconsistency:Navigating disparate and often complex reimbursement policies from public and private insurers across different countries creates administrative burdens and uncertain revenue cycles.
- Material Compliance:Sourcing raw materials like PMMA that consistently meet the varying biocompatibility and purity standards of regulators like China's NMPA poses a significant supply chain challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Eye Market |
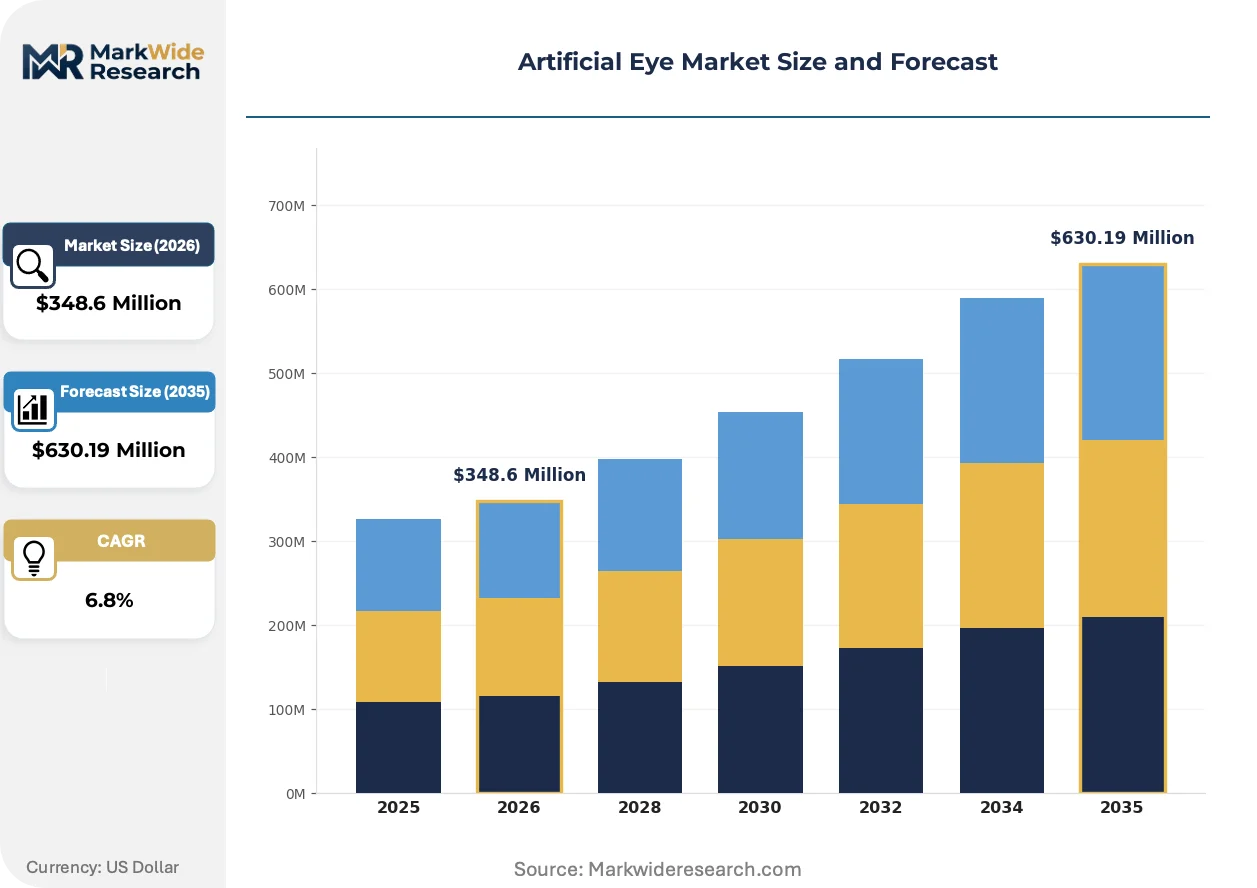
| Market Size in 2026 | $348.6 Million |
| Market Size in 2035 | $630.19 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corneal Implants, Retinal Implants, Bionic Eyes, Artificial Lenses End User: Hospitals, Eye Clinics, Rehabilitation Centers, Research Institutions Technology: Microelectronics, Biocompatible Materials, Optoelectronics, Sensor Technology Application: Vision Restoration, Cosmetic Enhancement, Clinical Trials, Research |
| Companies Covered | Second Sight Medical Products, Inc., International Prosthetic Eye Center, Advanced Artificial Eyes, Irises Unlimited, Studley Ocular Laboratories, F.AD. Müller Söhne GmbH & Co. KG, Ocular Prosthetics, Inc., Ferdinand A. Förster GmbH, Erickson Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Eye Market Strategic Shifts & Innovations
Technological evolution is pushing the boundaries of what an artificial eye can do, shifting focus from purely cosmetic applications toward functional restoration. This movement is prompting regulatory frameworks and clinical practices to adapt, creating distinct pathways for different product categories.
Bionic eye technology, particularly retinal implants, utilizes microelectrode arrays to electrically stimulate retinal ganglion cells, creating the perception of light and patterns for the user. Specialized hospitals and centers for severe vision impairment are the primary adopters, implementing these systems for patients with conditions like retinitis pigmentosa. This focus on functional restoration is decomposing the monolithic definition of an artificial eye into separate cosmetic and bionic categories.
The European Union's Medical Device Regulation (MDR) establishes a more stringent regulatory framework, emphasizing clinical evidence and post-market surveillance. This directive significantly increases the compliance burden for manufacturers, demanding more extensive data on biocompatibility and long-term device performance. The implantable bionic eye segment is most affected, compelling firms to increase investment in clinical trials to secure market access in Europe.
A patient-centric service model is gaining prominence over the traditional one-time product sale, especially for advanced functional implants. This change disrupts the standard clinic fitting by introducing long-term support contracts that cover software updates, device recalibration, and associated visual rehabilitation therapy. This integrated care approach is most evident in the United States and Germany, where specialized clinics bundle these services with the initial implant procedure.
Artificial Eye Market Segmentation
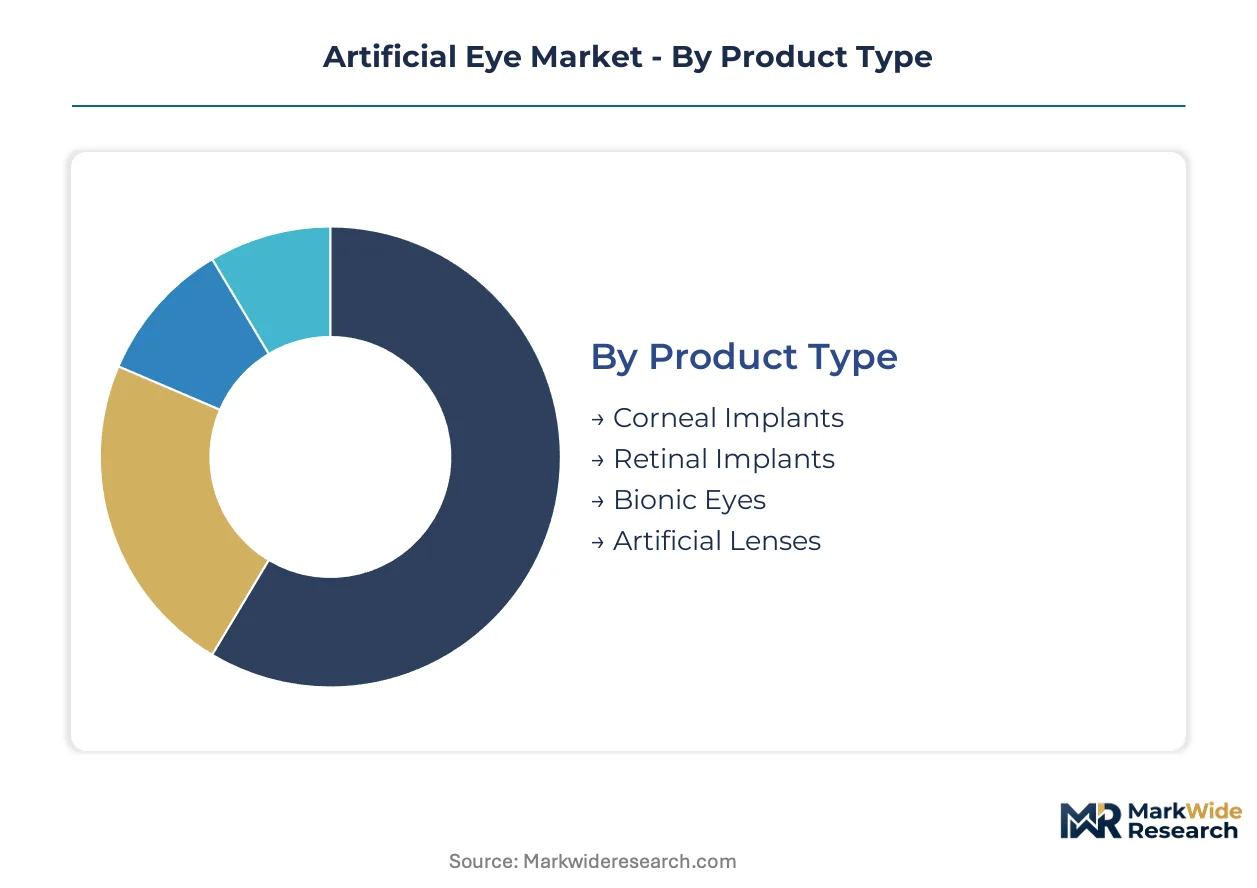
Understanding the distinct categories within the artificial eye market reveals where investment and innovation are concentrated. The market bifurcates into high-volume cosmetic products and technologically advanced, lower-volume functional implants, each serving different patient needs and clinical pathways.
Product Type:
The geographic spread of product adoption varies significantly, with some segments seeing domestic manufacturing advantages while others are export-led.
- Retinal Implants:These devices utilize microelectrode arrays to stimulate retinal ganglion cells, aiming to restore rudimentary vision for patients with severe retinal degeneration. Demand concentrates in specialized hospitals and research institutions in the United States and Germany, driven by ongoing clinical trials and advanced surgical capabilities.
- Artificial Lenses:Primarily used for cosmetic enhancement, these prosthetics are custom-painted from medical-grade acrylics to match existing eyes. Their widespread demand across all regions, including emerging markets like Brazil, makes them a significant export commodity for established manufacturers.
- Corneal Implants:These are medical devices designed to replace or repair damaged corneal tissue, often used to improve vision or address structural defects.
- Bionic Eyes:Advanced neuroprosthetic devices that aim to provide functional vision by interfacing directly with the visual cortex or optic nerve.
Artificial Lenses hold the largest share; momentum sits with Retinal Implants.
End User:
Each end-user segment demonstrates a distinct approach to procurement and patient care, influencing product development cycles.
- Hospitals:These institutions are primary adopters of advanced, implantable artificial eyes like retinal implants, driven by their capacity for complex surgical procedures and post-operative rehabilitation. Their procurement focuses on long-term support contracts and integrated care solutions.
- Research Institutions:Universities and specialized laboratories drive demand for bionic eye models, using them in studies on neural interfaces and severe vision impairment treatments. Their purchasing decisions prioritize technological sophistication and data collection capabilities.
- Eye Clinics:These facilities primarily cater to patients requiring custom-fit cosmetic prostheses, leveraging their network of ocularists for personalized services.
- Rehabilitation Centers:These centers focus on post-implant care, visual therapy, and patient adaptation to functional vision restoration devices.
Hospitals command the largest segment for high-value products, with Research Institutions showing the steepest expansion trajectory for experimental models.
Technology:
Investment in technology segments reflects the market's dual focus on enhancing existing products and pioneering new functional solutions.
- Biocompatible Materials:Advances in medical-grade acrylics like PMMA enable more realistic and durable prostheses, improving patient satisfaction and reducing replacement frequency. Manufacturers invest heavily in these materials to meet stringent regulatory standards from agencies like China's NMPA.
- Microelectronics:This segment is crucial for functional vision restoration, underpinning the design and performance of retinal implants and bionic eyes. Development is concentrated in areas requiring high precision and neural interface capabilities.
- Optoelectronics:This technology integrates optics and electronics, essential for capturing and processing visual information in advanced bionic systems.
- Sensor Technology:Critical for bionic eyes, these sensors detect light and convert it into electrical signals for neural stimulation, forming the basis of artificial vision.
Biocompatible Materials represent the foundational technology for most products, while Microelectronics is gaining share fastest due to bionic eye research.
Application:
The application landscape highlights the market's evolving priorities, from aesthetic solutions to advanced therapeutic interventions.
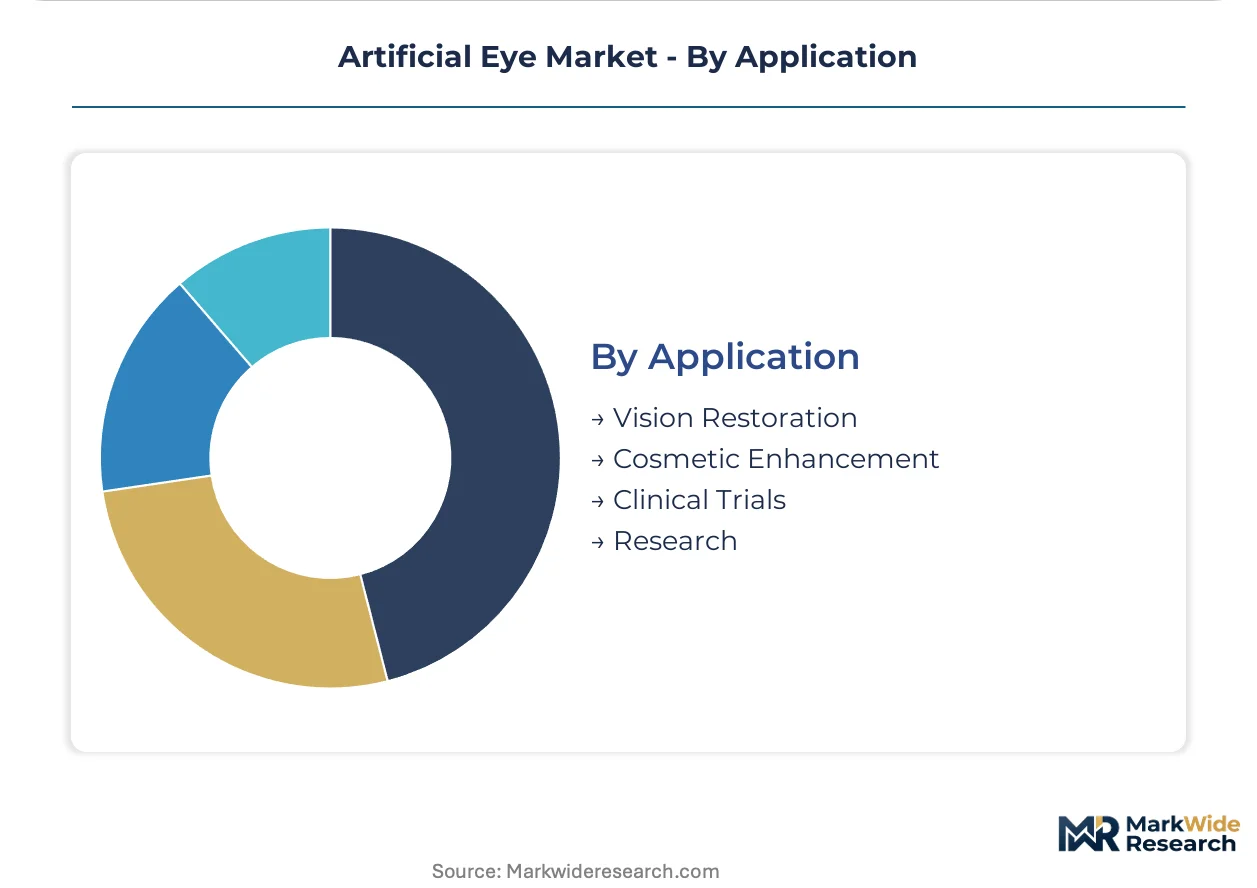
- Vision Restoration:This application focuses on functional improvement for patients with severe vision impairment, primarily through retinal implants and bionic eyes. It represents a high-margin segment with significant R&D investment, particularly in the United States and Europe.
- Cosmetic Enhancement:This segment involves providing custom-fit ocular prostheses to match the patient's existing eye, primarily for aesthetic purposes. It constitutes the largest volume segment, with demand spanning across general eye clinics globally.
- Clinical Trials:This application involves testing new artificial eye technologies and procedures in human subjects, crucial for regulatory approval from bodies like the US FDA and EU MDR.
- Research:This segment encompasses basic and applied scientific investigation into new materials, technologies, and interfaces for future artificial eye development.
Cosmetic Enhancement applications hold the majority volume, but Vision Restoration applications are climbing the fastest in terms of strategic importance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global artificial eye market's regional dynamics are underwritten by concentrations of advanced medical infrastructure and specialized research facilities. These localized strengths drive both the demand for high-volume cosmetic prosthetics and the development of cutting-edge functional vision restoration technologies. Regulatory frameworks in key countries significantly influence market access and product development pathways.
United States
The United States market is driven by a high concentration of specialized eye clinics and robust demand from research institutions for advanced bionic eye models. US FDA regulations govern the approval and marketing of implantable artificial eyes, ensuring device safety and efficacy. Advanced medical device manufacturing in states like California fosters innovation in neuroprosthetic development.
Germany
Germany exhibits strong demand for advanced, implantable artificial eyes, supported by its capacity for complex surgical procedures and post-operative rehabilitation. The EU's MDR establishes stringent regulatory frameworks for market entry, requiring extensive clinical evidence. Specialized clinics in cities like Berlin bundle long-term support contracts and visual rehabilitation therapy.
China
China's market is significantly influenced by its stringent NMPA standards for biocompatible materials used in ocular prosthetics, impacting market access. Growing medical advancements drive demand for both cosmetic and functional devices within the country. Manufacturing hubs in the Yangtze River Delta focus on sourcing raw materials that meet these rigorous purity requirements.
Brazil
Brazil presents a clear growth vector for establishing service networks for custom-fit cosmetic prosthetics in a large, medically advancing market. ANVISA, the national health surveillance agency, regulates the approval and sale of medical devices within the country. Major urban centers like São Paulo are seeing the expansion of specialized ocularist clinics to serve regional patient needs.
Artificial Eye Market Key Industry Players
Listed leaders compete with private specialists across the artificial eye market's dual focus on functional vision restoration and cosmetic enhancement. The market structure is tiered, with highly specialized firms focusing on bionic implants and others scaling production of high-volume cosmetic prosthetics. Strategic archetypes include technology innovators, custom-craftsmanship providers, and regional service network operators. Companies primarily engage in strategic partnerships for R&D and geographic expansion to secure market share.
Specialists in advanced functional restoration, such as Second Sight Medical Products, Inc., exemplify the technology innovator archetype focusing on bionic eye research. Custom-craftsmanship providers like Advanced Artificial Eyes occupy a position catering to global clientele with custom-fit cosmetic prostheses. Ocular Prosthetics, Inc. anchors the regional service network archetype, leveraging its US-based clinics to address specific patient needs for personalized ocular devices.
| Leading Market Players |
|---|
| Second Sight Medical Products, Inc. |
| International Prosthetic Eye Center |
| Advanced Artificial Eyes |
| Irises Unlimited |
| Studley Ocular Laboratories |
| F.AD. Müller Söhne GmbH & Co. KG |
| Ocular Prosthetics, Inc. |
| Ferdinand A. Förster GmbH |
| Erickson Laboratories |
| Others |
Cost & Logistics Intelligence
The six-month lead time for custom-painted ocular prosthetics from specialized labs underscores a supply chain concentrated in skilled craftsmanship, enabling premium pricing for personalized devices that meet specific patient needs.
Pricing Analysis
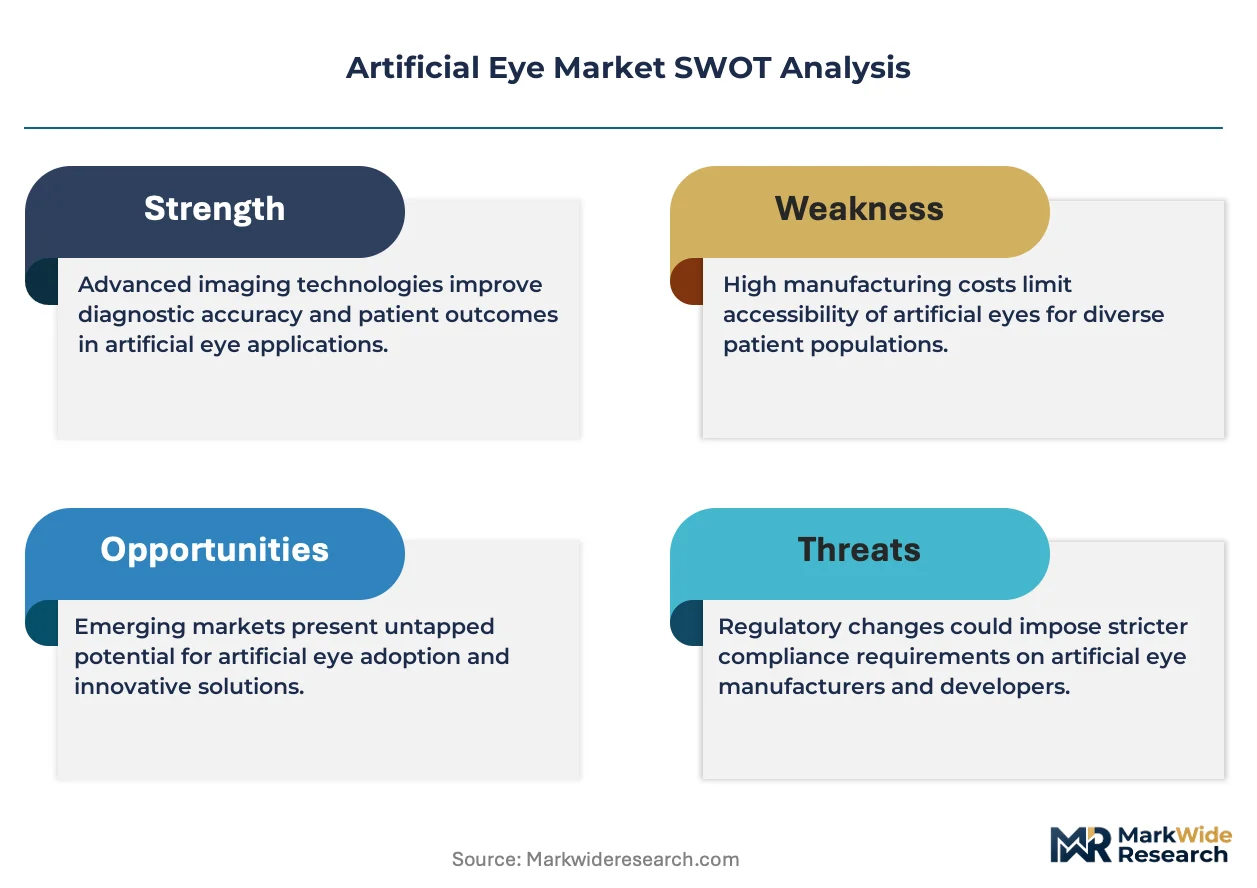
A tiered pricing structure across premium, mid-range, and economy levels characterizes the artificial eye market, reflecting varying degrees of customization and technological sophistication. Customization level, encompassing detailed iris painting and scleral tinting, drives significant price differentiation. Pricing pressure stems from the increasing availability of standardized cosmetic prosthetics, particularly in emerging markets. Patients seeking basic cosmetic enhancement are most price-sensitive, while research institutions procuring advanced bionic eye models prioritize technological capability over cost.
Supply Chain Analysis
The scarcity of highly trained ocularists globally represents a critical chokepoint in the supply chain for custom-fit ocular prosthetics, limiting service capacity. Raw material dependencies include medical-grade acrylics like PMMA sourced from Germany and specialized microelectronics from the United States for bionic implants. Material compliance with stringent standards, such as China's NMPA regulations, poses a structural risk across the supply chain. Distribution runs through specialized eye clinics for cosmetic devices and through hospitals for implantable bionic eyes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial eye market presents a defensive-moat story, primarily underpinned by significant regulatory entrenchment from bodies like the US FDA and EU MDR, which creates high barriers to entry for complex implantable devices.
For Market Incumbents: Compound existing leadership in retinal implant technology by securing additional clinical trial approvals under EU MDR, mitigating the threat from emerging bionic eye competitors. Invest in vertical integration into biocompatible material production to control quality and meet NMPA standards. Expand specialized ocularist training programs to address the capability scarcity in custom prosthetics.
For New Entrants and Emerging Players: Lead with specialized pediatric prosthetics, targeting the underserved segment of children requiring frequent resizing and biocompatible materials for developing orbital structures. Cosmetic enhancement in medically advancing markets like Brazil represents a highly penetrable segment. A direct-to-clinic sales approach for custom-fit prosthetics, emphasizing artistic precision, offers a viable go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger medical device conglomerates seeking to divest non-core cosmetic prosthesis divisions, offering opportunities for focused investment. The market demonstrates long-term viability over a 5-10 year window, driven by an aging global population and technological advancements. Accelerated FDA approvals for bionic eyes represent a specific signal to watch as an inflection indicator for functional vision restoration investments.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Ensures access to the European market for implantable devices under stringent EU MDR requirements. |
| Hospital System Partnership | Secures distribution channels and clinical adoption for advanced retinal implants within major healthcare networks. |
| Software Companion Development | Enhances the functionality and user experience of bionic eyes through improved signal processing algorithms. |
| Specialized Ocularist Training Programs | Addresses the critical skill scarcity in custom-fit prosthetics, improving service capacity and patient satisfaction. |
| Biocompatible Material R&D | Develops next-generation materials meeting rigorous NMPA standards for enhanced durability and patient comfort. |
Research Approach
The analysis maps artificial eye sub-sectors, including cosmetic prosthetics and bionic implants, each validated through extensive primary interviews with ocularists, R&D leads, and hospital procurement managers. Secondary validation involved reviewing US FDA filings, EU MDR guidelines, NMPA standards, and clinical trial registries. This approach employed both bottom-up and top-down triangulation to ensure data accuracy.
Forecast outputs were rigorously cross-referenced against external industry benchmarks and historical market performance across the analysis window. The analytical framework modeled segmentation dimensions by product type, end-user, technology, application, and regional regulatory cluster. Compound Annual Growth Rates were derived from a multi-factor regression analysis, incorporating biocompatible material advancements and bionic eye clinical trial success rates as key forecast inputs.
Forecasts assume regulatory continuity in US FDA and EU MDR regimes; material policy shifts would require re-modeling of market access and R&D investment trajectories. Unforeseen regulatory changes or significant R&D failures for bionic eyes represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as technological breakthroughs and healthcare policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
C-Arms Devices Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
Glass Syringe Market
Medical Devices
Vaginal Specula Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Neuromodulation Market