
 Contraceptive Rings Market | 2026-2036
Contraceptive Rings Market Size, Share, and Industry Trends Forecast 2026-2036
Contraceptive Rings Market Analytics
Ethylene vinyl acetate copolymer is broadening formulation flexibility for sustained-release hormone matrices in ring-based delivery. Bayer AG leverages captive polymer supply chains to protect margin structures across manufacturing stages. Pfizer Inc. sustains clinical trial infrastructure for next-generation progesterone-receptor modulators. Teva Pharmaceutical Industries Ltd. competes through abbreviated new drug application expertise in complex generics.
Contraceptive rings are flexible, toroidal polymer devices inserted intravaginally to release hormones—typically etonogestrel and ethinyl estradiol—over three weeks for fertility control. Hormonal rings dominate current volume, while biodegradable rings represent the fastest-growing segment as polymer degradation science eliminates retrieval requirements. Healthcare providers anchor end-user demand through prescription authority and insertion training, whereas community health centers occupy expanding access points for uninsured populations. Novel delivery systems concentrate margin pools where formulation patents and polymer processing know-how create technical barriers.
The FDA regulates contraceptive rings as combination drug-device products under 21 CFR requirements, while the EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations across EU member states. REACH compliance shapes silicone and polymer sourcing decisions for manufacturers supplying European markets. Stakeholders must monitor evolving bioequivalence standards and reimbursement parity between clinic-administered and self-administered methods.
Market Dynamics
Polymer degradation science is eliminating retrieval requirements for contraceptive rings, shifting clinical workflows from insertion-removal cycles toward single-administration biodegradable formats that reshape provider economics and patient compliance patterns.
Growth Catalysts
- Community health center expansion:Federally qualified health centers in the United States are embedding long-acting reversible contraceptive counseling into standard primary care workflows, creating new prescription volume at safety-net access points.
- FDA bioequivalence guidance:Updated recommendations for combination hormonal products streamline abbreviated new drug application pathways, compressing generic development timelines and expanding price-accessible supply.
- Ethylene vinyl acetate copolymer matrices:Advanced polymer processing enables tunable hormone release profiles across three-week and extended-duration formats, broadening formulation flexibility for sustained-release delivery.
Market Restraints
- Silicone feedstock concentration:Medical-grade silicone supply chains cluster among Asian polymer processors, exposing manufacturers to regional production disruptions and input cost volatility.
- Provider-administered reimbursement gaps:Clinic-based reimbursement for ring insertion remains stronger than pharmacy-dispensed alternatives, constraining self-administration channel expansion.
- Biodegradable polymer validation timelines:Extended degradation-rate verification studies delay regulatory submissions for retrieval-free formats, compressing near-term revenue realization.
Strategic Opportunities
- Uninsured population access points:Title X clinic networks in the United States serve contraceptive deserts where ring-based methods face minimal substitution from long-acting reversible alternatives.
- EMA centralized marketing authorizations:Single regulatory approval across EU member states reduces country-by-country registration burden, accelerating European market penetration.
- Telehealth prescription models:Remote consultation platforms are expanding ring access beyond traditional clinic geography, particularly for patients in rural or mobility-limited circumstances.
Industry Challenges
- Polymer processing talent scarcity:Specialized expertise in medical-grade extrusion and controlled-release matrix design concentrates among a limited pool of formulation scientists, constraining manufacturing scale-up.
- REACH compliance documentation:European chemical registration requirements for silicone and ethylene vinyl acetate sourcing impose extensive substance characterization obligations that extend procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contraceptive Rings Market |
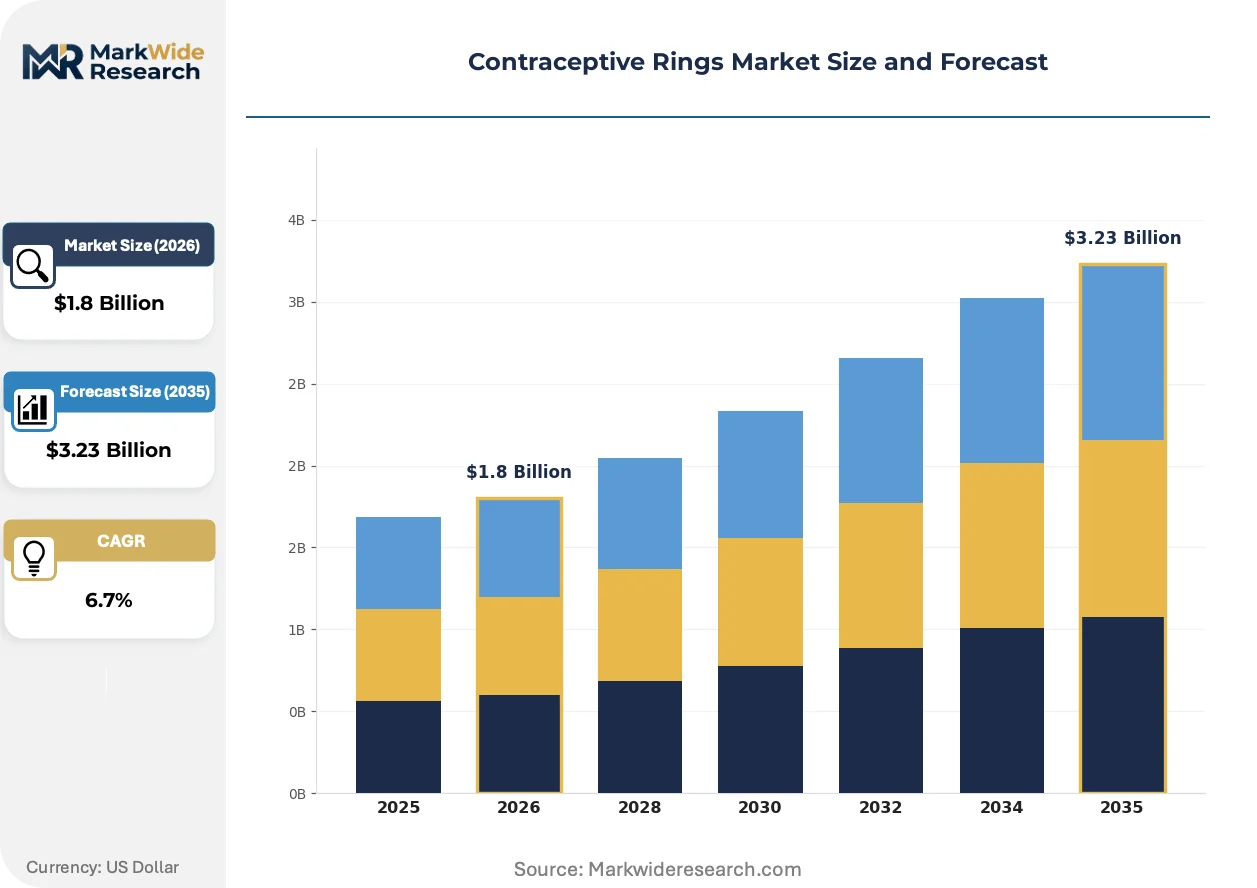
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Rings, Non-Hormonal Rings, Biodegradable Rings, Novel Delivery Systems End User: Healthcare Providers, Women of Reproductive Age, Clinics, Community Health Centers Delivery Mode: Intravaginal, Transdermal, Injectable, Oral Therapy Area: Fertility Control, Family Planning, Hormonal Regulation, Reproductive Health |
| Companies Covered | Bayer AG, AbbVie Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Janssen Pharmaceuticals Inc., Allergan, TherapeuticsMD Inc., Agile Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contraceptive Rings Market Evolving Landscape
Active pharmaceutical ingredient-polymer conjugation techniques are rewriting formulation economics, while regulatory convergence around bioequivalence standards and shifting patient preference toward discreet self-administration reshape competitive positioning across delivery formats.
Biodegradable lactide-glycolide copolymer rings are rewriting the clinical workflow for fertility control by eliminating retrieval appointments entirely. Community health centers in contraceptive deserts are piloting these formats for patients with limited healthcare access. The technology is compressing total cost-of-care calculations by removing follow-up infrastructure from provider reimbursement models.
REACH substance registration deadlines are tightening polymer sourcing requirements for manufacturers supplying European markets. ECHA compliance documentation now extends to catalyst residues and monomer trace levels in medical-grade silicones. German and French distributors are consolidating supplier qualification criteria, favoring manufacturers with captive polymer processing capabilities.
Patient preference for pharmacy-dispensed over clinic-administered methods is accelerating channel disintermediation in the United States. Retail pharmacy chains are expanding hormonal ring stocking and pharmacist consultation services. This shift concentrates in states with expanded Medicaid coverage for self-administered contraception, where appointment barriers historically suppressed ring uptake.
Contraceptive Rings Market Segmentation
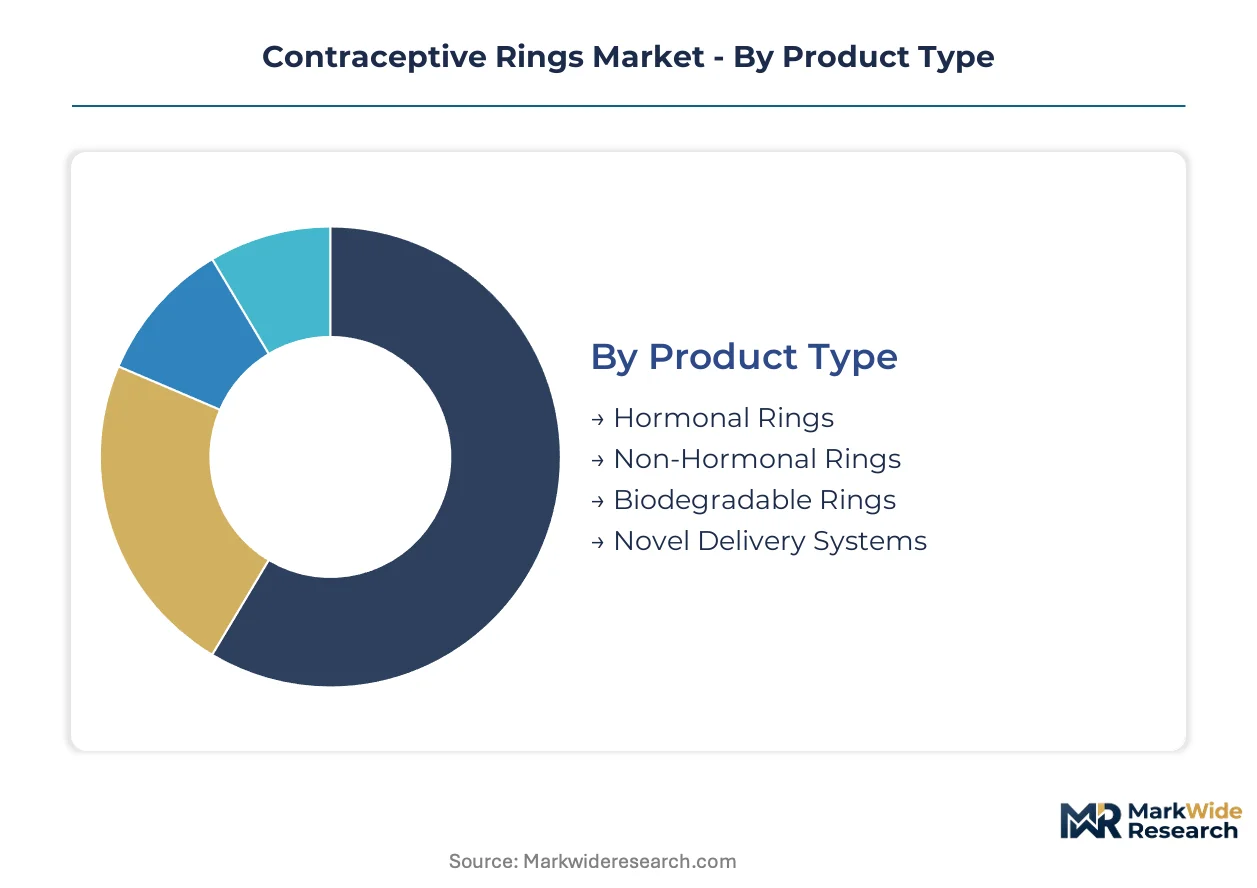
Contraceptive ring manufacturers design formulations around distinct patient compliance profiles and clinical access constraints. Segment boundaries shift as biodegradable polymers and telehealth distribution reshape which end-users control procurement decisions.
Product Type:
Patient retrieval tolerance and prescription renewal frequency drive product selection across hormonal and non-hormonal alternatives.
- Hormonal Rings:Ethylene vinyl acetate copolymer matrices release etonogestrel and ethinyl estradiol across 21-day cycles. Demand concentrates in the United States where clinic-based reimbursement for provider-administered methods remains strongest.
- Biodegradable Rings:Lactide-glycolide copolymer formulations eliminate retrieval appointments through controlled polymer degradation. Community health centers in contraceptive deserts pilot these formats for patients with limited healthcare access, compressing total cost-of-care by removing follow-up infrastructure.
- Non-Hormonal Rings:Copper-ion releasing or purely barrier-based mechanisms serve patients with estrogen contraindications.
- Novel Delivery Systems:API-polymer conjugation techniques and extended-duration formats target formulation patent windows.
Hormonal rings lead on scale; biodegradable rings lead on momentum.
End User:
Prescription authority and reimbursement channel structure determine which intermediaries capture patient contact.
- Healthcare Providers:Gynecologists and primary care physicians anchor volume through insertion training requirements and counseling workflows. Federally qualified health centers in the United States embed long-acting reversible contraceptive counseling into standard care, creating new prescription volume at safety-net access points.
- Community Health Centers:Title X clinic networks serve contraceptive deserts where ring-based methods face minimal substitution from long-acting reversible alternatives. Remote consultation platforms expand access beyond traditional clinic geography for rural or mobility-limited patients.
- Women of Reproductive Age:Direct-to-patient telehealth models and pharmacy-dispensed channels concentrate in states with expanded Medicaid coverage for self-administered contraception.
- Clinics:Private practice and hospital outpatient settings maintain stronger reimbursement for provider-administered insertion.
Healthcare providers lead on scale; community health centers lead on momentum.
Delivery Mode:
Administration site and patient handling complexity create divergent regulatory pathways and compliance profiles.
- Intravaginal:Flexible toroidal polymer devices releasing hormones over three weeks dominate current volume. FDA regulates these as combination drug-device products under 21 CFR requirements.
- Transdermal:Patch-based alternatives compete on discretion and self-administration convenience.
- Injectable:Depot formulations serve patients preferring quarterly rather than monthly or three-weekly renewal cycles.
- Oral:Daily pill regimens remain the substitution benchmark for ring-based methods in cost-sensitive segments.
Intravaginal delivery leads on scale; transdermal formats lead on momentum.
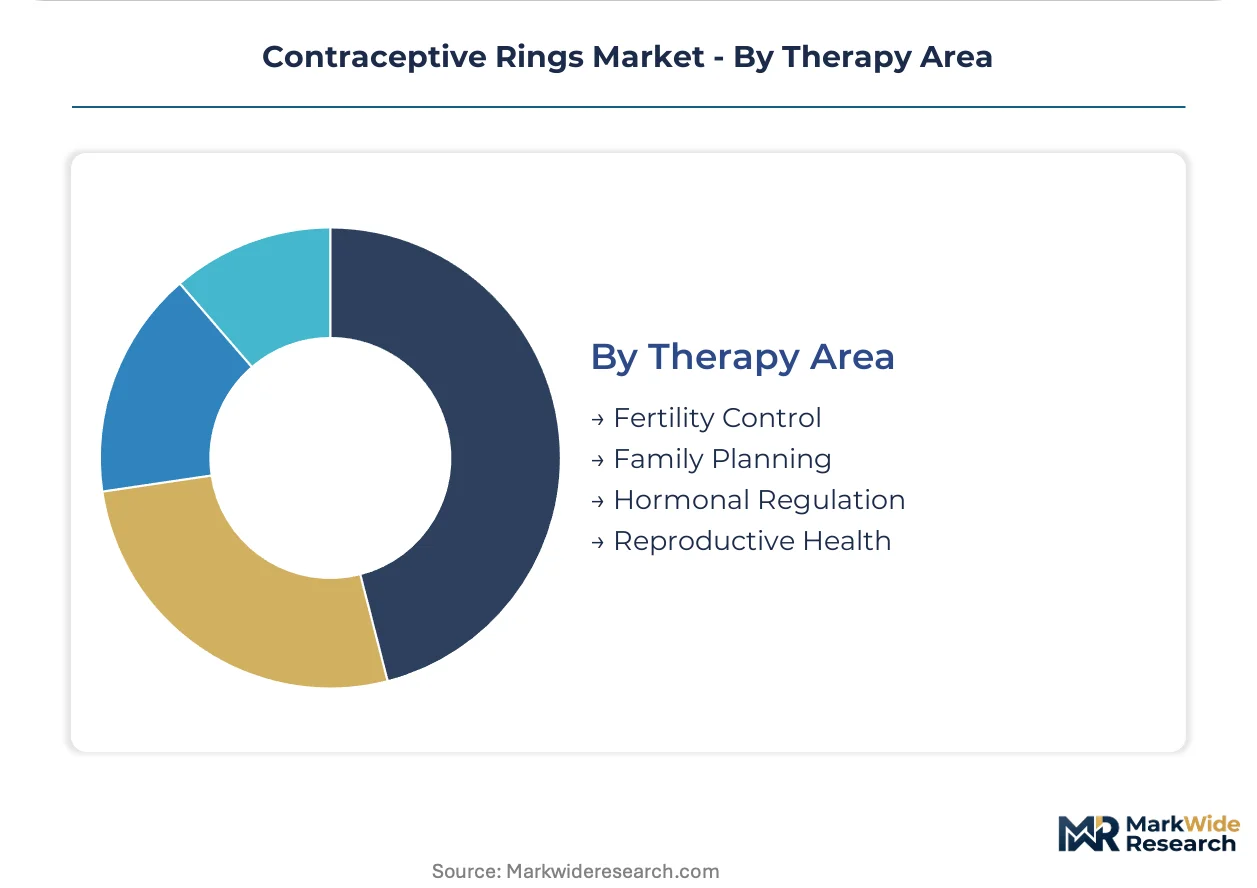
Therapy Area:
Clinical indication breadth shapes reimbursement coding and formulary placement across fertility and non-fertility applications.
- Fertility Control:Primary indication driving prescription volume through contraceptive efficacy claims. EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations for these indications across EU member states.
- Hormonal Regulation:Secondary indications for cycle management and menstrual symptom control expand addressable patient populations. REACH compliance shapes silicone and polymer sourcing decisions for manufacturers supplying European markets.
- Family Planning:Public health program procurement concentrates in government-subsidized channels.
- Reproductive Health:Broad category capturing polycystic ovary syndrome management and other gynecological applications.
Fertility control leads on scale; hormonal regulation leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park pharmaceutical cluster in North Carolina anchors North American contraceptive ring development, with polymer processing expertise and clinical trial infrastructure concentrating in this corridor.
United States
Title X clinic networks and federally qualified health centers drive prescription volume for ring-based methods in contraceptive deserts across the rural South and Midwest. FDA bioequivalence guidance for combination hormonal products streamlines abbreviated new drug application pathways for generic entrants. The Research Triangle Park corridor in North Carolina hosts polymer formulation and clinical research operations serving domestic manufacturing.
Germany
REACH substance registration deadlines tighten polymer sourcing requirements for medical-grade silicone and ethylene vinyl acetate copolymers entering European markets. ECHA compliance documentation now extends to catalyst residues in polymer feedstocks. The Rhine-Ruhr industrial region concentrates polymer processing capabilities and pharmaceutical distribution infrastructure serving EU member states.
France
ANSM oversight of combination drug-device products shapes marketing authorization pathways for ring-based contraceptives distributed through French pharmacy networks. The Paris-Saclay research cluster advances biodegradable polymer degradation science for retrieval-free ring formats. Lyon and the Auvergne-Rhône-Alpes region host medical device manufacturing operations supplying European distribution channels.
United Kingdom
MHRA post-Brexit regulatory autonomy creates divergent conformity assessment routes for ring-based products entering British versus EU markets. The Cambridge-London life sciences corridor maintains clinical trial infrastructure for hormone-receptor modulator development. Manchester and the Northern Powerhouse initiative concentrate polymer research partnerships between universities and medical device manufacturers.
India
CDSCO marketing authorization requirements for combination drug-device products shape domestic manufacturing and export strategies for polymer-based delivery systems. The PLI scheme for pharmaceuticals incentivizes active pharmaceutical ingredient and medical device component production. Hyderabad and the Telangana life sciences cluster concentrate formulation development capabilities serving emerging market distribution.
Contraceptive Rings Market Competitive Landscape
Global majors compete with regional champions across polymer supply chain control and regulatory submission expertise, producing a tiered structure where captive manufacturing capabilities separate premium-positioned players from generic competitors. Three archetypes dominate: vertically integrated pharmaceutical conglomerates with captive polymer operations, specialized generic manufacturers leveraging abbreviated new drug application expertise, and emerging biotechnology firms pursuing biodegradable formulation patents. Competitive moves concentrate on backward integration into medical-grade silicone sourcing and strategic partnerships with community health center networks.
Within the integrated pharmaceutical tier, Bayer AG exemplifies the conglomerate archetype through its polymer supply chain control, while Pfizer Inc. occupies a position anchored in clinical trial infrastructure for hormone-receptor modulators. Teva Pharmaceutical Industries Ltd. represents the generic specialist archetype, with its expertise in complex abbreviated new drug applications positioning it for FDA bioequivalence pathway execution.
| Leading Market Players |
|---|
| Bayer AG |
| AbbVie Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Janssen Pharmaceuticals Inc. |
| Allergan |
| TherapeuticsMD Inc. |
| Agile Therapeutics |
| Others |
Value Network & Pricing Analysis
Specialized polymer extrusion engineers concentrate in the Research Triangle Park corridor, where labor-cost premiums of 40-60% above Asian manufacturing hubs sustain pricing spreads between FDA-validated premium tiers and economy-grade alternatives sourced from emerging production centers.
Pricing Analysis
Medical-grade silicone and ethylene vinyl acetate copolymer feedstock costs pass through directly to finished ring pricing, with ethylene vinyl acetate price volatility compressing margins for non-integrated manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated originators from CE-marked European entrants and unbranded generic alternatives. Pricing pressure stems from abbreviated new drug application pathways accelerating generic entry timelines. Community health centers and Title X clinics exhibit highest price sensitivity, while hospital outpatient settings absorb premium markups for provider-administered insertion services.
Supply Chain Analysis
Ocean freight and cold-chain logistics costs for temperature-sensitive polymer feedstocks add 12-18% to landed input costs for European and North American manufacturers sourcing from Asian processors. Medical-grade silicone supply concentrates in China, South Korea, and Japan, while ethylene vinyl acetate copolymer production clusters in Germany, the United States, and Singapore. Manufacturers draw from single-source dependencies for catalyst-grade silicone precursors, exposing formulations to regional production disruptions. Distribution runs through pharmaceutical wholesalers and direct hospital system contracts, with retail pharmacy chains expanding self-administered channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contraceptive ring production economics favor geographic arbitrage between REACH-compliant European polymer processing and FDA-validated U.S. manufacturing, with regulatory compliance cost differentials of 15-25% creating margin expansion opportunities for dual-registered facilities.
For Market Incumbents: Cement backward integration into medical-grade silicone sourcing to insulate margin structures from Asian feedstock volatility. Expand captive polymer extrusion capacity in the Research Triangle Park corridor to protect formulation expertise from specialized talent scarcity. Prioritize biodegradable ring pipeline advancement before patent cliffs on etonogestrel-ethinyl estradiol formulations erode premium positioning.
For New Entrants and Emerging Players: Capture telehealth-enabled prescription flows in Medicaid-expansion states where self-administered reimbursement parity is displacing clinic-dependent incumbents. Target community health center procurement contracts in contraceptive deserts across the rural South and Midwest, where Title X funding insulates volume from long-acting reversible substitution. Lead with pharmacist consultation partnerships rather than direct-to-patient marketing to navigate FDA combination drug-device promotional restrictions.
For Investors and Strategic Acquirers: Vertically integrated pharmaceutical conglomerates with captive polymer operations are the most active acquirer in this space, seeking biodegradable formulation patents and FDA bioequivalence submission expertise. The acquisition target archetype combines polymer processing capabilities with abbreviated new drug application track records. Watch for EMA centralized marketing authorization approvals as inflection indicators for European market penetration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Pipeline Advancement | Eliminates retrieval appointments, compressing total cost-of-care for Title X clinic networks. |
| FDA Abbreviated New Drug Application Execution | Accelerates generic entry timelines, expanding price-accessible supply through pharmacy channels. |
| REACH-Compliant Silicone Sourcing Integration | Secures European market access as ECHA tightens catalyst residue documentation requirements. |
| Telehealth Prescription Platform Partnership | Expands ring access beyond clinic geography for rural and mobility-limited patient populations. |
| Community Health Center Network Contracting | Captures volume in contraceptive deserts with minimal substitution from long-acting alternatives. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with regulatory affairs leads, polymer formulation scientists, community health center procurement directors, and pharmaceutical distribution channel managers. Secondary validation draws from FDA 510(k) filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov hormone-receptor modulator protocols, and REACH substance registration databases. Bottom-up prescription volume modeling triangulates against top-down manufacturer revenue estimates across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics across hormonal, biodegradable, and non-hormonal product segments, with administration route and reimbursement channel as cross-cutting dimensions. CAGRs derive from segmented demand elasticity modeling and polymer feedstock cost trajectory assumptions. Forecast inputs include Title X funding appropriations, Medicaid expansion state policy tracking, and EMA marketing authorization approval velocity.
Regulatory guidance revisions, polymer feedstock supply disruptions, and reimbursement parity legislation are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Venturi Mask Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Knee Braces Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
Electric Handpiece Market
Medical Devices
South Korea ECG Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Global Hi-Tech Medical Devices Market
Medical Devices
Specimen Retrieval Nets Market