
 Global Vascular Embolization Devices Market | 2026-2036
Global Vascular Embolization Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vascular Embolization Devices Market Foresight
The vascular embolization devices market is decoupling into premium bioresorbable and commodity permanent implant tiers. Medtronic leverages its neurovascular portfolio to dominate the cerebral aneurysm segment with flow-diverting and coiling platforms. Boston Scientific Corporation anchors its position through interventional oncology applications, while Stryker Corporation differentiates via hemorrhagic stroke and arteriovenous malformation portfolios.
Vascular embolization devices are implantable or injectable agents designed to occlude blood vessels through mechanical blockage, chemical sclerosis, or flow redirection, typically delivered via catheter-based systems with fluoroscopic guidance. These devices employ platinum-tungsten alloys, nitinol, or calibrated microspheres ranging from 40 to 1200 microns to achieve targeted hemostasis, devascularization, or aneurysm isolation in interventional radiology and neurosurgery. Coil and liquid embolic platforms command the largest revenue pools due to established reimbursement and repeat intervention requirements in cerebral aneurysm management. Microsphere and particle segments are gaining structural momentum in tumor embolization and uterine fibroid therapy as outpatient migration accelerates.
The FDA's 510(k) and PMA pathways govern permanent implantable embolization devices, while the EU MDR and CE marking requirements are elevating clinical evidence standards for liquid embolics and flow modulators. Japan's PMDA maintains distinct pharmacovigilance reporting for neurovascular implants, creating asynchronous market access timelines across major jurisdictions. Stakeholders must monitor evolving health technology assessment criteria in Germany and France, where comparative effectiveness data increasingly determines hospital procurement decisions for embolization platforms.
Market Dynamics
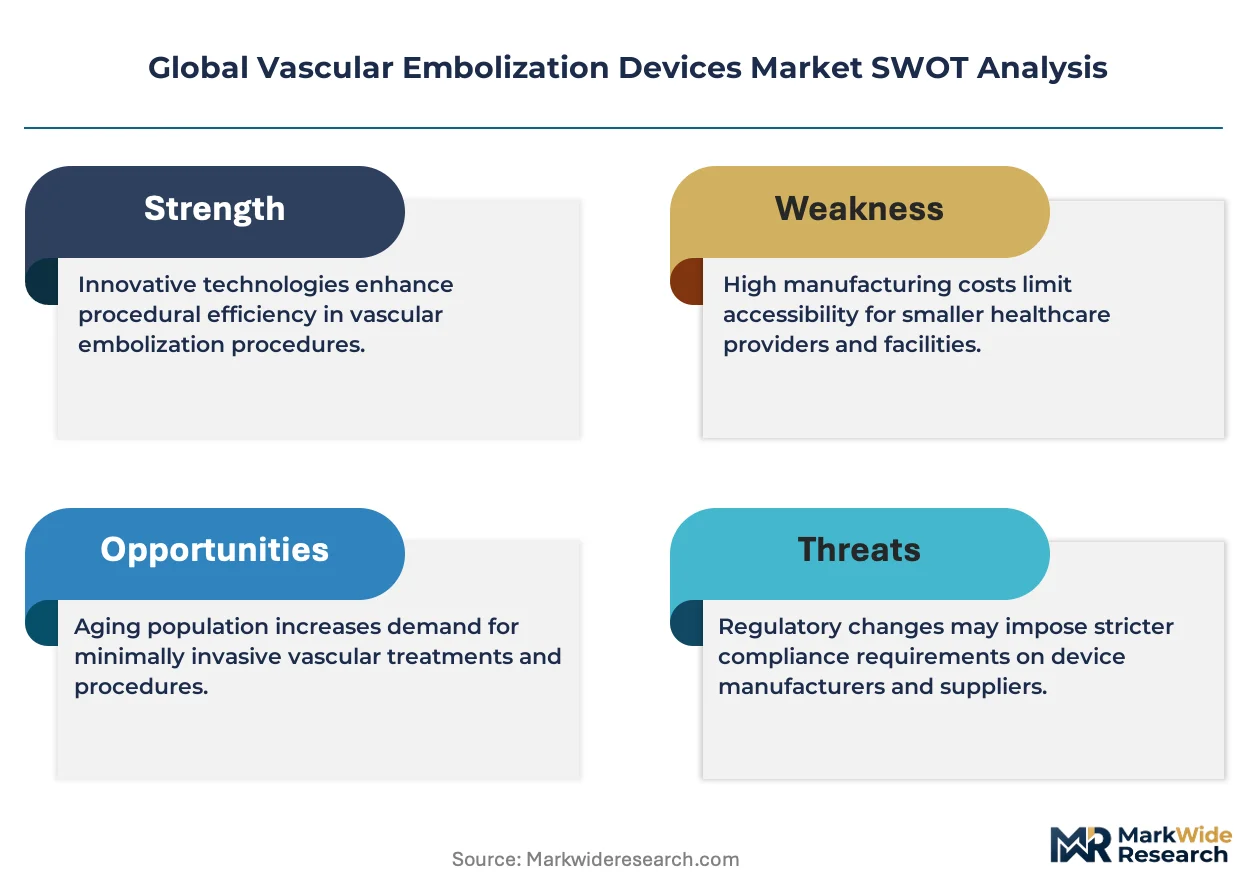
The vascular embolization devices market is bifurcating around bioresorbable versus permanent implant architectures, with FDA's intensified PMA scrutiny for neurovascular permanents compressing development timelines and capital allocation.
Growth Catalysts
- Outpatient Migration:Ambulatory surgical centers in the United States are expanding interventional radiology suites for uterine fibroid and tumor embolization, reducing hospital bed utilization.
- REACH Compliance:The EU's chemical safety framework is accelerating substitution of solvent-based liquid embolics with aqueous alternatives in European clinical practice.
- Platinum-Tungsten Alloys:Enhanced radiopacity in next-generation detachable coils is improving fluoroscopic visualization precision during cerebral aneurysm procedures.
Market Restraints
- Supply Concentration:Nitinol wire and platinum feedstock sourcing concentrates among a limited supplier base in Germany and Japan, creating input vulnerability.
- Technical Limitation:Liquid embolic penetration in high-flow arteriovenous malformations remains constrained by polymerization control challenges.
- Regulatory Friction:Japan's PMDA pharmacovigilance reporting requirements for neurovascular implants extend market access timelines by 18-24 months versus FDA pathways.
Strategic Opportunities
- Pediatric Application Gap:Congenital vascular malformation therapy in children represents an underpenetrated indication with limited device-specific labeling.
- India's PLI Scheme:Domestic manufacturing incentives for medical devices are attracting catheter production investment to serve South Asian demand.
- AI-Fluoroscopy Convergence:Real-time image guidance algorithms integrated with embolization delivery systems are reducing radiation exposure and procedure time.
Industry Challenges
- Interventional Radiology Training Bottleneck:Fellowship program capacity constraints in the United States and Germany are limiting operator pipeline expansion.
- MDR Clinical Evidence Burden:EU medical device regulation retrospective data requirements are forcing portfolio rationalization among mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vascular Embolization Devices Market |
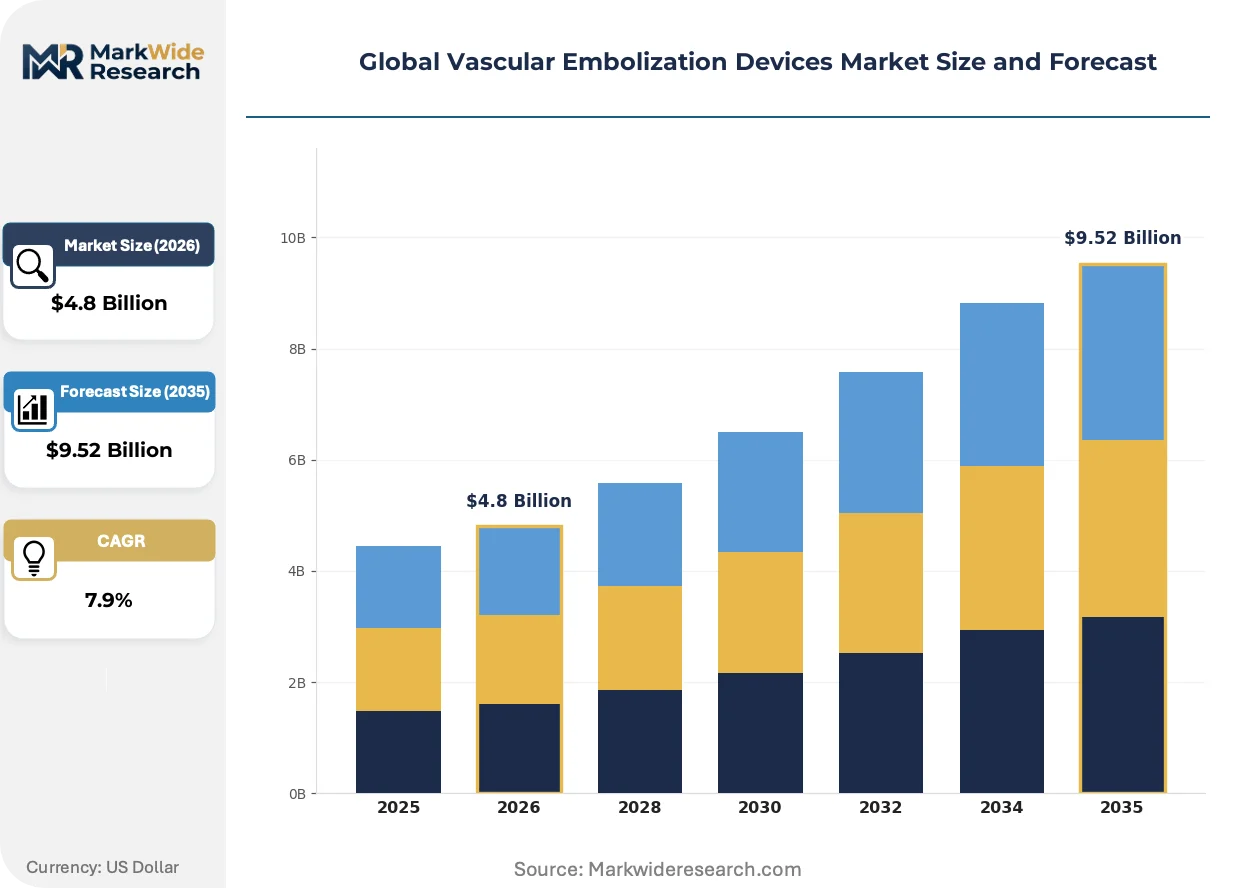
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coils, Particles, Liquid Embolics, Plug Devices, Balloons Technology: Mechanical Embolization, Fluid Embolization, Microspheres, Gelfoam, Polyvinyl Alcohol Application: Cerebral Aneurysm, Arteriovenous Malformations, Gastrointestinal Bleeding, Uterine Fibroids, Tumor Treatment End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes, Diagnostic Centers |
| Companies Covered | Medtronic, Boston Scientific Corporation, Stryker Corporation, Cook Medical, Terumo Corporation, Abbott Laboratories, Johnson & Johnson, Penumbra Inc., Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vascular Embolization Devices Market Shifts & Advancements
Device-level innovation is converging with digital integration and care setting migration, reshaping how embolization platforms are developed, regulated, and procured across tertiary and ambulatory environments.
Bioresorbable microsphere platforms are overtaking permanent synthetic particles in interventional oncology applications. Academic medical centers in Germany and Japan are piloting gelatin-based carriers for transarterial chemoembolization. The shift is compressing repeat intervention revenue pools while reducing long-term implant liability exposure.
The EU MDR's elevated clinical evidence standards for Class III implantable devices are extending PMA-equivalent timelines for liquid embolics and flow diverters. Manufacturers are consolidating European notified body relationships and prioritizing high-volume indications over niche orphan applications. France's ANSM is scrutinizing retrospective safety databases more aggressively than pre-MDR frameworks required.
Hospital procurement committees are unbundling device purchasing from procedure reimbursement, forcing price transparency in coil and microsphere contracting. Integrated delivery networks in the United States are consolidating vendor agreements across multiple hospital systems. The shift is most visible in Texas and California, where health system consolidation has concentrated purchasing leverage among three to four dominant networks.
Global Vascular Embolization Devices Market Segmentation
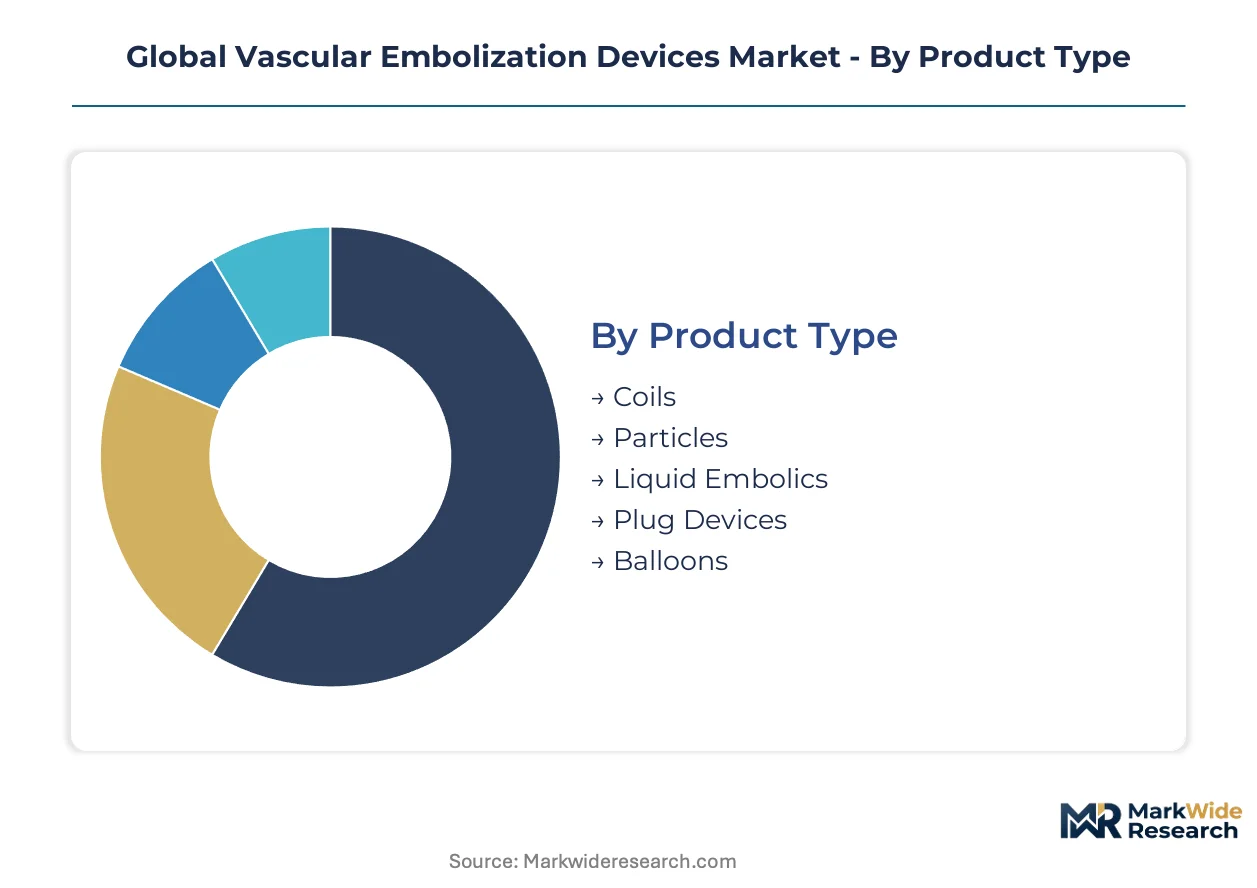
Segmentation in vascular embolization devices reveals how clinical utility, reimbursement economics, and procedural setting interact to determine commercial priority. Device selection varies sharply between high-acuity neurovascular interventions and outpatient tumor embolization workflows.
Product Type:
Volume concentration favors established mechanical platforms, while premium growth concentrates in next-generation liquid and flow-modulating architectures.
- Coils:Platinum-tungsten alloy constructs deliver mechanical occlusion through detachable or pushable configurations. Demand clusters in tertiary neurosurgical centers across the United States and Germany where cerebral aneurysm coiling maintains established reimbursement codes and repeat intervention protocols.
- Liquid Embolics:Precipitating or polymerizing agents including ethylene vinyl alcohol copolymers and n-butyl cyanoacrylate achieve conformal filling of complex vascular geometries. Penetration accelerates in arteriovenous malformation therapy at academic medical centers in Japan, constrained by polymerization control requirements in high-flow lesions.
- Particles:Calibrated microspheres and polyvinyl alcohol fragments enable distal embolization in hypervascular tumors and uterine fibroids.
- Plug Devices:Nitinol-based occluders deploy through large-bore catheters for proximal vessel sacrifice.
- Balloons:Temporary flow arrest adjuncts support liquid embolic delivery and hemorrhage control.
Mature deployment sits with Coils. Newer deployment is concentrated in Liquid Embolics.
Technology:
Technology segmentation tracks the shift from permanent synthetic implants toward bioresorbable and chemically modulated alternatives.
- Mechanical Embolization:Coil and plug platforms using platinum, nitinol, or stainless steel deliver immediate flow cessation through physical obstruction. Volume concentrates in cerebral aneurysm and trauma applications at hospital-based interventional radiology departments in the United States.
- Microspheres:Calibrated spherical embolics ranging from 40 to 1200 microns enable targeted devascularization with predictable distal penetration. Adoption climbs fastest in transarterial chemoembolization for hepatocellular carcinoma at German and Japanese oncology centers.
- Fluid Embolization:Liquid and semi-liquid agents achieve conformal casting of irregular vascular beds.
- Gelfoam:Absorbable gelatin sponge provides temporary embolization for preoperative devascularization.
- Polyvinyl Alcohol:Irregular synthetic particles serve cost-sensitive tumor embolization indications.
Established volume resides with Mechanical Embolization. Steepest expansion trajectory belongs to Microspheres.
Application:
Application segmentation reflects how disease prevalence, procedural reimbursement, and operator training availability concentrate commercial opportunity.
- Cerebral Aneurysm:Endovascular coiling and flow diversion dominate intracranial aneurysm management with established clinical evidence and dedicated CPT reimbursement in the United States. Procedure volume concentrates at comprehensive stroke centers with neurovascular fellowship programs.
- Tumor Treatment:Transarterial chemoembolization and radioembolization target hepatocellular carcinoma, renal cell carcinoma, and metastatic lesions. Migration toward ambulatory surgical centers in Texas and California accelerates as outpatient reimbursement frameworks mature.
- Arteriovenous Malformations:Congenital and acquired high-flow lesions require multimodal embolization combining liquid agents and coils.
- Uterine Fibroids:Uterine artery embolization offers fertility-preserving alternative to hysterectomy with expanding ASC penetration.
- Gastrointestinal Bleeding:Emergency embolization for upper and lower GI hemorrhage serves inpatient interventional radiology call panels.
Revenue concentration anchors in Cerebral Aneurysm. Volume expansion is shifting fastest into Tumor Treatment.
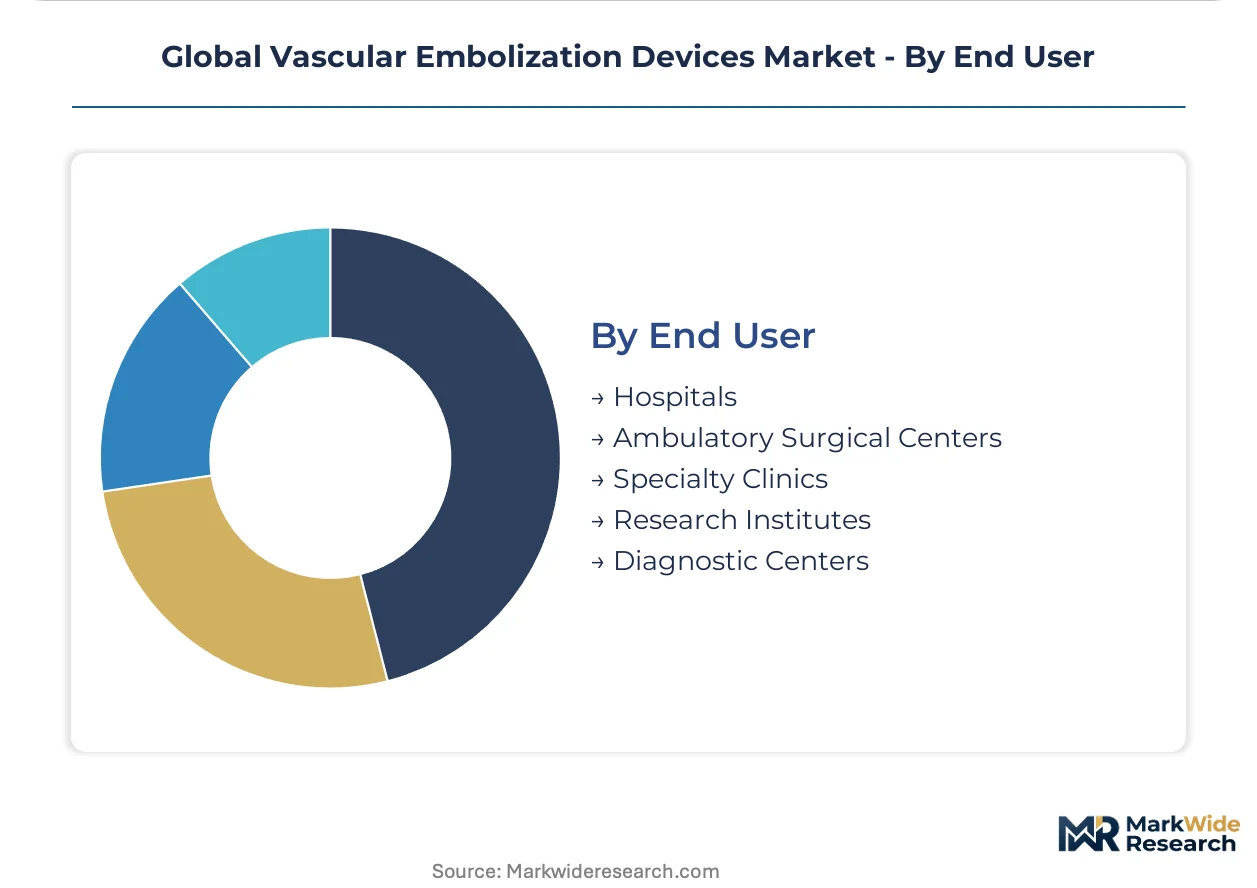
End User:
End user segmentation captures the structural migration of embolization procedures from inpatient to ambulatory settings.
- Hospitals:Tertiary academic centers and community hospitals maintain dominance for emergency hemorrhage control, complex neurovascular interventions, and multi-specialty tumor boards. Infrastructure requirements for biplane fluoroscopy and neuroanesthesia support concentrate this volume.
- Ambulatory Surgical Centers:Freestanding interventional radiology suites in the United States are capturing elective uterine fibroid embolization and select tumor therapies as reimbursement parity with hospital outpatient departments advances.
- Specialty Clinics:Dedicated interventional radiology practices handle routine oncology embolization.
- Research Institutes:Academic medical centers pilot novel bioresorbable platforms and device-drug combinations.
- Diagnostic Centers:Imaging facilities with catheterization capabilities perform limited diagnostic angiography with therapeutic extension.
Procedure volume concentrates in Hospitals. Capital deployment is shifting most aggressively toward Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American neurovascular device development, housing Medtronic's global headquarters and adjacent interventional radiology training consortiums. Tertiary hospitals across the United States, Germany, and Japan concentrate embolization procedure volume and reimbursement authority.
United States
Comprehensive stroke centers in Texas and California drive cerebral aneurysm coiling volume through established CPT reimbursement codes. The FDA's PMA pathway for permanent neurovascular implants compresses development timelines for domestic manufacturers. Minneapolis and Irvine host the dominant corporate R&D clusters for flow-diverting platforms.
Germany
Academic medical centers in Munich and Heidelberg pilot bioresorbable microsphere platforms for transarterial chemoembolization. The EU MDR elevates clinical evidence requirements for Class III implantable devices, extending notified body review cycles. The Baden-Württemberg medical technology corridor concentrates catheter manufacturing and fluoroscopy system integration.
Japan
PMDA pharmacovigilance reporting requirements for neurovascular implants extend market access timelines by 18-24 months versus FDA pathways. Tokyo and Osaka academic centers lead arteriovenous malformation liquid embolic adoption despite polymerization control constraints. METI funding supports domestic nitinol wire processing capabilities.
India
Domestic manufacturing incentives under the PLI scheme attract catheter production investment to serve South Asian demand. CDSCO regulatory harmonization with IMDRF standards accelerates import substitution for embolization coils. Hyderabad and Bengaluru emerge as interventional radiology training hubs for the subcontinent.
United Kingdom
NICE technology appraisals determine hospital procurement decisions for embolization platforms across NHS trusts. London teaching hospitals concentrate uterine fibroid embolization volume as outpatient migration accelerates. The MHRA's post-Brexit regulatory autonomy creates asynchronous CE marking recognition timelines for liquid embolics.
Global Vascular Embolization Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the bioresorbable-permanent implant divide, with FDA PMA scrutiny compressing returns for neurovascular permanents. The vendor base stratifies into three tiers: diversified conglomerates with neurovascular portfolios, interventional oncology specialists, and regional catheter fabricators. Dominant competitive moves include portfolio rationalization under EU MDR evidence burdens and backward integration into nitinol wire processing.
Within the diversified conglomerate tier, Medtronic, Boston Scientific Corporation, and Stryker Corporation occupy positions shaped by their historical neurovascular, interventional oncology, and hemorrhagic stroke specializations respectively. These Dublin-based, Massachusetts-based, and Michigan-based entities exemplify how geographic clustering around major medical device corridors reinforces R&D density and regulatory expertise accumulation.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Stryker Corporation |
| Cook Medical |
| Terumo Corporation |
| Abbott Laboratories |
| Johnson & Johnson |
| Penumbra Inc. |
| Merit Medical Systems |
| Others |
Supply & Pricing Matrix
Premium bioresorbable versus commodity permanent implant divergence splits pricing power and sourcing configurations across the vascular embolization devices landscape. Platinum-tungsten alloy coils command reimbursement premiums at comprehensive stroke centers in the United States, while calibrated microspheres compete on unit economics in outpatient tumor embolization workflows.
Pricing Analysis
Value-based pricing anchors on clinical outcome metrics and repeat intervention avoidance in cerebral aneurysm management. Three-tier pricing structure across premium flow-diverters, standard detachable coils, and economy pushable coils reflects FDA PMA certification levels and radiopacity performance. Cost compression in the microsphere segment intensifies as hospital procurement committees unbundle device purchasing from procedure reimbursement. Ambulatory surgical centers exhibit highest price sensitivity, while tertiary neurosurgical centers prioritize visualization precision over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for nitinol wire and platinum feedstock mandate multi-supplier qualification among catheter manufacturers in Germany and Japan. Raw material dependencies center on nickel-titanium alloys from the Baden-Württemberg corridor, platinum group metals from South African refiners, and ethylene vinyl alcohol copolymers from Japanese chemical producers. Single-source vulnerability concentrates in specialized polymerization catalysts for liquid embolics. Distribution runs through integrated delivery networks consolidating vendor agreements across hospital systems in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as manufacturers pursue captive control over nitinol wire processing to defend margin structures against feedstock volatility.
For Market Incumbents: Cement neurovascular portfolio dominance through backward integration into platinum-tungsten alloy processing and expanded interventional radiology training consortiums. Bioresorbable microsphere substitution threatens repeat intervention revenue pools. FDA PMA pathway expertise remains the critical defensive lever against mid-tier competitors facing EU MDR evidence burdens. For New Entrants and Emerging Players: AI-fluoroscopy convergence technologies offer entry wedge into radiation exposure reduction and procedure time compression. Pediatric congenital vascular malformation therapy presents the most penetrable indication gap with limited device-specific labeling. Reimbursement strategy alignment with ASC outpatient migration in Texas and California accelerates commercial traction. For Investors and Strategic Acquirers: Re-rating potential sits with bioresorbable platform specialists given REACH compliance acceleration and long-term implant liability reduction. Five-to-ten year viability hinges on clinical evidence generation speed. Acquisition target archetype: mid-tier manufacturers with notified body relationships and orphan indication portfolios. Watch EU MDR retrospective data requirements as inflection indicator for portfolio rationalization pressure.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Submission | Accelerates market access for permanent neurovascular implants against 510(k) competitors. |
| CE Marking Pathway | Navigates EU MDR clinical evidence requirements for liquid embolics and flow diverters. |
| Hospital System Partnership | Secures preferred vendor status within consolidated integrated delivery networks. |
| Software Companion Development | Integrates AI-fluoroscopy algorithms to reduce radiation exposure and procedure time. |
| Reimbursement Strategy | Aligns device pricing with CPT code parity for ASC outpatient migration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this vascular embolization devices analysis. Primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) and PMA databases, EU MDR notified body submissions, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis underwent triangulation validation.
Data-stream reconciliation across hospital procurement databases, GPO contract disclosures, and academic medical center pilot program announcements informed the analytical framework. Segmentation dimensions modeled include product type, technology platform, clinical application, and end-user setting across the projection horizon. CAGRs derived from procedure volume trajectories and ASP compression curves in coil and microsphere segments. Nitinol wire pricing volatility and platinum feedstock sourcing patterns served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including regulatory approval delays beyond notified body queue timelines and interventional radiology fellowship program expansion constraints. Forecasts reflect assumptions regarding reimbursement parity maintenance between hospital outpatient departments and ambulatory surgical centers. Deviation in FDA PMA review intensity or EU MDR retrospective data requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Memory Implants Market
Medical Devices
Indonesia Devices Market
Medical Devices
Micro-Bypass Systems Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Global Otoscopes Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Global Micro Guide Catheters Market