
 Intensive Care Unit (ICU) Ventilators Market | 2026-2036
Intensive Care Unit (ICU) Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
Intensive Care Unit (ICU) Ventilators Market Foresight
Hospital procurement departments are collapsing their traditional reliance on rental and lease models for ICU ventilators in favor of direct capital purchases with embedded service contracts. Philips Healthcare leverages its installed base of patient monitoring ecosystems to bundle ventilator sales with telemetry integration. Medtronic anchors its position through deep relationships with integrated delivery networks that prioritize single-vendor critical care platforms. Hamilton Medical differentiates on software-driven ventilation modes that adapt breath-by-breath to patient physiology.
Intensive care unit ventilators are electromechanical life-support systems that deliver precisely controlled mixtures of oxygen and air to patients with compromised spontaneous breathing, typically operating at pressure ranges from 5 to 40 cm H2O and incorporating microprocessor-controlled feedback loops for tidal volume regulation. Their primary purpose is to maintain adequate gas exchange and reduce work of breathing in patients with acute respiratory failure, anesthesia management, or neurological compromise. Invasive ventilation systems command the largest revenue pool due to their indispensable role in surgical and trauma ICUs, while portable ventilators represent the fastest-expanding segment as health systems decentralize step-down care and emergency transport capabilities. Volume control technology retains dominant placement in high-acuity settings, though adaptive modes are gaining share in centers pursuing lung-protective ventilation protocols.
The FDA governs premarket notification and quality system requirements for ventilators marketed in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence and post-market surveillance obligations on manufacturers accessing European health systems. Both frameworks are elevating barriers for new entrants and accelerating consolidation among established suppliers with robust regulatory affairs infrastructure. Stakeholders must monitor how reimbursement shifts toward value-based critical care contracts reshape equipment procurement criteria and vendor selection timelines.
Market Dynamics
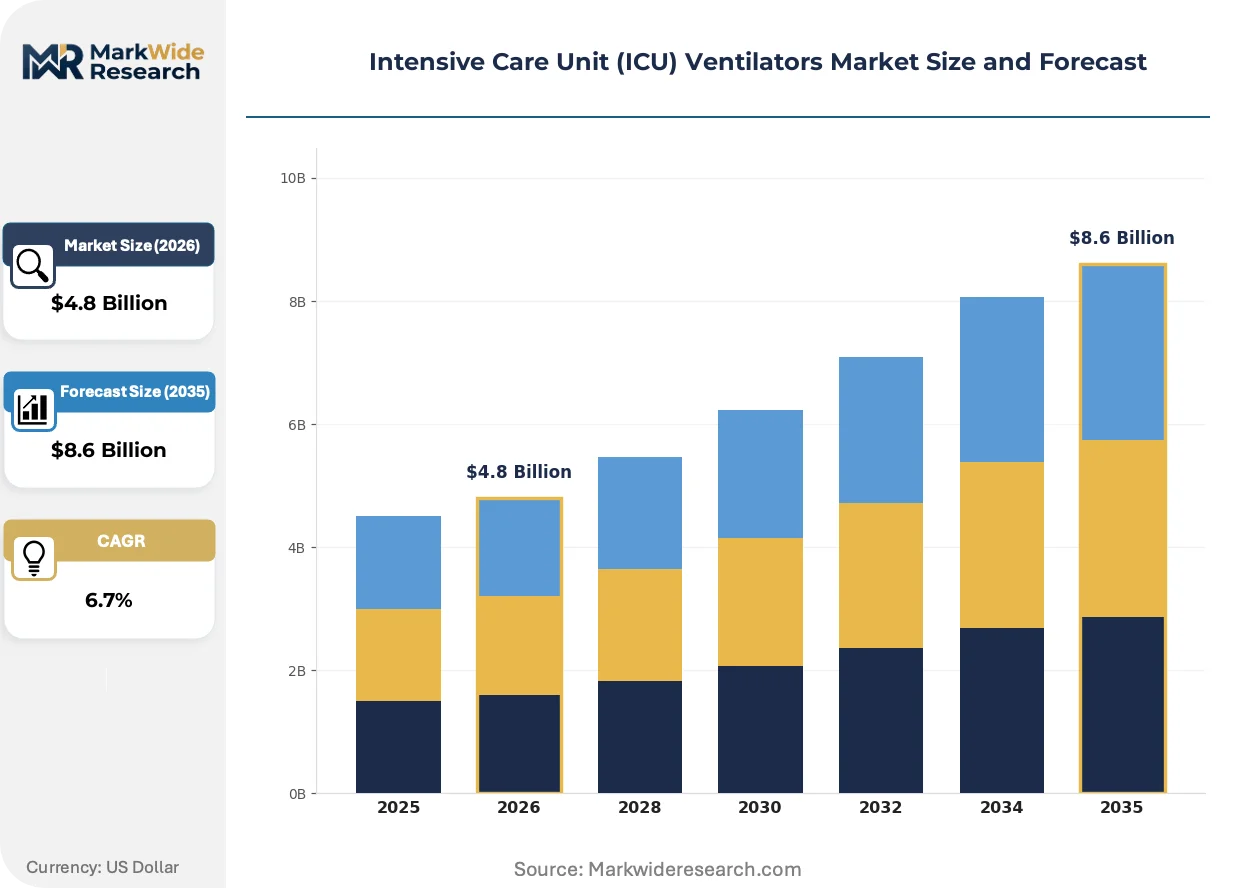
Hospital procurement departments are collapsing rental and lease models for ICU ventilators in favor of direct capital purchases with embedded service contracts, fundamentally restructuring vendor relationships and pricing architectures across critical care supply chains.
Growth Catalysts
- Critical care capacity rebuilding:Health systems are replacing pandemic-era ventilator depletion with modernized fleets, creating sustained equipment refresh cycles in tertiary centers.
- FDA 510(k) pathway evolution:Tighter premarket validation requirements for respiratory devices are filtering out marginal suppliers and concentrating demand among established manufacturers with robust regulatory affairs infrastructure.
- Data-integrated system preference:Tertiary care centers are prioritizing connected ventilators that interface with patient monitoring ecosystems, driving replacement of aging standalone units.
Market Restraints
- Microprocessor and sensor input concentration:Supply bottlenecks in specialized pneumatic valves and flow sensors create production volatility for manufacturers dependent on single-source semiconductor foundries.
- EU MDR clinical evidence burdens:Stricter post-market surveillance obligations and expanded clinical trial requirements for Class IIb respiratory devices extend time-to-market for new entrants by 18-36 months.
- High-acuity ventilator cost structure:Precision manufacturing requirements for pressure control systems and biocompatible breathing circuits sustain elevated unit economics that limit penetration in cost-constrained health systems.
Strategic Opportunities
- Step-down care decentralization:Portable ventilator demand is accelerating as health systems expand emergency transport and post-ICU respiratory support outside traditional hospital walls.
- Lung-protective ventilation protocol adoption:Adaptive ventilation modes that modulate breath-by-breath pressure and volume are capturing share from conventional volume control in centers pursuing ARDS prevention strategies.
- Value-based critical care contracts:Reimbursement shifts toward bundled payment models for respiratory failure episodes are reshaping procurement criteria to favor vendors demonstrating outcome-linked equipment performance.
Industry Challenges
- Biomedical engineering talent scarcity:Shortages of specialists capable of integrating ventilator software with hospital electronic health record systems delay deployment timelines and inflate implementation costs.
- Legacy fleet interoperability:Health systems with mixed-vendor critical care environments face complex data standardization requirements when connecting new ventilators to existing patient monitoring architectures.
- 510(k) submission preparation:Manufacturers must navigate expanded predicate device scrutiny and software documentation demands that compress product development schedules and strain regulatory affairs teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intensive Care Unit (ICU) Ventilators Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive, Non-invasive, Portable, High-frequency Technology: Pressure Support, Volume Control, Bi-level, Adaptive End User: Hospitals, Rehabilitation Centers, Home Care, Emergency Services Application: Respiratory Failure, Anesthesia, Neurological Disorders, Cardiac Arrest |
| Companies Covered | Philips Healthcare, Getinge AB, Medtronic, Drägerwerk AG & Co. KGaA, ResMed, Hamilton Medical, GE Healthcare, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Vyaire Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intensive Care Unit (ICU) Ventilators Market Shifts & Advancements
Software-driven ventilation architectures are redefining competitive differentiation in intensive care, with adaptive algorithms and remote connectivity capabilities becoming primary purchase criteria ahead of hardware specifications.
Adaptive pressure and volume modulation technology is supplanting conventional volume control as the default ventilation strategy in high-acuity settings. Tertiary care centers across the United States are adopting these systems at accelerated replacement cycles. This shift is compressing margins for manufacturers lacking real-time physiological feedback capabilities in their product portfolios.
The FDA's updated 510(k) pathway for respiratory devices is elevating software validation and cybersecurity documentation requirements. Manufacturers must now submit comprehensive evidence of algorithm robustness and data integrity protections. High-acuity invasive ventilation systems face the steepest compliance burdens, with submission timelines extending substantially for products incorporating machine learning-based breath adaptation.
Hospital acquisition committees are unbundling equipment purchases from traditional multi-year service agreements, negotiating discrete contracts for maintenance, training, and software updates. Integrated delivery networks are leading this restructuring, leveraging their scale to extract pricing transparency on lifecycle costs. This pattern is most pronounced in United States metropolitan markets where health system consolidation has concentrated buying power.
Intensive Care Unit (ICU) Ventilators Market Segmentation
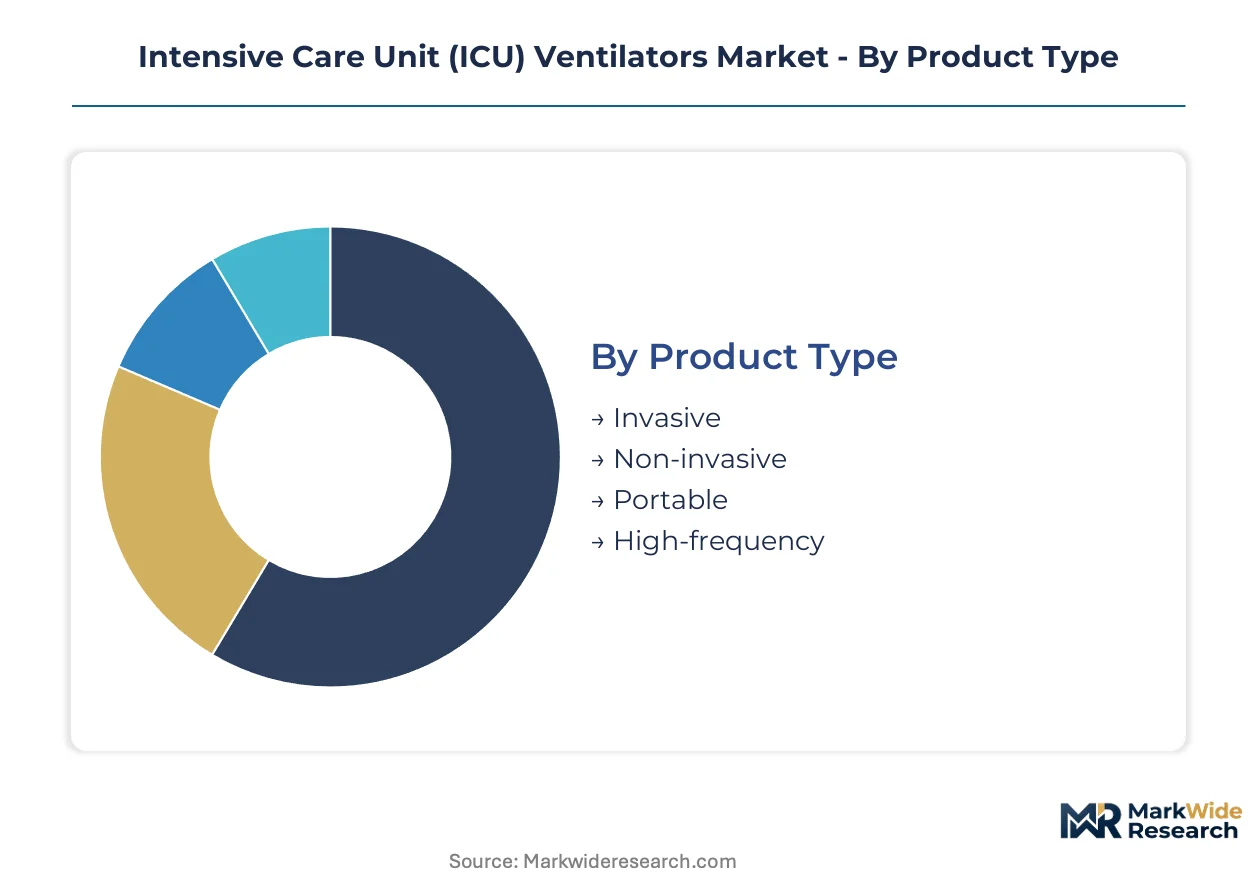
ICU ventilator procurement patterns diverge sharply across clinical settings and technological configurations. Manufacturers must align product portfolios with distinct reimbursement pathways and regulatory validation requirements that govern each segment's commercial trajectory.
Product Type:
Domestic health system procurement dominates invasive and high-frequency categories, while portable ventilators drive export-led expansion into decentralized care markets.
- Invasive:Electromechanical systems delivering controlled gas mixtures through endotracheal or tracheostomy interfaces, operating at 5-40 cm H2O pressure ranges with microprocessor feedback loops. Demand concentrates in United States tertiary surgical and trauma ICUs as health systems rebuild pandemic-depleted fleets with connected, data-integrated platforms.
- Portable:Lightweight battery-operated units designed for emergency transport and step-down respiratory support outside traditional ICU walls. Export markets in Germany and Japan are absorbing production capacity as these systems enable hospital-at-home reimbursement models.
- Non-invasive:Mask-based ventilation systems avoiding intubation for patients with acute-on-chronic respiratory failure.
- High-frequency:Specialized oscillatory ventilators delivering very small tidal volumes at rapid rates for neonatal and severe ARDS applications.
Invasive systems command the established base. The steepest expansion runs through portable ventilators.
Technology:
Cost tier stratification separates premium adaptive modes from standardized volume control platforms, with reimbursement rates determining hospital adoption thresholds.
- Adaptive:Software-driven architectures modulating breath-by-breath pressure and volume based on real-time physiological feedback. United States academic medical centers are prioritizing these systems for lung-protective ARDS prevention protocols, displacing conventional modes at accelerated replacement cycles.
- Volume Control:Conventional microprocessor-regulated systems delivering preset tidal volumes regardless of patient effort. Cost-constrained community hospitals in India and Brazil retain this technology as the default standard, limiting penetration of premium alternatives.
- Pressure Support:Patient-triggered, pressure-limited ventilation assisting spontaneous breathing efforts.
- Bi-level:Alternating inspiratory and expiratory positive airway pressure systems common in non-invasive applications.
Volume control retains the installed base. Adaptive technology is climbing the fastest among replacement purchases.
End User:
Customer type determines service contract structures, with integrated delivery networks negotiating enterprise pricing distinct from standalone facility procurement.
- Hospitals:Tertiary and community acute care facilities operating 24/7 critical care units. United States metropolitan health systems are collapsing rental models in favor of direct capital purchases with embedded telemetry integration.
- Home Care:Long-term ventilator-dependent patients receiving respiratory support outside institutional settings. Japan's aging demographic and Germany's hospital-at-home reimbursement expansion are driving demand for simplified, caregiver-operated interfaces.
- Rehabilitation Centers:Post-acute facilities weaning patients from mechanical ventilation.
- Emergency Services:Pre-hospital and inter-facility transport providers requiring ruggedized, battery-dependent systems.
Hospitals anchor procurement volume. Home care is gaining share fastest as reimbursement shifts toward decentralized models.
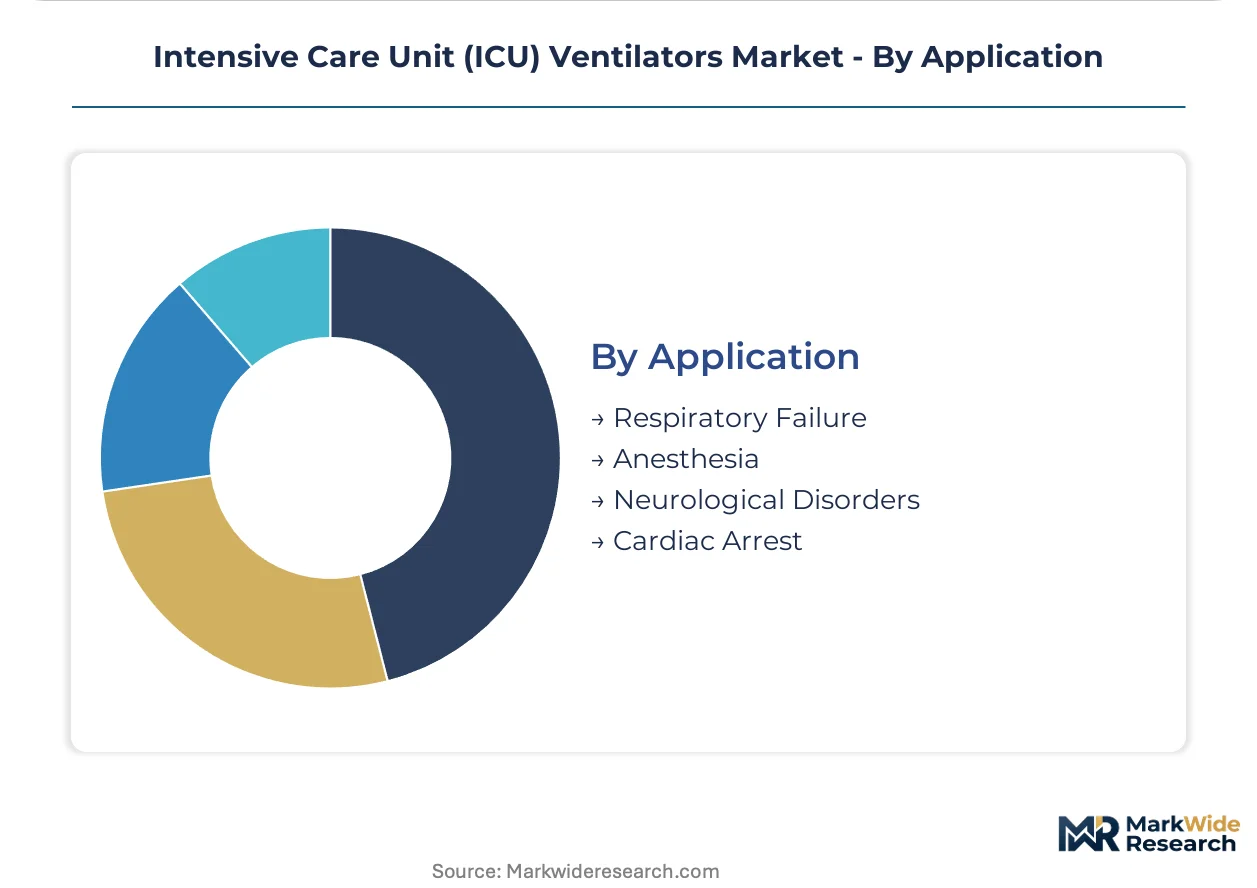
Application:
Clinical indication severity dictates hardware specifications, with respiratory failure requiring the most sophisticated monitoring integration.
- Respiratory Failure:Acute hypoxic or hypercapnic decompensation requiring immediate ventilatory support. United States surgical ICUs and medical ICUs are modernizing fleets to meet FDA's tightened 510(k) premarket validation for high-acuity respiratory devices.
- Anesthesia:Intraoperative mechanical ventilation during surgical procedures. Operating room integration with patient monitoring ecosystems determines vendor selection in consolidated United States delivery networks.
- Neurological Disorders:Ventilatory support for patients with compromised central respiratory drive.
- Cardiac Arrest:Post-resuscitation ventilation and targeted temperature management protocols.
Respiratory failure applications dominate unit deployment. Anesthesia-linked sales are expanding most quickly through OR modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics infrastructure underwrites Europe's distribution centrality for respiratory equipment, while the US Interstate highway network and dedicated medical air freight corridors enable rapid deployment across American health systems.
United States
Tertiary care centers in Houston and Boston are modernizing aging ventilator fleets with connected, data-integrated systems. FDA's updated 510(k) pathway tightens premarket validation requirements for respiratory devices. The Cleveland Clinic and Mayo Clinic networks are collapsing rental models in favor of direct capital purchases with embedded telemetry integration.
Germany
University hospitals in Berlin and Munich are absorbing portable ventilator production capacity for hospital-at-home reimbursement expansion. EU Medical Device Regulation imposes stricter clinical evidence and post-market surveillance obligations on manufacturers. The Baden-Württemberg medical technology cluster around Stuttgart is concentrating adaptive ventilation software development.
Japan
Aging demographics in Tokyo and Osaka are driving demand for simplified, caregiver-operated home care interfaces. METI coordinates industrial policy for medical device export competitiveness. The Kobe medical device manufacturing corridor is scaling production of lightweight battery-operated units for emergency transport applications.
China
Cost-constrained community hospitals in Shanghai and Guangzhou retain volume control technology as the default standard. NMPA governs premarket notification through streamlined Class II device pathways. The Shenzhen electronics manufacturing ecosystem is capturing sensor and microprocessor component supply for domestic ventilator assembly.
India
Private hospital chains in Mumbai and Delhi-NCR are prioritizing lung-protective ventilation protocols for ARDS prevention strategies. CDSCO regulates medical device imports through risk-based classification systems. The Karnataka medical technology corridor around Bangalore is developing software-driven ventilation architectures for price-sensitive Asian markets.
Intensive Care Unit (ICU) Ventilators Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates and specialized respiratory equipment manufacturers. Three to five established suppliers command the high-acuity segment through regulatory affairs infrastructure and installed base relationships. Strategic archetypes include patient monitoring ecosystem integrators, single-vendor critical care platform providers, and software-driven ventilation mode specialists. Competitive moves center on telemetry bundling contracts and adaptive algorithm differentiation.
Among diversified healthcare technology groups, Philips Healthcare and GE Healthcare exemplify the ecosystem-integrated archetype, leveraging patient monitoring infrastructure to anchor ventilator placement. Medtronic occupies a position within the single-vendor platform tier, while Hamilton Medical represents the software-specialist vector. Drägerwerk AG & Co. KGaA and Getinge AB sit within the European engineering-intensive segment, with Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchoring the Asia-Pacific manufacturing scale position.
| Leading Market Players |
|---|
| Philips Healthcare |
| Getinge AB |
| Medtronic |
| Drägerwerk AG & Co. KGaA |
| ResMed |
| Hamilton Medical |
| GE Healthcare |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Vyaire Medical |
| Others |
Supply & Pricing Matrix
FDA's updated 510(k) pathway for respiratory devices gates both supplier qualification and price differentiation simultaneously, concentrating procurement among manufacturers with validated regulatory affairs infrastructure while compressing margins for uncertified competitors. Health system procurement committees exploit this concentration to negotiate enterprise pricing on connected ventilator platforms.
Pricing Analysis
Volume-discount tiering structures dominate ICU ventilator procurement, with integrated delivery networks extracting graduated price concessions based on fleet replacement scale and telemetry bundling scope. Price differentiation hinges on FDA 510(k) clearance tier and embedded software service contracts, with adaptive mode systems commanding premiums over volume control platforms. Cost compression in standard-tier equipment is intensifying because Chinese and Indian manufacturers are scaling production of simplified microprocessor-controlled units. Community hospitals in emerging markets exhibit highest price sensitivity, while United States academic medical centers prioritize outcome-linked performance over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor precision pneumatic valve and flow sensor fabrication for high-acuity ventilator assembly, while China's Shenzhen electronics ecosystem captures microprocessor and display component supply. Taiwan and South Korea feed semiconductor foundry capacity for real-time physiological feedback systems. Supply chain risk centers on single-source dependency for specialized biocompatible breathing circuit polymers. Distribution runs through regional medical device logistics hubs with dedicated cold-chain capabilities for sensitive electronic components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICU ventilator demand sits in early-cycle expansion as health systems rebuild pandemic-depleted critical care capacity with connected, data-integrated platforms. This replacement wave offers incumbents and entrants distinct pathways to capture value.
For Market Incumbents: Secure telemetry bundling contracts with integrated delivery networks before competitors anchor patient monitoring ecosystem integration. Lock in multi-year software service agreements that embed ventilator fleets within hospital electronic health record architectures. Capacity addition in Germany's Baden-Württemberg medical technology cluster strengthens adaptive algorithm development against software-specialist challengers.
For New Entrants and Emerging Players: FDA's streamlined 510(k) predicate device pathway for software-upgradable platforms offers fastest certification velocity for adaptive ventilation mode specialists. Portable ventilator demand for hospital-at-home reimbursement models in Germany and Japan represents the most penetrable white-space segment. Partner with emergency medical services distributors to bypass entrenched hospital procurement gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to monetize non-core respiratory device divisions with established FDA clearances but lagging software capabilities. Long-term viability favors manufacturers with proprietary adaptive algorithm IP and recurring software revenue streams. Watch for inflection when bundled payment models for respiratory failure episodes achieve critical mass in United States metropolitan health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts lock in multi-year fleet replacement cycles with telemetry integration requirements. |
| Software Companion Development | Adaptive algorithm modules that interface with Epic and Cerner EHR systems differentiate premium ventilator platforms. |
| CE Marking Pathway | EU MDR compliance accelerates market access for manufacturers with robust post-market surveillance infrastructure. |
| Reimbursement Strategy | Value-based critical care contracts with CMS and commercial payors reshape procurement criteria toward outcome-linked performance. |
| Backward Integration | In-house production of specialized flow sensors reduces dependency on single-source German pneumatic component suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with critical care physicians, hospital procurement committee members, biomedical engineering directors, GPO contracts managers, and ventilator manufacturer product strategy leads. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract registries, and CMS Medicare respiratory therapy reimbursement data. Bottom-up unit demand estimates triangulated against top-down health system capital expenditure surveys.
Across the analysis window, volume and value outputs segmented by product type, technology tier, end-user facility category, and clinical application. CAGRs were derived from replacement cycle modeling and penetration rate assumptions for adaptive ventilation modes. Forecast inputs incorporated health system consolidation trajectories, FDA submission timeline projections, and EU MDR clinical evidence burden impacts on time-to-market.
Underlying assumptions cover sustained health system capital expenditure recovery and stable semiconductor supply for microprocessor-controlled feedback systems, with deviation risk concentrated in regulatory timeline extensions and biomedical engineering talent scarcity delaying deployment. Recalibration cycles align with material shifts in FDA 510(k) pathway evolution and bundled payment model adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Lung Injury Market
Respiratory Care
Emphysema Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Lung Management Products Market