
 Global Portable Ventilators Market | 2026-2036
Global Portable Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Ventilators Market Analysis
Aftermarket service revenue is reshaping profitability models across the portable ventilator industry. ResMed leverages its cloud-connected device ecosystem to sustain recurring revenue streams from remote patient monitoring. Koninklijke Philips N.V. anchors its position through integrated sleep and respiratory care platforms spanning hardware and digital health services. Hamilton Medical differentiates via high-acuity transport ventilators designed for critical care environments.
Portable ventilators are electrically or pneumatically powered mechanical devices that deliver controlled breathing support through positive pressure, typically operating at flow rates between 0.5 and 60 liters per minute with battery autonomy exceeding two hours for emergency transport. These devices serve patients with acute respiratory failure, chronic obstructive pulmonary disease, and neuromuscular conditions across clinical and non-clinical settings. Pressure Controlled systems command premium positioning in intensive care applications where precise lung-protective strategies reduce barotrauma risk. Home Care end users represent the fastest-expanding demand pool as payers shift reimbursement toward outpatient chronic disease management. Smart technology integration, encompassing adaptive algorithms and wireless telemetry, is displacing manual and basic electronic platforms in developed markets.
FDA 510(k) clearance pathways and EU MDR conformity assessment procedures govern market entry, with both frameworks intensifying clinical evidence requirements for software-enabled respiratory devices. ISO 80601-2-80 standards for emergency and transport ventilators establish baseline safety and performance benchmarks that manufacturers must satisfy for multi-jurisdiction commercialization. Stakeholders must evaluate how artificial intelligence-enabled diagnostic features will trigger novel regulatory classifications across FDA, EMA, and Japan's PMDA jurisdictions.
Market Dynamics
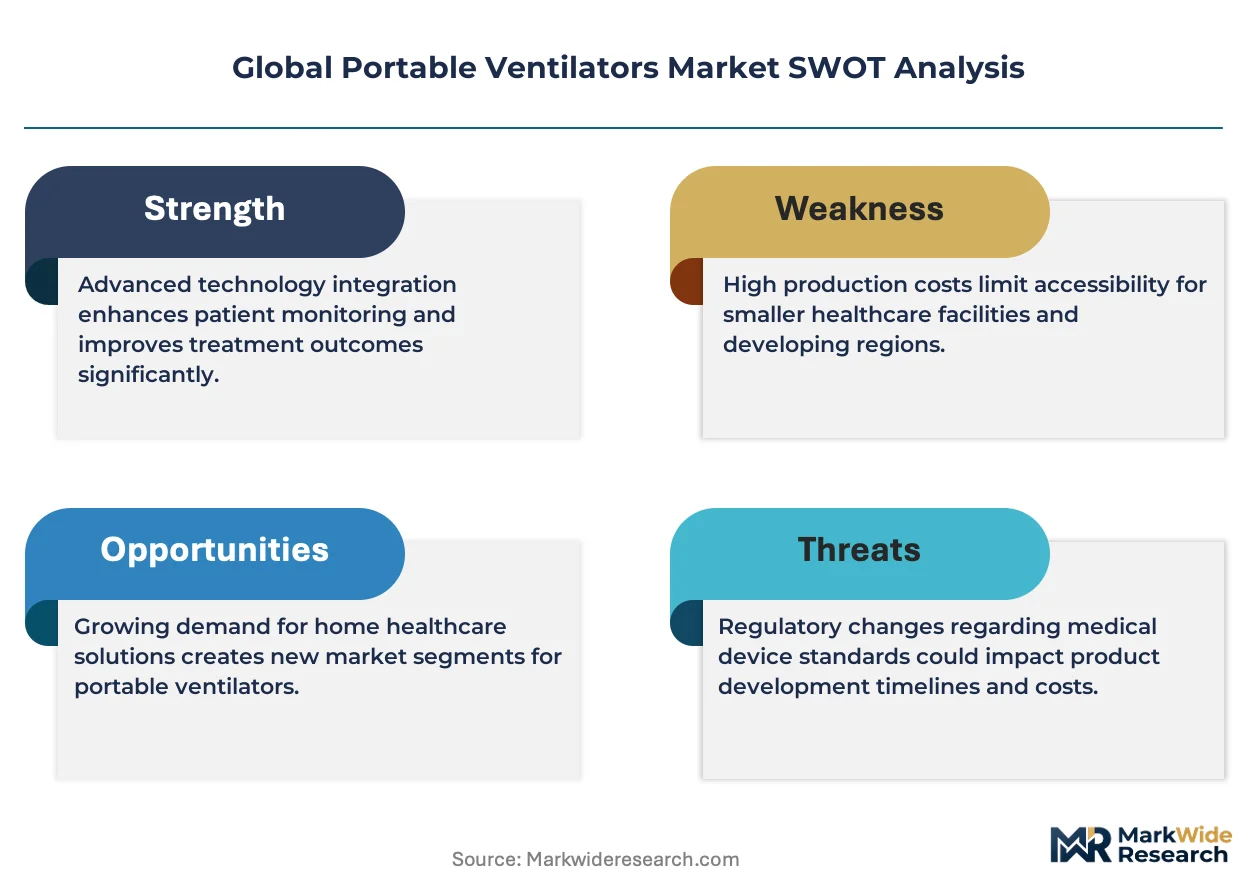
Cloud-connected respiratory ecosystems are restructuring competitive advantage around recurring revenue streams rather than device margins alone, forcing hardware manufacturers to build software and service capabilities or cede ground to integrated platform operators.
Growth Catalysts
- EU MDR compliance requirements:Stricter clinical evidence standards for software-enabled devices are consolidating the vendor base and elevating barriers that favor established players with regulatory infrastructure.
- Japan's aging demographic profile:Chronic respiratory disease prevalence among elderly populations in Tokyo and Osaka prefectures is expanding reimbursement-covered home ventilation programs.
- Adaptive algorithm integration:Machine learning-driven pressure adjustment protocols are improving patient adherence metrics and reducing hospital readmission rates for COPD management.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing capacity clusters in China's Hunan and Fujian provinces, exposing manufacturers to export control volatility and shipping disruption.
- FDA 510(k) pathway complexity:Software-as-medical-device determinations for AI-enabled diagnostic features are extending clearance timelines and inflating regulatory submission costs.
- Stationary ventilator substitution:Acute care facilities facing capital constraints are prioritizing fixed-installation devices over transport-capable alternatives for non-ambulatory patient populations.
Strategic Opportunities
- Germany's DiGA fast-track pathway:Digital health applications for remote ventilator monitoring qualify for statutory reimbursement, creating precedent for connected device ecosystem expansion across EU member states.
- Pediatric home care segments:Neuromuscular condition management for children remains underpenetrated by adult-calibrated device portfolios, opening whitespace for volume-optimized hardware formats.
- Telehealth platform integration:Direct API connectivity with Epic and Cerner electronic health record systems is enabling automated therapy data ingestion and reducing clinical documentation burden.
Industry Challenges
- Embedded systems engineering talent scarcity:Firmware development for real-time respiratory control loops requires specialized expertise that concentrates in Boston, Tel Aviv, and Shenzhen technology clusters.
- ISO 80601-2-80 multi-jurisdiction harmonization:Divergent national interpretations of alarm safety and battery endurance testing are forcing redundant certification cycles for single product variants.
- Legacy device cybersecurity retrofitting:Field-installed ventilator fleets with decade-old operating systems face patching limitations that expose healthcare networks to ransomware exploitation vectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Ventilators Market |
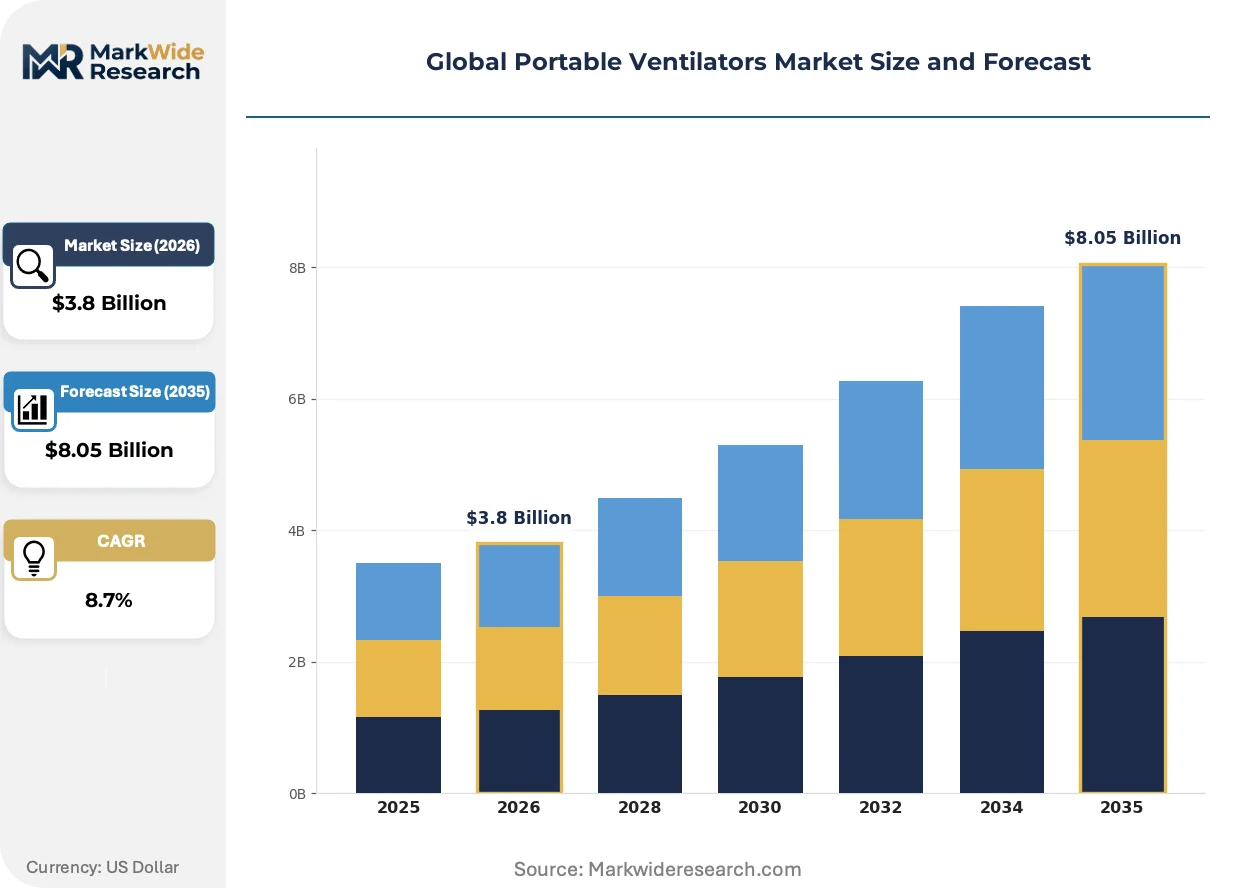
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Positive Airway Pressure, Bi-Level Positive Airway Pressure, Volume Controlled, Pressure Controlled End User: Hospitals, Home Care, Emergency Services, Rehabilitation Centers Technology: Manual, Electronic, Hybrid, Smart Feature: Portable, Battery Operated, Compact Design, User-Friendly Interface |
| Companies Covered | ResMed, Getinge AB, Koninklijke Philips N.V., Drägerwerk AG & Co. KGaA, Medtronic, Hamilton Medical, Vyaire Medical, Inc., GE Healthcare, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Ventilators Market Emerging Trajectories
Adaptive pressure control architectures and wireless telemetry integration are compressing the functional gap between transport ventilators and intensive care platforms, while regulatory frameworks race to classify software-enabled diagnostic capabilities.
Microprocessor-based turbine drive systems with active valve control are replacing traditional pneumatic bellows mechanisms in mid-acuity transport devices. Emergency medical services operators in the United States and Germany are adopting these platforms for inter-facility transfers. The technology shift is collapsing the price-performance boundary that previously separated critical-care ventilators from emergency transport units.
Japan's PMDA has issued draft guidance requiring clinical validation datasets for machine learning components in respiratory support algorithms. Manufacturers must submit prospective studies demonstrating non-inferiority to predicate devices under varied patient phenotypes. High-acuity transport ventilator segments face the steepest compliance burden as algorithm complexity increases.
Hospital procurement committees are unbundling device acquisition from preventive maintenance contracts, forcing manufacturers to compete on transparent lifecycle cost models rather than bundled financing. German university hospitals and Japanese prefectural medical centers are piloting outcome-based service agreements that tie payment to device uptime guarantees and remote monitoring response times. The purchasing pattern shift is most pronounced in tertiary care networks with centralized biomedical engineering departments.
Global Portable Ventilators Market Segmentation
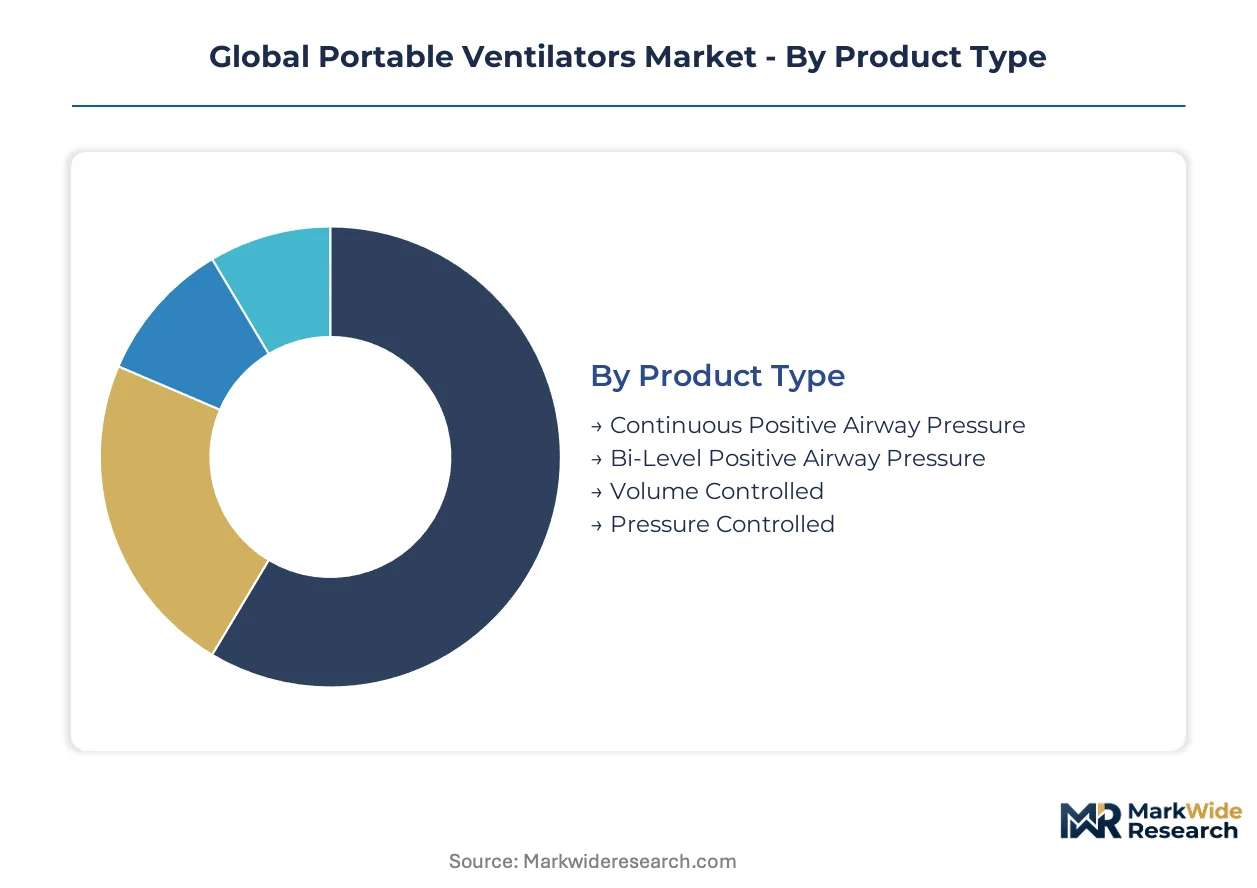
Portable ventilator segmentation reveals how clinical acuity, care setting migration, and algorithm sophistication split demand across hardware tiers. Manufacturers must align R&D investment with the specific pressure control architectures and connectivity standards dominating each segment.
Product Type:
Mature positive pressure modalities anchor hospital procurement, while emerging algorithm-driven systems capture outpatient expansion.
- Continuous Positive Airway Pressure:Delivers constant positive airway pressure through nasal or full-face interfaces at fixed therapeutic levels. Sleep apnea management in the United States and Germany concentrates demand as home reimbursement broadens.
- Bi-Level Positive Airway Pressure:Alternates between inspiratory and expiratory pressure thresholds to reduce work of breathing for neuromuscular patients. Japan's expanding elderly home care programs in Tokyo and Osaka prefectures drive volume for COPD and restrictive lung disease cases.
- Volume Controlled:Guarantees preset tidal volumes regardless of airway resistance changes. Critical care transport units favor this modality for trauma patients requiring precise minute ventilation.
- Pressure Controlled:Limits peak airway pressure to reduce barotrauma risk in acute respiratory distress syndrome. ICU-to-ward step-down protocols increasingly specify these units.
Pressure Controlled handles the majority of throughput in tertiary care networks; Bi-Level Positive Airway Pressure is climbing the fastest on share as home ventilation programs expand.
End User:
Cost tier stratification separates capital-intensive institutional procurement from patient-owned outpatient devices.
- Hospitals:Acute care facilities specify transport-capable units with turbine drive systems and active valve control for inter-departmental patient movement. FDA 510(k) clearance and EU MDR conformity assessment govern procurement qualification.
- Home Care:Compact devices with battery autonomy exceeding two hours dominate as payers shift reimbursement toward outpatient chronic disease management. Germany's DiGA fast-track pathway enables statutory coverage for remote monitoring integration.
- Emergency Services:Inter-facility transfer operators prioritize pneumatic backup capability and ruggedized chassis designs for ambulance and helicopter transport.
- Rehabilitation Centers:Weaning protocols require ventilators with progressive spontaneous breathing trial modes and precise pressure support adjustment.
Home Care is gaining share fastest as reimbursement policy tilts toward outpatient management; Hospitals retain the largest installed base.
Technology:
Application complexity determines whether basic mechanical systems or adaptive algorithm platforms satisfy clinical requirements.
- Manual:Simple pneumatic or spring-loaded pressure generators for resource-constrained settings without reliable electrical supply. Limited to emergency backup roles in developed markets.
- Electronic:Microprocessor-controlled pressure and flow regulation with basic alarm functions. Mid-acuity transport applications in Germany and Japan standardize on these platforms.
- Hybrid:Combines pneumatic reliability with electronic monitoring for redundancy-critical military and disaster response deployments.
- Smart:Machine learning-driven pressure adjustment with wireless telemetry and cloud-based adherence tracking. Japan's PMDA draft guidance imposes clinical validation requirements for these algorithmic components.
Electronic technology maintains the dominant installed footprint; Smart systems show the steepest expansion trajectory as remote patient monitoring integrates with electronic health records.
Feature:
Customer type differentiation separates clinical operators requiring technical specifications from patient caregivers prioritizing usability.
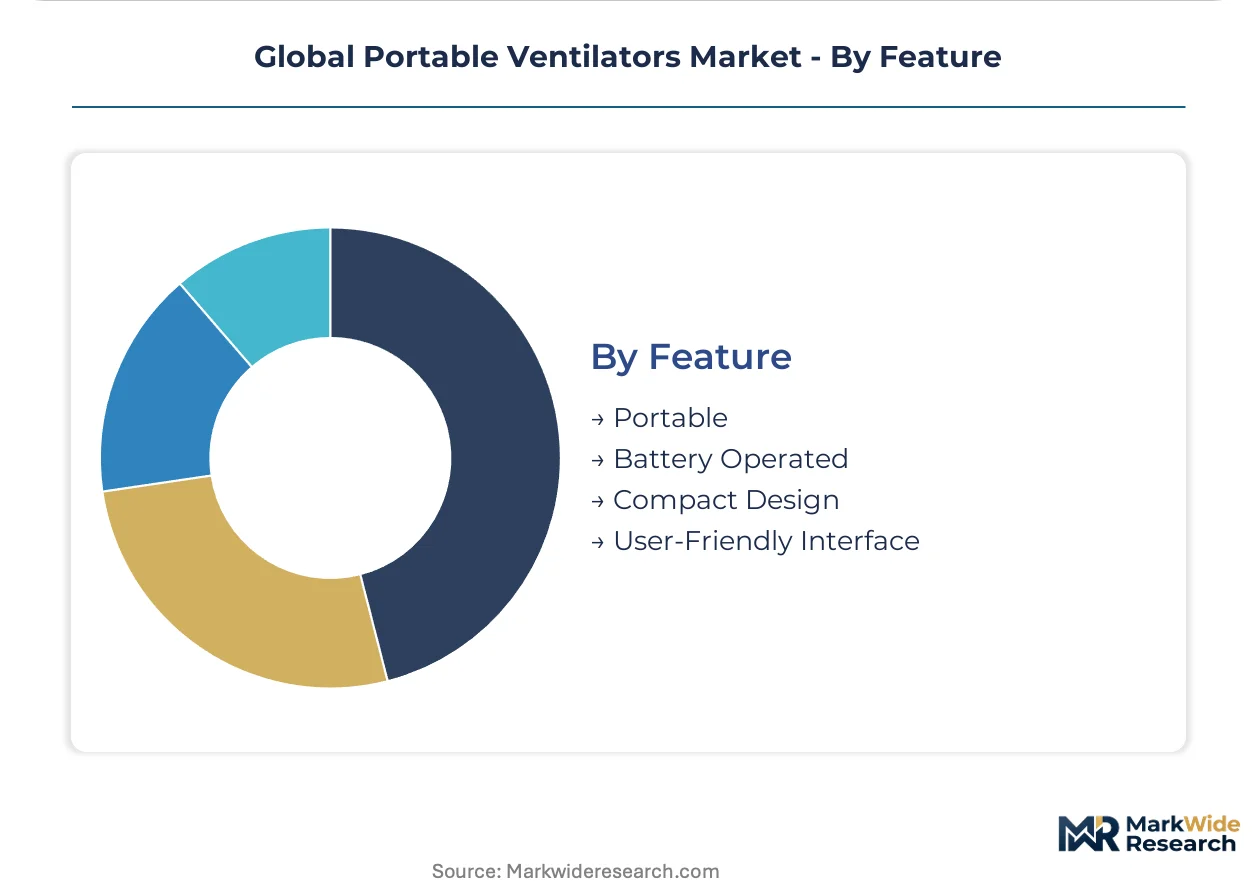
- Portable:Units under 10 kilograms with integrated carrying handles and mounting brackets for wheelchair or stretcher attachment. Emergency medical services in the United States specify these for field deployment.
- Battery Operated:Lithium-ion power systems with hot-swappable cells sustaining operation during patient transport. Supply concentration in China's Hunan and Fujian provinces creates procurement risk exposure.
- Compact Design:Reduced footprint devices for space-constrained home bedrooms and small ambulance compartments. Pediatric home care segments particularly value volume-optimized formats.
- User-Friendly Interface:Touchscreen displays with icon-driven menus and audible alarm differentiation for non-clinical caregivers. ISO 80601-2-80 alarm safety standards govern interface design for multi-jurisdiction commercialization.
Portable and Battery Operated features together address the majority of transport and home applications; User-Friendly Interface is expanding most quickly as non-clinical caregivers assume ventilation management responsibilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and Japanese buyers absorb premium pricing for algorithm-enabled systems, while Indian procurement prioritizes cost-optimized mechanical platforms. This demand-elasticity contrast shapes regional vendor strategies and certification investments.
United States
Medicare reimbursement expansion for home ventilation and aging demographic profiles in Florida and Arizona drive outpatient device demand. FDA 510(k) clearance pathways govern software-enabled respiratory device entry, with AI diagnostic features triggering novel determinations. Boston's biomedical engineering cluster concentrates firmware talent for real-time respiratory control development.
Germany
Statutory health insurance coverage for remote patient monitoring via the DiGA fast-track pathway accelerates connected ventilator adoption. EU MDR conformity assessment procedures elevate clinical evidence requirements for software-as-medical-device classifications. The Ruhr Valley medical technology corridor hosts precision manufacturing for turbine drive systems.
Japan
Tokyo and Osaka prefectures expand reimbursement-covered home ventilation programs for elderly COPD populations. PMDA draft guidance mandates prospective clinical validation for machine learning components in respiratory algorithms. The Kanagawa medical device cluster specializes in compact, battery-optimized hardware formats for space-constrained home bedrooms.
China
Provincial hospital procurement for emergency transport capabilities rises with inter-facility transfer network expansion. NMPA medical device registration requirements intensify for imported respiratory platforms. Shenzhen's electronics manufacturing ecosystem dominates lithium-ion battery assembly and cathode material processing for portable power systems.
India
State-level health mission tenders prioritize basic electronic ventilators for district hospital infrastructure. CDSCO medical device rules govern import and local manufacturing compliance for respiratory support equipment. The Bangalore medical technology corridor develops cost-optimized firmware for mid-acuity transport applications.
Global Portable Ventilators Market Vendor Landscape
Capability concentration sits with integrated platform operators; scale advantage sits with diversified medical technology conglomerates. The vendor base separates into three tiers: cloud-connected ecosystem builders, hardware-focused transport specialists, and emerging cost-optimized manufacturers. Consolidation pressure favors players with regulatory infrastructure across FDA, EU MDR, and PMDA jurisdictions. Dominant competitive moves include strategic partnerships for telehealth platform integration and backward integration into battery supply chains.
Within the integrated platform tier, ResMed and Koninklijke Philips N.V. exemplify recurring revenue architectures that combine hardware with remote monitoring services. Hamilton Medical occupies a position among high-acuity transport specialists serving critical care environments. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the cost-optimized manufacturing archetype leveraging China's electronics supply base for volume production.
| Leading Market Players |
|---|
| ResMed |
| Getinge AB |
| Koninklijke Philips N.V. |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Hamilton Medical |
| Vyaire Medical, Inc. |
| GE Healthcare |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries cathode materials and battery assemblies from China's Hunan province to European ventilator assembly plants, with freight cost volatility compressing margins on economy-tier devices while premium algorithm-enabled systems absorb logistics premiums through software recurring revenue streams.
Pricing Analysis
Preventive maintenance contracts and remote monitoring subscriptions now drive lifetime value capture across portable ventilator portfolios. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared transport units with AI diagnostics from basic electronic platforms and manual backup devices. Pricing pressure stems from hospital procurement committees unbundling acquisition and service contracts, forcing transparent lifecycle cost competition. Emergency medical services operators show highest price sensitivity; German university hospitals demonstrate lowest sensitivity due to outcome-based reimbursement frameworks.
Supply Chain Analysis
Flex Ltd. and Jabil Inc. concentrate electronics manufacturing services for turbine drive assemblies and microprocessor control boards in Shenzhen and Penang facilities. Lithium-ion cell production clusters in China's Fujian province, South Korea's Gyeonggi-do region, and Japan's Osaka prefecture. Cathode material processing draws from cobalt hydroxide feedstocks anchored in the Democratic Republic of Congo and refined in Chinese coastal zones. Single-source vulnerability runs through Hunan-based cathode precursor suppliers. Distribution runs through regional medical device distributors holding FDA and EU MDR import licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering talent for real-time respiratory control loops concentrates in Boston, Tel Aviv, and Shenzhen clusters, creating acquisition premiums for teams with ISO 80601-2-80 certification experience and PMDA submission track records.
For Market Incumbents: Harden regulatory infrastructure across FDA, EU MDR, and PMDA jurisdictions to defend against emerging cost-optimized manufacturers from Shenzhen. Deepen backward integration into lithium-ion battery supply chains to mitigate cathode material export control exposure. Prioritize cloud-connected ecosystem development to capture recurring revenue from remote patient monitoring subscriptions. For New Entrants and Emerging Players: Pursue pediatric home care segments in Japan's Tokyo and Osaka prefectures, where adult-calibrated device portfolios leave neuromuscular condition management underpenetrated. Target Germany's DiGA fast-track pathway for statutory reimbursement of remote monitoring integration. Lead with telehealth platform API connectivity to reduce clinical documentation burden for non-clinical caregivers. For Investors and Strategic Acquirers: Cloud-connected ecosystem builders with FDA 510(k) clearances and EU MDR conformity assessments command scarcity premiums in respiratory device portfolios. Long-term viability centers on recurring revenue share from software-enabled diagnostic features displacing hardware-only margins. Monitor Japan's PMDA draft guidance finalization for machine learning clinical validation requirements as inflection indicator for algorithm-enabled device valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Investment | Clinical evidence requirements for software-as-medical-device classifications favor established regulatory infrastructure holders. |
| Cloud-Connected Ecosystem Expansion | ResMed and Philips demonstrate recurring revenue capture from remote patient monitoring integration with Epic and Cerner EHR systems. |
| Pediatric Home Care Format Development | Volume-optimized hardware for neuromuscular condition management addresses whitespace in Japan's expanding elderly home ventilation programs. |
| Telehealth Platform API Integration | Direct connectivity with hospital electronic health records reduces clinical documentation burden and improves patient adherence metrics. |
| Battery Supply Chain Backward Integration | Cathode material processing concentration in China's Hunan province creates procurement risk exposure requiring upstream control. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with hospital biomedical engineers, emergency medical services procurement officers, home care reimbursement specialists, and ventilator manufacturer regulatory affairs directors. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body certificates, Japan's PMDA submission records, and hospital GPO contract repositories. Bottom-up demand modeling across clinical acuity tiers triangulated with top-down market sizing from import-export trade flows.
Calibration against historical volume data and regulatory approval timelines anchored growth projections across the analysis window. Segmentation dimensions modeled include pressure control modality, care setting migration, technology sophistication tier, and geographic reimbursement cluster. CAGR derivation incorporated algorithm adoption curves, battery autonomy improvements, and cloud connectivity penetration rates specific to respiratory device replacement cycles.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate pricing, semiconductor foundry utilization rates, or yen-euro exchange volatility would shift the trajectory for import-dependent markets. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement policy stability. Quarterly review of PMDA guidance finalization, EU MDR transition deadlines, and CMS home ventilation reimbursement updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Annuloplasty System Market
Medical Devices
Elbow Fixators Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Catheter Coatings Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Depression Devices Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Spherical IOL Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Body Contouring Devices and Procedures Market