
 North America Acute Respiratory Distress Syndrome (ARDS) Market | 2026-2036
North America Acute Respiratory Distress Syndrome (ARDS) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Acute Respiratory Distress Syndrome (ARDS) Market Analytics
The EPA's tighter medical device sterilization emissions standards is decoupling ventilator manufacturing from ethylene oxide-dependent supply chains. Medtronic plc leverages its Galway, Ireland-to-Minneapolis manufacturing corridor to sustain ventilator output under evolving EPA thresholds. Hamilton Medical AG specializes in turbine-driven ventilator architectures that eliminate compressed gas infrastructure, positioning the firm for U.S. hospital retrofit cycles. Getinge AB anchors its North American ventilator service network through regional technical centers in Ohio and California.
Acute Respiratory Distress Syndrome constitutes a life-threatening inflammatory lung injury characterized by bilateral pulmonary infiltrates, a PaO2/FiO2 ratio below 300 mmHg, and non-cardiogenic pulmonary edema requiring positive pressure mechanical ventilation. The syndrome demands rapid ICU intervention with precise tidal volume control, typically 6 ml/kg predicted body weight, to limit ventilator-induced lung injury while maintaining adequate gas exchange. Mechanical ventilators dominate product-type revenue given capital replacement cycles and software-upgradeable platforms, though pharmaceuticals represent the fastest-expanding margin pool as biologic candidates advance through Phase II trials. Hospitals absorb the majority of end-user spending due to centralized ICU infrastructure, while emergency services segments face equipment portability constraints that limit ventilator specification flexibility.
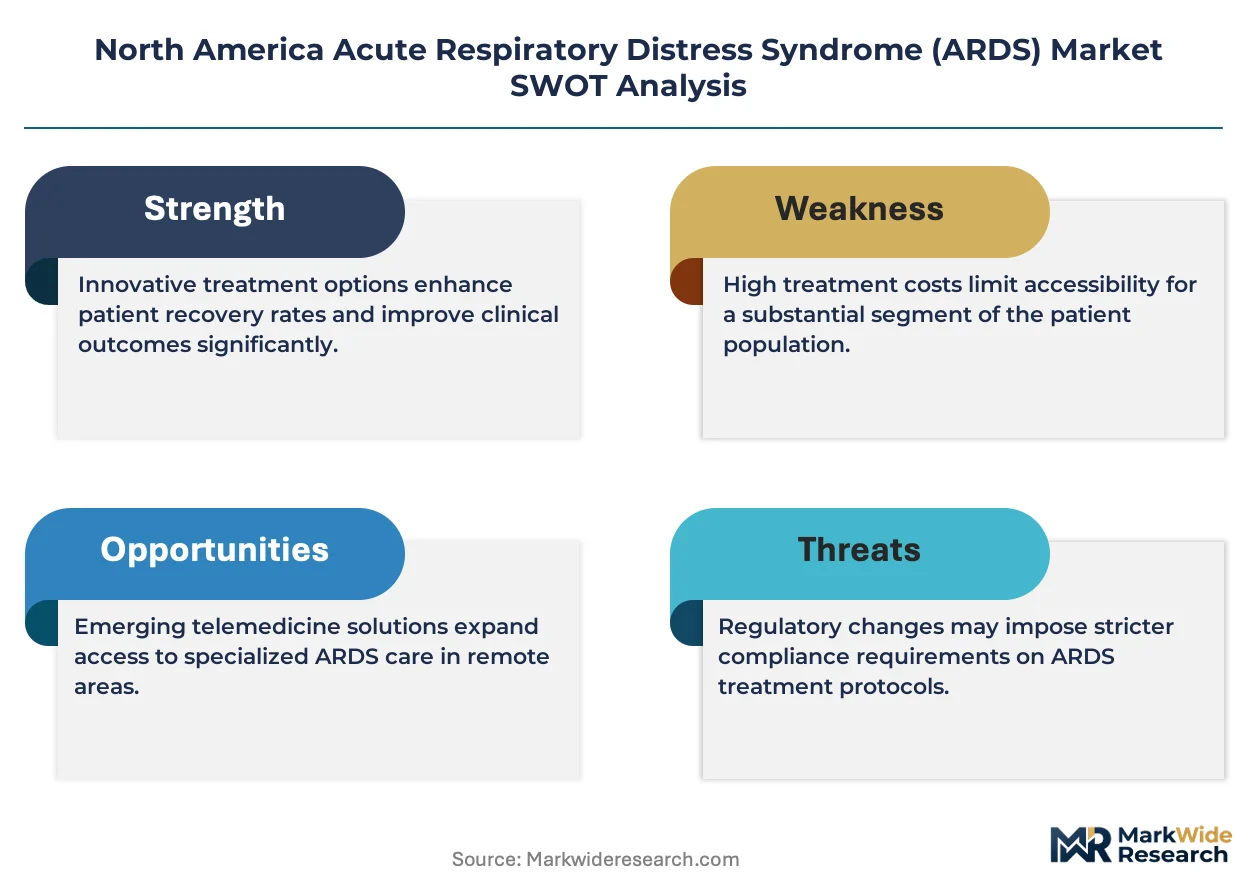
FDA's Breakthrough Therapy and Fast Track programs accelerate ARDS drug development timelines, compressing the pathway from preclinical to pivotal trials for sponsors meeting unmet need criteria. CMS reimbursement codes for prolonged mechanical ventilation directly influence hospital procurement decisions for ventilator platforms with extended-use reliability certifications. EPA medical waste incineration rules and OSHA respiratory protection standards further constrain device material selection and clinical staff training protocols. Stakeholders must monitor how FDA's evolving guidance on adaptive trial designs for critical care therapeutics reshapes competitive entry barriers for novel biologics against established supportive care protocols.
Market Dynamics
Post-pandemic CMS mandates for ICU surge capacity are forcing hospital systems to reconfigure ventilator procurement around platform modularity and software extensibility rather than standalone device purchases.
Growth Catalysts
- CMS Prolonged Mechanical Ventilation Reimbursement Codes:Extended-use payment categories incentivize hospitals to invest in ventilator platforms certified for reliability beyond 21-day continuous operation cycles.
- Cell-Based Biologics Pipelines:FDA Breakthrough Therapy designations for mesenchymal stromal cell therapies are redirecting pharmaceutical R&D investment toward ARDS-specific drug candidates.
- U.S. Southeast ICU Density:Transplant center clustering in Florida, Georgia, and Texas generates concentrated demand for advanced ventilation systems capable of supporting extracorporeal membrane oxygenation bridging protocols.
Market Restraints
- Ethylene Oxide Supply Chain Disruption:EPA medical device sterilization emissions thresholds are forcing ventilator manufacturers to qualify alternative sterilization methods or absorb capital-intensive facility upgrades.
- Single-Source Turbine Component Concentration:Precision turbine assemblies for turbine-driven ventilator architectures depend on limited European and Japanese suppliers, creating vulnerability to trade friction.
- Biologics Manufacturing Scale Constraints:Cell-based ARDS therapeutics face batch-to-batch variability challenges that limit commercial manufacturing yields relative to small-molecule production economics.
Strategic Opportunities
- Home-Based Ventilation Transition:CMS reimbursement expansion for prolonged home mechanical ventilation creates channel opportunity for portable ventilator platforms with remote monitoring capabilities.
- AI-Enabled Ventilator Titration:Machine learning algorithms integrated with closed-loop ventilation control are automating protective lung strategy execution in U.S. academic medical centers.
- Mexico Manufacturing Proximity:Nearshoring of ventilator component production to Baja California and Chihuahua reduces lead times for U.S. hospital supply chains subject to EPA compliance delays.
Industry Challenges
- Critical Care Respiratory Therapist Shortage:Specialized training requirements for advanced mode ventilation management outpace educational program output across U.S. hospital systems.
- FDA Adaptive Trial Design Uncertainty:Evolving guidance on Bayesian endpoints and master protocols for critical care therapeutics complicates biologics sponsor planning for pivotal ARDS trials.
- Legacy Fleet Software Integration:Hospital IT departments face technical debt from ventilator platforms with proprietary data architectures that resist interoperability with centralized electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Acute Respiratory Distress Syndrome (ARDS) Market |
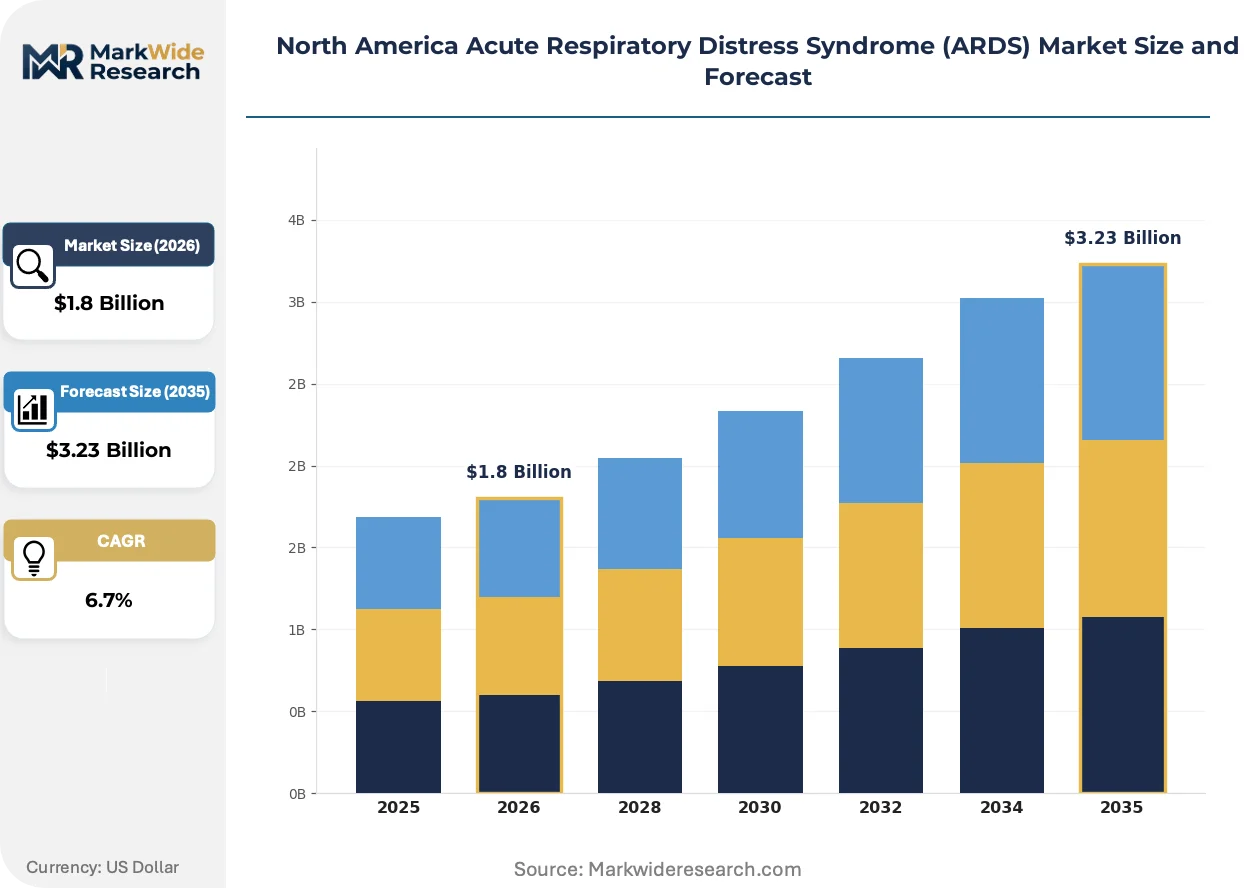
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Ventilators, CPAP Devices, Oxygen Therapy Equipment, Pharmaceuticals Delivery Mode: Inhalation, Intravenous, Oral, Subcutaneous End User: Hospitals, Home Care, Long-term Care Facilities, Emergency Services Application: ICU Care, Surgical Care, Emergency Care, Palliative Care |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Medtronic plc, GE Healthcare, Koninklijke Philips N.V., Hamilton Medical AG, Getinge AB, Athersys Inc., Faron Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Acute Respiratory Distress Syndrome (ARDS) Market Evolving Landscape
Mechanical ventilation platforms are converging with pharmaceutical monitoring systems, creating integrated care ecosystems that blur traditional boundaries between device and drug therapy management in critical care settings.
Closed-loop ventilation control systems incorporating real-time spirometry and gas exchange analytics are automating protective lung strategy execution. Academic medical centers in the U.S. Northeast and Midwest are piloting these platforms for ARDS populations requiring precise tidal volume limitation. The technology is automating clinician workload reduction while standardizing protocol adherence across nursing shift changes.
EPA medical device sterilization emissions standards are decoupling ventilator manufacturing from ethylene oxide-dependent supply chains. Manufacturers are qualifying vaporized hydrogen peroxide and nitrogen dioxide alternatives under accelerated FDA device requalification timelines. U.S.-based production facilities face the steepest compliance cost gradients given legacy infrastructure concentration.
Hospital procurement committees are unbundling ventilator hardware purchases from long-term service contracts, treating software upgrade rights as separately negotiable assets. Equipment financing firms and regional group purchasing organizations are capturing margin previously retained by original equipment manufacturers. This behavior is most visible in California and Texas health systems with centralized capital allocation committees.
North America Acute Respiratory Distress Syndrome (ARDS) Market Segmentation
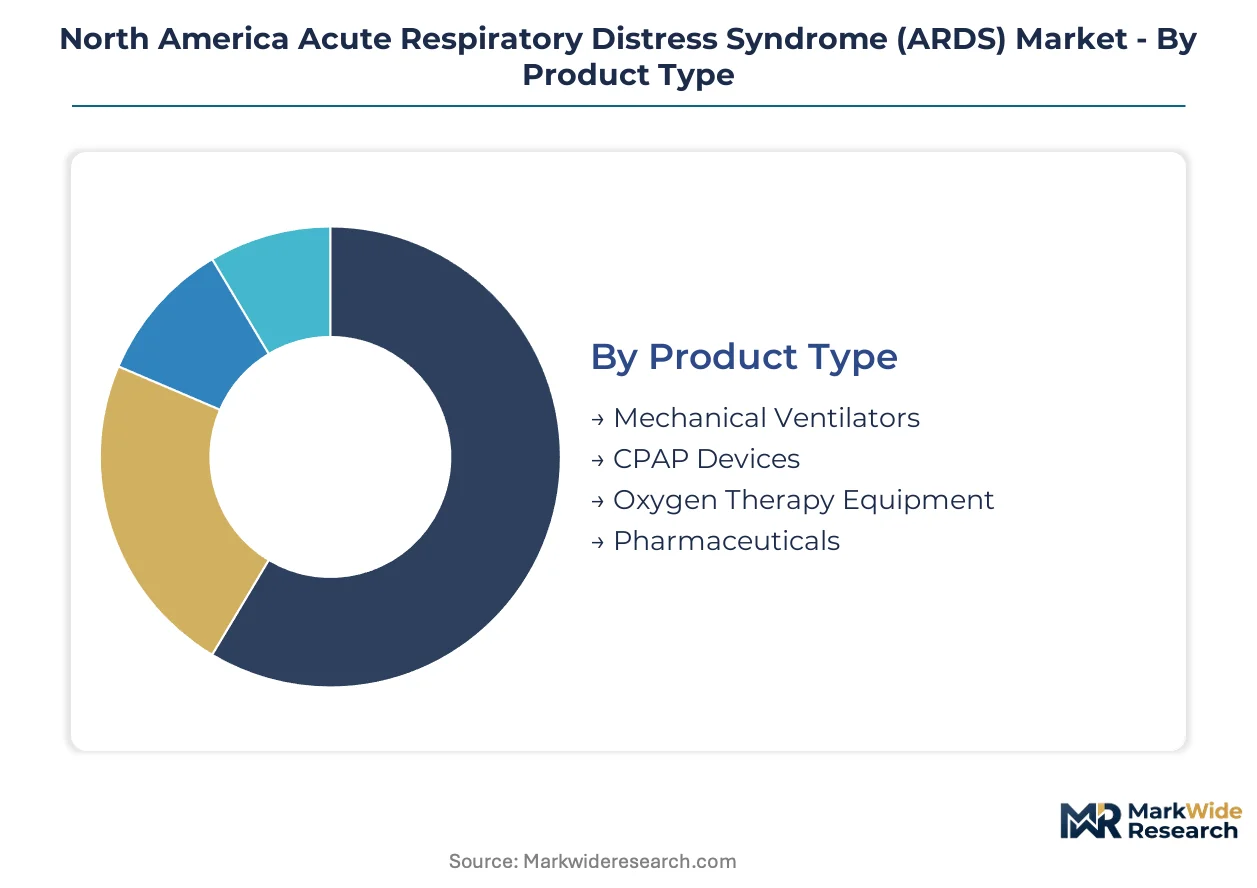
Segmentation in the North America ARDS market reflects divergent capital cycles between device replacement and pharmaceutical pipeline maturation. Hospital procurement committees weight platform modularity against therapeutic innovation timelines when allocating ICU infrastructure budgets.
Product Type:
Capital replacement cycles dominate procurement planning as post-pandemic preparedness mandates reshape hospital ventilator fleet strategies.
- Mechanical Ventilators:Software-upgradeable platforms with closed-loop control architectures command priority placement in U.S. academic medical centers. Demand concentrates in the U.S. Southeast transplant corridor, where ECMO bridging protocols require extended-use reliability certifications.
- Pharmaceuticals:Mesenchymal stromal cell therapies and biologic candidates redirect R&D investment toward ARDS-specific drug development. FDA Breakthrough Therapy designations accelerate sponsor timelines for sponsors meeting unmet need criteria in critical care populations.
- CPAP Devices:Transition-to-home protocols in Texas and Florida health systems drive portable platform adoption for prolonged mechanical ventilation reimbursement categories.
- Oxygen Therapy Equipment:High-flow nasal cannula systems integrate with ventilator weaning protocols across California ICU networks.
Mechanical Ventilators sits at the top of the volume ranking, with Pharmaceuticals climbing the fastest.
Delivery Mode:
Route selection follows therapeutic index requirements and vascular access constraints in critically ill populations.
- Intravenous:First-line administration for sedative-analgesic protocols and vasoactive support in mechanically ventilated ARDS patients. Concentrated demand in tertiary ICU settings with central line placement capabilities.
- Inhalation:Nebulized bronchodilators and inhaled prostacyclins target pulmonary vascular beds directly. Adoption accelerates in U.S. Midwest surgical ICUs with aerosol delivery standardization programs.
- Oral:Limited to stable weaning-phase patients with intact gastrointestinal function and airway protection reflexes.
- Subcutaneous:Anticoagulation prophylaxis and insulin protocols utilize this route for patients transitioning toward step-down units.
Intravenous anchors current utilization patterns, though Inhalation gains share fastest through targeted pulmonary delivery protocols.
End User:
Site-of-care economics and reimbursement granularity determine equipment specification flexibility across delivery settings.
- Hospitals:Centralized ICU infrastructure absorbs majority capital allocation, with CMS prolonged mechanical ventilation codes directly influencing platform procurement decisions. Concentrated spending in transplant center-dense geographies.
- Home Care:CMS reimbursement expansion creates channel opportunity for portable ventilator platforms with remote monitoring capabilities. Growth centers on Texas and California health systems with integrated discharge planning.
- Long-term Care Facilities:Equipment portability constraints and staffing limitations restrict ventilator specification flexibility in this segment.
- Emergency Services:Prehospital ventilation requires ruggedized turbine-driven architectures with compressed gas independence for field deployment.
Hospitals command absolute volume leadership, while Home Care demonstrates the steepest expansion trajectory through reimbursement channel development.
Application:
Clinical setting dictates ventilation mode complexity and monitoring integration requirements.
- ICU Care:Precise tidal volume limitation at 6 ml/kg predicted body weight demands advanced mode capabilities with real-time spirometry analytics. Demand clusters in U.S. Northeast academic medical centers piloting AI-enabled closed-loop control.
- Emergency Care:Rapid sequence intubation and lung-protective strategy initiation require portable platforms with automated protocol adherence. Adoption concentrates in Level I trauma centers across the Southeast.
- Surgical Care:Perioperative ventilation management in transplant and cardiac surgery units utilizes platform modularity for OR-to-ICU continuity.
- Palliative Care:Symptom-directed ventilation support prioritizes patient comfort over gas exchange optimization in terminal weaning protocols.
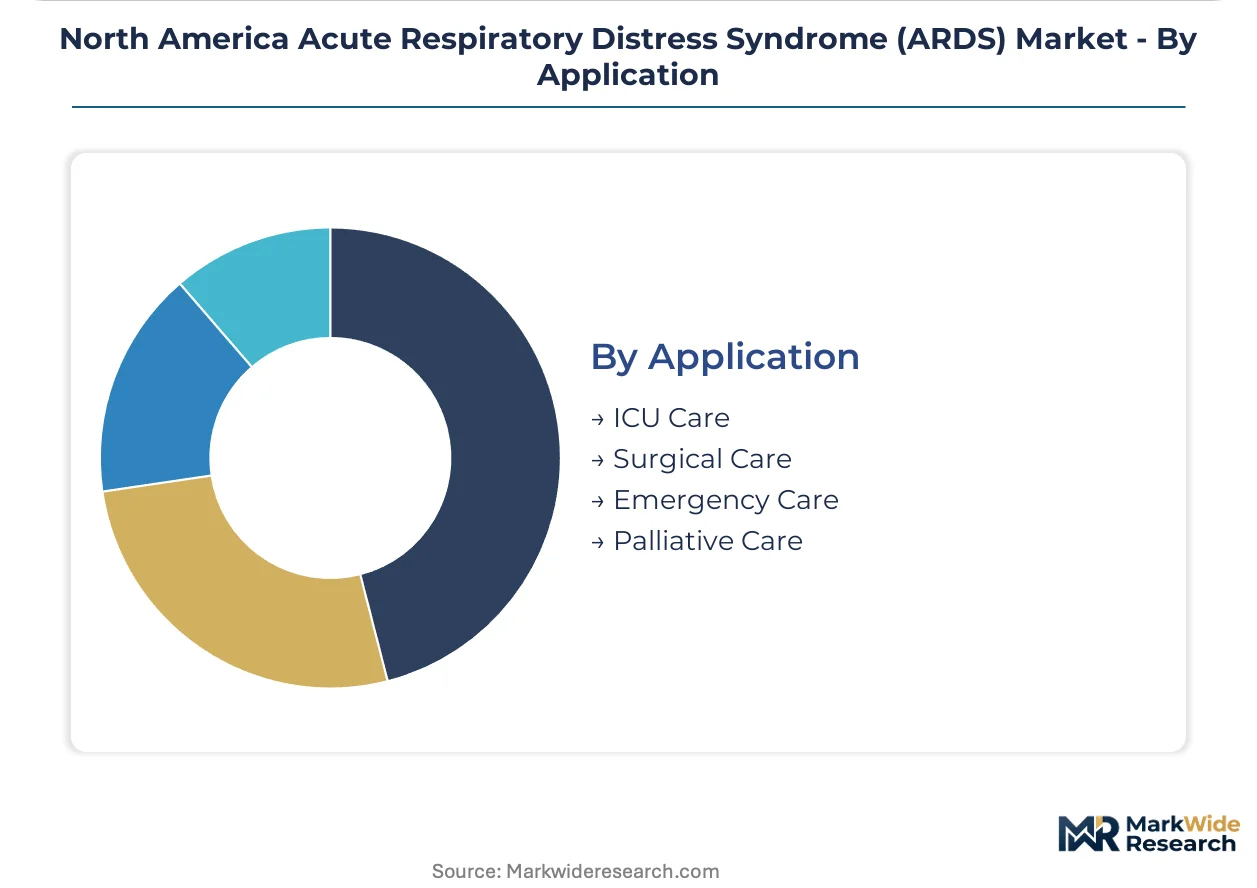
ICU Care holds the volume apex, with Emergency Care ascending fastest through prehospital protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized respiratory therapist training programs concentrate in the U.S. Southeast and Northeast, anchoring regional ICU staffing capacity for complex ventilation management. Transplant center density and aging demographics drive demand clustering. Cross-border manufacturing corridors in Mexico and Canada reshape supply chain configurations.
United States
The U.S. Southeast transplant corridor spanning Florida, Georgia, and Texas generates concentrated demand for ECMO-capable ventilator platforms. FDA Breakthrough Therapy designations for cell-based ARDS therapeutics redirect pharmaceutical R&D toward biologics pipelines. The Minneapolis medical device cluster sustains ventilator manufacturing output under evolving EPA sterilization emissions thresholds.
Canada
Provincial health authorities in Ontario and Quebec prioritize ventilator fleet standardization across academic medical center networks. Health Canada guidance on adaptive trial designs for critical care therapeutics influences biologics sponsor entry strategies. The Greater Toronto Area anchors respiratory device distribution infrastructure serving prairie province ICU networks.
Mexico
Nearshoring of ventilator component production to Baja California and Chihuahua reduces lead times for U.S. hospital supply chains. Mexican federal health procurement programs expand ICU infrastructure in Mexico City and Monterrey metropolitan zones. The Tijuana medical device manufacturing corridor qualifies alternative sterilization methods under accelerated FDA device requalification timelines.
North America Acute Respiratory Distress Syndrome (ARDS) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America ARDS market. The vendor base stratifies between diversified medical technology conglomerates and specialized respiratory device fabricators. Three archetypes dominate: integrated critical care platform suppliers, biologics-focused pharmaceutical developers, and turbine-driven ventilation specialists. Competitive moves center on EPA compliance-driven manufacturing reconfiguration and CMS reimbursement-aligned product portfolio expansion.
Among diversified medical technology conglomerates, Medtronic plc and GE Healthcare exemplify integrated critical care platform suppliers with multi-product ICU ecosystems. Koninklijke Philips N.V. occupies a position bridging diagnostic imaging and respiratory support architectures. Hamilton Medical AG and Getinge AB represent turbine-driven ventilation specialists with compressed gas-independent architectures. Pfizer Inc. and GlaxoSmithKline plc anchor the pharmaceutical tier developing ARDS-specific therapeutic candidates.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Medtronic plc |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Hamilton Medical AG |
| Getinge AB |
| Athersys Inc. |
| Faron Pharmaceuticals Ltd. |
| Others |
Value Network & Pricing Analysis
Ethylene oxide sterilization cost indices cascade through North American ventilator manufacturing, compressing margins for legacy producers while rewarding turbine-driven architectures that bypass compressed gas infrastructure entirely. This input cost divergence stratifies pricing tiers across hospital procurement committees, with EPA-compliant platforms commanding premium placement against ethylene oxide-dependent alternatives facing qualification delays.
Pricing Analysis
The bundled-versus-unbundled service split is decoupling ventilator hardware from long-term maintenance contracts, with software upgrade rights now treated as separately negotiable assets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA extended-use reliability certifications anchoring premium placement. Cost compression in standard-tier platforms is intensifying because regional group purchasing organizations are capturing margin previously retained by original equipment manufacturers. Emergency services segments demonstrate highest price sensitivity due to equipment portability constraints, while transplant center-dense geographies in the U.S. Southeast show lowest sensitivity given ECMO bridging protocol requirements.
Supply Chain Analysis
Precision turbine assemblies for ventilator architectures rest on limited European and Japanese specialty producers, creating geographic concentration across Germany, Switzerland, and Japan. Raw material dependencies span medical-grade aluminum castings, precision bearings, and silicone diaphragms for pneumatic circuits. Single-source vulnerability in turbine component supply exposes manufacturers to trade friction and logistics chokepoint risk. Distribution runs through regional technical service centers anchored in Ohio and California, with hospital procurement committees increasingly demanding localized spare parts inventory commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ARDS market functions as a geographic-arbitrage play where EPA sterilization compliance costs in legacy U.S. facilities run substantially higher than nearshored Mexican manufacturing corridors, creating cost-structure differentiation between domestic and cross-border production strategies.
For Market Incumbents: Deploy backward integration into precision turbine component supply to mitigate single-source vulnerability from European and Japanese suppliers. Incumbent ventilator manufacturers must secure captive supply of medical-grade aluminum castings and silicone diaphragms while accelerating vaporized hydrogen peroxide sterilization qualification to defend against EPA compliance cost escalation. Channel control through regional technical service centers in Ohio and California anchors hospital procurement relationships against emerging turbine-driven specialists. For New Entrants and Emerging Players: Group purchasing organizations represent the most accessible channel partner type for bypassing incumbent OEM procurement relationships. White-space opportunity concentrates in home-based ventilation transition protocols, where CMS reimbursement expansion for prolonged mechanical ventilation creates penetrable demand in Texas and California health systems with integrated discharge planning. Portable ventilator platforms with remote monitoring capabilities offer the clearest go-to-market angle against hospital-centric incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with turbine-driven ventilation specialists possessing compressed gas-independent architectures and established Mexico manufacturing footprints. Long-term viability in this market hinges on regulatory compliance adaptability and biologics pipeline optionality across the analysis window. Acquisition targets should display EPA sterilization alternative qualification progress and closed-loop control software development. The signal to watch is FDA Breakthrough Therapy designation velocity for mesenchymal stromal cell therapies, which would reweight pharmaceutical margin pools against device-centric revenue.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Pathway | Accelerated approval timelines for mesenchymal stromal cell therapies redirect R&D investment toward biologics. |
| Hospital System Partnership | Academic medical center pilot programs for AI-enabled closed-loop ventilation anchor platform adoption in ICU networks. |
| Manufacturing Scale-Up | Nearshoring to Baja California and Chihuahua reduces lead times for EPA-compliant component supply. |
| Software Companion Development | Remote monitoring capabilities unlock CMS reimbursement expansion for prolonged home mechanical ventilation categories. |
| Reimbursement Strategy | CMS prolonged mechanical ventilation codes directly influence hospital procurement decisions for extended-use reliability certifications. |
Research Methodology
Direct dialogue with respiratory therapists, hospital procurement committee members, biomedical engineers, and GPO contracts managers grounded this analysis in operational realities across U.S. ICU networks. Secondary validation drew from FDA device filings, CMS Medicare reimbursement databases, hospital procurement records, and EPA emissions compliance disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis and capital expenditure tracking.
Segment-level outputs across mechanical ventilators, pharmaceuticals, CPAP devices, and oxygen therapy equipment were generated through the projection horizon, with delivery mode, end user, and application dimensions cross-tabulated against regional regulatory clusters. CAGRs were derived from installed base replacement cycles, pipeline maturation timelines, and reimbursement policy trajectory. Forecast inputs incorporated EPA sterilization compliance cost curves and FDA adaptive trial design guidance evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biologics manufacturing scale constraints and respiratory therapist training pipeline expansion. Assumptions reflect current CMS reimbursement codes, EPA emissions thresholds, and FDA breakthrough therapy designation criteria. A small set of named triggers warrants ongoing watch: EPA alternative sterilization method qualification velocity, turbine component supplier consolidation, and adaptive trial design guidance finalization for critical care therapeutics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Emphysema Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Lung Injury Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market