
 Chronic Refractory Cough Treatment Market | 2026-2036
Chronic Refractory Cough Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Refractory Cough Treatment Market Outlook
Specialist-grade biologic and targeted neurokinin-1 receptor antagonist formulations is bifurcating the chronic refractory cough landscape into premium precision-therapy and conventional symptomatic-relief tiers. AstraZeneca plc leverages its respiratory biologics infrastructure to anchor clinical trial networks across North America and Europe. Bellus Health Inc. specializes in P2X3 antagonist development, occupying a narrow but defensible position in peripherally acting antitussive innovation. Merck & Co., Inc. competes through its established immunology and respiratory R&D footprint, extending candidate pipelines into refractory cough mechanisms.
Chronic refractory cough treatment encompasses pharmacological and non-pharmacological interventions targeting persistent cough unresponsive to standard therapy, typically defined as cough duration exceeding eight weeks with inadequate response to proton pump inhibitors, inhaled corticosteroids, and angiotensin-converting enzyme inhibitor discontinuation. The primary purpose centers on symptom suppression, quality-of-life restoration, and reduction of healthcare utilization burden across pulmonology, gastroenterology, and otolaryngology referral pathways. Cough suppressants and P2X3 antagonists lead product-type revenue pools due to their direct neuromodulatory action on cough reflex hypersensitivity, while inhalation delivery modes capture growing share as nebulized and dry-powder formulations improve lung-targeted bioavailability. Hospital and clinic end-user segments concentrate the highest-acuity patient volumes, though home-care channels expand as oral therapies simplify administration protocols.
The FDA breakthrough therapy and fast-track designations shape development economics by compressing regulatory review timelines for novel antitussive mechanisms, while the EMA's adaptive pathways pilot creates parallel European access corridors for refractory cough biologics. Reimbursement coding evolution under CMS and NICE frameworks directly determines prescriber adoption thresholds and patient out-of-pocket exposure for specialty cough therapies. Stakeholders must monitor P2X3 antagonist phase-three readouts and corresponding pricing negotiations to calibrate portfolio prioritization between symptomatic and disease-modifying approaches.
Market Dynamics
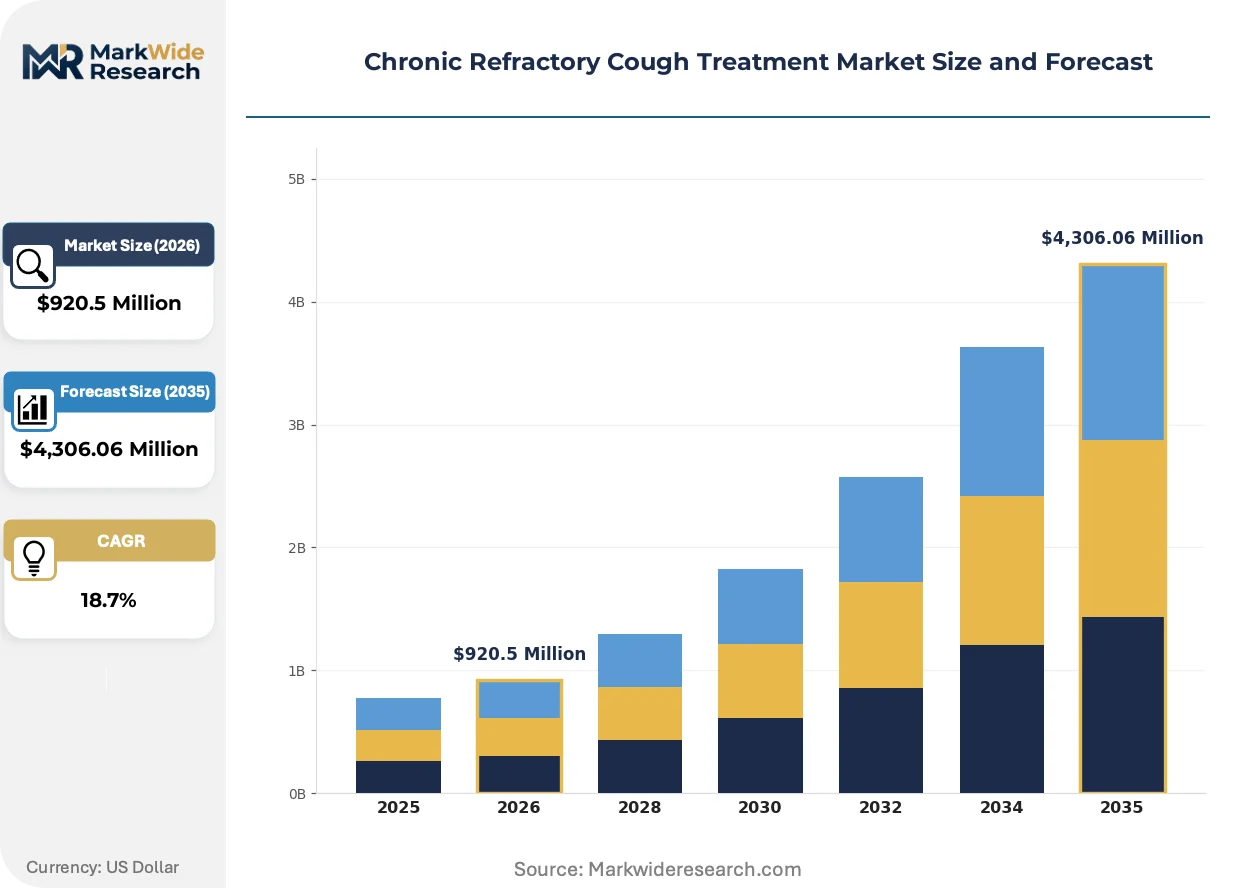
The FDA's breakthrough therapy designation pathway is compressing clinical trial timelines for novel P2X3 antagonists, while pulmonology clinics build dedicated chronic cough centers as standalone profit centers. This dual pressure from accelerated regulatory access and service-line commercialization is restructuring how therapies reach refractory cough patients.
Growth Catalysts
- Specialty Reimbursement Coding:CMS-established evaluation codes for refractory cough assessment in the United States reduce physician administrative burden and expand specialist referral volume.
- EMA Adaptive Pathways:The pilot program creates accelerated European market access corridors for biologic antitussives, compressing time-to-revenue for novel mechanisms.
- P2X3 Antagonist Mechanism Validation:Targeted neuromodulation of cough reflex hypersensitivity offers disease-modifying potential beyond symptomatic suppression, attracting R&D investment from respiratory-focused biopharmaceutical pipelines.
Market Restraints
- Clinical Trial Endpoint Variability:Lack of standardized cough frequency measurement protocols across investigational sites creates regulatory submission risk and extends FDA review cycles.
- Specialist Workforce Concentration:Board-certified pulmonologists and cough clinic physicians cluster in urban academic medical centers, limiting rural and community hospital access to refractory cough diagnosis.
- Generic Opioid Antitussive Substitution:Low-cost codeine and hydrocodone formulations retain formulary preference in cash-constrained health systems despite inferior efficacy profiles.
Strategic Opportunities
- Home-Based Nebulized Delivery:Portable nebulizer technology convergence with connected health platforms enables post-acute care channel expansion beyond hospital and clinic settings.
- Pediatric Indication Extension:Current therapies target adult populations exclusively; juvenile refractory cough represents an untapped regulatory pathway with orphan drug incentive potential.
- Japan's Aging Demographic:METI healthcare infrastructure investment targets chronic respiratory disease management in super-aged municipalities, creating demand concentration for non-opioid antitussive alternatives.
Industry Challenges
- Biomarker Validation Gap:Absence of validated predictive biomarkers for P2X3 antagonist response forces broad patient screening and dilutes per-patient economics.
- Multi-Site Trial Coordination:Cough hypersensitivity heterogeneity requires large, geographically dispersed phase-three programs with complex central adjudication of subjective endpoints.
- Legacy Formulary Contracts:Hospital purchasing agreements with generic manufacturers create switching friction for premium-priced targeted therapies despite superior clinical profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Refractory Cough Treatment Market |
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $4,306.06 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cough Suppressants, Antihistamines, Corticosteroids, Antibiotics Therapy Area: Respiratory Disorders, Allergies, Infections, Neurological Conditions Delivery Mode: Oral, Inhalation, Intranasal, Injectable End User: Clinics, Hospitals, Home Care, Pharmacies |
| Companies Covered | Merck & Co., Inc., Bellus Health Inc., Bayer AG, AstraZeneca plc, GlaxoSmithKline plc, Sanofi S.A., Pfizer Inc., Novartis AG, Shionogi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Refractory Cough Treatment Market Strategic Shifts
Neuromodulatory drug delivery and connected diagnostic platforms are converging to transform chronic cough from a symptom-managed condition to a precision-treated disease state. These shifts are compressing traditional therapeutic categories and redefining stakeholder value capture.
P2X3 receptor antagonist formulations are displacing centrally acting opioid antitussives in pulmonology clinic prescribing patterns. Academic medical centers and specialty cough centers are adopting peripherally acting mechanisms as first-line refractory therapy. This displacement is compressing the addressable market for legacy cough suppressants and forcing generic manufacturers toward commodity pricing.
The FDA's breakthrough therapy designation pathway is accelerating antitussive development timelines by enabling rolling review and more frequent agency interaction. Sponsors gain compressed approval schedules for novel mechanisms demonstrating substantial improvement over available therapy. Respiratory biologics developers are restructuring clinical trial networks to exploit this regulatory tailwind, prioritizing North American site activation.
Integrated cough monitoring devices are reshaping patient selection and outcome verification in specialty clinics. Wearable acoustic sensors and smartphone-based cough counters replace subjective diary entries in clinical practice. This behavioral shift is most visible in United States academic medical centers where quality metrics and value-based contracts demand objective treatment response documentation.
Chronic Refractory Cough Treatment Market Segmentation
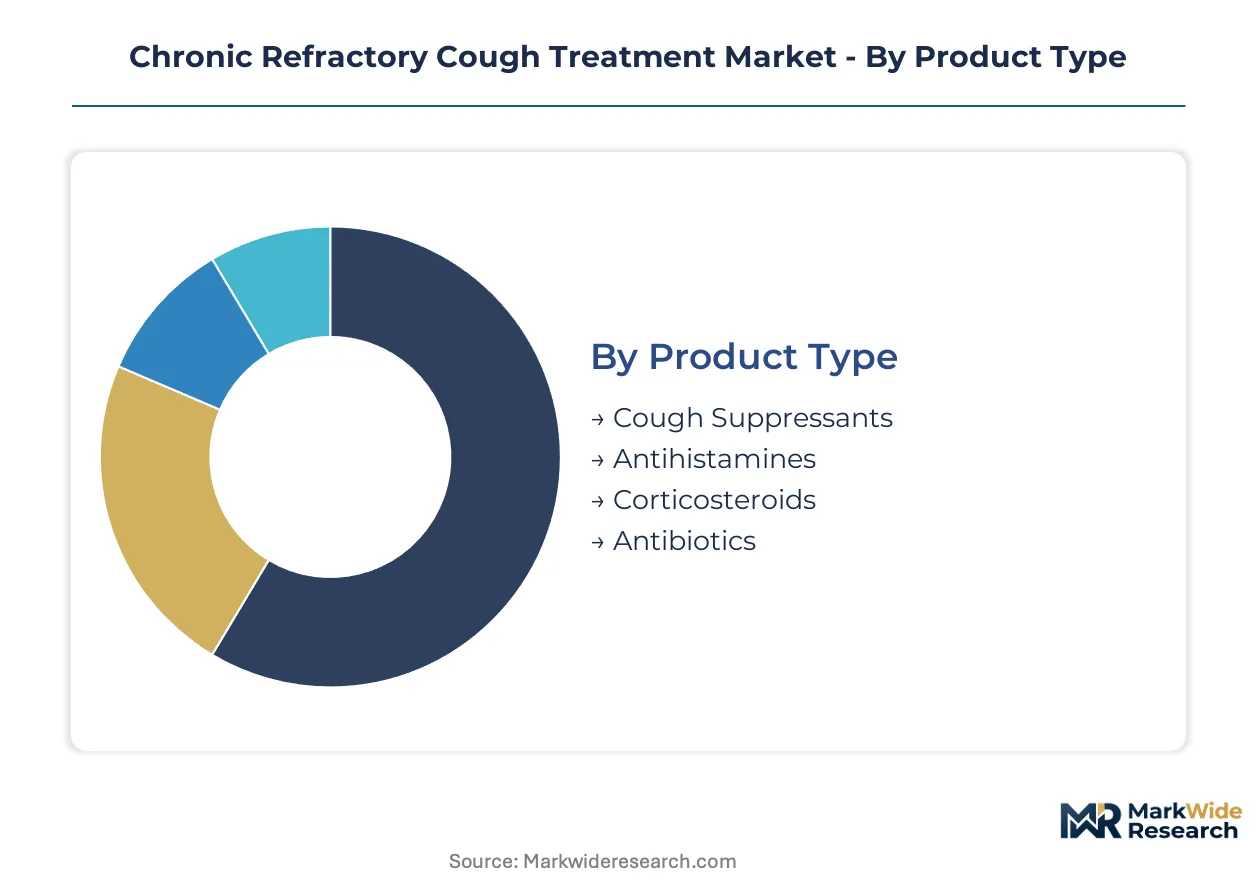
Segmentation in chronic refractory cough treatment reveals how therapeutic innovation concentrates value capture across mechanism classes and care settings. Understanding these divisions exposes where P2X3 antagonists and neuromodulatory platforms displace legacy symptomatic options.
Product Type:
Margin pools concentrate in neuromodulatory agents with disease-modifying claims, while commoditized symptomatic therapies compete on formulary access and generic substitution economics.
- Cough Suppressants:Centrally acting opioid and non-opioid formulations dampen medullary cough center activity. Demand clusters in United States pulmonology clinics where CMS reimbursement codes for refractory cough evaluation reduce prescribing friction for premium mechanisms.
- Antihistamines:Histamine receptor antagonists address cough of allergic etiology through peripheral and central pathways. European prescribing patterns favor these agents in community settings where EMA adaptive pathway access for novel biologics remains limited.
- Corticosteroids:Inhaled and systemic anti-inflammatory agents target eosinophilic airway inflammation.
- Antibiotics:Antimicrobial therapy addresses post-infectious cough persistence and bacterial superinfection.
The dominant share belongs to Cough Suppressants, while P2X3 antagonist platforms within this segment are climbing the fastest toward premium positioning.
Therapy Area:
Application intensity varies sharply by underlying pathology, with respiratory-focused mechanisms commanding development investment and neurological targets representing emerging frontier science.
- Respiratory Disorders:Asthma, chronic obstructive pulmonary disease, and interstitial lung disease-associated cough drive specialist referral volume. United States academic medical centers concentrate the highest-acuity patients for mechanism-driven trials.
- Neurological Conditions:Vagal neuropathy and central sensitization syndromes represent mechanistically distinct refractory cough etiologies. Japanese super-aged municipalities generate concentrated demand as METI infrastructure investment targets chronic respiratory disease management.
- Allergies:Allergic rhinitis and upper airway cough syndrome respond to antihistamine and intranasal corticosteroid protocols.
- Infections:Post-viral cough and chronic bronchitis require antimicrobial or anti-inflammatory intervention.
Respiratory Disorders anchor clinical trial recruitment and prescriber education investment, though Neurological Conditions is expanding most quickly as P2X3 mechanism validation advances.
Delivery Mode:
Route selection determines bioavailability profiles, patient adherence economics, and the feasibility of home-based administration outside specialist supervision.
- Oral:Tablet and liquid formulations dominate outpatient prescribing for chronic maintenance therapy. Pharmacies in United States retail networks capture volume as simplified administration protocols expand patient eligibility beyond hospital-based initiation.
- Inhalation:Nebulized and dry-powder delivery achieves lung-targeted drug deposition with reduced systemic exposure. Connected nebulizer platforms in home-care channels enable post-acute monitoring and value-based outcome documentation.
- Intranasal:Nasal spray delivery targets upper airway cough reflex modulation.
- Injectable:Parenteral administration reserves for acute exacerbation management and biologic loading doses.
Oral delivery retains volume leadership through pharmacy channel convenience, while Inhalation is gaining share fastest on connected device integration and pulmonologist preference for targeted deposition.
End User:
Care setting determines patient acuity, reimbursement complexity, and the balance between specialist-directed initiation and maintenance therapy decentralization.
- Clinics:Dedicated cough centers and pulmonology practices concentrate diagnostic expertise and mechanism-specific prescribing. United States specialist referral networks mature around CMS-established evaluation codes that reduce administrative burden.
- Home Care:Post-acute and long-term administration shifts to residential settings as oral and nebulized therapies simplify protocols. Portable device convergence with remote monitoring platforms enables outcome verification without clinic visits.
- Hospitals:Inpatient units manage acute exacerbations and complex diagnostic workups.
- Pharmacies:Retail and specialty dispensing channels handle maintenance prescription fulfillment.
Clinics command the highest-value patient encounters through specialist access, while Home Care is expanding most quickly on device-enabled decentralization and payer pressure to reduce facility-based costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in the United States, where specialist referral networks and reimbursement infrastructure mature fastest. European markets follow with adaptive regulatory pathways, while Japan's aging demographics drive non-opioid antitussive demand.
United States
Pulmonology clinics expand dedicated cough centers as standalone profit centers under CMS-established evaluation codes. FDA breakthrough therapy designations compress development timelines for novel P2X3 antagonists. Academic medical centers in Boston, New York, and California anchor phase-three trial recruitment and prescriber education networks.
Germany
Respiratory biologics infrastructure attracts multinational trial site activation and manufacturing investment. EMA adaptive pathways pilot creates accelerated market access corridors for peripherally acting antitussives. The Rhine-Ruhr and Bavarian pharmaceutical clusters concentrate cough hypersensitivity research and specialist physician training programs.
Japan
METI healthcare infrastructure investment targets chronic respiratory disease management in super-aged municipalities. PMDA consultation procedures align with FDA breakthrough designations for synchronized development timelines. The Kanto region around Tokyo hosts the highest density of cough specialty clinics and geriatric pulmonology services.
United Kingdom
NICE technology appraisal frameworks determine prescriber adoption thresholds for premium-priced targeted therapies. NHS England specialist commissioning policies concentrate refractory cough diagnosis in designated respiratory centers. The Oxford-Cambridge-London corridor dominates translational research and early-phase clinical investigation.
Australia
TGA priority review pathways align with FDA and EMA accelerated mechanisms for novel antitussive candidates. PBS reimbursement negotiations shape patient out-of-pocket exposure for specialty cough therapies. Sydney and Melbourne academic hospitals lead Southern Hemisphere trial enrollment and regional prescriber network development.
Chronic Refractory Cough Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the chronic refractory cough treatment landscape. Large-cap respiratory biopharmaceuticals command clinical trial infrastructure and regulatory engagement capacity, while mid-cap neuromodulation specialists occupy mechanism-specific innovation niches. The market structure tiers into biologics developers, P2X3 antagonist specialists, and legacy symptomatic therapy manufacturers. Competitive moves center on phase-three readout timing and specialty reimbursement code capture.
Among large-cap respiratory developers, AstraZeneca plc and Merck & Co., Inc. represent the biologics-led archetype with established immunology and respiratory R&D footprints. Bellus Health Inc. exemplifies the P2X3 antagonist specialist model, occupying a narrow but defensible position in peripherally acting antitussive innovation. These three companies anchor distinct strategic vectors—platform breadth versus mechanism depth—shaping how novel therapies reach specialist prescriber networks.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bellus Health Inc. |
| Bayer AG |
| AstraZeneca plc |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Pfizer Inc. |
| Novartis AG |
| Shionogi |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between P2X3 antagonist developers and North American academic medical centers lock in supply access for phase-three trial materials while anchoring price visibility for neuromodulatory therapies against generic opioid substitution. These contracts tie reimbursement code capture to volume commitments, compressing margin variability for sponsors navigating FDA breakthrough pathway acceleration.
Pricing Analysis
CMS-established evaluation codes dictate the pricing tier structure for refractory cough assessment and treatment initiation in United States specialist clinics. Three-tier pricing structure across premium biologic, standard targeted, and economy generic levels segments patients by insurance coverage depth and prior authorization burden. Price differentiation hinges on FDA breakthrough designation status and pulmonologist prescribing authority within academic medical center networks. Cost compression in the generic opioid tier intensifies because hospital formulary contracts prioritize low acquisition cost over clinical efficacy profiles. Cash-constrained health systems exhibit highest price sensitivity, while insured patients accessing dedicated cough centers demonstrate lowest sensitivity due to reduced out-of-pocket exposure under specialty reimbursement frameworks.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes from API manufacturers in India and China to formulation facilities in the United States and Germany elevate inbound logistics costs for active pharmaceutical ingredients. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, while final dosage form manufacturing clusters in the United States, Germany, and Japan for regulatory proximity advantages. Raw material dependencies span P2X3 receptor antagonist chemical precursors, specialized inhalation device components, and biologic excipient grades. Single-source vulnerability for P2X3 antagonist intermediates sourced from select Indian contract manufacturers presents concentration risk. Distribution runs through specialty pharmacy networks and hospital outpatient infusion centers for biologic therapies, with retail pharmacy channels handling oral maintenance prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected cough monitoring platforms and remote patient management services attach recurring revenue layers expanding faster than pharmaceutical hardware alone, transforming chronic refractory cough from episodic treatment into continuous care relationships.
For Market Incumbents: Compound defensive moats around P2X3 antagonist mechanism leadership through backward integration into diagnostic biomarker development and captive control over connected device supply chains. Deepen vertical integration into nebulizer technology manufacturing to secure home-care channel expansion against generic substitution pressure. Prioritize FDA breakthrough designation maintenance and CMS reimbursement code expansion to preserve pricing power against emerging neuromodulatory competitors. For New Entrants and Emerging Players: Lead with pediatric indication development as the most penetrable regulatory pathway, exploiting orphan drug incentive structures and absent incumbent positioning in juvenile refractory cough. Target Japan's super-aged municipalities where METI infrastructure investment concentrates demand for non-opioid alternatives and pulmonologist density lags prescription volume. Deploy pulmonologist-direct educational detailing as the primary go-to-market angle, bypassing hospital formulary gatekeepers through specialist prescriber relationships. For Investors and Strategic Acquirers: Mid-cap neuromodulation specialists with validated P2X3 antagonist phase-two data represent the highest-conviction acquisition target archetype for portfolio exposure to disease-modifying cough mechanisms. Frame long-term viability around five-to-ten year windows for mechanism validation and reimbursement infrastructure maturation rather than near-term revenue capture. Monitor phase-three readout timing and corresponding pricing negotiation outcomes as the critical inflection signal for portfolio reallocation between symptomatic and disease-modifying therapeutic approaches.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough pathway compression accelerates P2X3 antagonist approval timelines for refractory cough indications. |
| Regulatory Approval Pathway | EMA adaptive pathways pilot creates parallel European access corridors for neuromodulatory antitussive candidates. |
| Reimbursement Strategy | CMS evaluation code capture determines prescriber adoption thresholds and patient out-of-pocket exposure levels. |
| Manufacturing Scale-Up | Connected nebulizer platform production expansion enables home-care channel penetration beyond hospital settings. |
| Pipeline Diversification | Pediatric indication extension opens orphan drug incentive pathways in currently untapped juvenile populations. |
Study Parameters
Operator-level perspectives from pulmonology clinic directors, formulary access specialists, regulatory affairs leads, and hospital procurement managers anchored the qualitative base for this analysis. Primary interviews with cough center physicians and payer strategy executives combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS reimbursement databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Sensitivity analysis across regulatory approval probability scenarios and reimbursement code adoption curves shaped the analytical framework for value projections across the modeling period. Segmentation dimensions modeled include treatment mechanism class, delivery mode, therapy area etiology, end-user care setting, and regional regulatory cluster. CAGRs derived from patient prevalence trends, prescriber adoption curves, and pricing evolution assumptions. Forecast inputs incorporated P2X3 antagonist pipeline progression milestones and connected device penetration rates.
The analysis sits within stated boundaries; outcomes outside FDA breakthrough designation maintenance, CMS reimbursement code expansion, or EMA adaptive pathway continuity would require recalibration. Forecasts reflect documented assumptions regarding mechanism validation timelines and specialist workforce distribution. Pipeline failure risk, generic substitution acceleration, and biomarker validation gaps represent specific factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Lung Injury Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market