
 Global Neonatal Intensive Care Respiratory Devices Market | 2026-2036
Global Neonatal Intensive Care Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neonatal Intensive Care Respiratory Devices Market Foresight
Hospital purchasing for neonatal units is shifting toward integrated respiratory platforms that combine ventilation with continuous monitoring capabilities. Koninklijke Philips N.V. leverages its diagnostic imaging heritage to bundle respiratory devices with patient monitoring ecosystems. GE HealthCare anchors its position through embedded analytics software that reduces alarm fatigue in intensive care settings. Drägerwerk AG & Co. KGaA specializes in closed-loop ventilation algorithms that automate oxygen titration for preterm infants.
Neonatal intensive care respiratory devices encompass mechanical ventilators, continuous positive airway pressure systems, oxygen delivery apparatus, and humidification equipment engineered for patients below 44 weeks gestational age, typically operating at tidal volumes under 20 mL and pressures below 30 cm H₂O. These systems sustain pulmonary function in premature neonates with surfactant-deficient lungs, preventing ventilator-induced lung injury while maintaining adequate gas exchange. CPAP devices command durable installed bases across mature markets, though high-frequency ventilation technology captures expanding preference for severe respiratory distress cases where conventional modes risk barotrauma. Bubble CPAP dominates resource-limited settings due to lower capital requirements and simplified maintenance protocols. Home care represents the fastest-growing end user channel as early discharge protocols and portable oxygen concentrators enable sub-acute management outside institutional walls.
FDA premarket notification requirements under 21 CFR 892 classify neonatal ventilators as Class II devices with substantial equivalence benchmarks, while EMA Medical Device Regulation mandates clinical evidence for respiratory support systems marketed across EU member states. ISO 80601-2-80 establishes particular standards for emergency and transport ventilators, including neonatal-specific alarm systems and breathing circuit integrity tests that manufacturers must satisfy for international market access. Stakeholders should monitor evolving cybersecurity guidance from FDA and notified bodies as connected respiratory platforms proliferate in networked hospital environments.
Market Dynamics
Neonatal respiratory device manufacturers face intensifying pressure from FDA and EMA safety protocols that mandate stricter alarm system validation and breathing circuit integrity testing, compressing development timelines while elevating compliance costs across product portfolios.
Growth Catalysts
- EMA Medical Device Regulation:The MDR's clinical evidence requirements for respiratory support systems create competitive moats for established manufacturers with robust documentation capabilities, filtering out marginal entrants.
- Home care end-use channel:Portable oxygen concentrators and early discharge protocols enable sub-acute management outside institutional walls, expanding addressable patient populations beyond traditional NICU boundaries.
- Bubble CPAP technology:Lower capital requirements and simplified maintenance protocols drive procurement in resource-limited settings across India and sub-Saharan Africa where infrastructure constraints limit conventional ventilator deployment.
Market Restraints
- Input cost volatility:Medical-grade polymers and precision sensors face supply concentration from German and Japanese specialty chemical suppliers, exposing margins to petrochemical price swings.
- Technical limitation:Tidal volumes below 2 mL for extremely preterm infants challenge conventional flow sensor accuracy, constraining device applicability at the lowest gestational ages.
- Regulatory friction:ISO 80601-2-80's neonatal-specific alarm testing protocols extend certification timelines by 8-14 months versus adult-equivalent devices, delaying revenue recognition.
Strategic Opportunities
- China healthcare infrastructure expansion:Provincial hospital upgrades in Sichuan and Guangdong create procurement windows for integrated respiratory-monitoring platforms as NICU bed capacity doubles through 2030.
- Cybersecurity guidance evolution:FDA's draft guidance on connected device security creates first-mover advantages for manufacturers embedding encryption and access controls ahead of mandatory requirements.
- Technology convergence:Closed-loop ventilation algorithms combined with continuous pulse oximetry feedback enable automated oxygen titration, reducing nursing workload and hypoxia episodes simultaneously.
Industry Challenges
- Specialized clinical engineering talent:Neonatal ventilator maintenance requires expertise in low-volume pneumatic systems that conventional biomedical technicians rarely possess, creating service coverage gaps.
- Legacy system integration:Hospital information systems from the 2010s lack interoperability protocols for modern respiratory device data streams, forcing costly middleware development or manual documentation workarounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neonatal Intensive Care Respiratory Devices Market |
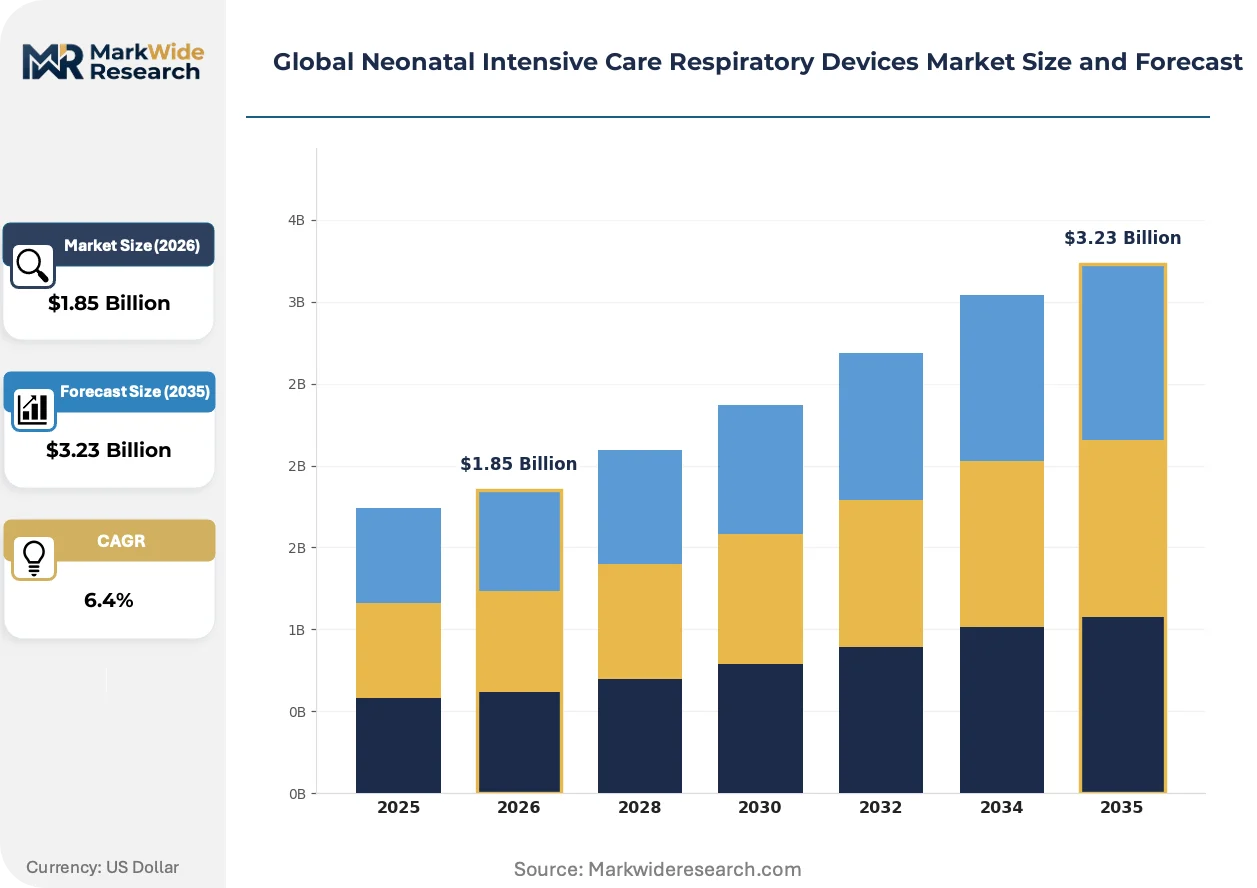
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, CPAP Devices, Oxygen Concentrators, Humidifiers Technology: High-Frequency Ventilation, Bubble CPAP, Liquid Ventilation, Conventional Ventilation End User: Hospitals, Neonatal Units, Specialized Clinics, Home Care Application: Respiratory Distress, Bronchopulmonary Dysplasia, Apnea, Congenital Disorders |
| Companies Covered | Koninklijke Philips N.V., GE HealthCare, Drägerwerk AG & Co. KGaA, Medtronic plc, Fisher & Paykel Healthcare Limited, Hamilton Medical AG, Getinge AB, Vyaire Medical, Inspiration Healthcare Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neonatal Intensive Care Respiratory Devices Market Shifts & Advancements
Neonatal respiratory care is undergoing fundamental restructuring as automation, connectivity mandates, and care site migration reshape equipment specifications and commercial relationships across manufacturer portfolios.
High-frequency oscillatory ventilation is rewriting clinical protocols for severe respiratory distress syndrome. Level III NICUs in the United States and Germany are adopting these systems at accelerating rates for infants failing conventional modes. The technology is compressing average ventilation duration and reducing barotrauma incidence, shifting purchasing criteria toward platforms offering multiple modalities.
REACH restrictions on persistent organic pollutants in medical device plastics are forcing material substitutions across European supply chains. Manufacturers must validate alternative polymers for biocompatibility and sterilization resilience under accelerated aging protocols. Neonatal breathing circuits and humidification chambers face the most immediate reformulation pressure given direct patient contact requirements.
Subscription-based equipment access is displacing capital purchase models in North American health systems facing constrained budgets. Third-party asset management firms now acquire device fleets and charge per-patient-day fees, transferring utilization risk from hospitals to vendors. This arrangement concentrates most visibly in multi-hospital networks in Texas and Florida seeking balance sheet flexibility.
Global Neonatal Intensive Care Respiratory Devices Market Segmentation
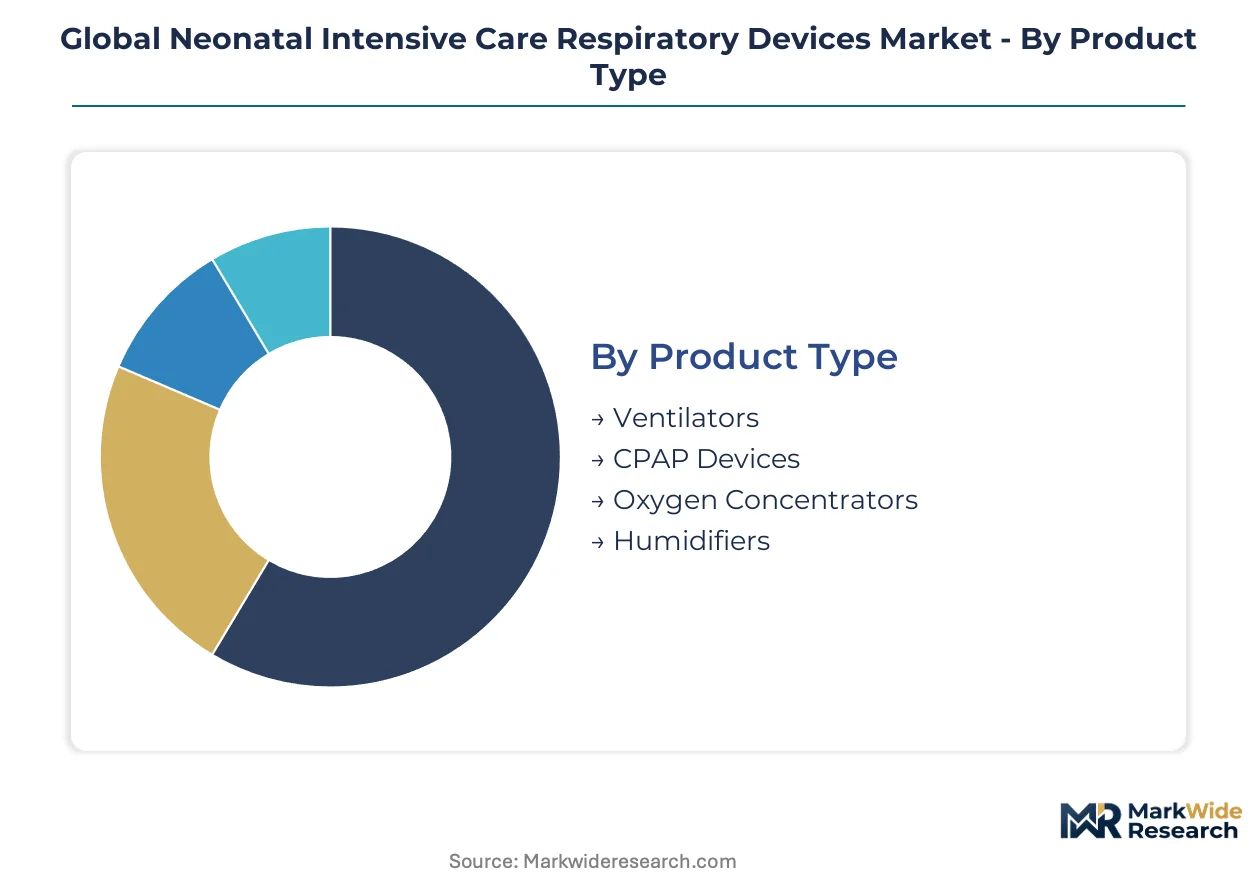
Neonatal respiratory device purchasing splits sharply between high-acuity hospital platforms and portable home systems. Each segmentation dimension reveals distinct margin profiles, certification burdens, and service intensity requirements that reshape manufacturer portfolio priorities.
Product Type:
Ventilators command premium pricing tiers while CPAP devices anchor volume deployment across cost-sensitive procurement environments.
- Ventilators:Mechanical systems deliver precise tidal volumes below 20 mL with pressure controls under 30 cm H₂O. Demand concentrates in Level III NICUs across the United States and Germany where severe respiratory distress cases require invasive support modalities.
- CPAP Devices:Continuous positive airway pressure systems maintain spontaneous breathing with applied pressure support. Procurement in India and sub-Saharan Africa favors bubble CPAP configurations for their minimal capital outlay and field-serviceable pneumatic circuits.
- Oxygen Concentrators:Portable units enabling sub-acute management outside institutional walls are gaining procurement traction through early discharge protocols.
- Humidifiers:Heated breathing circuit accessories prevent mucosal drying during prolonged ventilation runs.
Mature deployment sits with ventilators. Newer deployment is concentrated in oxygen concentrators.
Technology:
High-frequency modalities capture severe-case premium pricing while bubble systems penetrate infrastructure-constrained settings.
- High-Frequency Ventilation:Oscillatory systems operate at respiratory rates exceeding 300 breaths per minute with tidal volumes below dead space. United States and German Level III NICUs are adopting these platforms fastest for infants failing conventional modes, reducing barotrauma incidence.
- Bubble CPAP:Immersion-based pressure generation eliminates electronic complexity. Resource-limited settings across India deploy these systems where biomedical engineering capacity cannot sustain conventional ventilator maintenance protocols.
- Liquid Ventilation:Perfluorocarbon-based total liquid ventilation remains investigational with limited commercial availability.
- Conventional Ventilation:Time-cycled, pressure-limited systems constitute the installed base majority across mature markets.
Conventional ventilation retains the largest installed base. High-frequency ventilation is climbing the fastest among active procurement categories.
End User:
Hospital networks concentrate capital expenditure while home care channels expand addressable patient populations beyond traditional boundaries.
- Hospitals:Acute care institutions purchase integrated respiratory-monitoring platforms with embedded analytics software. Procurement in China's Sichuan and Guangdong provinces is accelerating as provincial hospital upgrades double NICU bed capacity.
- Neonatal Units:Dedicated Level II and III facilities within larger hospital complexes specify devices with closed-loop oxygen titration algorithms.
- Specialized Clinics:Private neonatal intensive care centers in Brazil and Mexico operate smaller device fleets with multi-modality flexibility requirements.
- Home Care:Portable oxygen concentrators and monitoring peripherals enable early discharge protocols. Texas and Florida multi-hospital networks are pioneering subscription-based equipment access models that transfer utilization risk to third-party asset managers.
Hospital procurement dominates capital flows. Home care represents the steepest expansion trajectory for patient-day volume.
Application:
Respiratory distress syndrome anchors clinical protocols while apnea management drives monitoring technology convergence.
- Respiratory Distress:Surfactant-deficient lung conditions in preterm infants below 32 weeks gestational age require immediate ventilatory support. Device specifications prioritize gentle ventilation modes that prevent volutrauma in fragile pulmonary tissue.
- Bronchopulmonary Dysplasia:Chronic lung disease following prolonged ventilation creates demand for weaning protocols and non-invasive transition support.
- Apnea:Central and obstructive apnea events in premature neonates necessitate continuous cardiorespiratory monitoring with automated stimulation backup.
- Congenital Disorders:Diaphragmatic hernia and pulmonary hypoplasia cases require specialized high-frequency ventilation capacity from initial resuscitation through surgical correction.
Respiratory distress applications command the largest device allocation. Apnea management is gaining share fastest through monitoring-ventilation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States, while procurement accelerates fastest across China and India as NICU infrastructure expands. Consumption patterns diverge sharply between mature markets adopting high-frequency ventilation and emerging economies deploying bubble CPAP systems.
United States
Level III NICUs in Texas and Florida drive demand for integrated respiratory-monitoring platforms with embedded analytics. FDA premarket notification requirements under 21 CFR 892 enforce substantial equivalence benchmarks for Class II ventilator devices. The Southeast hospital networks pioneer subscription-based equipment access models that transfer utilization risk to third-party asset managers.
Germany
EMA Medical Device Regulation clinical evidence requirements filter out marginal entrants while favoring established manufacturers with robust documentation capabilities. REACH restrictions on persistent organic pollutants force material substitutions across breathing circuit supply chains. The Baden-Württemberg industrial corridor anchors precision sensor production for low-volume pneumatic systems.
China
Provincial hospital upgrades in Sichuan and Guangdong double NICU bed capacity through 2030, creating procurement windows for ventilator fleets. NMPA certification protocols align increasingly with ISO 80601-2-80 standards for neonatal-specific alarm validation. The Yangtze River Delta cluster concentrates domestic manufacturing of portable oxygen concentrators for home care channels.
India
Bubble CPAP deployment dominates resource-limited settings where biomedical engineering capacity cannot sustain conventional ventilator maintenance. CDSCO import regulations and local manufacturing incentives under PLI schemes reshape procurement toward domestically assembled devices. The Maharashtra hospital network in Mumbai-Pune corridor scales NICU capacity fastest among state-level systems.
Brazil
Private neonatal intensive care centers in São Paulo and Rio de Janeiro operate smaller device fleets with multi-modality flexibility requirements. ANVISA regulatory harmonization with MDR frameworks extends certification timelines for European-imported equipment. The Southeast region concentrates purchasing decisions for respiratory platforms across the national private hospital network.
Global Neonatal Intensive Care Respiratory Devices Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while mid-scale specialists concentrate on modality-specific devices. The vendor base stratifies across three tiers: diversified medical technology conglomerates with diagnostic imaging heritage, pure-play respiratory device manufacturers with closed-loop algorithm expertise, and regional assemblers serving price-sensitive procurement channels. Two strategic archetypes dominate competitive positioning: ecosystem bundlers combining ventilation with patient monitoring, and automation-focused developers of oxygen titration algorithms. M&A activity targets telemetry and analytics capabilities, while geographic expansion concentrates on provincial hospital networks in Sichuan and Guangdong.
Among diversified technology conglomerates, Koninklijke Philips N.V. and GE HealthCare occupy positions exemplifying ecosystem bundling strategies that leverage diagnostic imaging heritage. Drägerwerk AG & Co. KGaA represents the automation-specialist archetype through its focus on closed-loop ventilation algorithms. These three entities anchor the premium tier where regulatory documentation capabilities and embedded software analytics create competitive moats against emerging market entrants.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| GE HealthCare |
| Drägerwerk AG & Co. KGaA |
| Medtronic plc |
| Fisher & Paykel Healthcare Limited |
| Hamilton Medical AG |
| Getinge AB |
| Vyaire Medical |
| Inspiration Healthcare Group plc |
| Others |
Supply & Pricing Matrix
Medical-grade polymer feedstocks from German and Japanese specialty chemical suppliers cascade through three distinct pricing tiers before reaching hospital procurement committees, with concentration at the resin-manufacturing stage amplifying margin capture upstream while squeezing device assemblers facing CDSCO and NMPA compliance investments.
Pricing Analysis
Cost-down pressure on economy-tier bubble CPAP systems accelerates because Maharashtra state hospitals and sub-Saharan African ministries of health prioritize capital minimization over feature depth. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared closed-loop ventilators from CE-marked conventional systems from non-certified field-serviceable units. ISO 80601-2-80 alarm validation costs widen the premium-economy gap. Public-sector buyers in India exhibit highest price sensitivity; Level III NICUs in Texas and Germany demonstrate lowest.
Supply Chain Analysis
Ocean freight cost volatility from Baden-Württemberg sensor manufacturers to Yangtze River Delta assembly plants compresses landed margins on precision flow sensors. Supply concentrates in Germany for pneumatic components, Japan for medical-grade polymers, and China for portable oxygen concentrator final assembly. Raw material dependencies span perfluorocarbon formulations, platinum resistance temperature detectors, and silicone breathing circuit tubing. Single-source vulnerability sits with German specialty chemical suppliers for biocompatible polymer feedstocks. Distribution runs through third-party asset management firms in North American multi-hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Medical Device Regulation clinical evidence requirements erect compliance moats that filter marginal entrants while rewarding established manufacturers with robust documentation capabilities.
For Market Incumbents: Hedge against pricing erosion in mature ventilator segments by embedding closed-loop oxygen titration software that commands subscription revenue streams. Fortify supply security through backward integration into precision sensor production or long-term offtake agreements with Baden-Württemberg suppliers. Acquire telemetry analytics capabilities to defend against ecosystem bundlers.
For New Entrants and Emerging Players: Capture white-space opportunity in bubble CPAP aftermarket service networks across India's Maharashtra and sub-Saharan Africa where biomedical engineering scarcity creates coverage gaps. Target provincial hospital upgrade windows in Sichuan and Guangdong before integrated platform vendors lock procurement relationships. Lead with field-serviceable pneumatic simplicity rather than electronic complexity.
For Investors and Strategic Acquirers: NMPA alignment with ISO 80601-2-80 standards is the leading indicator that domestic Chinese manufacturers will achieve export competitiveness within the analysis window. Position for platform consolidation plays targeting telemetry and analytics specialists. Monitor FDA draft cybersecurity guidance publication as inflection signal for connected device security premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Evidence Investment | EMA documentation capabilities filter competitors and lock hospital procurement relationships across EU member states. |
| Cybersecurity Pre-Compliance | FDA draft guidance embedding creates first-mover advantage before mandatory connected device security requirements. |
| Bubble CPAP Service Network | Field-engineering coverage gaps in India and sub-Saharan Africa enable recurring revenue capture outside equipment sales. |
| Closed-Loop Algorithm Development | Automated oxygen titration reduces nursing workload while differentiating platforms in Level III NICU procurement. |
| Provincial Hospital Partnership | Sichuan and Guangdong NICU bed expansion creates fleet installation windows before competitor platform consolidation. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineering directors, and GPO contracts managers underwrites the qualitative findings. Primary fieldwork with neonatal intensive care clinicians and regulatory affairs specialists at notified bodies combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, and NMPA registration records. Bottom-up device shipment analysis triangulates against top-down healthcare infrastructure spending data from provincial hospital upgrade disclosures.
Rate-of-change decomposition across product type, technology modality, end-user channel, and application severity segments structures the analytical framework. CAGRs derive from installed base evolution modeling and replacement cycle analysis rather than extrapolation. Forecast inputs incorporate REACH material substitution timelines and PLI scheme domestic manufacturing incentives without year-specific anchoring.
The model holds under stable regulatory harmonization trajectories; deviation in FDA cybersecurity rulemaking or EMA MDR enforcement intensity would shift competitive positioning. Forecasts reflect assumptions about provincial hospital upgrade pacing and premature birth rate trends. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Emphysema Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Healthcare-Associated Pneumonia Market