
 Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market | 2026-2036
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market Foresight
Modular ventilator configurations is decoupling hardware from software subscriptions across procurement channels. Medtronic plc leverages its integrated critical care portfolio to sustain hospital loyalty in South African metropolitan centers. Getinge AB anchors its regional position through specialized extracorporeal membrane oxygenation system distribution. Koninklijke Philips N.V. competes on connected monitoring ecosystems that extend service revenue beyond initial device placement.
Acute Respiratory Distress Syndrome constitutes a life-threatening inflammatory lung injury characterized by non-cardiogenic pulmonary edema, hypoxemic respiratory failure with PaO2/FiO2 ratios below 300 mmHg, and bilateral radiographic opacities requiring mechanical ventilation or advanced oxygenation support. The condition demands rapid intervention through positive pressure ventilation, prone positioning, and pharmacological management to restore gas exchange and prevent multi-organ dysfunction. Ventilators and monitoring devices command the largest installed base across Middle East and Africa facilities, though ECMO technology represents the fastest-expanding segment as referral centers build surgical perfusion capabilities. Drug therapies occupy narrower margin pools due to generic competition, while high-flow oxygen therapy systems penetrate intermediate care settings between invasive ventilation and conventional oxygen delivery.
South Africa's national pharmaceutical regulator, Saudi Arabia's SFDA, and the UAE's MOHAP collectively enforce medical device registration, clinical evidence requirements, and post-market surveillance for ARDS equipment distributed across the region. These frameworks elevate compliance costs for manufacturers while creating differentiated access tiers between regulatory harmonization leaders and markets with fragmented approval pathways. Stakeholders must monitor which Gulf health systems advance toward centralized procurement and whether East African hospital networks develop sufficient critical care volume to justify dedicated ARDS device distribution.
Market Dynamics
Modular ventilator architectures are decoupling hardware procurement from software subscription models across Middle East and Africa hospital systems. This structural shift is compressing capital expenditure cycles while extending vendor revenue streams through recurring service contracts.
Growth Catalysts
- Critical care infrastructure investment:Gulf Cooperation Council states are expanding intensive care unit capacity in tertiary hospitals. Government health budgets in Saudi Arabia and the UAE prioritize mechanical ventilation equipment procurement.
- SFDA harmonization initiatives:Saudi Arabia's medical device regulatory framework is streamlining approval pathways for ARDS equipment. This reduces time-to-market for ventilator and ECMO manufacturers targeting the Gulf region.
- ECMO capability building:Regional referral centers are establishing surgical perfusion programs. Extracorporeal membrane oxygenation systems address refractory hypoxemia cases that fail conventional ventilation.
Market Restraints
- Input cost volatility:Semiconductor shortages and polymer supply disruptions inflate ventilator manufacturing costs. Manufacturers absorb margin compression or pass through pricing to constrained hospital budgets.
- Supply concentration risk:High-flow oxygen therapy systems depend on concentrated compressor module suppliers in East Asia. Middle East and Africa distributors face extended lead times and currency exposure.
- Technical limitation:Prone positioning automation remains underdeveloped for resource-limited settings. Manual repositioning protocols strain nursing staff and limit intervention consistency.
Strategic Opportunities
- East African hospital network development:Kenya and Ethiopia are constructing critical care wings in national referral hospitals. These facilities lack established ARDS device distribution relationships.
- Connected monitoring convergence:Integration of ventilator data streams with electronic health record systems enables predictive analytics. Philips and regional IT vendors are co-developing interoperability layers.
- MOHAP centralized procurement pilots:The UAE Ministry of Health and Prevention is testing consolidated ventilator purchasing across emirate-level health systems. Winning vendors secure multi-year volume commitments.
Industry Challenges
- Perfusionist talent scarcity:ECMO program expansion outpaces trained surgical perfusion specialist availability. Regional training partnerships with European centers address pipeline gaps.
- Post-market surveillance compliance:South Africa's national pharmaceutical regulator intensifies adverse event reporting requirements. Device distributors must maintain localized quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market |
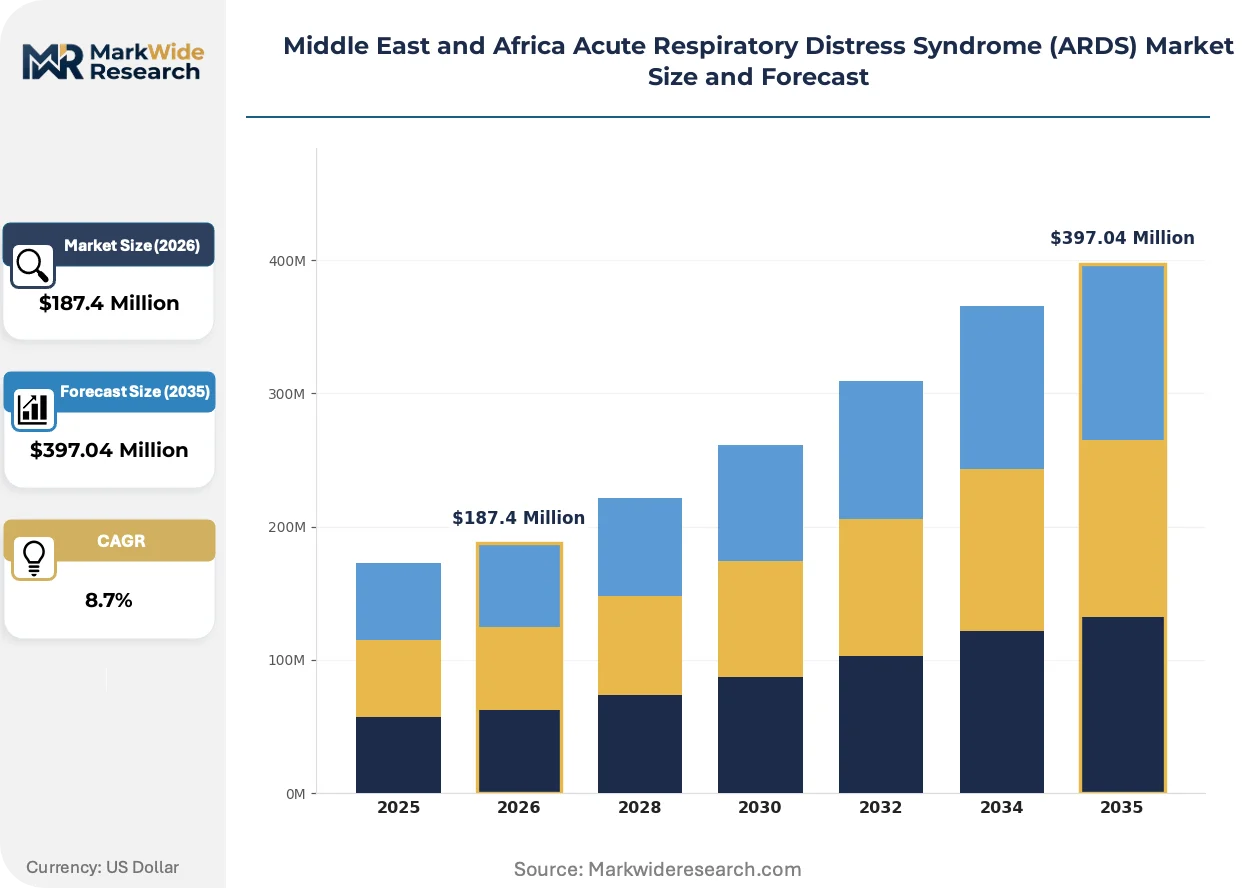
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Oxygen Therapy Equipment, Monitoring Devices, Drug Therapies End User: Hospitals, Clinics, Home Care, Research Laboratories Delivery Mode: Inhalation, IV Administration, Oral Delivery, Nasal Administration Technology: Non-Invasive Ventilation, High-Flow Oxygen Therapy, ECMO, Bi-level Positive Airway Pressure |
| Companies Covered | Johnson & Johnson Services Inc., GlaxoSmithKline plc, Medtronic plc, Getinge AB, Boehringer Ingelheim International GmbH, Koninklijke Philips N.V., Novartis AG, Dräger Safety AG & Co. KGaA, GE Healthcare, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market Shifts & Advancements
Software-defined ventilation platforms are redefining how Middle East and Africa hospitals acquire and operate mechanical respiratory support. Three convergent developments are compressing replacement cycles and reshaping vendor relationships.
Adaptive lung-protective ventilation algorithms are electrifying clinical decision support in intensive care units. These systems automate tidal volume titration and driving pressure optimization based on real-time respiratory mechanics. Saudi Arabian tertiary hospitals are piloting these platforms in COVID-19 legacy ICUs. The technology is compressing demand for conventional volume-control ventilators while elevating procurement specifications toward intelligent automation.
South Africa's national pharmaceutical regulator is tightening clinical evidence requirements for high-risk ARDS devices. Manufacturers must submit local safety data and post-market surveillance plans alongside technical dossiers. This elevates compliance costs for emerging market entrants. Established suppliers with existing African regulatory infrastructure capture disproportionate share of new hospital tenders.
Service unbundling is fragmenting traditional ventilator procurement relationships. Gulf hospital systems now separate hardware acquisition from preventive maintenance contracts and software upgrade subscriptions. This purchasing pattern shift compresses upfront capital commitments while extending total cost of ownership calculations. The UAE's MOHAP centralized procurement pilots explicitly structure multi-vendor service tier competitions independent of device placement.
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market Segmentation
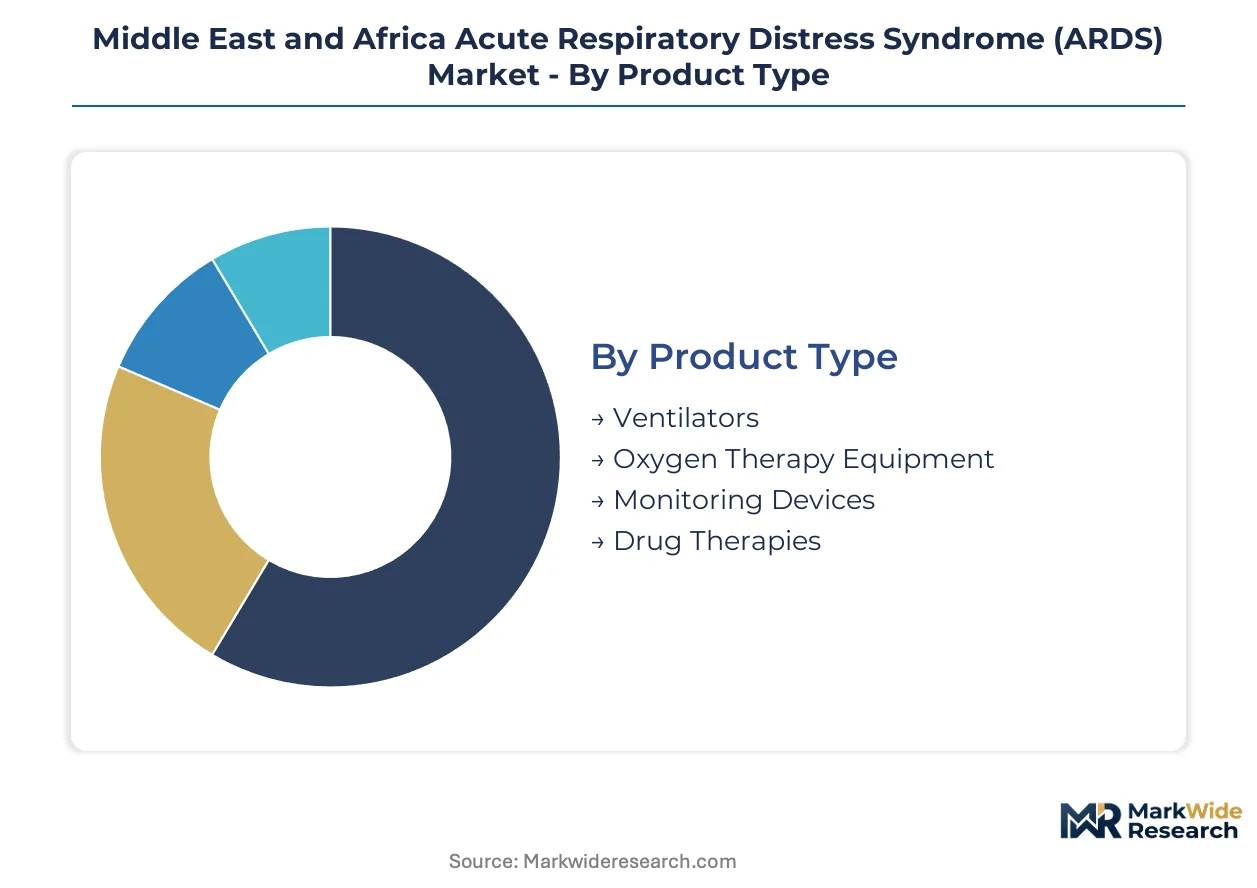
ARDS intervention strategies vary sharply by care setting and disease severity across Middle East and Africa health systems. Segment-level procurement patterns reveal where capital investment concentrates versus where operational budgets absorb recurring consumables.
Product Type:
Ventilator hardware specifications diverge between Gulf tertiary hospitals and East African referral centers.
- Ventilators:Positive pressure systems with lung-protective modes dominate ICU procurement in Saudi Arabian and UAE tertiary facilities. Saudi Arabia's SFDA registration requirements favor established suppliers with regional service infrastructure.
- Oxygen Therapy Equipment:High-flow nasal cannula systems bridge invasive ventilation and conventional oxygen delivery in intermediate care wards. South African metropolitan hospitals deploy these for step-down protocols to free ICU capacity.
- Monitoring Devices:Multiparameter platforms with respiratory mechanics tracking.
- Drug Therapies:Neuromuscular blockade and corticosteroid formulations facing generic competition.
Ventilators lead on scale; oxygen therapy equipment leads on momentum.
End User:
Care delivery economics reshape device specifications across facility tiers.
- Hospitals:Tertiary medical centers in Gulf Cooperation Council states command the installed base of mechanical ventilation and ECMO capability. Government health budgets in Saudi Arabia and the UAE prioritize centralized procurement of critical care infrastructure.
- Clinics:Intermediate respiratory support concentrates in South African urban clinic networks. These facilities lack surgical perfusion programs but deploy high-flow oxygen systems for stabilizing patients prior to referral.
- Home Care:Post-acute ventilation weaning and long-term oxygen programs.
- Research Laboratories:Academic medical centers in Egypt and Morocco conducting ARDS pathophysiology studies.
Hospitals anchor volume absorption; clinics are climbing fastest as intermediate care expands.
Delivery Mode:
Route selection follows severity stratification and vascular access availability.
- Inhalation:Aerosolized bronchodilators and pulmonary surfactant delivery for pediatric ARDS cases. Nebulizer compatibility requirements influence ventilator specification in pediatric ICUs.
- IV Administration:Sedation protocols and vasoactive support for mechanically ventilated patients. Central line placement capability limits deployment in resource-constrained settings.
- Oral Delivery:Enteral nutrition and select anti-inflammatory agents.
- Nasal Administration:High-flow oxygen delivery interfaces and intranasal sedation adjuncts.
Inhalation dominates pediatric applications; IV administration commands critical care pharmacology.
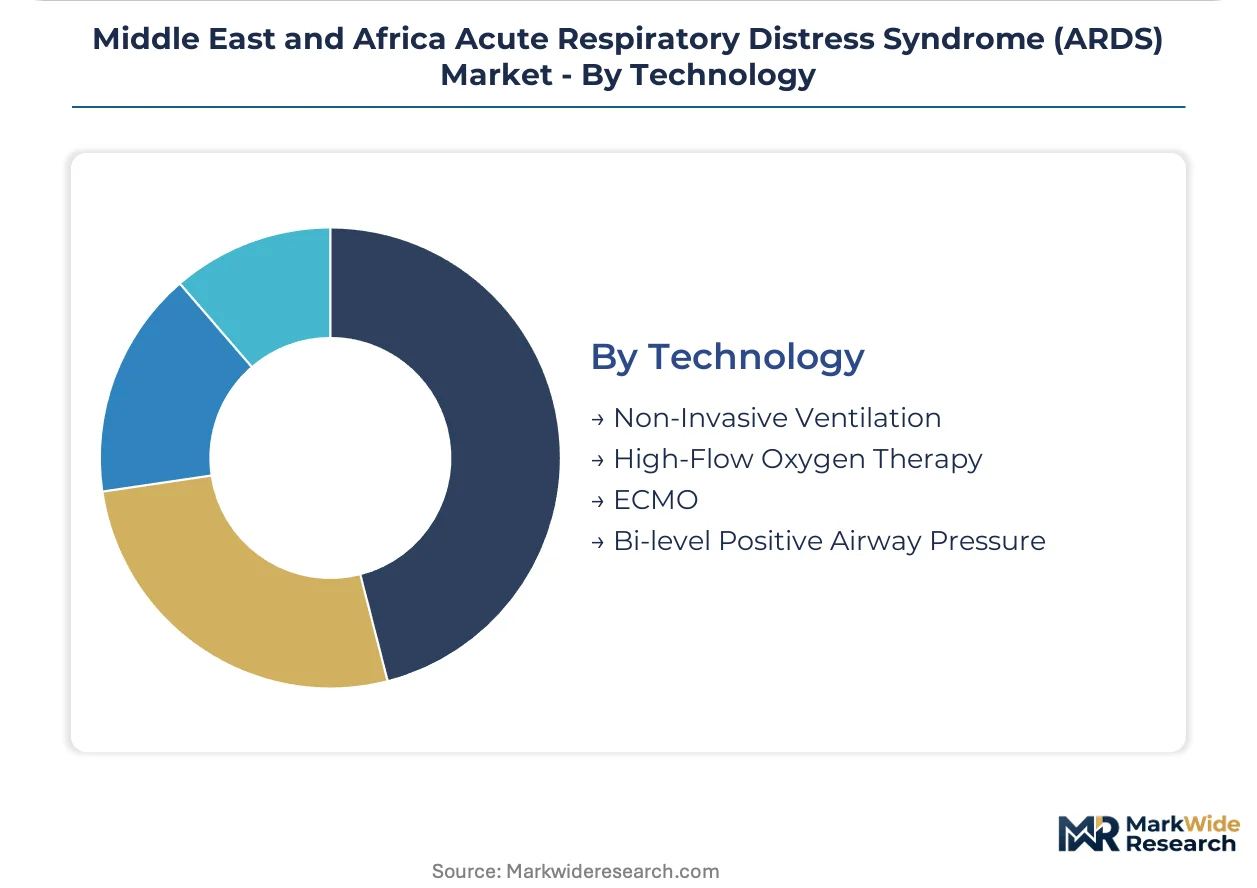
Technology:
Interface invasiveness determines capital intensity and staff training requirements.
- Non-Invasive Ventilation:Bi-level positive airway pressure systems deployed in emergency departments and step-down units. South African public hospitals leverage these to delay or avoid intubation in capacity-constrained settings.
- High-Flow Oxygen Therapy:Heated humidification systems with precise FiO2 control gaining penetration in Gulf private hospital chains. The technology reduces intubation rates in moderate hypoxemia.
- ECMO:Veno-venous configurations for refractory hypoxemia requiring surgical perfusionist staffing. Regional referral centers in Saudi Arabia and South Africa are building perfusion programs.
- Bi-level Positive Airway Pressure:Sleep-disordered breathing platforms adapted for acute hypoxemic respiratory failure.
Non-invasive ventilation holds installed base leadership; ECMO shows steepest expansion trajectory as referral centers build surgical capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Critical care infrastructure for respiratory failure management first scaled through Gulf Cooperation Council hospital investments during the 2010s, then expanded through South African public health system upgrades and East African referral center construction.
Saudi Arabia
Government health budgets prioritize mechanical ventilation procurement for tertiary hospitals in Riyadh and Jeddah. The Saudi Food and Drug Authority streamlines ARDS device approval pathways through harmonized technical dossier requirements. King Faisal Specialist Hospital anchors ECMO program development in the Eastern Province.
United Arab Emirates
Private hospital chains in Dubai deploy high-flow oxygen systems to reduce ICU admission rates. The Ministry of Health and Prevention pilots centralized ventilator purchasing across emirate-level health systems. Cleveland Clinic Abu Dhabi maintains the Gulf's largest surgical perfusion capability for refractory hypoxemia cases.
South Africa
Metropolitan public hospitals in Johannesburg and Cape Town absorb ventilator demand from regional referral networks. The national pharmaceutical regulator intensifies adverse event reporting requirements for high-risk respiratory devices. Groote Schuur Hospital anchors academic ECMO training partnerships with European centers.
Egypt
Cairo's tertiary medical centers expand ICU capacity through government infrastructure bonds. The country's national pharmaceutical regulator enforces medical device registration with clinical evidence requirements. Ain Shams University Hospital conducts ARDS pathophysiology research in academic collaboration with Moroccan centers.
Kenya
National referral hospitals in Nairobi construct critical care wings without established ARDS device distribution relationships. The country's central medical supplies agency tests consolidated oxygen therapy procurement for devolved health systems. Kenyatta National Hospital anchors East African ECMO capability building through perfusionist training programs.
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service bundling intensity, with integrated critical care portfolios commanding hospital loyalty through extended maintenance contracts. The vendor base stratifies between diversified medical technology conglomerates and specialized respiratory device manufacturers. Three archetypes dominate: full-stack critical care integrators, ECMO perfusion specialists, and connected monitoring ecosystem providers. Competitive moves concentrate on software subscription unbundling and multi-year centralized procurement commitments.
Within the integrated critical care tier, Medtronic plc and Koninklijke Philips N.V. exemplify full-stack positioning through hardware-software convergence strategies. Getinge AB occupies a specialized position in extracorporeal support systems. Among pharmaceutical manufacturers, GlaxoSmithKline plc and Boehringer Ingelheim International GmbH represent the neuromuscular blockade and anti-inflammatory therapy segments facing generic margin compression.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| GlaxoSmithKline plc |
| Medtronic plc |
| Getinge AB |
| Boehringer Ingelheim International GmbH |
| Koninklijke Philips N.V. |
| Novartis AG |
| Dräger Safety AG & Co. KGaA |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Surgical perfusionist scarcity across the Gulf Cooperation Council widens pricing spreads between ECMO-capable tertiary centers and standard ICU ventilator deployments. Labor-cost differentials between European-trained specialist staffing and locally sourced respiratory therapist coverage translate into three-tier equipment procurement structures across Saudi Arabian and South African hospital systems.
Pricing Analysis
Hardware-software unbundling now governs ventilator acquisition across Middle East and Africa health systems. Three-tier pricing structure across premium, standard, and economy levels separates subscription-enabled adaptive platforms from conventional volume-control units and refurbished legacy devices. Price differentiation hinges on SFDA registration tier and after-sales service bundling. Cost compression in economy-tier ventilators is intensifying because semiconductor input volatility forces manufacturers to absorb margin erosion. Government hospital procurement committees in Saudi Arabia and the UAE exhibit lowest price sensitivity; East African referral centers face acute budget constraints.
Supply Chain Analysis
Perfusionist training pipeline limitations in Saudi Arabia and South Africa constrain ECMO system deployment velocity. Compressor module manufacturing concentrates in Germany, China, and Japan; polymer components for disposable circuits draw from South Korean and Taiwanese petrochemical operations. Semiconductor dependencies for ventilator control systems rest on single-source vulnerability for specialized analog chips. Distribution runs through Dubai-based medical device free zones serving Gulf markets and Johannesburg distribution hubs covering sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa ARDS market compounds steadily through critical care infrastructure investment cycles across Gulf Cooperation Council states. Government health budget prioritization of mechanical ventilation procurement sustains predictable demand visibility.
For Market Incumbents: Cement hospital loyalty through multi-year preventive maintenance contracts that lock out competitor service penetration. Deepen backward integration into ventilator software development to capture recurring subscription revenue streams. Emerging modular platform entrants threaten installed base stickiness; prioritize CE marking and SFDA dual-certification pathways to maintain tender eligibility across Gulf markets. For New Entrants and Emerging Players: East African national referral hospitals lacking established ARDS device distribution relationships represent the most penetrable buyer archetype. Kenya's devolved health system procurement experiments and Ethiopia's critical care wing construction create white-space entry points. Lead with high-flow oxygen therapy systems that require lower perfusionist staffing than ECMO alternatives; partner with regional distributors holding MOHAP or South African pharmaceutical regulator relationships. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking connected monitoring ecosystem assets. The market supports long-term compounder positioning through recurring service revenue attachment rates. Target acquisition candidates with established Gulf hospital system relationships and regulatory infrastructure spanning SFDA, MOHAP, and South Africa's national pharmaceutical regulator. Watch ECMO program expansion velocity at King Faisal Specialist Hospital and Cleveland Clinic Abu Dhabi as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Harmonization Pathway | Streamlined technical dossier requirements accelerate Gulf market entry for ventilator manufacturers. |
| Hospital System Partnership | Multi-year centralized procurement commitments with UAE MOHAP secure volume and service revenue visibility. |
| Software Companion Development | Adaptive lung-protective algorithms differentiate hardware offerings and extend replacement cycles. |
| Reimbursement Strategy | Government health budget prioritization in Saudi Arabia and UAE anchors sustainable pricing power. |
| CE Marking Pathway | European regulatory alignment enables accelerated SFDA registration through harmonized technical standards. |
Research Methodology
Multiple input streams — primary interviews with critical care physicians, biomedical engineers, and hospital procurement managers; secondary validation through SFDA registration databases, MOHAP tender records, and South African pharmaceutical regulator filings; plus customs trade data for ventilator and ECMO equipment imports — were reconciled through bottom-up and top-down triangulation. Intensive care unit directors at King Faisal Specialist Hospital, Groote Schuur Hospital, and Kenyatta National Hospital provided clinical workflow and equipment utilization perspectives. GPO contracts and government health budget disclosures supplied pricing and procurement pattern intelligence.
Data-stream reconciliation across product type, end-user facility tier, technology invasiveness, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs were derived through log-linear trend fitting across the projection horizon, with ECMO segment expansion calibrated to perfusionist training program announcements and referral center construction timelines. Ventilator replacement cycle compression and software subscription attachment rates informed hardware-software revenue split modeling.
Inputs from hospital procurement committees and regulatory filing databases were available through the study window; gaps in real-time East African distributor inventory data introduce uncertainty bands for Kenya and Ethiopia market sizing. Forecasts reflect assumptions regarding Gulf Cooperation Council health budget continuity and SFDA harmonization progression. Material deviation in semiconductor supply availability or perfusionist training pipeline expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Emphysema Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market