
 Lung Management Products Market | 2026-2036
Lung Management Products Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Management Products Market Analytics
Smart inhaler certification standards are redrawing competitive boundaries in respiratory care. Medtronic PLC leverages its hospital channel depth to sustain placement across integrated delivery networks. Vyaire Medical, Inc. specializes in ventilation and respiratory diagnostics, occupying a narrow but defensible niche. Koninklijke Philips N.V. anchors its position through connected care ecosystems that extend from acute settings into home environments.
Lung management products encompass therapeutic and diagnostic devices designed to monitor, deliver medication to, or support the function of the respiratory system, typically incorporating flow sensors, pressure transducers, or mesh/nebulizer plates with particle size distributions optimized for lower airway deposition. Their primary purpose spans chronic disease management, acute respiratory failure intervention, and post-surgical pulmonary rehabilitation across care continuums. Inhalers and smart inhalers within the technology dimension capture concentrated R&D investment as pharmaceutical-device convergence deepens, while home healthcare end users represent the fastest-expanding access point as reimbursement shifts favor decentralized chronic disease management. Digital therapeutics and wearable monitors are attracting venture funding but face longer regulatory validation cycles before structural volume shifts materialize.
The FDA's 510(k) clearance framework and the EPA's device sterilization emissions standards jointly determine market entry feasibility and manufacturing location decisions for US-bound products. The EU MDR and FDA's quality system regulation impose parallel clinical evidence requirements that favor companies with established regulatory infrastructure over emerging entrants. Stakeholders must weigh the capital intensity of dual-territory compliance against the revenue protection that FDA and CE-marked portfolios provide in concentrated hospital purchasing systems.
Market Dynamics
Hospital procurement networks in the United States are consolidating vendor relationships around integrated digital platforms, compressing supplier margins while elevating connectivity requirements as a gating factor for contract eligibility.
Growth Catalysts
- FDA 510(k) Pathway:The premarket notification framework accelerates clearance timelines for Class II respiratory devices, enabling faster commercialization of connected inhalers and ventilator accessories.
- Home Healthcare Migration:Reimbursement shifts toward decentralized chronic disease management pull patient monitoring and therapeutic delivery into residential settings, expanding addressable volume.
- Mesh Nebulizer Plates:Advances in particle size distribution control optimize lower airway deposition rates, improving therapeutic efficacy in COPD and asthma management protocols.
Market Restraints
- EU MDR Compliance Burden:The Medical Device Regulation imposes parallel clinical evidence requirements that extend validation timelines and favor established regulatory infrastructure over emerging entrants.
- EPA Sterilization Emissions:Device sterilization standards constrain manufacturing location decisions for US-bound products, elevating operational complexity at contract sterilization facilities.
- Silicon Pressure Transducers:Concentrated supply of precision sensor components creates input vulnerability, with single-source dependencies in foundry capacity for MEMS-based flow sensing.
Strategic Opportunities
- Digital Therapeutics Convergence:Integration of prescription software with inhaler hardware creates reimbursable software-as-medical-device categories, opening new revenue streams beyond hardware margins.
- Wearable Respiratory Monitors:Continuous pulse oximetry and respiratory rate tracking via wrist-worn form factors address gaps in nocturnal and ambulatory hypoxemia detection.
- India CDSCO Alignment:Harmonization with international standards at India's central drug regulator enables streamlined market entry for CE-marked and FDA-cleared portfolios.
Industry Challenges
- Clinical Validation Timelines:Digital therapeutics and AI-enabled diagnostic modules face extended regulatory validation cycles before structural volume shifts materialize, compressing venture-funded runway.
- Legacy System Integration:Acute care EMR interoperability requirements impose technical friction on connected device deployment, requiring dedicated health IT engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Management Products Market |
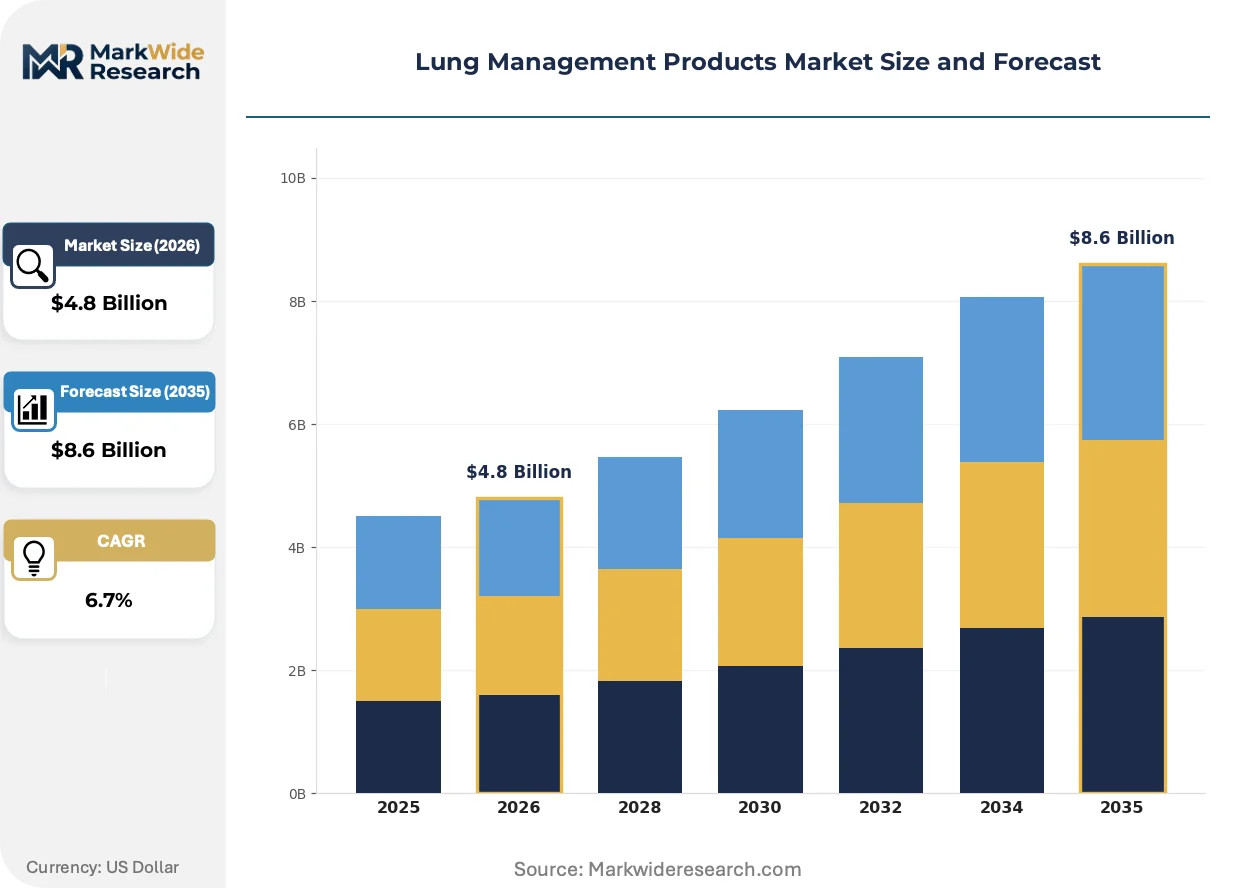
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Spirometers, Peak Flow Meters Application: Chronic Obstructive Pulmonary Disease, Asthma, Pulmonary Rehabilitation, Home Care End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Technology: Digital Therapeutics, Smart Inhalers, Telemedicine Solutions, Wearable Monitors |
| Companies Covered | Medtronic PLC, Teleflex, Inc., Masimo Corporation, Baxter International, Inc., Nihon Kohden Corporation, ICU Medical, Inc., Vyaire Medical, Inc., Becton, Dickinson and Company, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Management Products Market Evolving Landscape
Respiratory care technology is fragmenting into divergent performance tiers as connectivity requirements split product portfolios between premium connected systems and cost-optimized conventional alternatives.
Mesh nebulizer technology is bifurcating the aerosol delivery landscape. Vibrating membrane systems with precision particle engineering enable targeted lower airway deposition for biologic therapies. Tertiary hospital intensive care units adopt these platforms for acute respiratory failure intervention, while home healthcare providers retain compressed-air alternatives for cost-sensitive chronic management. This split is compressing mid-tier conventional nebulizer margins while expanding premium attach rates.
REACH substance restrictions and RoHS substance limitations are reshaping material selection in device manufacturing. The European framework restricts phthalates and heavy metals in patient-contacting plastics, forcing reformulation of inhaler housings and circuit components. Manufacturers serving EU markets respond by qualifying alternative polymer grades, with certification delays most acute for single-use consumables with complex supply chains.
Integrated delivery networks now mandate API-enabled device connectivity as a contract prerequisite. Hospital procurement committees in the United States favor platforms that stream usage data directly into population health dashboards, displacing standalone devices without interoperability certification. This behavioral shift is most visible in asthma and COPD management programs at accountable care organizations, where adherence monitoring drives therapeutic optimization protocols.
Lung Management Products Market Segmentation
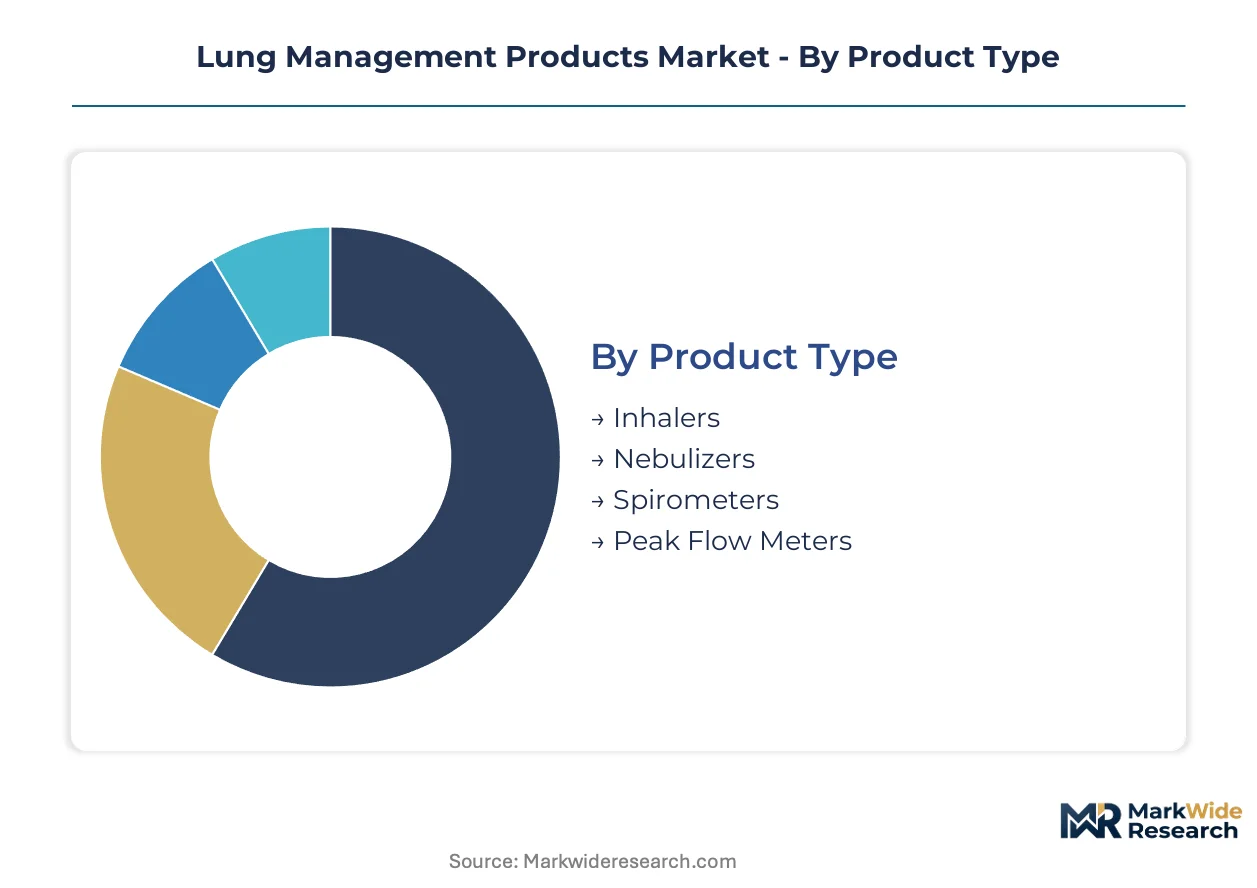
Segmentation in lung management products reveals divergent growth vectors across device categories and care settings. Product portfolios fragment between acute intervention hardware and connected chronic disease platforms, each demanding distinct regulatory pathways and channel strategies.
Product Type:
Domestic manufacturing dominates inhaler and nebulizer supply for regulated markets, while spirometers and peak flow meters flow through export-oriented production hubs serving price-sensitive geographies.
- Inhalers:Pressurized metered-dose and dry powder devices deliver bronchodilators and corticosteroids through optimized particle engineering. Demand concentrates in US hospital procurement networks where connected inhaler certification gates contract eligibility. FDA 510(k) pathways favor established manufacturers with validated quality systems.
- Nebulizers:Mesh and jet nebulizer systems aerosolize liquid formulations for patients unable to coordinate inhaler technique. European REACH substance restrictions force polymer reformulation in patient-contacting components, extending certification timelines for single-use consumables.
- Spirometers:Diagnostic devices measuring forced expiratory volume support COPD and asthma diagnosis in clinic settings.
- Peak Flow Meters:Mechanical and digital variants enable patient self-monitoring of expiratory flow limitation in home environments.
Inhalers hold the largest share; momentum sits with nebulizers as biologic therapy delivery requirements expand.
Application:
Cost tier stratification separates premium biologic-compatible platforms from standard maintenance therapy devices across clinical indications.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation drives demand for combination long-acting bronchodilator delivery systems. Tertiary hospital intensive care units adopt connected platforms streaming adherence data into population health dashboards at US accountable care organizations.
- Asthma:Inflammatory airway disease management relies on inhaled corticosteroid and rescue medication delivery with usage tracking. Home healthcare reimbursement shifts pull monitoring and therapeutic delivery into residential settings, expanding addressable volume for digital-enabled devices.
- Pulmonary Rehabilitation:Post-acute respiratory muscle training and oxygen titration support recovery from critical illness.
- Home Care:Decentralized chronic disease management protocols favor patient-operated devices with simplified interfaces.
COPD applications command the dominant revenue position; asthma represents the steepest expansion trajectory as pediatric and adult prevalence climbs.
End User:
Customer type determines connectivity requirements, with integrated delivery networks mandating API-enabled data streaming as a contract prerequisite.
- Hospitals:Acute care settings demand ventilator accessories and high-flow oxygen delivery systems with EMR interoperability. Procurement committees favor platforms integrating directly into clinical workflow systems, displacing standalone devices without certification.
- Clinics:Outpatient diagnostic and therapeutic delivery centers prioritize portable spirometry and nebulizer systems for same-day respiratory assessment.
- Home Healthcare:Residential care providers seek cost-optimized conventional alternatives to premium connected systems for chronic management.
- Long-term Care Facilities:Skilled nursing environments require durable equipment supporting ventilator-dependent residents.
Hospitals anchor volume concentration; home healthcare is gaining share fastest as reimbursement migration accelerates.
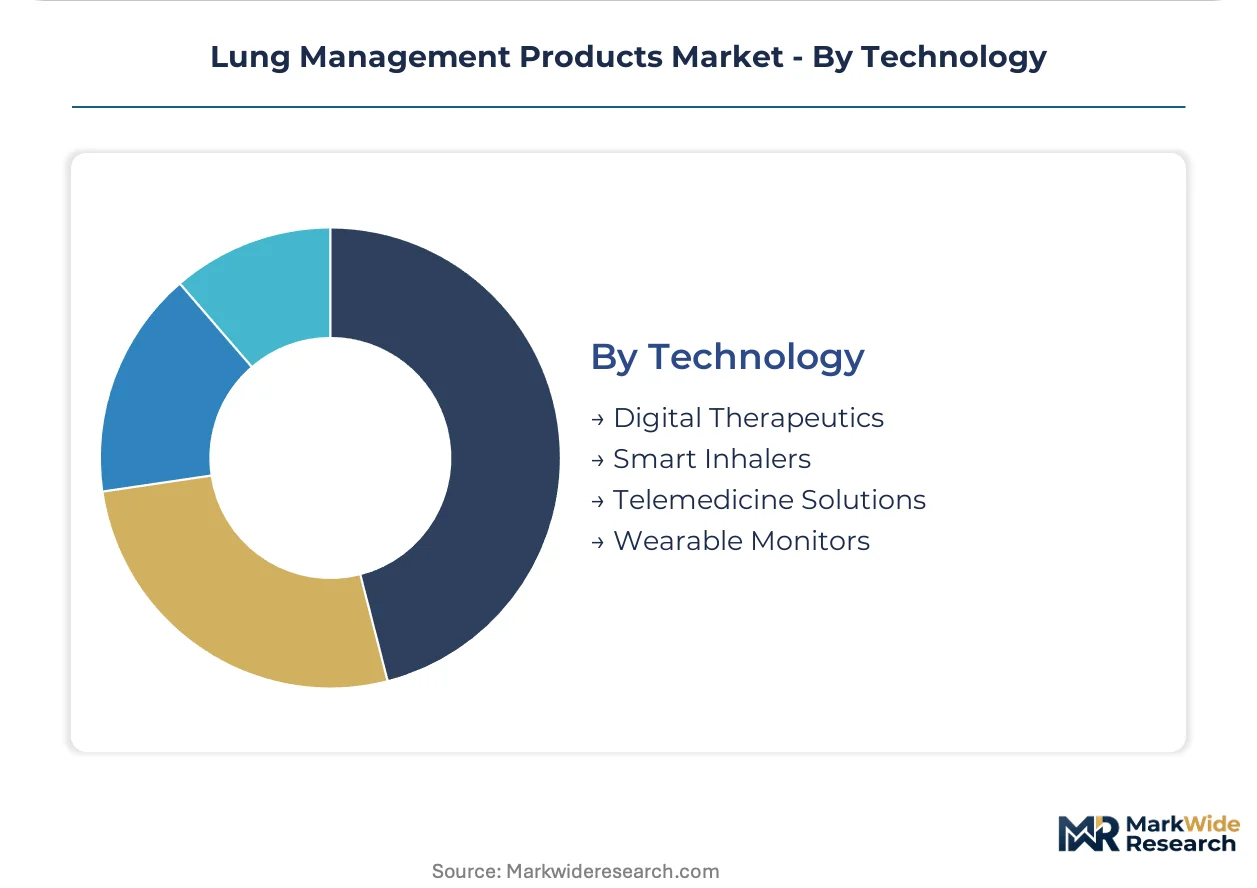
Technology:
Supply concentration in MEMS sensor foundries creates input vulnerability for precision flow measurement components across digital device categories.
- Digital Therapeutics:Prescription software integrated with inhaler hardware creates reimbursable software-as-medical-device categories. Extended regulatory validation cycles compress venture-funded runway before structural volume shifts materialize.
- Smart Inhalers:Bluetooth-enabled dose counters and adherence trackers connect to patient and provider dashboards. Certification standards are redrawing competitive boundaries as FDA premarket notification pathways accelerate clearance timelines for Class II respiratory devices.
- Telemedicine Solutions:Remote patient monitoring platforms bridge acute and home care settings for respiratory specialist consultation.
- Wearable Monitors:Continuous pulse oximetry and respiratory rate tracking via wrist-worn form factors address gaps in nocturnal hypoxemia detection.
Smart inhalers dominate current revenue; digital therapeutics carry the highest growth optionality pending reimbursement establishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement networks in the United States display the lowest price elasticity, accepting premium connected devices with adherence tracking, while home healthcare providers in India and Southeast Asia prioritize cost-optimized conventional alternatives. This demand bifurcation shapes manufacturing location decisions and regulatory pathway investments across territories.
United States
Integrated delivery networks mandate API-enabled connectivity as a contract prerequisite for inhaler and nebulizer procurement. FDA 510(k) pathways accelerate clearance timelines for Class II respiratory devices, favoring established manufacturers with validated quality systems. The Boston-Cambridge corridor concentrates digital therapeutics development, with venture-funded startups targeting prescription software-as-medical-device categories.
Germany
Tertiary hospital intensive care units drive demand for mesh nebulizer systems with precision particle engineering for biologic therapy delivery. EU MDR compliance imposes parallel clinical evidence requirements that extend validation timelines and elevate documentation burdens. The Baden-Württemberg industrial cluster hosts precision sensor foundries supplying MEMS-based flow sensing components to device manufacturers.
China
Domestic manufacturers capture volume in conventional nebulizer and spirometer categories serving price-sensitive clinic and home care segments. NMPA regulatory harmonization with international standards streamlines market entry for CE-marked portfolios through priority review pathways. The Yangtze River Delta concentration spans Shanghai-based R&D centers and Suzhou contract manufacturing facilities serving export markets.
India
Home healthcare reimbursement shifts pull patient monitoring into residential settings, expanding addressable volume for patient-operated devices with simplified interfaces. CDSCO alignment with international standards enables streamlined market entry for FDA-cleared and CE-marked portfolios. The Maharashtra-Gujarat pharmaceutical-device corridor concentrates inhaler manufacturing for domestic consumption and regional export.
Japan
Aging demographics and COPD prevalence drive demand for connected chronic disease management platforms extending from acute settings into home environments. PMDA quality system requirements parallel FDA regulations, favoring companies with established regulatory infrastructure. The Tokyo-Osaka corridor anchors population health dashboard integration at accountable care organizations.
Lung Management Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with diversified medical technology conglomerates commanding premium connected device segments and regional specialists capturing conventional hardware volume. The market structure concentrates around hospital procurement networks that consolidate vendor relationships around integrated digital platforms. Three archetypes dominate: diversified multinationals with regulatory infrastructure depth, mid-cap specialists in ventilation or diagnostics, and regional cost-optimized manufacturers. Competitive moves center on portfolio diversification into digital therapeutics and strategic partnerships for EMR interoperability certification.
Among diversified medical technology conglomerates, Medtronic PLC and Koninklijke Philips N.V. occupy positions spanning acute care through home environments, with the former leveraging hospital channel depth across integrated delivery networks and the latter anchoring connected care ecosystems. Vyaire Medical, Inc. sits within the specialist tier, representing the narrow-but-defensible niche archetype in ventilation and respiratory diagnostics. These three exemplify how regulatory infrastructure scale and channel relationships determine contract eligibility in concentrated purchasing systems.
| Leading Market Players |
|---|
| Medtronic PLC |
| Teleflex, Inc. |
| Masimo Corporation |
| Baxter International, Inc. |
| Nihon Kohden Corporation |
| ICU Medical, Inc. |
| Vyaire Medical, Inc. |
| Becton, Dickinson and Company |
| Koninklijke Philips N.V. |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for MEMS pressure transducers concentrate pricing power with foundry operators in Baden-Württemberg and the Yangtze River Delta, compressing margins for device manufacturers lacking captive sensor supply or long-term offtake agreements. This lead-time rigidity forces tiered procurement strategies where hospital networks absorb premium connectivity costs while home healthcare providers seek conventional alternatives.
Pricing Analysis
Consumables and service contracts generate lifetime value exceeding hardware margins by substantial multiples in connected respiratory portfolios. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) certification tier and EMR interoperability grade. Cost compression in conventional nebulizer tiers is intensifying because Indian and Southeast Asian manufacturers compete on polymer conversion costs. Home healthcare providers exhibit highest price sensitivity; tertiary hospital procurement committees accept connectivity premiums for population health dashboard integration.
Supply Chain Analysis
Inventory cycles stretching ninety days for precision MEMS components signal supply rigidity across the tier. Manufacturing concentrates in Germany, China, and India for finished devices, with silicon wafer processing anchored in Taiwan and South Korea. Supply chains draw from medical-grade polymer feedstocks, platinum-cured silicone circuits, and lithium-ion cell assemblies. Single-source vulnerability in MEMS foundry capacity threatens continuity. Distribution runs through hospital GPO contracts, regional device distributors, and direct-to-clinic e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lung management products market sits in cyclical recovery as hospital capital expenditure cycles rebound from deferred procurement during acute respiratory demand peaks. Reimbursement migration toward decentralized care models sustains volume growth independent of acute care cyclicality.
For Market Incumbents: Fortify regulatory infrastructure depth against emerging digital therapeutic entrants by accelerating FDA 510(k) submissions for software-as-medical-device modules. Deepen backward integration into MEMS sensor supply through foundry partnerships or captive capacity in Taiwan. Channel control through integrated delivery network exclusivity agreements protects placement against mid-cap specialists.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market entry for AI-enabled diagnostic modules with abbreviated clinical validation requirements. Target pediatric asthma management programs at US accountable care organizations where adherence monitoring gaps persist. White-space exists in wearable nocturnal hypoxemia detection for home healthcare reimbursement expansion. Go-to-market through telemedicine platform partnerships bypasses hospital GPO exclusion.
For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease platform play because respiratory management extends across acute intervention, transitional care, and lifetime maintenance therapy. Acquisition targets with established CE marking and FDA dual-certification infrastructure command scarcity premiums as EU MDR documentation burdens persist. Watch for reimbursement code establishment for prescription digital therapeutics as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Fast-track clearance timelines compress commercialization runway for connected inhaler portfolios against EU MDR delays. |
| Hospital System Partnership | Integrated delivery network exclusivity agreements lock out competing vendors through EMR interoperability mandates. |
| Software Companion Development | Prescription digital therapeutic modules create recurring revenue streams beyond hardware transaction margins. |
| CE Marking Pathway Investment | Dual-territory regulatory infrastructure protects European revenue exposure against MDR compliance failures. |
| Reimbursement Strategy | CPT code establishment for remote patient monitoring enables provider billing for connected device data streams. |
Research Methodology
Operator-level perspectives from hospital procurement managers, biomedical engineers, GPO contracts specialists, and home healthcare reimbursement directors anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up unit economics and top-down epidemiological modeling triangulated volume estimates across patient populations and care settings.
Sensitivity analysis tested forecast robustness against reimbursement policy shifts, regulatory timeline extensions, and MEMS supply disruption scenarios. Segmentation dimensions spanned device category, clinical indication, care setting, connectivity tier, and regional regulatory cluster. CAGRs derived from patient volume projections, replacement cycle analysis, and pricing trajectory assumptions. Forecast inputs incorporated COPD prevalence modeling, asthma pediatric incidence tracking, and biologic therapy adoption curves.
Decision-makers should treat outputs as directional under stable reimbursement migration and regulatory harmonization assumptions; material deviation in FDA digital health guidance or EU MDR implementation rigor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market