
 Respiratory Distress Syndrome Management Market | 2026-2036
Respiratory Distress Syndrome Management Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Distress Syndrome Management Market Analytics
Aftermarket service revenue for ventilator fleets is rewriting profitability expectations across the respiratory device landscape. Medtronic plc leverages its installed base of critical care ventilators to sustain recurring service contracts that anchor hospital purchasing decisions. Drägerwerk AG & Co. KGaA competes through specialized neonatal ventilation platforms that dominate European tertiary care networks.
Respiratory Distress Syndrome Management encompasses clinical interventions, pharmaceutical agents, and mechanical support systems designed to restore adequate gas exchange in patients with surfactant deficiency or alveolar collapse, typically requiring positive pressure ventilation with fractional inspired oxygen titration and exogenous surfactant administration. The primary purpose centers on reducing ventilation-induced lung injury while maintaining tissue oxygenation in premature neonates and acute lung injury populations. Ventilators and Continuous Positive Airway Pressure systems capture the dominant share of capital expenditure as hospitals prioritize lung-protective ventilation protocols, while Oxygen Therapy Devices represent the fastest-growing segment amid expanding homecare transitions and portable concentrator innovation. The Therapy Area dimension shows Acute Respiratory Distress Syndrome commanding premium pricing due to intensive care dependency, though Obstructive Sleep Apnea generates higher volume throughput through outpatient diagnostic pathways.
The US FDA and EMA jointly shape product development through pediatric investigation plans and orphan drug incentives that dictate surfactant formulation trials, while the EU MDR recertification timeline is forcing device manufacturers to consolidate technical documentation for ventilator platforms. Japan's PMDA accelerates market access through Sakigake designation for neonatal respiratory innovations. Stakeholders must monitor how post-market surveillance requirements evolve across FDA, EMA, and PMDA jurisdictions to anticipate compliance cost reallocations.
Market Dynamics
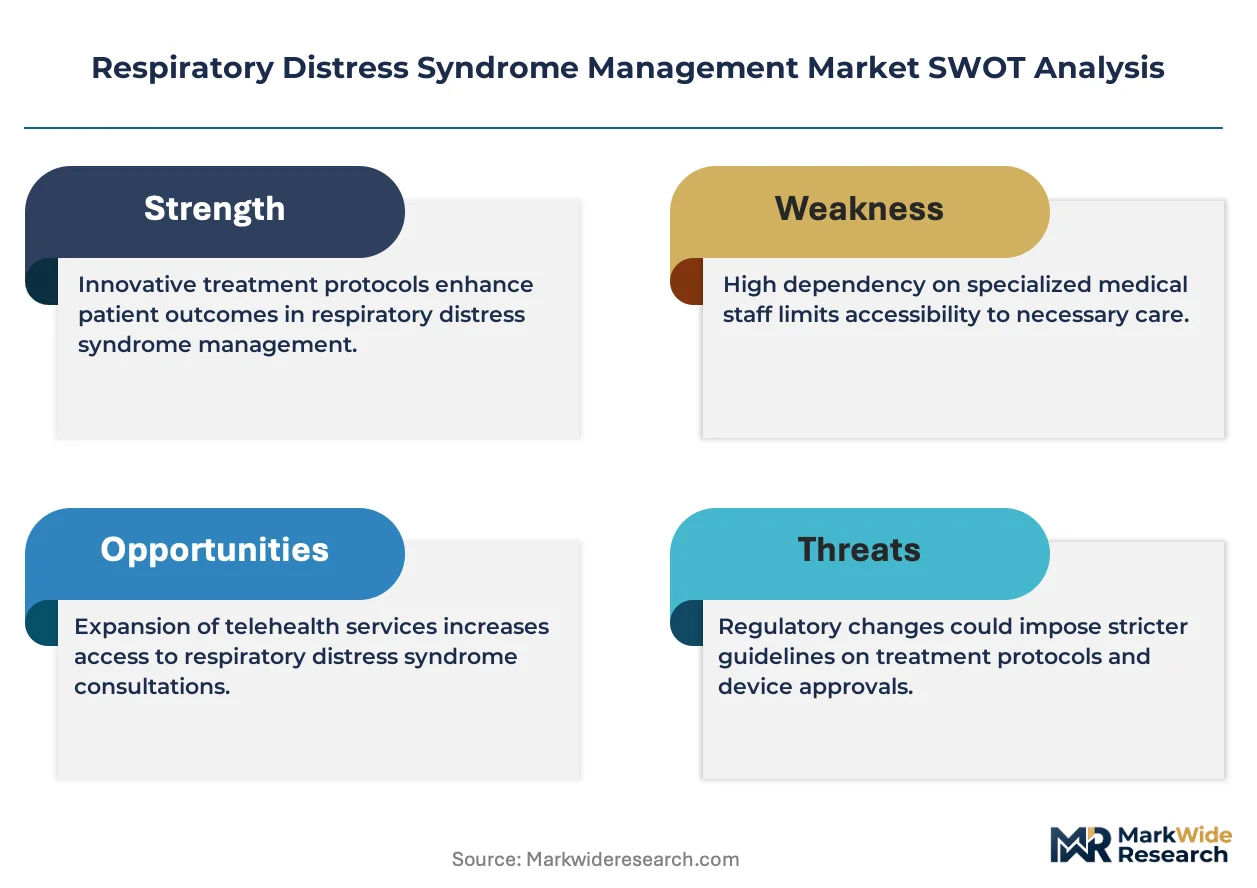
The Respiratory Distress Syndrome Management Market is experiencing structural pressure from the FDA's pediatric exclusivity incentives, which are accelerating surfactant formulation trials while simultaneously tightening post-market surveillance requirements for mechanical ventilation platforms.
Growth Catalysts
- Neonatal ICU Infrastructure Expansion:Tertiary hospitals in the United States are expanding NICU bed capacity and surfactant administration capabilities, creating sustained demand for integrated ventilation-surfactant systems.
- EMA Orphan Drug Incentives:European regulatory pathways for rare pediatric conditions are shortening development timelines for novel surfactant formulations targeting preterm neonates.
- Homecare Oxygen Transition:Portable concentrator innovation is enabling post-acute care discharges, extending therapeutic reach beyond hospital walls into residential settings.
Market Restraints
- Specialized Polymers Supply Concentration:Medical-grade silicone membrane production for ventilator circuits concentrates among a limited supplier base in Germany and Switzerland, exposing manufacturers to input bottlenecks.
- EU MDR Recertification Burden:The European Medical Device Regulation's technical documentation requirements are forcing ventilator manufacturers to consolidate product portfolios, delaying platform updates.
- Less-Invasive Ventilation Substitution:High-flow nasal cannula systems are displacing conventional mechanical ventilation in moderate respiratory distress cases, compressing addressable volume for invasive platforms.
Strategic Opportunities
- Japan's Sakigake Designation:The PMDA's accelerated approval pathway for neonatal respiratory innovations offers first-mover positioning for surfactant-device combination products in Asian markets.
- Rural NICU Network Gaps:Underpenetrated secondary hospitals in India present white-space demand for cost-optimized CPAP systems with simplified training protocols.
- Digital Twin Convergence:Integration of computational lung modeling with real-time ventilator feedback loops is enabling predictive titration protocols that reduce ventilation-induced lung injury.
Industry Challenges
- Perfusion Technology Talent Scarcity:Clinical specialists capable of managing extracorporeal membrane oxygenation integration with surfactant therapy remain concentrated in academic medical centers, limiting service expansion.
- ISO 18562 Biocompatibility Testing:Gas pathway testing timelines for new ventilator materials are extending certification cycles by 8-14 months, compressing product launch windows.
- Interoperability Fragmentation:Legacy hospital information systems lack standardized data exchange protocols with modern ventilator analytics platforms, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Distress Syndrome Management Market |
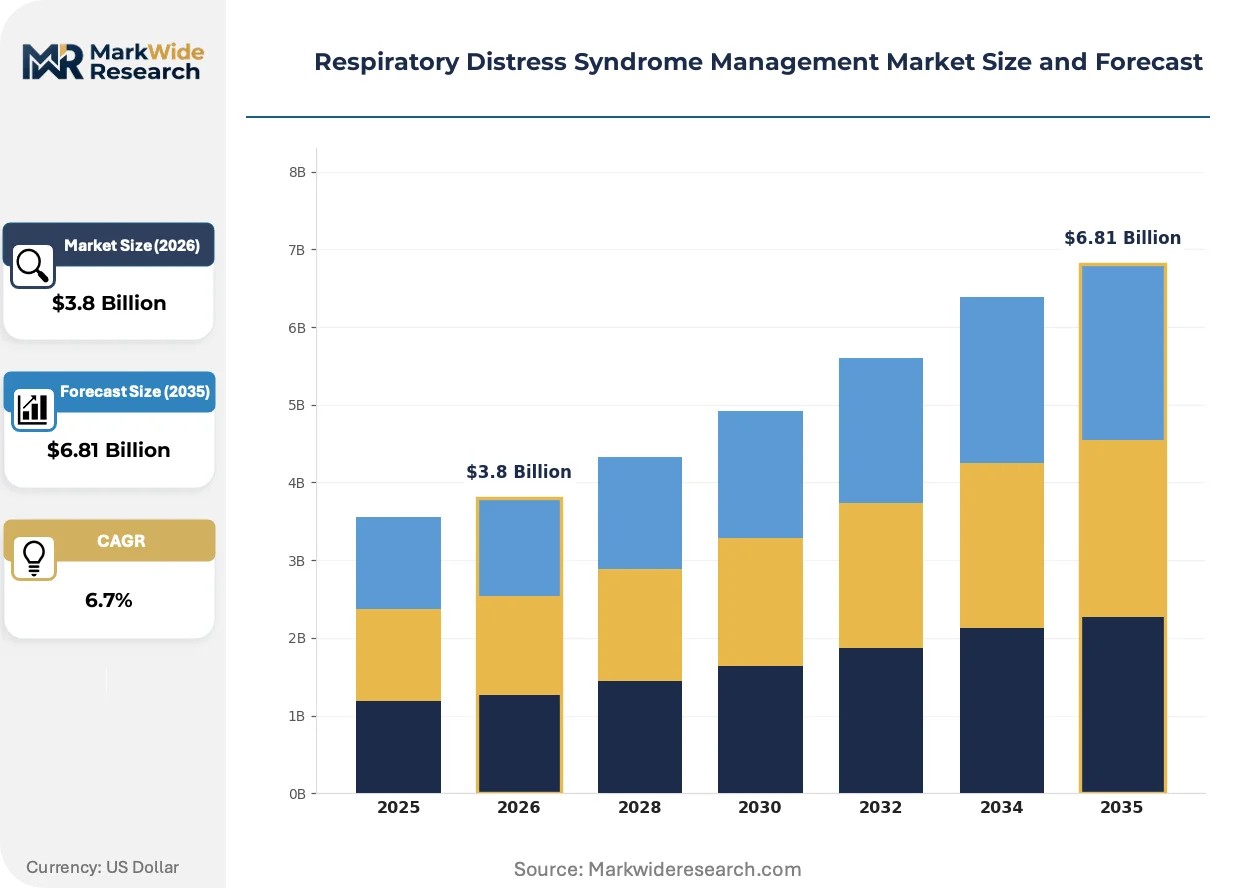
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Therapy Devices, Ventilators, Continuous Positive Airway Pressure, Nebulizers Therapy Area: Asthma, COPD, Acute Respiratory Distress Syndrome, Obstructive Sleep Apnea End User: Hospitals, Homecare Settings, Rehabilitation Centers, Emergency Services Delivery Mode: Inhalation, Intravenous, Subcutaneous, Oral |
| Companies Covered | Pfizer Inc., Novartis AG, GlaxoSmithKline plc, AbbVie Inc., AstraZeneca, Medtronic plc, Getinge AB, F. Hoffmann-La Roche Ltd, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Distress Syndrome Management Market Evolving Landscape
Computational approaches are displacing empirical protocols across respiratory care, with artificial intelligence and physics-based modeling converging to personalize ventilation parameters and surfactant dosing in real time.
Digital lung twin technology is virtualizing traditional ventilator management by creating patient-specific computational models that simulate alveolar recruitment responses before physical intervention. Academic medical centers in the United States and Germany are piloting these platforms for ARDS populations, compressing time-to-optimal PEEP settings from hours to minutes. This virtualization is reducing ventilation-induced lung injury incidence while enabling remote specialist oversight of distributed NICU networks.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic collection of real-world performance data across ventilator fleets, forcing manufacturers to embed connectivity modules as standard features rather than premium upgrades. Device companies are responding by restructuring service contracts to include continuous compliance monitoring, shifting revenue from capital sales to recurring data-subscription models. European tertiary care networks are experiencing the most acute compliance pressure, with German and French hospitals leading fleet modernization efforts.
Hospital procurement departments are unbundling ventilator hardware from multi-year service agreements, creating competitive pressure on aftermarket revenue streams that previously anchored manufacturer profitability. Standalone service providers and third-party maintenance firms are capturing disaggregated contracts in the United States, particularly among nonprofit health systems seeking operational flexibility. This unbundling is most pronounced in California and Texas, where consolidated purchasing cooperatives are driving standardization across member facilities.
Respiratory Distress Syndrome Management Market Segmentation
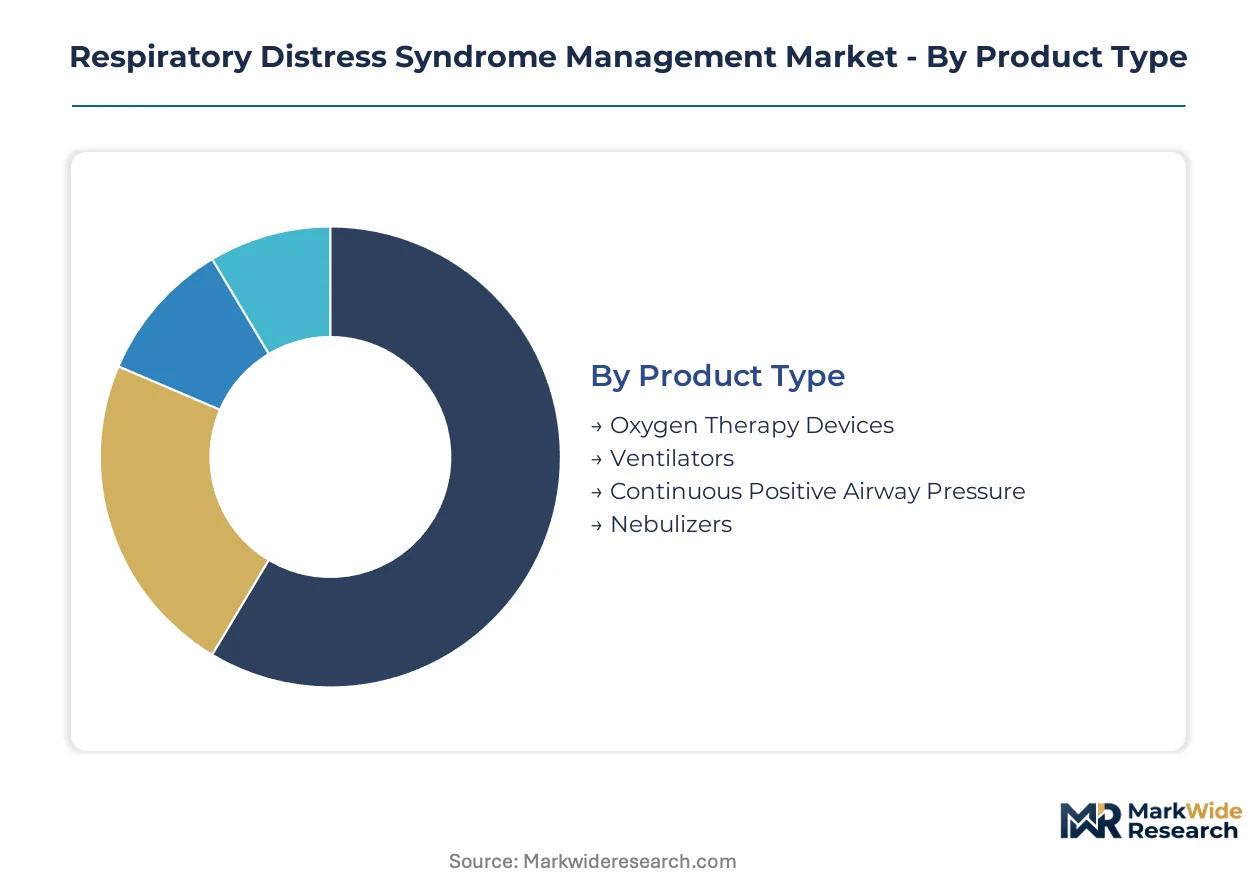
Segmentation in respiratory distress syndrome management reveals distinct procurement patterns across acute versus chronic care pathways. Product configuration, therapy intensity, and care setting determine reimbursement codes and capital allocation priorities.
Product Type:
Use-case spectrum spans from emergency stabilization through long-term home oxygen dependency, with device complexity scaling to clinical severity.
- Ventilators:Critical care platforms deliver precise tidal volume control and lung-protective ventilation protocols for NICU and ARDS populations. Tertiary hospitals in the United States concentrate procurement of these systems amid expanding pediatric ICU capacity.
- Oxygen Therapy Devices:Portable concentrators and high-flow delivery systems enable post-acute transitions to residential settings. Homecare agencies in Germany and Japan are scaling fleet deployments as reimbursement frameworks shift toward outpatient oxygen management.
- Continuous Positive Airway Pressure:Non-invasive pressure support systems reduce intubation rates in moderate respiratory distress cases. Secondary hospitals in India represent white-space demand for simplified CPAP platforms with reduced training requirements.
- Nebulizers:Aerosol delivery systems administer bronchodilators and surfactant formulations across pediatric and adult populations.
Ventilators dominate installed base. Oxygen Therapy Devices is where expansion concentrates.
Therapy Area:
Cost tier stratification separates intensive care dependency from outpatient diagnostic throughput.
- Acute Respiratory Distress Syndrome:Life-threatening pulmonary inflammation demands mechanical ventilation with fractional inspired oxygen titration and prone positioning protocols. Academic medical centers in Germany and the United States anchor demand for integrated ECMO-surfactant capabilities.
- Obstructive Sleep Apnea:Chronic upper airway collapse generates high-volume CPAP and BiPAP prescriptions through sleep medicine clinics. Diagnostic pathways in Japan and Australia are expanding home-based polysomnography to reduce hospital backlog.
- COPD:Progressive airflow limitation requires long-term oxygen therapy and non-invasive ventilation during acute exacerbations.
- Asthma:Reversible bronchospasm management relies on metered-dose inhalers and nebulized corticosteroids across pediatric emergency departments.
Acute Respiratory Distress Syndrome commands premium pricing tiers. Obstructive Sleep Apnea is climbing the fastest on volume throughput.
End User:
Customer type determines device portability requirements, training intensity, and service contract structures.
- Hospitals:Tertiary NICUs and medical ICUs procure integrated ventilation-surfactant systems with 24/7 technical support. United States health systems are consolidating purchasing through regional cooperatives in California and Texas.
- Homecare Settings:Skilled nursing agencies and durable medical equipment suppliers manage portable oxygen concentrator fleets. Japan's Ministry of Health is expanding reimbursement for home-based respiratory therapy to reduce hospital readmission.
- Rehabilitation Centers:Post-acute facilities wean patients from mechanical ventilation through progressive exercise tolerance protocols.
- Emergency Services:Pre-hospital providers deploy transport ventilators and CPAP systems for field stabilization.
Hospitals retain capital expenditure concentration. Homecare Settings is gaining share fastest on policy-driven discharge acceleration.
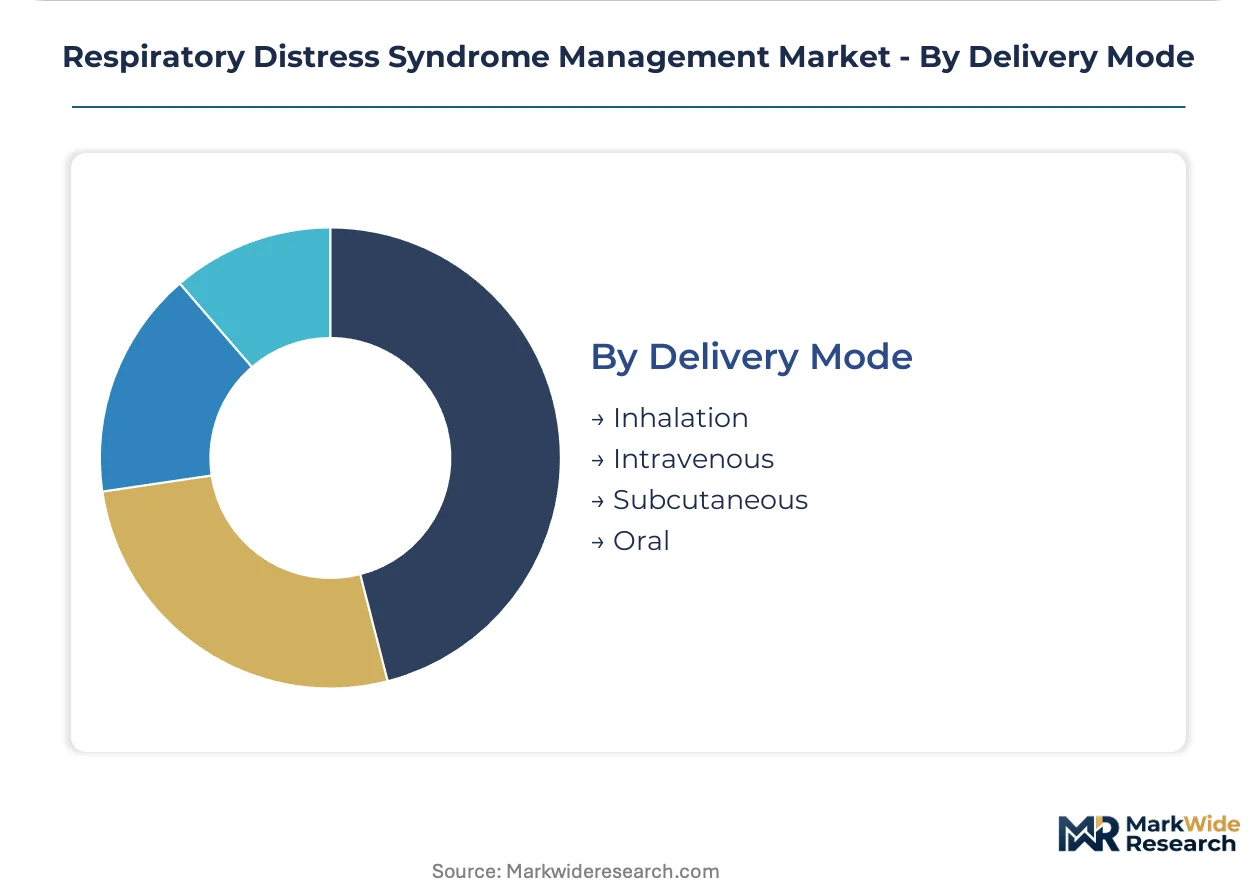
Delivery Mode:
Pharmacokinetic requirements and patient compliance shape administration pathway selection.
- Inhalation:Direct alveolar deposition of surfactant and bronchodilators via nebulization or intratracheal instillation. Premature neonates in United States NICUs represent the primary population for exogenous surfactant aerosolization.
- Intravenous:Systemic corticosteroids and vasopressors support hemodynamic stability in ARDS with refractory hypoxemia. European intensive care protocols emphasize early intravenous methylprednisolone for COVID-19-related respiratory failure.
- Subcutaneous:Maintenance biologics for severe asthma target IL-5 and IgE pathways through patient self-administration.
- Oral:Chronic COPD maintenance relies on long-acting muscarinic antagonists and phosphodiesterase-4 inhibitors.
Inhalation anchors neonatal surfactant administration. Intravenous is expanding most quickly on ARDS pharmacotherapy protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone membrane production concentrates in Germany and Switzerland, exposing ventilator manufacturers to input bottlenecks while shaping regional procurement patterns. Tertiary hospital networks in high-income markets anchor demand for integrated ventilation-surfactant systems. Regulatory divergence between FDA pediatric exclusivity pathways and EU MDR recertification timelines is fragmenting product launch sequencing across jurisdictions.
United States
Premature birth rates and NICU infrastructure investment outpace other national markets, sustaining demand for lung-protective ventilation platforms. The FDA's breakthrough therapy designations and pediatric exclusivity incentives accelerate surfactant formulation trials while tightening post-market surveillance for mechanical devices. Academic medical centers in Boston and California pilot digital lung twin technology for ARDS populations, compressing time-to-optimal PEEP settings.
Germany
Specialized neonatal ventilation platforms dominate European tertiary care networks, with Drägerwerk AG & Co. KGaA anchoring regional supply chains. The EU MDR recertification timeline forces device manufacturers to consolidate technical documentation, delaying platform updates while mandating embedded connectivity modules. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate medical-grade polymer production for ventilator circuits.
Japan
The PMDA's Sakigake designation accelerates market access for neonatal respiratory innovations, offering first-mover positioning for surfactant-device combination products. Homecare agencies scale portable oxygen concentrator deployments as the Ministry of Health expands reimbursement for residential respiratory therapy. Diagnostic pathways in Tokyo and Osaka advance home-based polysomnography to reduce hospital backlog for sleep apnea management.
India
Underpenetrated secondary hospitals present white-space demand for cost-optimized CPAP systems with simplified training protocols. The country's national pharmaceutical regulator oversees surfactant formulation imports while state-level health missions expand rural NICU networks. Industrial corridors in Maharashtra and Gujarat assemble basic ventilation platforms for domestic hospital procurement.
Respiratory Distress Syndrome Management Market Competitive Landscape
Diversified medical technology conglomerates and specialized respiratory device fabricators split the market across capital equipment and pharmaceutical agent domains. The installed base of critical care ventilators anchors recurring service contracts that shape hospital purchasing decisions, while aftermarket unbundling creates entry points for third-party maintenance providers. Two archetypes dominate: integrated critical care platform suppliers with deep NICU relationships, and focused surfactant formulation specialists leveraging orphan drug incentives. Competitive intensity concentrates on M&A consolidation of ventilation-surfactant capabilities and geographic expansion into underpenetrated Asian markets.
Within the diversified medical technology tier, Medtronic plc and Drägerwerk AG & Co. KGaA exemplify platform-centric positioning through critical care ventilation infrastructure and neonatal specialization respectively. Among pharmaceutical-centric participants, Pfizer Inc. and Novartis AG occupy positions shaped by surfactant development pipelines and pediatric exclusivity strategies. Getinge AB represents the acute care systems archetype with perfusion technology integration capabilities. These entities collectively illustrate how regulatory incentives and installed base economics determine competitive mobility across the respiratory intervention landscape.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| AbbVie Inc. |
| AstraZeneca |
| Medtronic plc |
| Getinge AB |
| F. Hoffmann-La Roche Ltd |
| Drägerwerk AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Undercapacity in medical-grade silicone membrane fabrication across German and Swiss industrial clusters is compressing supplier margins while amplifying pricing power for ventilator circuit manufacturers serving tertiary NICU networks.
Pricing Analysis
The FDA's pediatric exclusivity incentives dictate the pricing tier structure across surfactant replacement therapies, creating premium positioning for breakthrough-designated formulations against standard-of-care alternatives. Three-tier pricing structure across premium, standard, and economy levels separates lung-protective ventilation platforms with embedded connectivity modules from basic CPAP systems and refurbished fleet deployments. Cost compression in economy-tier concentrators is intensifying because homecare agencies in Japan and Germany are consolidating purchasing through regional cooperatives. Secondary hospitals in India exhibit the highest price sensitivity due to state-level health mission budget constraints, while academic medical centers in Boston and California demonstrate lowest sensitivity given NIH-funded research procurement protocols.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are now standard for ventilator OEMs sourcing from Baden-Württemberg polymer specialists, straining working capital across mid-tier device assemblers. Medical-grade silicone membrane production concentrates in Germany and Switzerland, with industrial clusters in North Rhine-Westphalia anchoring specialty polymer compounding for neonatal ventilation circuits. Raw material dependencies center on platinum-cured silicone elastomers, polycarbonate housing resins, and precision-machined aluminum flow sensors. Single-source vulnerability in platinum catalyst supply creates exposure to precious metal price volatility. Distribution runs through hospital GPO contracts in the United States, direct tender awards in Germany, and state-level health mission procurement in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through pediatric exclusivity and orphan drug incentives creates sustained incumbent advantage against substitution threats.
For Market Incumbents: Entrench installed base economics by embedding predictive analytics modules as standard features rather than premium upgrades, converting capital sales to recurring data-subscription revenue. Deepen backward integration into medical-grade silicone membrane production to neutralize supply bottlenecks from German and Swiss suppliers. High-flow nasal cannula substitution for moderate respiratory distress cases represents the primary displacement threat requiring preemptive portfolio repositioning.
For New Entrants and Emerging Players: Rural secondary hospitals in Maharashtra and Gujarat present the most penetrable white-space for cost-optimized CPAP platforms with simplified training protocols and localized service networks. Japan's Sakigake designation pathway offers accelerated positioning for surfactant-device combination products targeting neonatal respiratory innovation gaps. A partnership-first go-to-market model with state-level health missions bypasses entrenched GPO relationships dominating tertiary procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ventilator fleet operators with embedded connectivity compliance modules mandated by EU MDR post-market surveillance requirements. The 5-10 year viability window favors targets with demonstrated FDA breakthrough therapy designations and active pediatric investigation plans. Watch for inflection signals in Japan's reimbursement expansion for home-based respiratory therapy, which would accelerate portable oxygen concentrator deployment multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Deep NICU relationships with 24/7 technical support anchor multi-year service contract renewals. |
| FDA Submission | Breakthrough therapy designation accelerates surfactant formulation trials ahead of pediatric exclusivity windows. |
| CE Marking Pathway | EU MDR recertification compliance with embedded connectivity modules enables European tertiary care network access. |
| Software Companion Development | Digital lung twin integration compresses time-to-optimal PEEP settings for ARDS populations. |
| Reimbursement Strategy | Japan's Ministry of Health residential therapy expansion reduces hospital readmission costs for homecare agencies. |
Research Methodology
Initial hypotheses were tested against primary input from neonatologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EMA pediatric investigation plans, ClinicalTrials.gov surfactant protocol registries, and CMS Medicare durable medical equipment claims data. Bottom-up demand modeling across therapy area segments triangulated with top-down market sizing from ventilator installed base audits and surfactant formulation shipment records.
Demand-supply balance dynamics across the analysis window anchored the quantitative framework, with segmentation modeling across product type, therapy intensity, care setting, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and replacement cycle analysis. Industry-specific forecast inputs incorporated NICU bed capacity expansion timelines from United States hospital construction databases and Japan's Ministry of Health reimbursement schedule revisions.
Practitioners should monitor FDA pediatric exclusivity incentive modifications, EU MDR post-market surveillance enforcement intensity, and PMDA Sakigake designation throughput for early signals of competitive mobility shifts. Forecasts reflect assumptions about sustained premature birth rate trajectories and hospital infrastructure investment continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Lung Injury Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Emphysema Market