
 Aspirin Exacerbated Respiratory Disease Market | 2026-2036
Aspirin Exacerbated Respiratory Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Aspirin Exacerbated Respiratory Disease Market Outlook
Biologic formulations are expanding their share of the AERD treatment landscape, displacing chronic corticosteroid dependence in moderate-to-severe patient cohorts. Sanofi leverages its Dupixent franchise to anchor biologic penetration in type 2 inflammatory asthma overlapping with AERD. Regeneron Pharmaceuticals sustains R&D intensity through co-development pipelines targeting IL-4Rα blockade. AstraZeneca competes with Fasenra positioning in eosinophil-driven respiratory disease subsets.
Aspirin Exacerbated Respiratory Disease constitutes a severe asthma phenotype characterized by cysteinyl leukotriene overproduction, nasal polyposis, and bronchoconstriction triggered by cyclooxygenase-1 inhibition, typically managed through leukotriene receptor antagonists, 5-lipoxygenase inhibitors, and escalating biologic intervention. The therapy area segments reveal respiratory disorders and asthma management commanding the largest patient volumes, while allergy treatment represents the fastest-growing addressable subset as desensitization protocols and biologic co-administration expand. Inhalation powder within delivery mode segments occupies the premium margin tier due to device complexity and formulation stability requirements, whereas oral tablets dominate volume through generic accessibility.
FDA oversight through the Center for Drug Evaluation and Research shapes biologic approval standards for respiratory indications, while EMA's Committee for Medicinal Products for Human Use enforces parallel efficacy benchmarks across European markets. The EPA regulates environmental allergen exposure thresholds that indirectly influence AERD exacerbation frequency and treatment intensity. Stakeholders must monitor evolving payer criteria for step-therapy prior authorization as biologic eligibility narrows to documented eosinophil counts and exacerbation history thresholds.
Market Dynamics
Biologic monoclonal antibodies are restructuring the AERD treatment hierarchy by displacing chronic corticosteroid dependence in moderate-to-severe patient cohorts. FDA accelerated approval pathways for respiratory biologics compress competitive entry timelines and reshape prescriber behavior.
Growth Catalysts
- Specialist Network Density:United States pulmonology referral centers concentrate diagnostic capacity for Samter's Triad, driving advanced therapy uptake in severe asthma phenotypes.
- EMA Parallel Scientific Advice:Coordinated FDA-EMA development programs compress regulatory timelines for biologic respiratory candidates targeting cysteinyl leukotriene pathways.
- Eosinophil Biomarker Adoption:Blood count thresholds standardize patient stratification, expanding reimbursable biologic eligibility criteria across commercial and Medicare payers.
Market Restraints
- Biologic Manufacturing Concentration:Contract development organizations cluster in Switzerland and Massachusetts, creating single-source vulnerability for monoclonal antibody supply.
- Refractory Polyposis Surgery Rates:Endoscopic sinus procedures remain fallback for biologic non-responders, fragmenting chronic disease management revenue pools.
- Step-Therapy Authorization Burden:Prior authorization requirements for documented exacerbation history delay biologic initiation by months in managed care populations.
Strategic Opportunities
- Pediatric Label Expansion:Uncontrolled severe asthma in adolescents represents an underpenetrated cohort where biologic penetration lags adult benchmarks.
- Subcutaneous Formulation Preference:Self-administration protocols reduce infusion center dependency and expand addressable geography beyond academic medical centers.
- Desensitization Protocol Integration:Aspirin desensitization combined with biologic co-administration opens allergy clinic channels previously outside respiratory specialty reach.
Industry Challenges
- Biomarker Testing Infrastructure:FeNO and eosinophil count availability varies across community pulmonology practices, creating patient identification gaps.
- Real-World Evidence Generation:Post-marketing studies for respiratory biologics require multi-year follow-up to demonstrate polyposis recurrence prevention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aspirin Exacerbated Respiratory Disease Market |
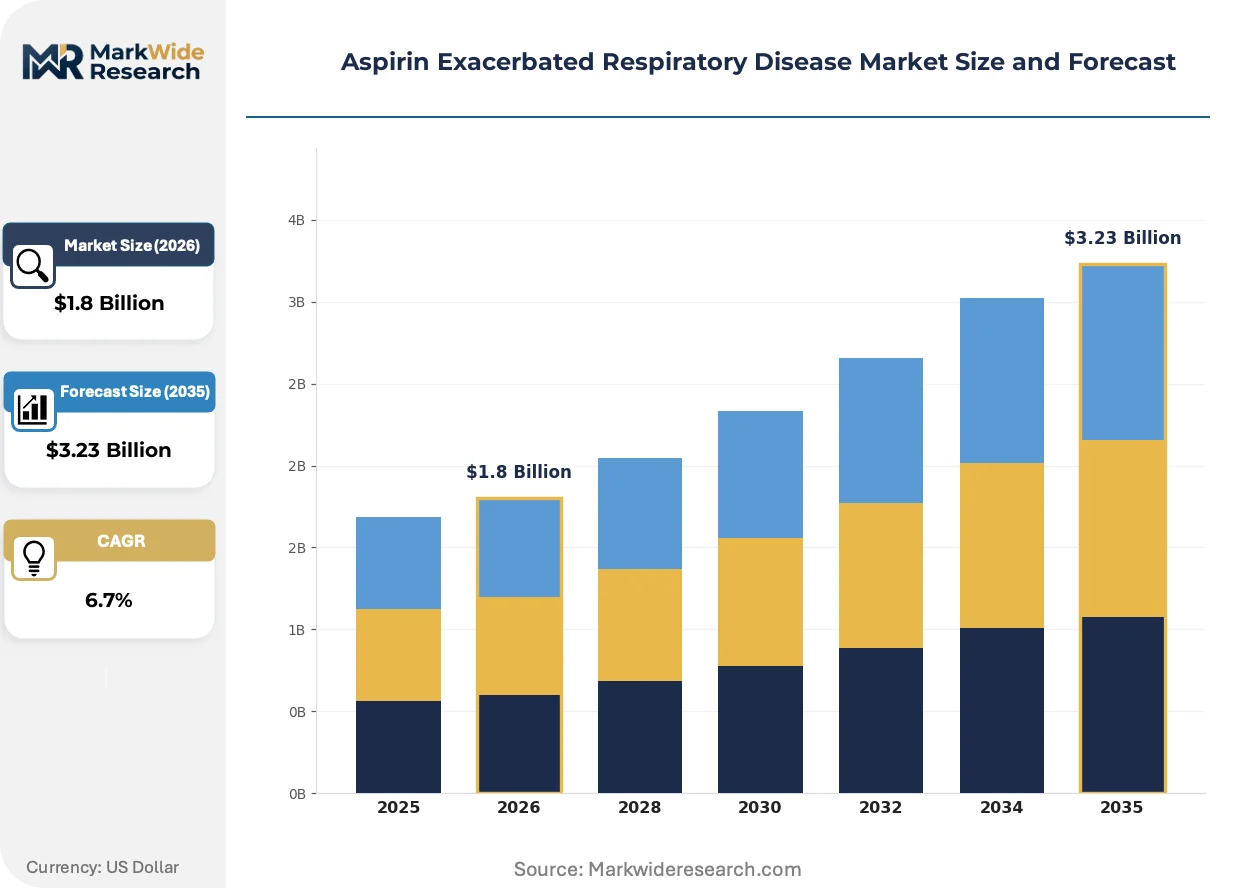
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Solution, Inhalation Powder Therapy Area: Respiratory Disorders, Allergy Treatment, Chronic Sinusitis, Asthma Management End User: Hospitals, Clinics, Pharmacies, Homecare Settings Delivery Mode: Oral, Inhalation, Injectable, Topical |
| Companies Covered | Sanofi, Regeneron Pharmaceuticals, GlaxoSmithKline, AstraZeneca, Novartis, Teva Pharmaceuticals, Amgen, Pfizer, Boehringer Ingelheim Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aspirin Exacerbated Respiratory Disease Market Strategic Shifts
Delivery technology convergence and diagnostic biomarker standardization are compressing the gap between identification and intervention for severe AERD phenotypes. These shifts alter how therapies reach patients and how payers evaluate value.
Dual-acting bronchodilator-inhalation corticosteroid fixed-dose combinations are modularizing maintenance therapy protocols across severe asthma populations. Community pulmonology practices in Germany and the United Kingdom adopt these platforms at accelerating rates. Device-agnostic formulation stability is modularizing supply chain flexibility, reducing pharmacy inventory complexity for multi-product respiratory portfolios.
REACH authorization requirements for propellant chemistry are forcing hydrofluoroalkane transition timelines in metered-dose inhaler portfolios. Industrial consequence includes accelerated investment in dry powder and soft mist alternatives across European manufacturing networks. Eosinophil-directed biologics face additional environmental footprint scrutiny under EU Green Deal pharmaceutical sector benchmarks, with Switzerland and Denmark implementing early disclosure mandates.
Specialist referral patterns are compressing diagnostic intervals for Samter's Triad through integrated allergy-immunology and pulmonology service lines. Academic medical centers in Boston and Philadelphia consolidate these functions, displacing fragmented community-based evaluation. United Kingdom NHS long-term plan incentives accelerate this consolidation, tying respiratory outcome metrics to integrated care system funding.
Aspirin Exacerbated Respiratory Disease Market Segmentation
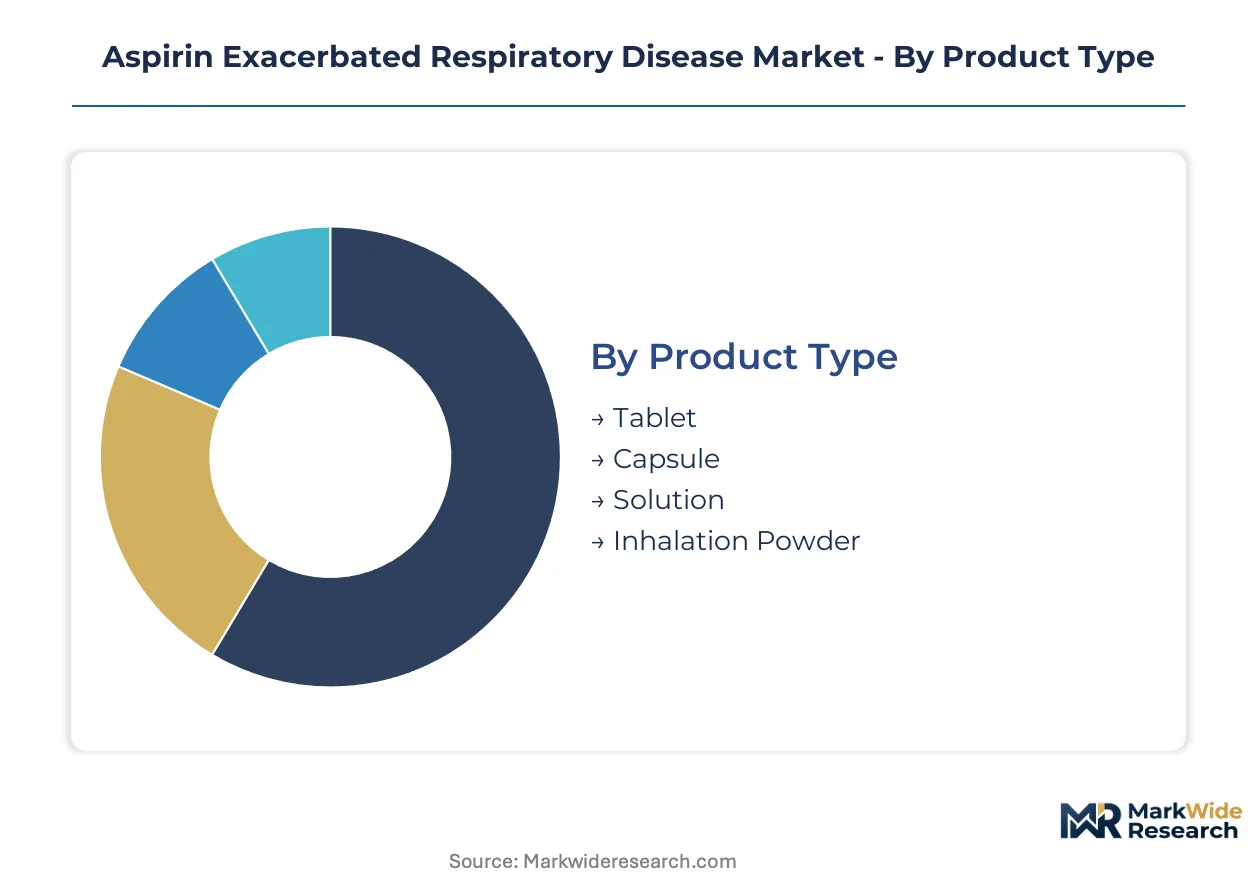
Segmentation in the Aspirin Exacerbated Respiratory Disease market reflects divergent clinical workflows across acute intervention and chronic maintenance settings. Product form factors and delivery technologies must align with prescriber specialty, patient self-management capacity, and reimbursement tier.
Product Type:
Standardized oral solid doses dominate volume manufacturing, while specialized inhalation formats command premium positioning through device-integrated complexity.
- Tablet:Compressed oral solids enable high-throughput production and stable shelf-life profiles. Demand concentrates in community pharmacy dispensing for leukotriene receptor antagonist maintenance therapy, constrained by generic price compression.
- Inhalation Powder:Dry powder inhalers require sophisticated formulation engineering for particle size distribution and device-actuation consistency. Prescriber concentration in United States academic pulmonology centers drives adoption for biologic-naive patients stepping up from metered-dose platforms.
- Capsule:Gelatin or HPMC shells accommodate moisture-sensitive actives with modified-release kinetics. Manufacturing scales efficiently across contract development organizations in Switzerland and Massachusetts.
- Solution:Liquid formulations serve pediatric and geriatric populations with swallowing difficulties. Hospital formulary placement depends on unit-dose packaging compliance.
Most installed capacity flows through Tablet. Expansion is steepest in Inhalation Powder.
Therapy Area:
Application intensity varies by disease chronicity, with acute exacerbation management demanding rapid-onset formats against long-term polyposis prevention protocols.
- Asthma Management:Severe eosinophilic phenotypes represent the primary reimbursable indication for IL-4Rα and IL-5 biologic intervention. United States specialist networks concentrate diagnostic capacity for Samter's Triad identification.
- Respiratory Disorders:Broad category capturing chronic bronchoconstriction and airway hyperresponsiveness beyond classical asthma definitions. Community pulmonology practices in Germany and the United Kingdom drive maintenance therapy volumes.
- Chronic Sinusitis:Nasal polyp recurrence prevention requires sustained anti-inflammatory exposure. Endoscopic surgery fallback fragments pharmaceutical revenue capture for refractory cases.
- Allergy Treatment:Aspirin desensitization protocols combined with biologic co-administration are expanding allergy clinic channel access. This segment is gaining share fastest as integrated care models consolidate referral pathways.
Revenue concentration sits with Asthma Management. Steepest climb occurs in Allergy Treatment.
End User:
Channel economics diverge sharply between institutional procurement with formulary committees and direct-to-patient dispensing with prior authorization burden.
- Hospitals:Inpatient admission for acute bronchospasm drives high-unit-cost biologic utilization. Academic medical centers in Boston and Philadelphia anchor severe phenotype referral networks.
- Homecare Settings:Self-administered subcutaneous biologics reduce infusion center dependency. Patient training infrastructure varies across Medicare Advantage plan geographies.
- Clinics:Outpatient specialist practices manage step-therapy documentation for commercial payer authorization. Eosinophil count availability constrains patient identification in community settings.
- Pharmacies:Retail dispensing handles generic leukotriene modifier maintenance with minimal clinical intervention. 90-day supply mandates compress dispensing frequency.
Volume throughput peaks at Hospitals. Addressable geography is expanding most quickly in Homecare Settings.
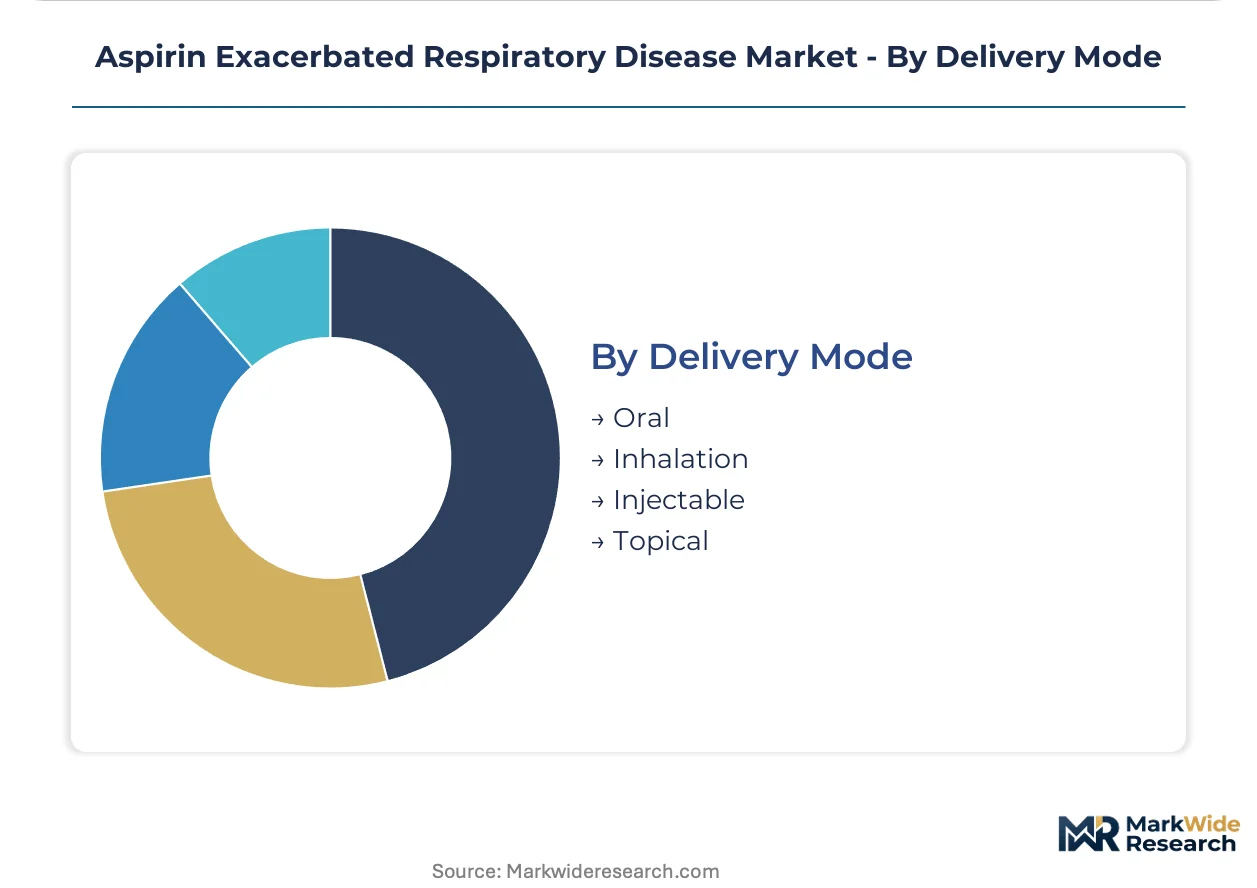
Delivery Mode:
Margin structure inverts between high-volume oral generics and low-volume injectable biologics with cold-chain complexity.
- Injectable:Subcutaneous monoclonal antibodies require refrigerated distribution and patient training for self-administration. FDA Center for Drug Evaluation and Research oversees batch release testing for respiratory biologics.
- Inhalation:Pulmonary deposition efficiency depends on device mechanics and patient technique standardization. REACH authorization timelines for hydrofluoroalkane propellants are forcing dry powder investment across European manufacturing.
- Oral:Gastrointestinal absorption kinetics limit bioavailability for cysteinyl leukotriene pathway targets. Generic accessibility sustains volume leadership despite efficacy ceiling.
- Topical:Nasal corticosteroid sprays serve adjuvant polyp management with limited systemic exposure. Compliance drops off with chronic use duration.
Patient volume concentrates in Oral. Value capture is climbing fastest in Injectable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pulmonology networks anchor diagnostic capacity for Samter's Triad, with academic medical centers in Boston and Philadelphia driving biologic therapy uptake through integrated allergy-immunology referral pathways.
United States
Specialist referral density concentrates in Massachusetts and Pennsylvania, where cysteinyl leukotriene pathway biologics command premium reimbursement through Medicare Advantage step-therapy frameworks. FDA Center for Drug Evaluation and Research maintains accelerated approval pathways for respiratory monoclonal antibodies. Boston anchors severe asthma phenotype research through consolidated academic pulmonology service lines.
Germany
Community pulmonology practices in Bavaria and North Rhine-Westphalia drive maintenance therapy volumes for dual-acting bronchodilator-inhalation corticosteroid combinations. EMA Committee for Medicinal Products for Human Use enforces parallel efficacy benchmarks for biologic respiratory candidates. The Rhine-Ruhr industrial corridor hosts contract manufacturing organizations supplying dry powder inhaler components across European markets.
United Kingdom
NHS long-term plan incentives tie respiratory outcome metrics to integrated care system funding, consolidating allergy-pulmonology referral pathways in London and Manchester. MHRA operates post-Brexit recognition procedures for EMA-approved respiratory biologics. The Southeast England cluster accelerates diagnostic biomarker standardization through specialist commissioning frameworks.
Japan
PMDA review timelines for IL-4Rα and IL-5 biologics compress competitive entry for severe eosinophilic asthma phenotypes. METI industrial policy supports domestic inhalation device manufacturing in the Osaka-Kobe corridor. Tokyo academic medical centers lead real-world evidence generation for nasal polyp recurrence prevention protocols.
Switzerland
Swissmedic enforces batch release testing standards for subcutaneous biologics distributed across European markets. Basel and Zürich concentrate contract development organization capacity for monoclonal antibody manufacturing. The country's pharmaceutical sector faces early disclosure mandates under EU Green Deal environmental footprint benchmarks.
Aspirin Exacerbated Respiratory Disease Market Competitive Environment
Global majors compete with regional champions across biologic development and respiratory device manufacturing. The market structures around three tiers: integrated pharmaceutical conglomerates with respiratory franchises, biotechnology specialists co-developing monoclonal antibodies, and generic manufacturers supplying leukotriene modifier maintenance therapy. Strategic moves concentrate on pediatric label expansion for severe asthma cohorts and subcutaneous formulation development to reduce infusion center dependency.
Within the integrated pharmaceutical tier, Sanofi and AstraZeneca occupy positions anchored by biologic respiratory franchises, while Regeneron Pharmaceuticals exemplifies the biotechnology specialist model through co-development pipelines targeting type 2 inflammatory pathways. These companies represent divergent approaches to addressing cysteinyl leukotriene-driven disease mechanisms.
| Leading Market Players |
|---|
| Sanofi |
| Regeneron Pharmaceuticals |
| GlaxoSmithKline |
| AstraZeneca |
| Novartis |
| Teva Pharmaceuticals |
| Amgen |
| Pfizer |
| Boehringer Ingelheim Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Academic medical center procurement committees in the United States concentrate purchasing power for biologic respiratory therapies, anchoring value-based contracting models that tie reimbursement to documented exacerbation reduction and eosinophil threshold compliance.
Pricing Analysis
Input-cost pass-through from monoclonal antibody manufacturing runs through Swiss and Massachusetts contract development organizations, elevating unit costs for subcutaneous biologics against oral generic alternatives. Three-tier pricing structure across biologic premium, device-integrated standard, and generic economy levels segments patient access by insurance tier and prior authorization burden. Pricing pressure stems from Medicare Advantage step-therapy requirements that delay biologic initiation until documented corticosteroid failure. Community pulmonology practices exhibit highest price sensitivity due to formulary constraints, while academic referral centers maintain lowest sensitivity through bundled outcome contracts.
Supply Chain Analysis
FDA batch release certification and EMA parallel scientific advice gating concentrates monoclonal antibody manufacturing in Switzerland, Massachusetts, and the Rhine-Ruhr corridor, with cold-chain distribution tethered to these hubs. Active pharmaceutical ingredient supply draws from Irish fermentation capacity and Singapore biologics processing for IL-4Rα and IL-5 pathway targets. Single-source vulnerability at Swiss contract manufacturing organizations for subcutaneous formulation fill-finish creates structural risk. Distribution runs through specialty pharmacy networks with patient training infrastructure, bypassing retail channels for biologic delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologics manufacturing cost differentials between Swiss high-regulation environments and emerging Singapore capacity create geographic-arbitrage opportunities for respiratory monoclonal antibody production.
For Market Incumbents: To counter biosimilar entry pressure from Korean and Indian contract manufacturers, anchor defensive positioning through backward integration into fill-finish capacity in Basel and Singapore. Prioritize pediatric label expansion for severe asthma cohorts where biologic penetration lags adult benchmarks, securing orphan exclusivity windows against follower molecules. For New Entrants and Emerging Players: FDA accelerated approval pathways for respiratory biologics open a window for cysteinyl leukotriene pathway candidates with biomarker-enriched trial designs. Target allergy clinic channels in the United Kingdom and Germany where aspirin desensitization protocols integrate with biologic co-administration. Pursue subcutaneous formulation development to reduce infusion center dependency and expand addressable geography beyond academic medical centers. For Investors and Strategic Acquirers: Large-cap respiratory franchises at integrated pharmaceutical conglomerates are the most active acquirer in this space, seeking biologic pipeline fill through mid-stage monoclonal antibody assets. Five-to-ten year viability hinges on sustained biomarker adoption for eosinophil-directed patient stratification. Watch for PMDA approval timelines in Japan as inflection indicator for Asia-Pacific competitive entry compression.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Label Expansion | Orphan exclusivity in adolescent severe asthma captures undertreated cohorts ahead of biosimilar entry. |
| Subcutaneous Formulation Development | Self-administration protocols reduce dependency on Boston and Philadelphia infusion center networks. |
| EMA Parallel Scientific Advice | Coordinated FDA-EMA programs compress regulatory timelines for cysteinyl leukotriene pathway candidates. |
| Allergy Clinic Channel Partnership | Desensitization protocol integration opens Manchester and London referral pathways outside pulmonology. |
| Biomarker Testing Infrastructure Investment | FeNO and eosinophil count availability in community practices expands reimbursable patient identification. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient volume estimates by severity phenotype and top-down biologic revenue triangulation anchored market sizing across the analysis window.
Historical reference periods spanning pre-biologic standard-of-care eras through current monoclonal antibody penetration established baseline growth trajectories. Segmentation modeling captured therapy area, delivery mode, product type, and regional regulatory cluster dimensions. CAGRs derived from exponential smoothing of annual prescription volumes and price deflation curves, with forecast inputs incorporating biomarker adoption rates and prior authorization approval velocity by payer type.
Revisions become necessary when FDA approval pathway changes, biosimilar launch timelines, or reimbursement policy shifts materialize. Forecasts reflect assumptions about eosinophil testing infrastructure expansion and step-therapy burden stability. A model refresh is warranted upon material change in Medicare Advantage biologic access criteria or EMA parallel scientific advice throughput capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market