
 Global Respiratory Care Devices Market | 2026-2036
Global Respiratory Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Respiratory Care Devices Market Outlook
Connected sensor integration and cloud-based remote patient monitoring is rewriting how respiratory devices deliver care beyond clinical walls. ResMed Inc. leverages its digital health platform to sustain recurring revenue streams from sleep apnea management. Koninklijke Philips NV anchors its position through hospital-grade ventilator systems with embedded AI-driven weaning protocols. Drägerwerk AG & Co. KGaA differentiates via advanced turbine technology that competes on precision in critical care environments.
Respiratory care devices encompass mechanical ventilators, positive airway pressure systems, nebulizers, and oxygen delivery apparatus engineered to maintain or restore pulmonary function through precise gas exchange management, pressure-controlled airflow modulation, and medication aerosolization at therapeutic particle sizes typically between one and five micrometers. These systems serve acute intervention in intensive care units, chronic disease management for COPD and asthma patients, and nocturnal therapy for obstructive sleep apnea across hospital, clinic, and domiciliary settings. The ventilators segment dominates capital expenditure in acute care facilities where multi-parameter monitoring integration commands premium positioning, while the home care end-user channel captures the fastest structural expansion as reimbursement frameworks shift toward preventive outpatient models and portable oxygen concentrators displace stationary units. Sleep apnea application demand concentrates in North American and Western European markets where diagnostic penetration and therapy adherence programs have matured.
The FDA's Quality System Regulation and 510(k) premarket notification requirements shape device design controls and clinical validation burdens for US market access, while the EU Medical Device Regulation imposes stricter post-market surveillance and notified body oversight across European Economic Area distribution. Japan's Ministry of Health, Labour and Welfare through PMDA enforces country-specific electrical safety and electromagnetic compatibility standards that add certification layers for imported respiratory equipment. Stakeholders must monitor how divergent cybersecurity guidance for connected medical devices across FDA, EMA, and Japan's METI will reshape development roadmaps and regional launch sequencing.
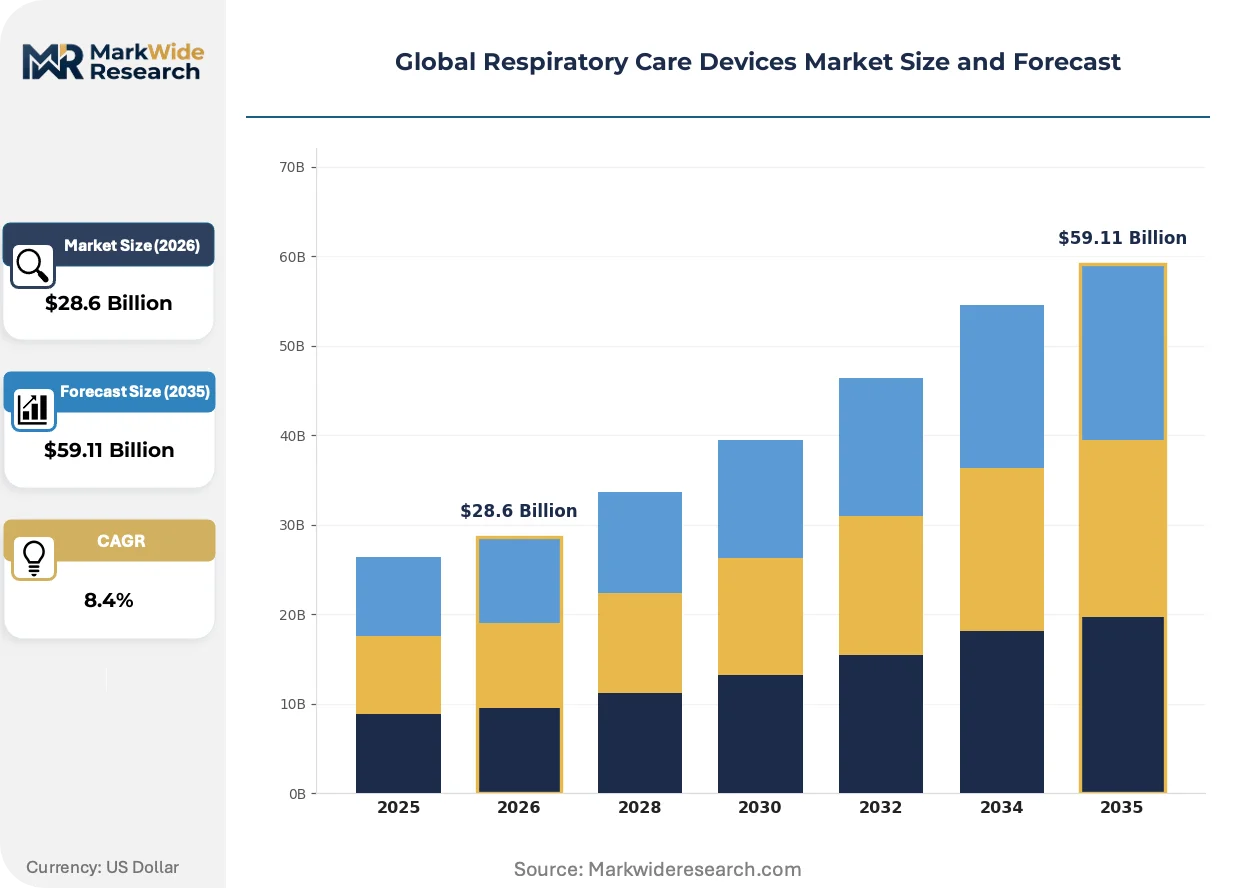
Market Dynamics
The migration of respiratory therapy from institutional settings to domiciliary environments is compressing equipment form factors and demanding seamless connectivity architectures. This structural shift forces manufacturers to reconcile clinical-grade performance with consumer-electronics usability standards.
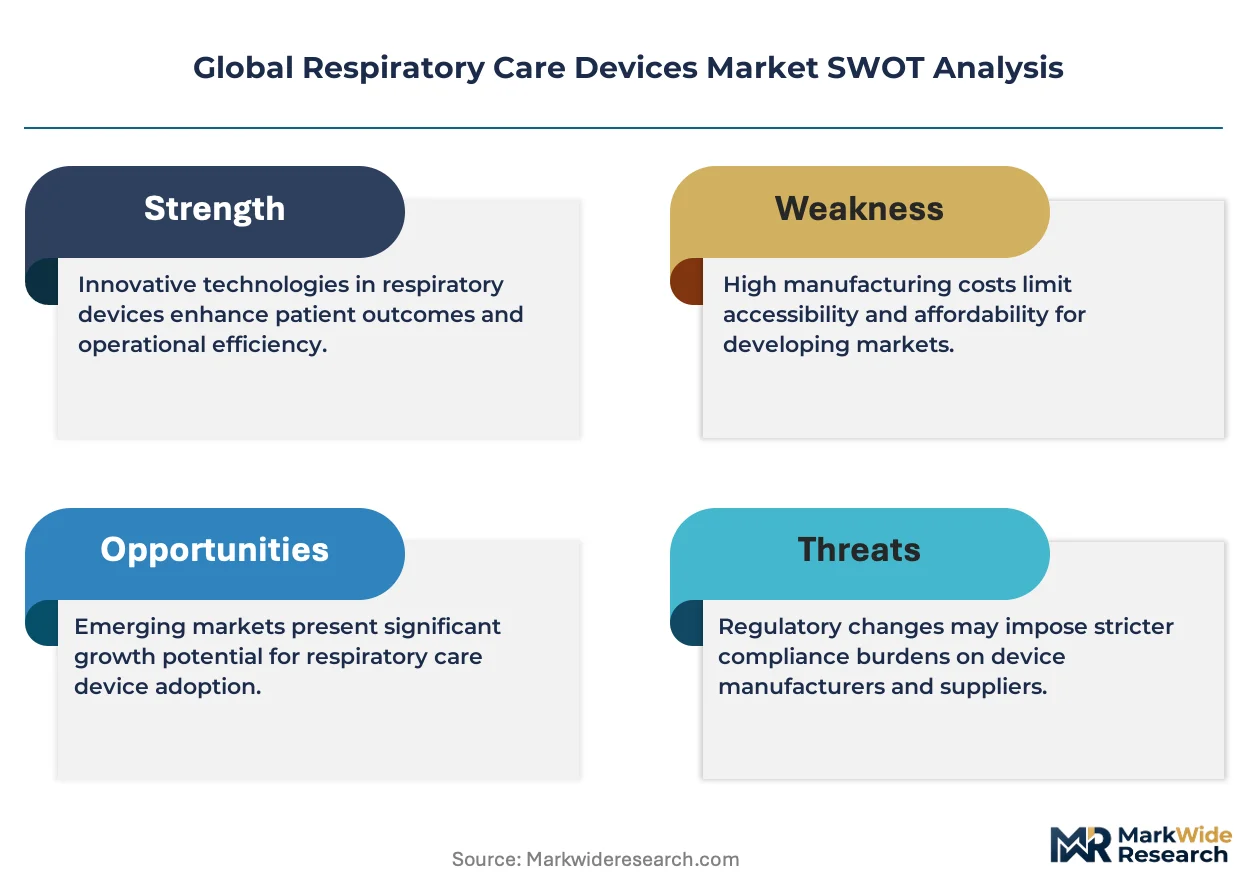
Growth Catalysts
- Japan's PMDA streamlined approval pathways:Accelerated market entry for connected oxygen concentrators targeting home care expansion.
- COPD prevalence clusters:Germany, the United States, and Japan exhibit concentrated chronic respiratory disease burdens driving sustained device procurement.
- Portable turbine miniaturization:Advances in compact compressor technology enable ambulatory oxygen delivery without stationary infrastructure.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fabrication dependencies create input volatility for ventilator control systems.
- FDA 510(k) clinical validation burdens:Substantial equivalence demonstrations for Class II respiratory devices extend development timelines and capital lockup.
- Stationary oxygen concentrator substitution:Cylinder-based liquid oxygen systems retain cost advantages in specific reimbursement environments.
Strategic Opportunities
- India's underpenetrated diagnostic infrastructure:Nascent sleep apnea screening programs create first-mover positioning for CPAP device deployment.
- EU MDR post-market surveillance mandates:Real-world performance data requirements favor manufacturers with embedded remote monitoring capabilities.
- Telehealth platform convergence:Integration of respiratory device data streams with virtual care workflows opens subscription revenue models.
Industry Challenges
- Embedded systems cybersecurity certification:FDA, EMA, and Japan METI divergent guidance on connected medical device hardening complicates unified product architectures.
- Biocompatibility testing timelines:ISO 18562 series validation for gas pathway materials extends regulatory submission preparation.
- Legacy hospital IT integration:HL7 FHIR interoperability requirements impose middleware development costs for device connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Respiratory Care Devices Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Nebulizers, CPAP Devices, Oxygen Concentrators End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Technology: Electronic, Manual, Portable, Robotic Application: Asthma, COPD, Sleep Apnea, Critical Care |
| Companies Covered | ResMed Inc., Invacare Corporation, Koninklijke Philips NV, Hamilton Medical, Teleflex, Medtronic, Drägerwerk AG & Co. KGaA, Masimo Corporation, Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Respiratory Care Devices Market Strategic Shifts
Respiratory device architectures are converging around sensor fusion and edge computing, enabling predictive intervention models that transcend reactive therapy delivery. This transformation redefines value capture from hardware margins to data-enabled service ecosystems.
Miniaturized MEMS flow sensors paired with machine learning inference at the device edge is hybridizing conventional ventilator and CPAP platforms into adaptive pressure-support systems. Home care providers in Germany and Japan are piloting these convergent architectures for nocturnal COPD management. The technology is compressing the distinction between acute and chronic respiratory support modalities.
EU MDR Article 10 post-market clinical follow-up obligations are mandating systematic real-world evidence collection across distributed device fleets. Manufacturers must now engineer automated data pipeline infrastructure as a core design requirement rather than aftermarket accessory. The sleep apnea segment faces particular scrutiny given long-term therapy adherence variability.
Hospital procurement committees are unbundling device acquisition from preventive maintenance contracts, favoring third-party service providers with multi-vendor certification capabilities. This disintermediation pressures original equipment manufacturers to defend recurring revenue through proprietary consumables and software licensing. The United States exhibits the most pronounced shift toward independent service organization competition.
Global Respiratory Care Devices Market Segmentation
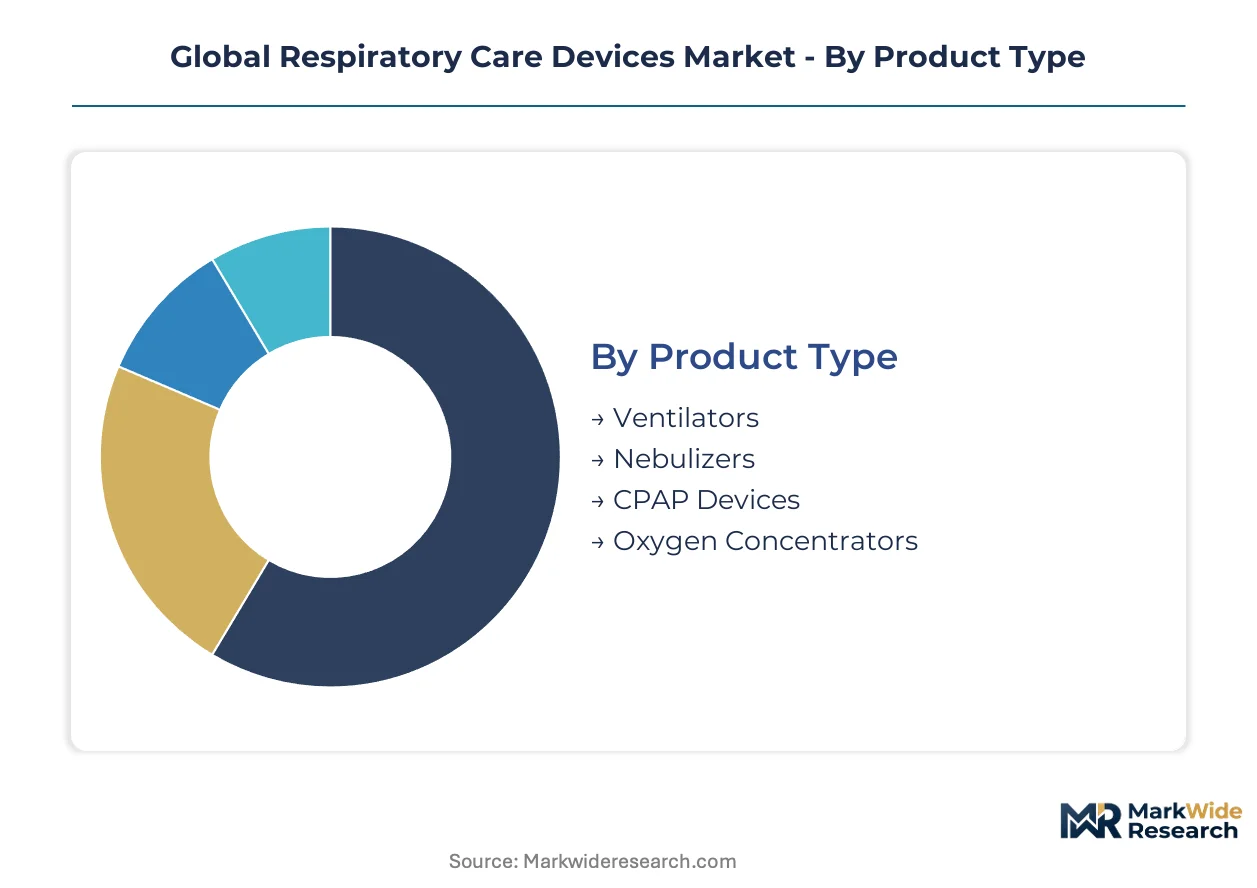
Respiratory device purchasing cycles vary dramatically across categories, with acute care equipment requiring decade-long capital planning while portable home care units turn over every 3-5 years. This divergence forces manufacturers to maintain parallel supply chains and service architectures optimized for fundamentally different replacement rhythms.
Product Type:
Ventilators command the longest procurement cycles at 7-10 years, while portable oxygen concentrators and CPAP devices refresh fastest as battery and sensor technologies advance.
- Ventilators:Electromechanical systems delivering precise tidal volume, PEEP, and FiO2 control through turbine or piston-driven gas compression. Intensive care units in Germany and Japan anchor demand as these countries expand critical care bed capacity to manage aging-related respiratory failure.
- CPAP Devices:Continuous positive airway pressure systems maintaining patent upper airways via algorithm-adjusted blower output. Sleep clinics across the United States drive replacement demand as diagnostic penetration deepens and insurance mandates shorten device depreciation schedules.
- Nebulizers:Compressor or ultrasonic-based medication aerosolization systems targeting 1-5 micrometer particle size for optimal alveolar deposition. Pediatric asthma management in Japanese outpatient settings sustains steady procurement volumes.
- Oxygen Concentrators:Pressure swing adsorption or membrane separation systems extracting medical-grade oxygen from ambient air. Stationary units dominate Indian hospital procurement while portable variants gain traction in German home care reimbursement frameworks.
Ventilators anchor the volume base while portable oxygen concentrators gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital infrastructure from consumer-accessible home care channels with divergent margin structures and regulatory burdens.
- Hospitals:Acute care facilities requiring FDA 510(k) cleared or EU MDR Class IIa/IIb certified devices with multi-parameter monitoring integration. German university hospitals and Japanese tertiary centers concentrate procurement of high-acuity ventilator systems.
- Home Care:Domiciliary settings demanding lightweight, battery-operated devices with cellular connectivity for remote adherence monitoring. United States Medicare reimbursement shifts toward preventive outpatient models accelerate this channel's expansion.
- Clinics:Outpatient respiratory therapy centers prioritizing rapid patient turnover and multi-condition device versatility. Pulmonary rehabilitation clinics in Japan favor nebulizer-integrated oxygen delivery systems.
- Long-term Care Facilities:Skilled nursing environments balancing clinical oversight with limited on-site technical expertise. German Pflegeheime increasingly specify simplified CPAP interfaces for dementia-competent staff operation.
Hospitals anchor the volume base while home care gains share fastest as reimbursement migrates toward preventive outpatient models.
Technology:
Application context determines technology selection, with critical care demanding precision electronic control while resource-limited settings retain manual alternatives.
- Electronic:Microprocessor-controlled systems with closed-loop feedback, touchscreen interfaces, and automated alarm management. FDA-cleared electronic ventilators dominate United States ICU procurement.
- Portable:Battery-optimized designs under 5 kilograms enabling ambulatory oxygen therapy and travel-compliant CPAP operation. German and Japanese regulatory frameworks for airborne medical devices shape certification requirements.
- Manual:Bag-valve-mask resuscitators and pneumatic nebulizers requiring operator skill rather than powered components. Emergency preparedness stockpiling across Indian district hospitals sustains residual demand.
- Robotic:Automated mechanical ventilation with AI-driven weaning protocol optimization and predictive deterioration alerting. Early deployment concentrates in Japanese super-aging hospitals facing intensivist shortages.
Electronic systems anchor the volume base while robotic ventilation climbs the fastest as labor constraints intensify in developed markets.
Application:
Disease prevalence and diagnostic infrastructure maturity create geographically clustered demand patterns with distinct therapy adherence profiles.
- COPD:Chronic obstructive pulmonary disease requiring long-term oxygen therapy and non-invasive ventilation escalation protocols. German disease management programs and United States Medicare bundled payment models concentrate device procurement.
- Sleep Apnea:Obstructive sleep apnea mandating nightly CPAP adherence with remote monitoring for insurance compliance. Diagnostic penetration in the United States and Western Europe sustains the largest installed base.
- Asthma:Reversible airway obstruction managed through bronchodilator nebulization and peak flow monitoring. Pediatric prevalence clusters in urban Japan drive compact, school-compatible device demand.
- Critical Care:Acute respiratory failure, ARDS, and post-surgical ventilation requiring invasive and non-invasive life support. Japanese and German ICU expansion programs concentrate high-acuity ventilator procurement.
COPD management anchors the volume base while sleep apnea applications expand most quickly as home diagnostic technologies proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ventilator manufacturers export precision turbine systems to Japanese university hospitals and United States ICU networks, establishing a transatlantic-Asia trade corridor that concentrates high-acuity respiratory equipment flows.
United States
Medicare bundled payment shifts and sleep apnea diagnostic penetration drive CPAP and portable oxygen concentrator procurement. FDA 510(k) pathways for Class II respiratory devices enforce substantial equivalence demonstrations that extend market entry timelines. Minneapolis and San Diego anchor device development clusters where digital health integration accelerates.
Germany
Critical care bed expansion and COPD disease management programs sustain ventilator and oxygen therapy demand. EU MDR post-market surveillance mandates through notified bodies impose real-world evidence collection requirements. Baden-Württemberg and North Rhine-Westphalia concentrate precision manufacturing for turbine-based respiratory systems.
Japan
Super-aging demographics and intensivist shortages accelerate robotic ventilation and AI-driven weaning protocol adoption. PMDA streamlined approval pathways for connected home care devices reduce time-to-market for portable oxygen concentrators. Tokyo and Osaka metropolitan areas dominate hospital procurement of high-acuity systems.
India
Nascent sleep apnea screening infrastructure and district hospital emergency preparedness programs create device deployment opportunities. CDSCO medical device rules classify respiratory equipment under notified category requirements with import license obligations. Maharashtra and Karnataka host emerging distribution networks for CPAP and nebulizer systems.
China
Domestic critical care capacity expansion and chronic respiratory disease management programs drive ventilator and oxygen concentrator procurement. NMPA medical device registration requirements enforce clinical trial obligations for Class II and III respiratory products. Yangtze River Delta manufacturing clusters supply compressor components for global device assembly.
Global Respiratory Care Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures where hospital procurement consolidation meets home care direct-to-patient distribution. The vendor base clusters around three archetypes: diversified medtech conglomerates with multi-parameter monitoring integration, pure-play respiratory specialists with therapy adherence platforms, and regional fabricators with cost-optimized mechanical designs. Competitive moves concentrate on M&A for digital health capabilities and strategic partnerships for telehealth platform convergence.
Within the diversified medtech tier, Koninklijke Philips NV and Medtronic occupy positions spanning hospital-grade ventilator systems through home care monitoring ecosystems. ResMed Inc. exemplifies the therapy-platform archetype with recurring revenue models anchored to sleep apnea management software. Drägerwerk AG & Co. KGaA represents German precision engineering specialization in critical care turbine technology.
| Leading Market Players |
|---|
| ResMed Inc. |
| Invacare Corporation |
| Koninklijke Philips NV |
| Hamilton Medical |
| Teleflex |
| Medtronic |
| Drägerwerk AG & Co. KGaA |
| Masimo Corporation |
| Fisher & Paykel Healthcare |
| Others |
Value Chain & Pricing Dynamics
Taiwan and South Korea semiconductor fabrication concentration anchors ventilator control system costs, with foundry capacity allocation decisions rippling directly through to hospital procurement committee budgets and home care device margin structures.
Pricing Analysis
Current-generation robotic ventilation systems with AI-driven weaning protocols command substantial premiums over prior-generation electronic platforms, while next-generation MEMS-integrated adaptive pressure-support devices are resetting price baselines in German and Japanese pilot programs. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) clearance tier and embedded remote monitoring capability. Cost compression in portable oxygen concentrators is intensifying because battery cell commoditization and compressor miniaturization are eroding hardware margins. Home care channels exhibit highest price sensitivity due to Medicare reimbursement caps, while Japanese university hospitals demonstrate lowest sensitivity given intensivist shortage premiums.
Supply Chain Analysis
Zeolite molecular sieve feedstock for pressure swing adsorption systems draws from specialized mineral processing operations concentrated in the United States, China, and select European deposits. Precision MEMS flow sensors and lithium-ion battery cells constitute critical component dependencies alongside medical-grade aluminum for turbine housings. Single-source vulnerability in Taiwan semiconductor foundries creates exposure for ventilator control board supply. Distribution runs through hospital GPO contracts in the United States, direct-to-patient channels for home care, and specialized medical device distributors in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as hospital capital expenditure budgets normalize following pandemic-era ventilator stockpiling depletion and chronic disease management program expansion resumes.
For Market Incumbents: Pre-empt emerging entrant incursions into India's nascent sleep apnea screening infrastructure by accelerating CPAP device registration under CDSCO notified category pathways before local fabricators achieve scale. Consolidate position through backward integration into precision turbine manufacturing in Baden-Württemberg to defend against Asian cost-optimized mechanical design imports.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated diagnostic infrastructure by partnering with district hospital emergency preparedness programs for nebulizer and manual resuscitator deployment. Target German Pflegeheime long-term care facilities with simplified CPAP interfaces designed for dementia-competent staff operation, leveraging EU MDR post-market surveillance data requirements as a competitive moat.
For Investors and Strategic Acquirers: Capital is best deployed toward therapy-platform specialists with embedded remote monitoring capabilities and recurring revenue software licensing models rather than hardware-only fabricators facing margin compression. The acquisition target archetype combines FDA-cleared device portfolios with HL7 FHIR interoperability infrastructure. Watch PMDA streamlined approval pathway utilization rates as the inflection indicator for connected home care device market entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortens market entry timelines for Class II respiratory devices in the United States. |
| CE Marking Pathway Investment | Secures EU MDR notified body alignment for post-market surveillance data pipelines. |
| Hospital System Partnership | Locks in multi-parameter monitoring integration for ICU ventilator procurement committees. |
| Software Companion Development | Enables subscription revenue capture from sleep apnea therapy adherence platforms. |
| Reimbursement Strategy Optimization | Aligns device specifications with Medicare bundled payment shifts toward preventive outpatient models. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, GPO contracts managers, home care equipment providers, and PMDA regulatory consultants, validated against secondary sources including FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement schedules, and Japanese Ministry of Health device approval records. Bottom-up device shipment modeling and top-down healthcare expenditure allocation analysis were triangulated to anchor volume estimates.
Calibration against historical procurement cycle patterns and replacement rhythm analysis shaped the analytical framework across the analysis window, with segmentation dimensions spanning product type, end user channel, technology tier, and application disease state. CAGRs were derived from installed base evolution and penetration rate trajectories, incorporating COPD prevalence clustering data and sleep apnea diagnostic infrastructure buildout timelines as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, semiconductor foundry capacity allocation, or reimbursement policy shifts would shift the trajectory materially. Cross-checking against external healthcare technology expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Emphysema Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Lung Management Products Market