
 Global Respiratory Heaters Market | 2026-2036
Global Respiratory Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Respiratory Heaters Market Intelligence
The ISO 13485 certification cycle, a critical gatekeeper for medical device quality, is unwinding previous supply chain assumptions. Fisher & Paykel Healthcare dominates the specialized field of advanced airway humidification technologies. Drägerwerk AG & Co. KGaA positions its integrated systems for the high-acuity critical care environment, while Medtronic leverages its extensive hospital network to distribute a broad portfolio of respiratory care devices.
A respiratory heater is a medical device designed to warm and humidify inspired gas for patients, particularly during mechanical ventilation. These systems typically maintain gas temperatures between 33°C and 42°C to prevent airway drying and mucosal damage. Within product types, active respiratory heaters hold a significant market share due to precise temperature control in critical care. The home care settings segment represents the fastest-growing end-user category, driven by decentralization trends in patient management.
Regulatory compliance is a significant factor shaping market access and product design. The US FDA classifies most respiratory heaters as Class II devices, requiring 510(k) premarket notification. Similarly, CE marking under Europe's MDR and approvals from China's NMPA mandate rigorous safety and performance validation. Stakeholders must balance investment in feature-rich hospital units against simplified, cost-effective designs for the growing home care channel.
Market Dynamics
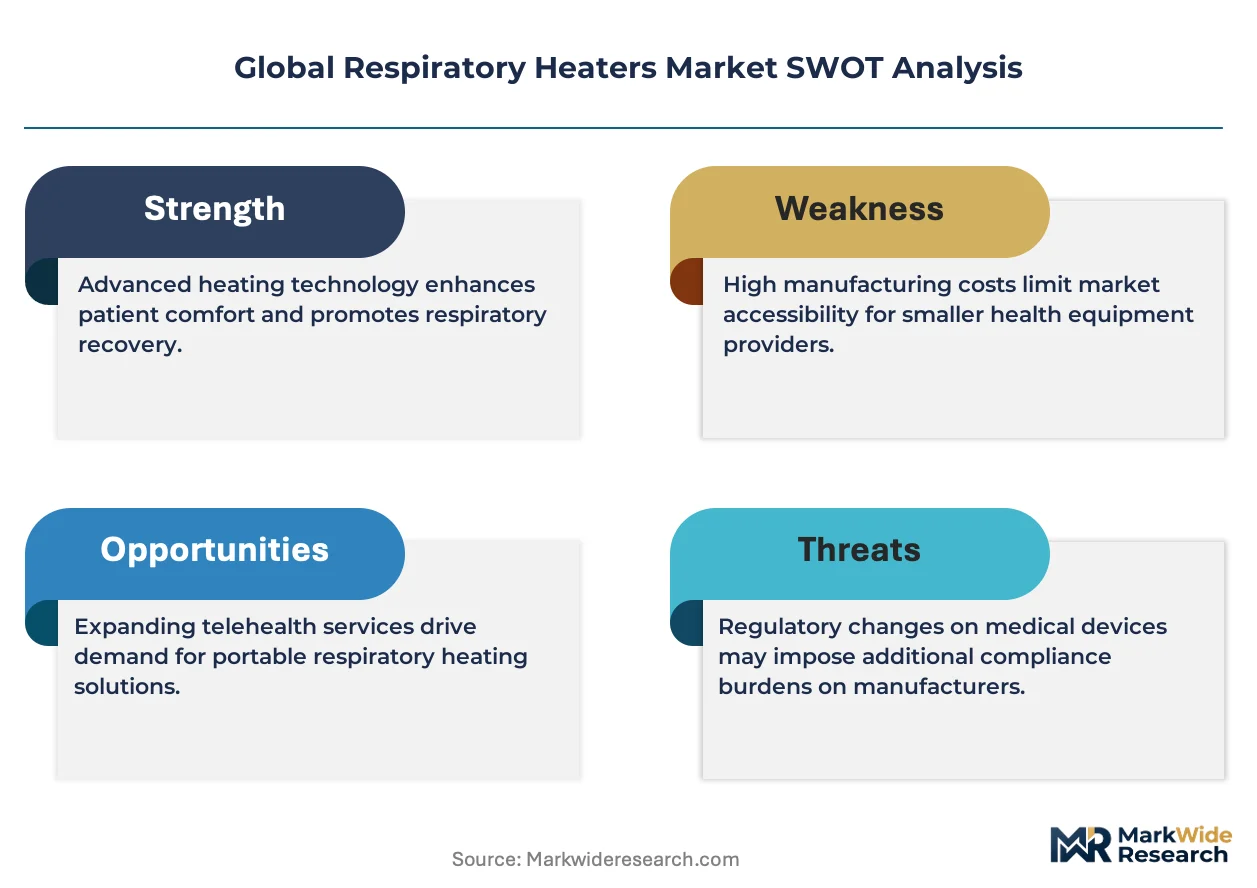
Intensifying regulatory scrutiny across key geographies is the central force shaping the respiratory heater market. Stricter performance and safety mandates from bodies like the EU, FDA, and NMPA are raising the barrier to entry and forcing incumbents to reinvest in compliance.
Growth Catalysts
- Neonatal Care Expansion:The need for precise thermal management in neonatal intensive care units (NICUs) to prevent hypothermia and support respiratory function in premature infants is a primary demand driver.
- China's Hospital Infrastructure:Sustained government and private investment in building out hospital capacity across China, particularly in secondary and tertiary care facilities, creates a large, concentrated new market for critical care equipment.
- Home Care Decentralization:A clinical push towards managing chronic respiratory patients in home settings creates demand for simplified, cost-effective respiratory heaters designed for non-professional users and long-term use.
Market Restraints
- High Unit Cost:The expense of advanced active respiratory heaters, incorporating precise servocontrollers and safety alarms, limits their adoption in cost-sensitive healthcare systems and emerging economies.
- EU Medical Device Regulation (MDR):The stringent clinical evidence and post-market surveillance requirements of the EU's MDR increase compliance costs and extend time-to-market, delaying innovation and market access.
- Risk of Airway Contamination:The inherent challenge of maintaining sterility within the humidification chamber and breathing circuit presents a persistent technical restraint, requiring rigorous cleaning protocols or reliance on costly disposable components.
Strategic Opportunities
- Smart Device Integration:There is an opportunity to embed connectivity features, enabling remote monitoring, data logging for clinical records, and integration with hospital information systems to improve patient management.
- Emerging Market Penetration:Developing mid-tier devices that balance performance with affordability can unlock significant volume in markets like Brazil, where regulators like ANVISA are formalizing standards.
- Home Care-Specific Designs:Creating simplified, durable, and user-friendly heaters tailored specifically for the fast-growing home care segment addresses an unmet need for non-clinical user operation.
Industry Challenges
- Regulatory Divergence:Manufacturers face the operational challenge of managing distinct and complex submission pathways for the US FDA's 510(k), Europe's CE marking, and China's NMPA approval.
- System Interoperability:Ensuring seamless compatibility and communication between respiratory heaters and the diverse ecosystem of mechanical ventilators and breathing circuits from different manufacturers remains a significant technical hurdle.
- Component Supplier Qualification:The stringent validation and change control processes mandated by ISO 13485 make it difficult and time-consuming for device manufacturers to qualify new or alternative component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Respiratory Heaters Market |
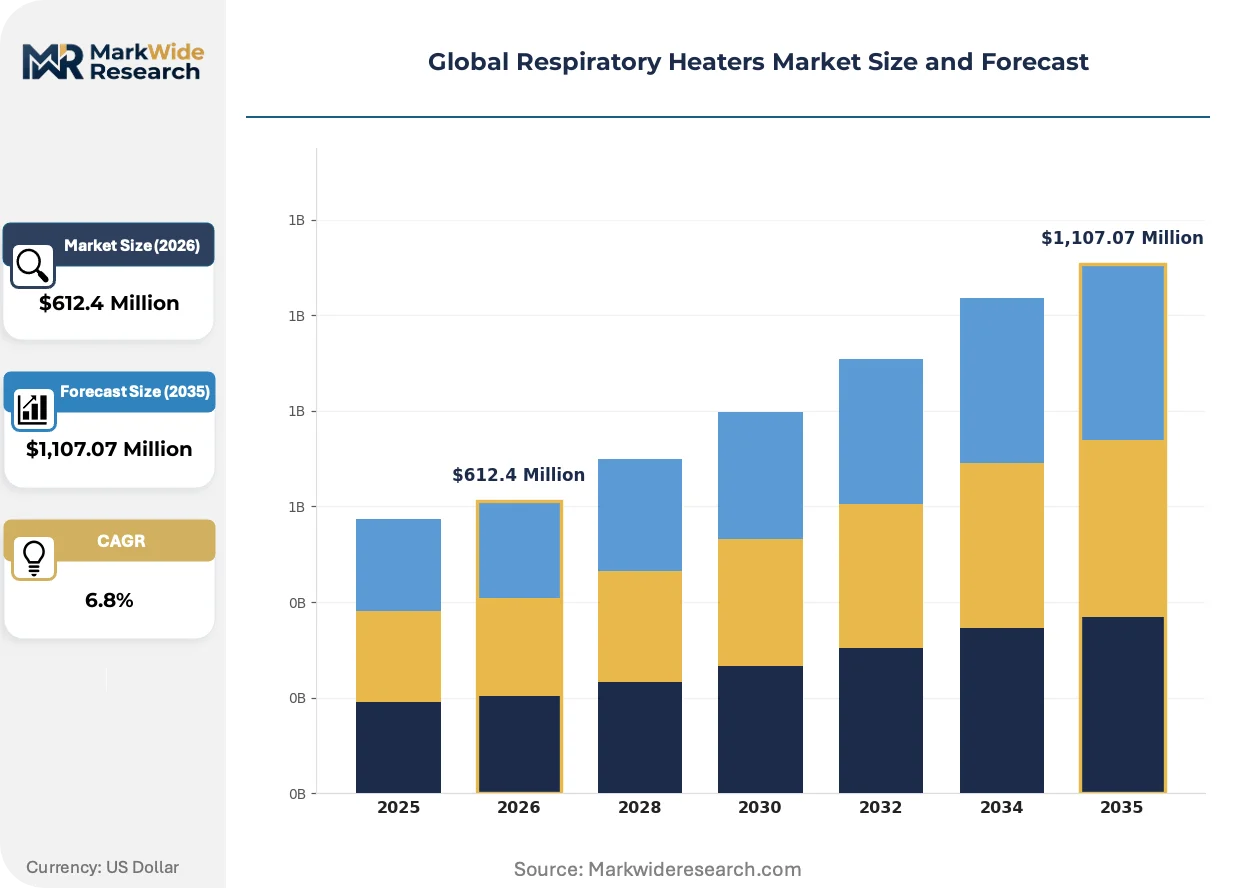
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Respiratory Heater, Passive Respiratory Heater, Dual Heat and Moisture Exchanger, Portable Respiratory Heater Application: Mechanical Ventilation, Anesthesia Delivery, Oxygen Therapy, Neonatal Care, Critical Care End User: Hospitals, Ambulatory Surgical Centers, Home Care Settings, Specialized Clinics Technology: Airway Humidification, Heat Moisture Exchange, Electronic Temperature Control, Passive Heat Conservation |
| Companies Covered | ResMed, Getinge AB, Koninklijke Philips N.V., GE Healthcare, Fisher & Paykel Healthcare, Drägerwerk AG & Co. KGaA, Medtronic, Hamilton Medical, Smiths Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Respiratory Heaters Market Strategic Shifts & Innovations
Product development is shifting from standalone hardware to integrated, data-enabled systems. Connectivity and patient-adaptive algorithms are becoming key differentiators, moving the technology's focus from simple gas warming to optimized, patient-specific respiratory therapy within a connected care framework.
Closed-loop control systems that use distal airway temperature sensors provide real-time feedback to the heater. These advanced systems are seeing uptake in high-acuity ICU and neonatal environments where precise thermal regulation is critical. This technology is bifurcating the market into premium, algorithm-driven hospital platforms and simpler, more economical open-loop devices for transport and home care applications.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence, risk management, and post-market surveillance. This regulation increases the burden of proof for demonstrating device safety and performance, extending development timelines for all manufacturers. Consequently, companies marketing Class II devices like respiratory heaters are investing more heavily in clinical data generation to obtain and maintain CE marking.
Hospital purchasing behavior is moving away from single-device acquisitions toward bundled solutions that include heaters, humidification chambers, and proprietary circuits from one vendor. This shift favors large medtech firms with broad portfolios, challenging smaller, specialized component suppliers who lack an integrated platform. This trend is most visible within large, integrated delivery networks in the United States and Europe seeking to standardize equipment and consumables.
Global Respiratory Heaters Market Segmentation
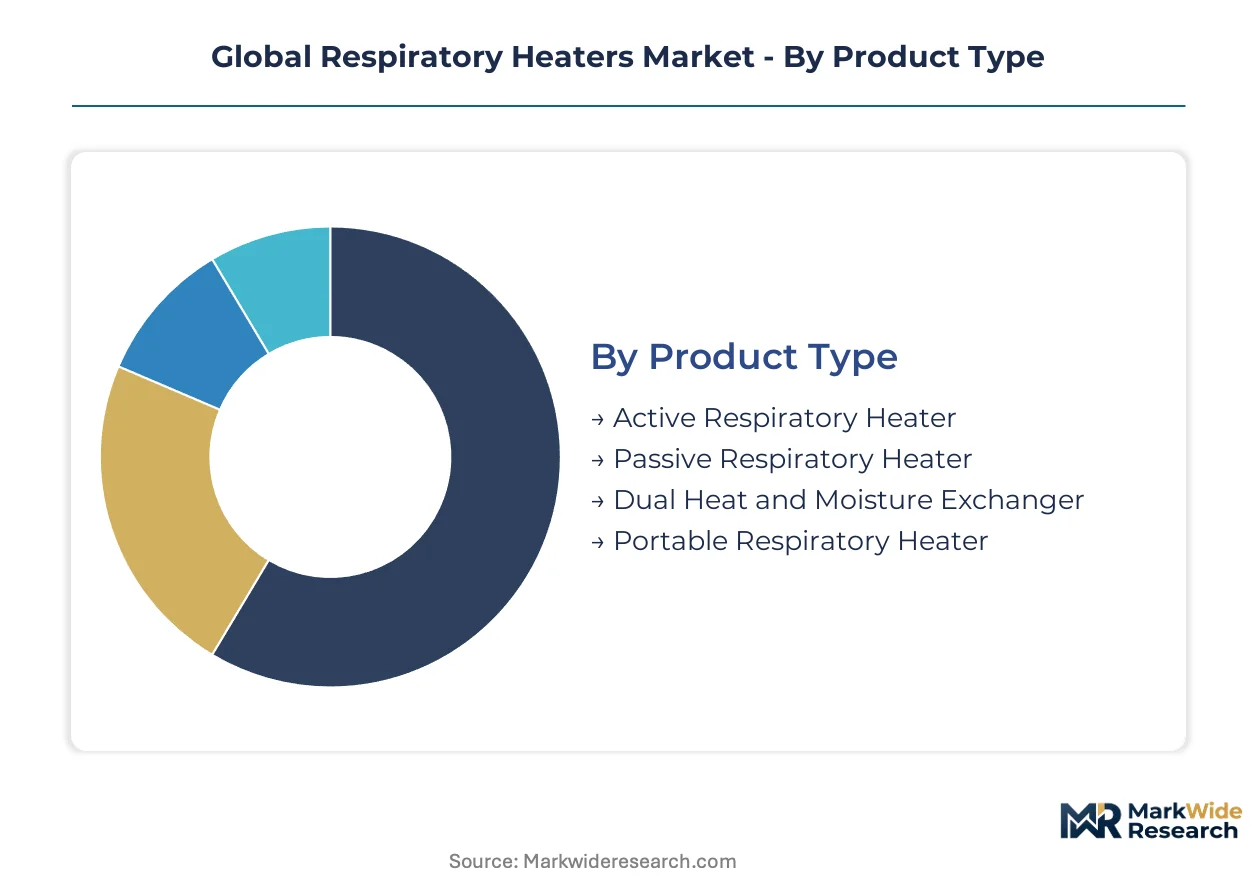
Segmentation within the global respiratory heaters market reveals distinct product, application, and end-user requirements, shaping both innovation and commercial strategies. Understanding these divisions is crucial for manufacturers to align product development with specific clinical needs and procurement patterns across diverse healthcare environments.
Product Type:
The respiratory heater market faces substitution pressure from simpler humidification methods, pushing product type innovation towards advanced solutions with precise control. This market segment categorizes devices based on their operational mechanism and features.
- Active Respiratory Heater:These devices electronically heat and humidify inspired gas, often incorporating precise servocontrollers to maintain temperatures between 33°C and 42°C. Demand is high in critical care environments across major hospital networks in the United States and Germany, where precise thermal regulation is essential for mechanically ventilated patients.
- Portable Respiratory Heater:Designed for mobility and ease of use outside clinical settings, these compact units often feature battery power and simplified interfaces. Their demand is rapidly expanding within home care settings in countries like Canada and Australia, supporting patients with chronic respiratory conditions who require continuous humidification.
- Passive Respiratory Heater:These units utilize a patient's exhaled breath to warm and humidify the inspired air, typically through a heat and moisture exchanger. They offer a cost-effective solution for short-term use during patient transport or in resource-constrained facilities.
- Dual Heat and Moisture Exchanger:Combining humidification and bacterial/viral filtration, these passive devices are integrated into breathing circuits. They find application in anesthesia delivery and short-term ventilation where infection control is a primary concern.
Active Respiratory Heaters retain volume leadership; Portable Respiratory Heaters hold the steepest expansion curve.
Application:
Application segments often dictate the cost tier of respiratory heaters, with critical care demanding premium, feature-rich devices. This segment reflects the specific clinical contexts where respiratory heaters are employed.
- Neonatal Care:Respiratory heaters in this application provide precise thermal management and humidification for premature infants or neonates with respiratory distress. This segment is experiencing significant demand growth in NICUs across China, driven by expanding hospital infrastructure and specialized medical needs.
- Mechanical Ventilation:These applications involve warming and humidifying gas delivered to patients on life support, preventing airway drying and mucosal damage. Demand concentrates within high-acuity intensive care units in Europe, where patient outcomes are directly linked to optimal respiratory support.
- Critical Care:This broad application encompasses patients in intensive care units requiring advanced respiratory support, where maintaining physiological humidity and temperature is vital.
- Anesthesia Delivery:During surgical procedures, respiratory heaters ensure warmed and humidified gases are delivered to patients under general anesthesia, maintaining patient core body temperature.
- Oxygen Therapy:For patients receiving supplemental oxygen, heaters prevent nasal dryness and irritation, improving comfort and compliance with long-term therapy.
Hospitals remain the primary end-user for Mechanical Ventilation, while Neonatal Care applications are expanding most quickly.
End User:
End-user segments reflect varying patient volumes and operational requirements, influencing device design and distribution channels. This category differentiates where respiratory heater devices are primarily utilized.
- Home Care Settings:This segment caters to patients managing chronic respiratory conditions outside institutional environments, requiring simplified, user-friendly, and durable respiratory heaters. The decentralization of patient management drives significant growth here, particularly in regions with aging populations like Japan and Germany.
- Hospitals:Acute care facilities, including general wards, ICUs, and operating rooms, represent a major end-user for advanced respiratory heaters. Hospital purchasing behavior favors bundled solutions and interoperable systems from large medical technology firms.
- Ambulatory Surgical Centers:These facilities utilize respiratory heaters for patients undergoing short-stay procedures requiring anesthesia or oxygen therapy. They prioritize compact, reliable, and easy-to-maintain devices.
- Specialized Clinics:Respiratory heaters find use in pulmonary clinics or sleep disorder centers for diagnostic procedures or long-term patient management. These clinics often require devices adaptable to various patient needs.
Hospitals represent a mature segment with established procurement, while Home Care Settings are gaining share fastest.
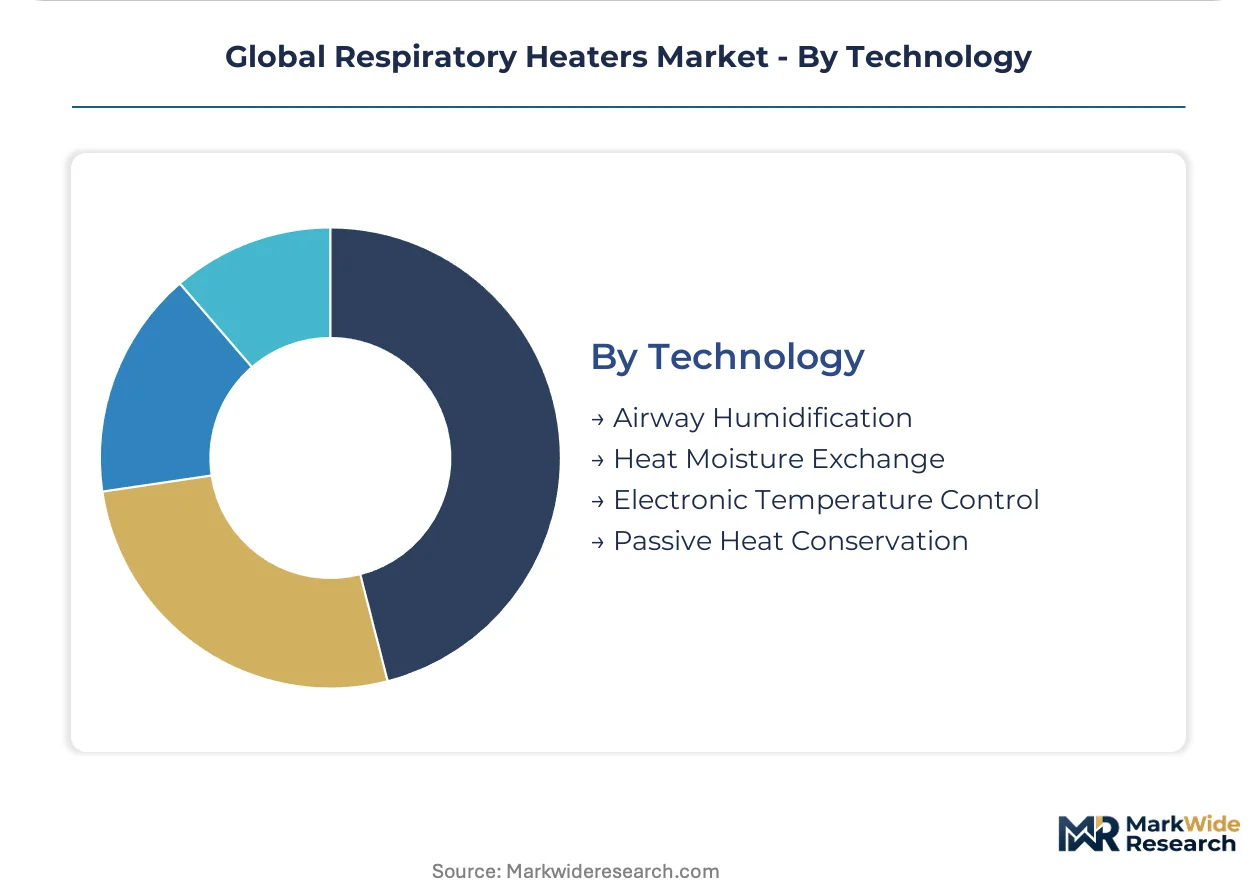
Technology:
Technology choices in respiratory heaters are often dictated by the specific application, from basic humidification to advanced thermal regulation. This segment focuses on the underlying technical principles and components of the devices.
- Electronic Temperature Control:These advanced systems use microprocessors and sensors to precisely regulate the temperature of inspired gas, often incorporating closed-loop feedback mechanisms. They are critical in high-acuity settings like NICUs and ICUs, particularly in advanced healthcare markets such as the United States.
- Airway Humidification:This technology focuses on adding moisture to dry medical gases, preventing desiccation of the patient's airway mucosa. Fisher & Paykel Healthcare specializes in advanced airway humidification technologies, demonstrating its market importance.
- Heat Moisture Exchange:These passive technologies capture heat and moisture from exhaled breath and return it to the inspired gas, offering a simple and cost-effective solution.
- Passive Heat Conservation:This technology aims to minimize heat loss from the breathing circuit, contributing to patient thermal management without active heating elements.
Electronic Temperature Control technologies see concentrated investment from large medtech firms, while Heat Moisture Exchange offers a broader supply base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government investment and policy initiatives significantly influence regional demand for respiratory heaters. China's sustained investment in hospital infrastructure drives demand for critical care equipment. Regulatory bodies like the US FDA and Europe's MDR shape product design and market access across key geographies.
United States
The United States market demands advanced active respiratory heaters for high-acuity ICUs and neonatal care. US FDA 510(k) premarket notification ensures device safety and performance for Class II products. Medtech innovation clusters in the Greater Boston area and California develop next-generation respiratory support systems.
Germany
Germany exhibits strong demand for precise thermal regulation in critical care and home settings due to an aging population. CE marking under Europe's MDR imposes stringent clinical evidence and post-market surveillance requirements. Bavaria's medtech manufacturing base and North Rhine-Westphalia's extensive hospital networks drive adoption.
China
China's expanding public and private hospital systems create a large, concentrated market for critical care equipment. NMPA approvals mandate rigorous safety and performance validation for new medical devices. The Yangtze River Delta region sees significant investment in medical device production and hospital expansion.
Japan
Japan's rapidly aging population fuels demand for simplified, cost-effective respiratory heaters in home care settings. PMDA regulatory approvals ensure device quality and efficacy for the domestic market. The Tokyo metropolitan area serves as a hub for medtech R&D and specialized respiratory clinics.
Brazil
Brazil represents an emerging market opportunity for mid-tier respiratory heaters balancing performance with affordability. ANVISA is formalizing standards, influencing market access and product design. São Paulo's robust healthcare infrastructure supports medical device distribution and adoption across the region.
Global Respiratory Heaters Market Key Industry Players
Player mix skews toward established medical technology firms with broad portfolios and specialized innovators focusing on specific respiratory care needs. The market structure favors large medtech firms capable of offering bundled solutions and integrated systems to standardize equipment. Strategic archetypes include global diversified healthcare conglomerates, focused respiratory care specialists, and regional pure-play manufacturers. Companies are increasingly pursuing portfolio diversification, strategic partnerships, and geographic expansion to navigate regulatory complexities and broaden market reach.
Specialized innovators like Fisher & Paykel Healthcare, a New Zealand-based company, exemplify leadership in advanced airway humidification technologies, carving out a significant niche in this critical segment. German-headquartered Drägerwerk AG & Co. KGaA represents companies positioning integrated systems for high-acuity critical care environments, offering comprehensive solutions that extend beyond standalone devices into full patient monitoring. Medtronic, a global medical technology company with an extensive portfolio, demonstrates the strategy of leveraging its broad hospital network to distribute a wide range of respiratory care devices and associated consumables across diverse clinical settings.
| Leading Market Players |
|---|
| ResMed |
| Getinge AB |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Fisher & Paykel Healthcare |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Hamilton Medical |
| Smiths Medical |
| Others |
Cost & Logistics Intelligence
Lead-time for highly specialized electronic components, such as microprocessors and precise sensors, directly influences the supply chain's agility and pricing power for advanced respiratory heaters. This dependency fosters strategic stockpiling for critical parts, impacting overall product cost structures.
Pricing Analysis
Certification level (US FDA 510(k) clearance, CE marking, NMPA approval) creates the primary spread in respiratory heater pricing. The dominant pricing model is per-unit transactional for devices, complemented by recurring revenue from proprietary humidification chambers and breathing circuits. Price differentiation stems from the precision of temperature control and the integration of advanced safety features. Pricing pressure intensifies within the home care segment due to demands for cost-effective, simplified devices. High-acuity intensive care units exhibit the lowest price sensitivity, prioritizing clinical efficacy above all.
Supply Chain Analysis
Strategic stockpiling of critical electronic components and specialized plastics is common for advanced respiratory heater manufacturers, balancing just-in-time principles with supply resilience. Geographic supply concentration for electronic components centers in East Asia, while final assembly often occurs in Germany, the United States, and New Zealand. Raw material dependencies include medical-grade polymers for patient circuits and heating elements. A significant supply chain risk is single-source vulnerability for highly specialized sensor technology. Distribution runs through direct sales channels to large hospital networks and third-party distributors for home care settings and smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The respiratory heater market is undergoing a high-growth disruption, driven by the technological inflection of smart device integration and decentralization of patient care.
For Market Incumbents: Fortify core market positions by investing in next-generation closed-loop control systems and patient-adaptive algorithms. Consolidate market share through bundled solutions that integrate devices, consumables, and digital platforms, leveraging existing extensive hospital networks. The threat of increasing regulatory burden necessitates continuous investment in compliance capabilities, particularly for EU MDR requirements. Deepen vertical integration into specialized component manufacturing to mitigate supply chain risks.
For New Entrants and Emerging Players: A service-layer gap exists in providing user-friendly, connected respiratory heaters specifically designed for non-clinical home care use. Target this white-space opportunity by developing simplified, durable, and cost-effective portable devices with integrated remote monitoring capabilities. The most penetrable segment is the growing home care market in emerging economies like Brazil, where ANVISA is formalizing standards. A viable go-to-market angle involves partnerships with home health agencies or direct-to-consumer models.
For Investors and Strategic Acquirers: Long-term, this sits as a medical technology essential play because of sustained demand from aging populations and chronic respiratory conditions. Acquisition targets should focus on specialized innovators in smart device connectivity, advanced humidification technologies, or manufacturers with strong penetration in the rapidly expanding home care segment. The signal to watch is the rate of reimbursement policy changes favoring home-based respiratory care, which will accelerate market decentralization.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Secures timely access to the European market under stringent Medical Device Regulation requirements. |
| Hospital System Partnership Expansion | Standardizes equipment procurement and integrates devices into established clinical workflows. |
| Software Companion Application Development | Enables remote patient monitoring and data logging for improved home care management. |
| Portable Respiratory Heater Launch | Addresses the unmet need for user-friendly, mobile humidification in decentralized settings. |
| Localized Manufacturing Investment | Enhances market penetration and reduces logistics costs in key emerging markets like Brazil. |
Research Approach
A spread of perspectives from biomedical engineers, hospital procurement managers, NICU clinicians, and home care providers converged on the working assumptions for the respiratory heaters market. This approach combined extensive primary interviews with rigorous secondary validation from sources including US FDA 510(k) filings, EU MDR documentation, NMPA approvals, and medical device industry reports. Bottom-up and top-down triangulation ensured data consistency and robust market sizing.
Segmentation by product type (active, portable), application (neonatal care, mechanical ventilation), end-user (hospitals, home care), and regional regulatory environment formed the core of the analytical framework. CAGRs were derived from historical growth patterns and projected demand drivers across the modeling period. Key industry-specific forecast inputs included chronic respiratory disease prevalence rates and global neonatal intensive care unit bed capacity expansion.
Forecasts assume regulatory continuity in the United States, Europe, and China; material policy shifts would require re-modeling. The analysis reflects assumptions regarding technological adoption curves and healthcare expenditure trends. Revision becomes warranted when significant changes in global public health policies or major supply chain disruptions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Budesonide Inhaler Market