
 Pulmonary Edema Market | 2026-2036
Pulmonary Edema Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Edema Market Outlook
Hospital procurement channels for pulmonary edema diagnostics and therapeutics are reshaping competitive access across acute care networks. Edwards Lifesciences dominates hemodynamic monitoring systems used in ICU settings for cardiogenic pulmonary edema management. Siemens Healthineers anchors imaging workflows that guide treatment selection between invasive and non-invasive interventions. Pfizer Inc. competes across the diuretic and vasodilator portfolios that physicians deploy during acute decompensated heart failure episodes.
Pulmonary edema constitutes abnormal fluid accumulation within lung interstitium and alveoli driven by elevated pulmonary capillary pressure or increased vascular permeability, with arterial blood gas analysis typically revealing hypoxemia and respiratory alkalosis in early stages. The condition serves as both a critical care emergency requiring immediate oxygenation support and a chronic management target in congestive heart failure protocols. Cardiogenic edema segments command the largest current revenue pool given their direct linkage to heart failure hospitalization volumes, while non-cardiogenic categories including acute respiratory distress syndrome attract intensifying R&D investment as sepsis and trauma protocols evolve. Intravenous delivery modes retain institutional dominance in acute settings, though inhalation pathways gain traction for rapid symptom relief in emergency departments.
FDA oversight of heart failure drug approvals and EMA pharmacovigilance requirements for diuretic combinations shape product development timelines and label expansions across major markets. The EU Medical Device Regulation imposes enhanced clinical performance documentation on hemodynamic monitors and pulse oximetry systems deployed in pulmonary edema workflows. Stakeholders must track how CMS reimbursement adjustments and NICE technology appraisals redirect capital toward predictive analytics platforms that identify decompensation before ICU admission.
Market Dynamics
Hospital procurement consolidation is compressing vendor access across acute care networks, with integrated delivery networks now centralizing pulmonary edema diagnostic purchasing decisions at the system level rather than individual facility autonomy.
Growth Catalysts
- EU Medical Device Regulation:Enhanced clinical performance documentation requirements for hemodynamic monitors are accelerating replacement cycles across European ICU networks.
- Japan's super-aged demographic:The country's 29% population over 65 sustains elevated heart failure hospitalization volumes and corresponding pulmonary edema treatment demand.
- Point-of-care ultrasound:Emergency departments deploy bedside lung imaging to expedite cardiogenic versus non-cardiogenic edema differentiation, shortening time-to-treatment protocols.
Market Restraints
- Furosemide API concentration:Active pharmaceutical ingredient production for loop diuretics concentrates in Indian and Chinese manufacturing clusters, exposing supply continuity to geopolitical friction.
- CMS reimbursement compression:Medicare severity-adjusted diagnosis-related group payments for acute heart failure episodes constrain hospital margins for intensive pulmonary edema interventions.
- Mechanical ventilation capacity:ICU bed shortages during respiratory surge events limit admission availability for severe hypoxemic pulmonary edema patients requiring invasive support.
Strategic Opportunities
- Remote patient monitoring:Wearable impedance cardiography devices enable pre-decompensation detection in Germany's congestive heart failure outpatient programs.
- Inhalation diuretic delivery:Nebulized furosemide formulations target emergency department rapid symptom relief without intravenous line placement delays.
- AI-integrated chest radiography:Machine learning algorithms automate pulmonary edema severity scoring across United States health system teleradiology networks.
Industry Challenges
- Critical care nursing specialization:Hemodynamic monitoring competency requirements exceed training pipeline output across mid-sized hospital systems.
- FDA 510(k) predicate evolution:Novel pulse oximetry algorithms face extended review timelines as the agency tightens equivalence standards for low-perfusion performance claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Edema Market |
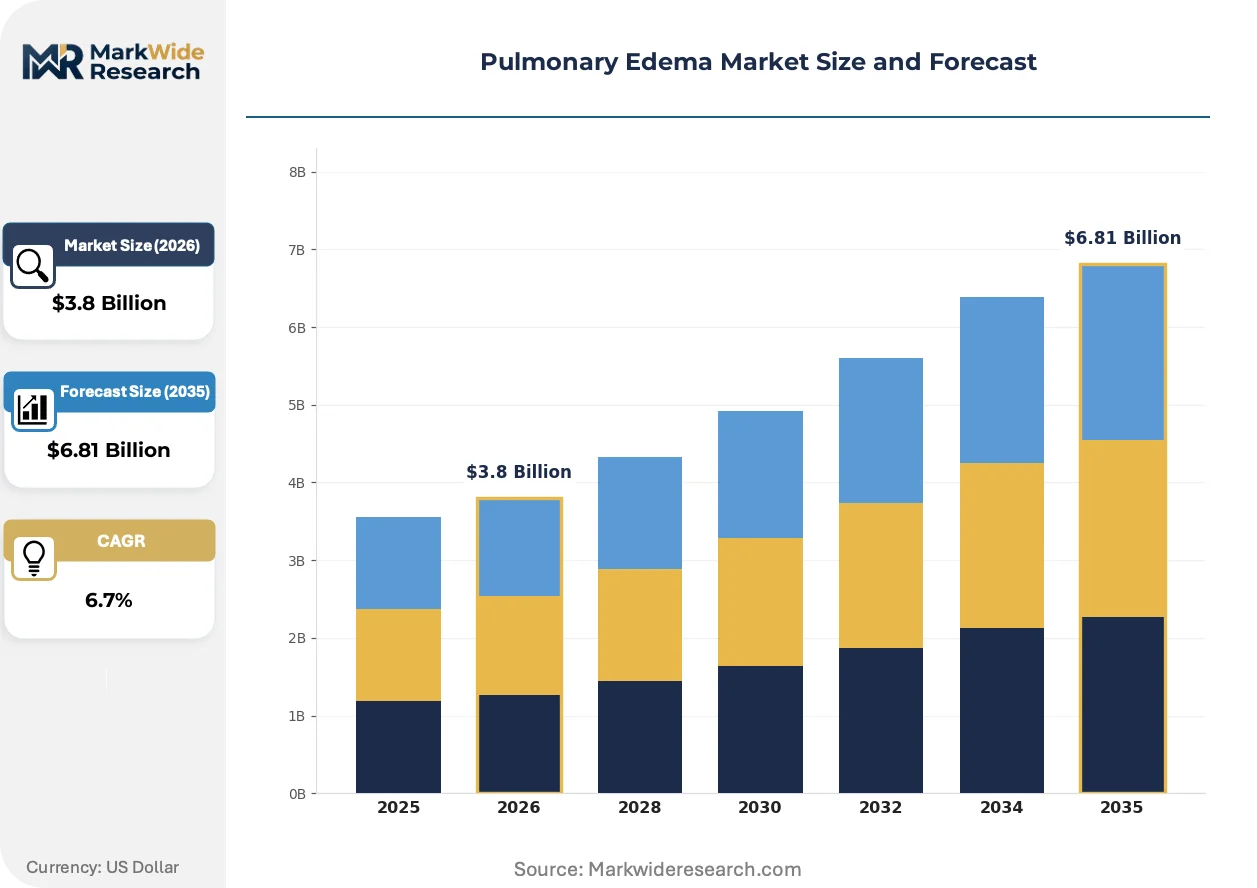
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
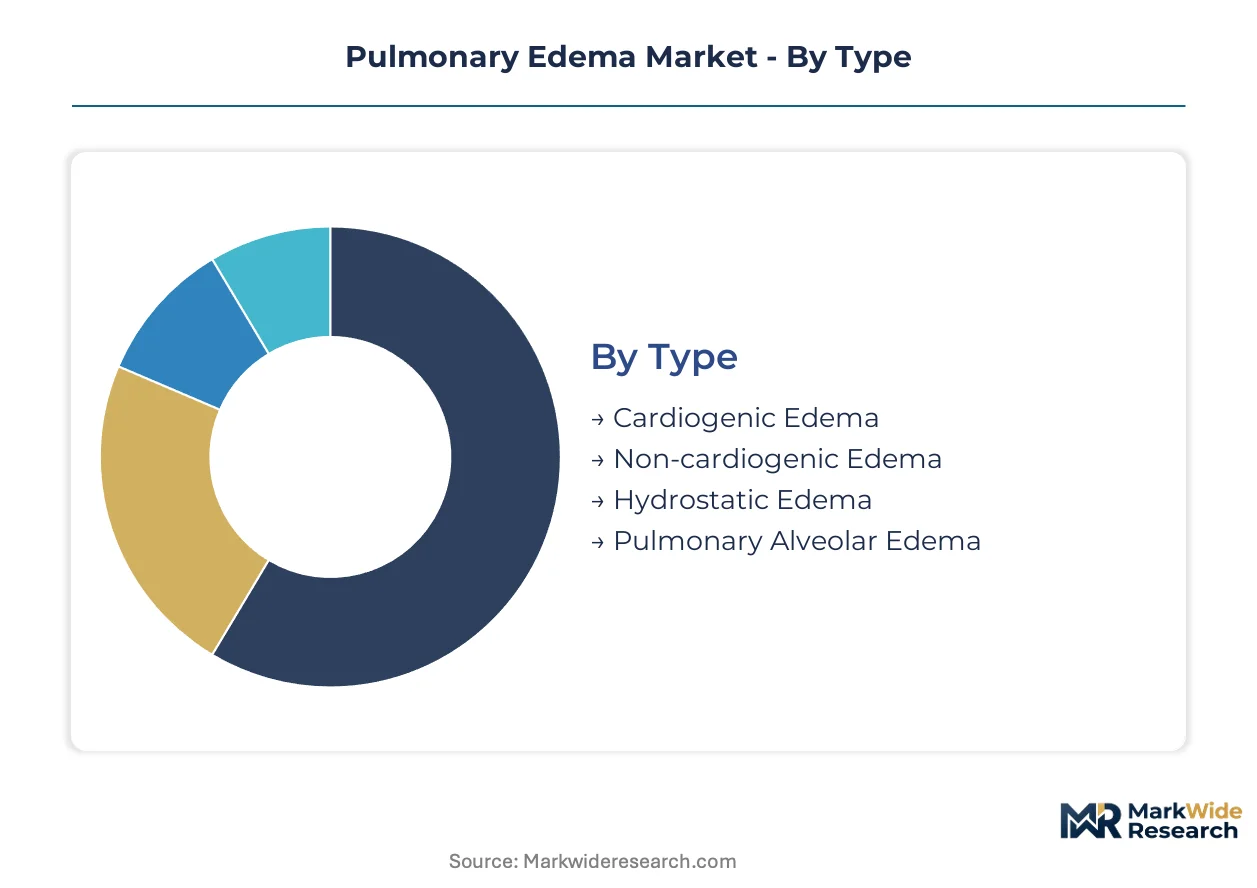
| Segmentation | Type: Cardiogenic Edema, Non-cardiogenic Edema, Hydrostatic Edema, Pulmonary Alveolar Edema Delivery Mode: Intravenous, Inhalation, Oral, Subcutaneous End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Industry Vertical: Healthcare, Pharmaceuticals, Research Institutions, Bioengineering |
| Companies Covered | Edwards Lifesciences Corporation, AstraZeneca, Pfizer Inc., Lupin Pharmaceuticals, Siemens Healthineers, Novartis AG, BD (Becton, Dickinson and Company), Roche Holding AG, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Edema Market Strategic Shifts
Digital biomarker integration is restructuring how clinicians anticipate pulmonary edema decompensation, shifting intervention timing from reactive crisis management toward predictive protocol activation.
Implantable pulmonary artery pressure sensors are collapsing the traditional reactive hospitalization model for chronic heart failure patients. Cardiology practices in the United States embed these wireless monitors to trigger outpatient diuretic adjustments before acute pulmonary edema develops. The technology is collapsing emergency department admission volumes for recurrent decompensators while redistributing revenue toward remote monitoring service contracts.
REACH chemical safety requirements now extend to sterilants and disinfectants used in reusable respiratory circuit components across European ICU environments. Manufacturers reformulate cleaning chemistries to maintain material compatibility under tightened substance restriction thresholds. German and French hospital procurement teams now require full material disclosure documentation prior to contract award.
Academic medical centers increasingly unbundle hemodynamic monitoring hardware from disposable sensor contracts, reversing decades of bundled purchasing arrangements. Hospital supply chain directors negotiate separate pricing for Edwards Lifesciences catheter systems and third-party compatible transducers. This shift is most pronounced in California and Texas health systems seeking to diversify vendor exposure while preserving interoperability with existing monitoring platforms.
Pulmonary Edema Market Segmentation
Segmentation in pulmonary edema markets separates acute intervention pathways from chronic management workflows. Treatment modality selection varies sharply across care settings, with hospital procurement driving device-heavy segments and outpatient programs favoring pharmaceutical delivery innovations.
Type:
Clinical presentation type determines intervention urgency and reimbursement coding across acute care networks.
- Cardiogenic Edema:Elevated left ventricular end-diastolic pressure forces fluid into pulmonary interstitium and alveoli. United States heart failure hospitalization protocols concentrate demand here, with CMS severity-adjusted diagnosis groups sustaining treatment volumes in tertiary medical centers.
- Non-cardiogenic Edema:Increased vascular permeability from sepsis, trauma, or inhalation injury drives ARDS-related presentations. German and Japanese ICU networks are expanding ventilator capacity for this category as sepsis protocols evolve.
- Hydrostatic Edema:Fluid accumulation from elevated pulmonary capillary wedge pressure without primary cardiac dysfunction.
- Pulmonary Alveolar Edema:Severe alveolar flooding requiring immediate mechanical ventilation support.
Cardiogenic edema holds installed capacity. Non-cardiogenic edema is rotating up the share rankings.
Delivery Mode:
Route of administration shapes competitive access through regulatory pathway complexity and care setting requirements.
- Intravenous:Loop diuretics and vasodilators delivered via central or peripheral lines dominate acute decompensated heart failure episodes. United States emergency departments maintain institutional protocols favoring IV furosemide bolus administration for rapid symptom control.
- Inhalation:Nebulized furosemide and bronchodilator combinations target emergency department throughput optimization. Japanese regulatory pathways for inhaled cardiac therapeutics are accelerating clinical trial enrollment for novel formulations.
- Oral:Maintenance diuretic regimens for chronic heart failure outpatient management.
- Subcutaneous:Emerging delivery pathway for loop diuretics in home-based decompensation prevention programs.
Intravenous delivery commands current revenue concentration. Inhalation pathways are expanding most quickly across emergency medicine protocols.
End User:
Care setting determines technology intensity and reimbursement structure for pulmonary edema interventions.
- Hospitals:Acute care facilities deploy hemodynamic monitoring systems, mechanical ventilation, and ICU-based diuretic protocols. United States integrated delivery networks centralize purchasing decisions for these capital-intensive workflows at the system level.
- Clinics:Outpatient cardiology practices manage chronic heart failure with oral diuretic titration and remote monitoring integration. German congestive heart failure programs are embedding wearable impedance devices in these settings.
- Homecare:Post-acute diuretic management and telehealth monitoring for recurrent decompensators.
- Rehabilitation Centers:Pulmonary rehabilitation following acute edema resolution.
Hospitals retain capital expenditure dominance. Homecare is climbing the fastest as remote monitoring redistributes acute intervention timing.
Industry Vertical:
Vertical participation determines R&D funding sources and regulatory pathway selection for new interventions.
- Healthcare:Hospital systems and acute care networks constitute the primary demand channel for diagnostics and therapeutics. FDA oversight of heart failure drug approvals shapes product development timelines for this vertical.
- Pharmaceuticals:Diuretic, vasodilator, and novel therapeutic development targets acute and chronic management protocols. EMA pharmacovigilance requirements for diuretic combinations influence label expansion strategies across European markets.
- Research Institutions:Academic medical centers conduct mechanistic studies on edema pathophysiology and novel intervention testing.
- Bioengineering:Device development for hemodynamic monitoring and implantable pressure sensors.
Healthcare verticals anchor current procurement volumes. Bioengineering is gaining share fastest through implantable sensor commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European distribution for acute heart failure therapeutics, while Japan's Kansai International Airport biologics hub expedites Asia-Pacific supply continuity for pulmonary edema interventions.
United States
Integrated delivery networks in California and Texas centralize procurement for hemodynamic monitoring systems at the system level. FDA oversight of heart failure drug approvals shapes product development timelines for diuretic and vasodilator portfolios. The Greater Boston medical device cluster anchors development of implantable pulmonary artery pressure sensors for chronic heart failure management.
Germany
Super-aged demographics sustain elevated heart failure hospitalization volumes across Bavaria and North Rhine-Westphalia. EMA pharmacovigilance requirements for diuretic combinations influence label expansion strategies for pharmaceutical manufacturers. The Mannheim-Heidelberg medical technology corridor concentrates production of advanced hemodynamic monitoring platforms for ICU deployment.
Japan
Twenty-nine percent of the population over 65 drives demand for acute decompensated heart failure interventions. PMDA regulatory pathways for inhaled cardiac therapeutics accelerate clinical trial enrollment for novel nebulized formulations. The Tokyo-Osaka medical corridor hosts concentrated deployment of point-of-care ultrasound systems for emergency department edema differentiation.
United Kingdom
NICE technology appraisals redirect capital toward predictive analytics platforms that identify decompensation before ICU admission. The NHS Long Term Plan embeds remote monitoring in congestive heart failure outpatient programs across England. The Cambridge-London health technology cluster develops AI-integrated chest radiography algorithms for automated pulmonary edema severity scoring.
India
Active pharmaceutical ingredient production for loop diuretics concentrates in Hyderabad and Ahmedabad manufacturing clusters. CDSCO regulatory frameworks govern domestic approval timelines for generic diuretic formulations. The Mumbai-Pune pharmaceutical corridor supplies furosemide API to formulation facilities serving acute heart failure protocols across emerging markets.
Pulmonary Edema Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in discrete sensor and pharmaceutical ingredient supply. The vendor base stratifies across three tiers: multinational conglomerates with diversified critical care portfolios, mid-cap device specialists focused on hemodynamic monitoring, and generic pharmaceutical manufacturers supplying diuretic active ingredients. Competitive positioning depends on bundled versus unbundled contract structures, with hospital procurement teams increasingly separating hardware from disposable purchasing. M&A activity concentrates on remote monitoring capabilities, while capacity expansion targets inhalation formulation facilities for emergency department rapid relief protocols.
Among multinational healthcare conglomerates, Edwards Lifesciences Corporation and Medtronic exemplify the platform integration archetype, anchoring hemodynamic system deployment across acute care networks. Siemens Healthineers occupies a position spanning imaging and monitoring workflows that guide treatment selection between invasive and non-invasive interventions. Pfizer Inc. represents the pharmaceutical tier competing across diuretic and vasodilator portfolios deployed during acute decompensated heart failure episodes.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| AstraZeneca |
| Pfizer Inc. |
| Lupin Pharmaceuticals |
| Siemens Healthineers |
| Novartis AG |
| BD (Becton, Dickinson and Company) |
| Roche Holding AG |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Furosemide API production concentrates in Hyderabad and Ahmedabad manufacturing clusters, anchoring cost structures for loop diuretic formulations while margin pools accumulate with finished-dose packagers in regulated markets. This upstream concentration constrains pricing flexibility for generic manufacturers dependent on Indian supply continuity.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement contracts for hemodynamic monitoring systems, with integrated delivery networks extracting steeper rebates for multi-facility deployments. Price differentiation hinges on FDA 510(k) clearance tier and bundled service agreements. Pricing pressure stems from CMS reimbursement compression for acute heart failure episodes. Community hospitals exhibit highest price sensitivity; academic medical centers prioritize interoperability over cost.
Supply Chain Analysis
Contract manufacturing for pulse oximetry sensors concentrates with Malaysian and Mexican EMS providers serving North American demand, while European ICU monitor assembly rests on German and Czech production facilities. Raw material dependencies span semiconductor wafers, medical-grade polymers, and sterilizable elastomers. Single-source vulnerability in furosemide API exposes formulation continuity to geopolitical friction. Distribution runs through regional medical device distributors holding GPO contracts with hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—FDA 510(k) predicates and EMA MDR documentation—erects substantial barriers against rapid competitive displacement.
For Market Incumbents: Harden installed-base protection by embedding proprietary data formats that raise switching costs for hospital IT departments. Deepen backward integration into disposable sensor manufacturing to capture margin pools currently leaking to third-party transducer suppliers. The threat of unbundled procurement demands captive production of compatible consumables.
For New Entrants and Emerging Players: Mid-tier German hospital systems seeking alternatives to Edwards Lifesciences bundled contracts represent the most penetrable entry point for compatible hemodynamic monitoring hardware. Japanese emergency departments deploying point-of-care ultrasound for edema differentiation offer secondary access for AI-integrated imaging software. A reimbursement-first go-to-market strategy accelerates adoption.
For Investors and Strategic Acquirers: Capital is best deployed toward remote monitoring platform developers with FDA-cleared algorithms for pre-decompensation detection. Long-term viability rests on recurring revenue models displacing episodic acute intervention economics. Watch CMS innovation center demonstration projects for inflection signals on remote patient monitoring reimbursement expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Implantable Pressure Sensor | CardioMEMS pathway clearance enables outpatient diuretic titration before ICU admission. |
| CE Marking Pathway for Inhaled Diuretic | EMA MDR compliance accelerates European emergency department adoption of nebulized furosemide. |
| Hospital System Partnership for Bundled Monitoring | Integrated delivery network contracts secure multi-year hemodynamic system deployments. |
| Software Companion Development for AI Radiography | Machine learning algorithms automate pulmonary edema severity scoring across teleradiology networks. |
| Reimbursement Strategy for Remote Monitoring | CMS coverage determination drives wearable impedance cardiography adoption in congestive heart failure programs. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with ICU directors, hospital procurement officers, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EMA MDR submissions, CMS Medicare cost reports, and hospital procurement databases. Bottom-up demand modeling triangulated with top-down market sizing across acute care network expansion trajectories.
Forecast inputs span cardiogenic versus non-cardiogenic edema type splits, intravenous versus inhalation delivery mode transitions, and hospital versus homecare end-user migration patterns. CAGRs derive from segmented growth rate reconciliation against macro healthcare expenditure trends. Modeled inputs include heart failure hospitalization volumes, ICU bed capacity expansion, and remote monitoring reimbursement policy evolution across the projection horizon.
Practitioners should monitor FDA predicate device clearance timelines, EMA MDR transition deadlines, and CMS severity-adjusted diagnosis-related group adjustments for early signals of forecast revision. Quarterly review of hospital capital expenditure commitments and pharmaceutical API import data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Global Respiratory Heaters Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Lung Injury Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Emphysema Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Respiratory Distress Syndrome Management Market