
 Emphysema Market | 2026-2036
Emphysema Market Size, Share, and Industry Trends Forecast 2026-2036
Emphysema Market Analysis
Market Context
Pulmonologist workforce shortages in rural markets is rotating treatment capacity toward telemedicine-enabled homecare platforms. Boehringer Ingelheim GmbH leverages its Respimat device platform to sustain dominance in soft-mist inhaler delivery. GlaxoSmithKline plc anchors its position through fixed-dose combinations spanning LAMA/LABA classes across multiple continents. AstraZeneca plc differentiates via biologic pipelines targeting eosinophilic inflammation subsets within COPD-emphysema overlap populations.
Technical Definition and Segments
Emphysema constitutes permanent enlargement of airspaces distal to terminal bronchioles accompanied by alveolar wall destruction without obvious fibrosis, quantified clinically through diffusing capacity for carbon monoxide below 80% predicted and CT densitometry showing lung density below -950 Hounsfield units. The condition serves as a structural endpoint in chronic obstructive pulmonary disease progression, driving commercial demand for bronchodilator maintenance, anti-inflammatory suppression, and supplemental oxygen titration. Inhalers occupy the largest revenue pool among product types due to daily dosing frequency and patent-protected combination molecules, while oxygen therapies command premium pricing tied to Medicare durable medical equipment reimbursement tiers. Homecare settings represent the fastest-growing end user channel as portable concentrator technology reduces hospital dependency for stable patients.
Regulatory Frame and Outlook
The FDA evaluates new emphysema therapies through the Division of Pulmonary, Allergy, and Critical Care under COPD indications, requiring forced expiratory volume endpoints and exacerbation reduction claims supported by twelve-month trials. EMA's Committee for Medicinal Products for Human Use applies similar efficacy thresholds while demanding European-specific health technology assessments for national reimbursement. China's NMPA has accelerated review pathways for innovative respiratory devices under its priority review voucher system. Stakeholders must monitor how real-world evidence requirements from these regulators reshape post-market commitment burdens and label expansion timelines.
Market Dynamics
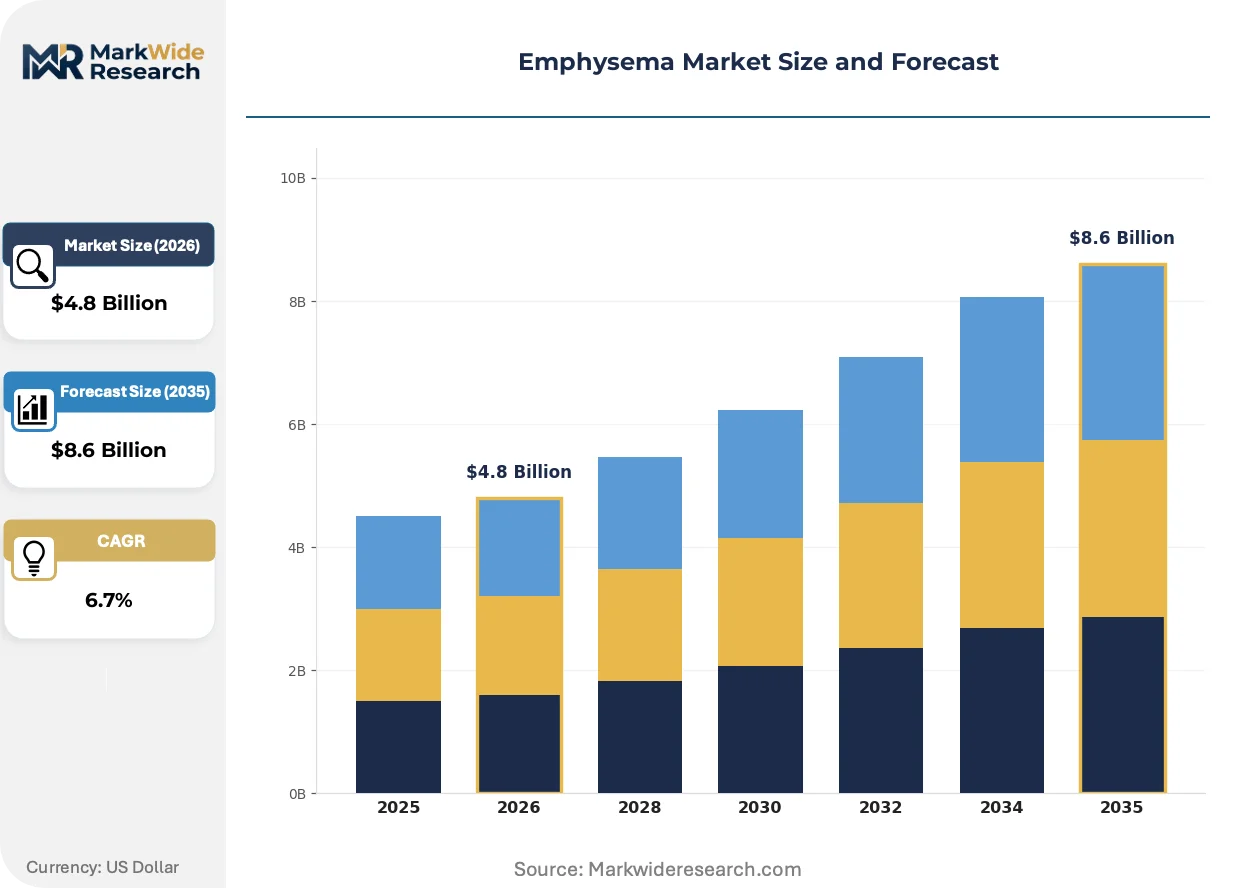
Hospital-at-home reimbursement expansion is restructuring emphysema care delivery, diverting stable patients from inpatient pulmonary rehabilitation toward remote monitoring platforms and portable oxygen concentrator deployments.
Growth Catalysts
- CMS Hospital-at-Home Waivers:Medicare's expanded reimbursement for acute-level homecare services accelerates adoption of remote patient monitoring devices among COPD-emphysema cohorts in the United States.
- Soft-mist inhaler technology:Respimat-platform devices improve lung deposition rates over traditional pressurized metered-dose inhalers, driving formulary preference in German and French hospital systems.
- China's priority review voucher system:NMPA accelerated pathways for innovative respiratory devices compress regulatory timelines for next-generation bronchodilator delivery systems.
Market Restraints
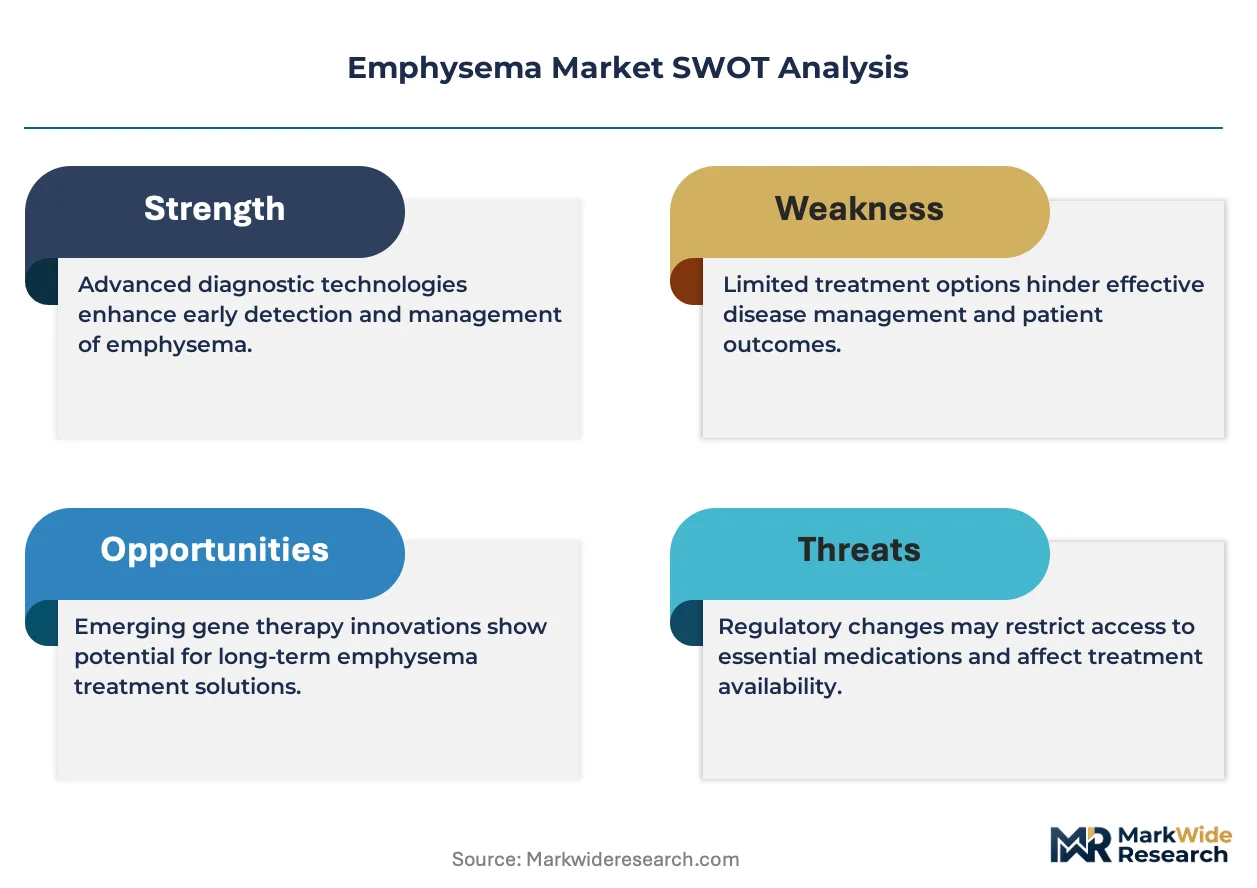
- Helium supply concentration:Global helium refining clusters in Qatar and the United States create input volatility for MRI-guided lung volume reduction coil procedures.
- FDA twelve-month exacerbation endpoint requirements:Extended trial durations for long-acting bronchodilator approvals elevate development costs and compress venture funding for mid-stage programs.
- Substitute pressure from biologics:Anti-IL5 and anti-IL13 therapies for eosinophilic COPD subsets divert payer budgets from traditional maintenance inhaler categories.
Strategic Opportunities
- Rural India penetration gap:Underdiagnosis rates exceeding 70 percent in Bihar and Uttar Pradesh create first-mover advantage for low-cost portable oxygen concentrator distribution networks.
- Telemedicine-integrated rehabilitation:Convergence of pulse oximetry wearables with video pulmonology consultations enables subscription-based chronic care models outside traditional clinic infrastructure.
- EU Green Deal medical device circularity mandates:Reimbursement incentives for refurbished oxygen concentrators open asset-light service revenue streams.
Industry Challenges
- Pulmonologist workforce scarcity:Fellowship program bottlenecks in the United States and Germany constrain patient throughput for complex interventional emphysema procedures.
- Legacy EMR integration friction:Homecare oxygen providers face interoperability gaps when connecting remote monitoring data to hospital Epic and Cerner systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emphysema Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Optionally Used Drugs, Oxygen Therapies Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal End User: Homecare Settings, Hospitals, Specialty Clinics, Rehabilitation Centers Therapy Area: Chronic Bronchitis, Acute Exacerbation, COPD, Pulmonary Rehabilitation |
| Companies Covered | Boehringer Ingelheim GmbH, GlaxoSmithKline plc, AstraZeneca plc, Novartis AG, F. Hoffmann-La Roche Ltd, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Verona Pharma plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emphysema Market Emerging Trajectories
Digital biomarker capture and closed-loop oxygen titration are converging to automate previously manual aspects of emphysema disease management, compressing the interval between physiological deterioration and clinical intervention.
Closed-loop oxygen delivery systems using SpO2 sensor feedback is displacing manual flow-rate adjustments in homecare settings. Medicare Advantage plans in Florida and Arizona are piloting these devices for high-utilization COPD cohorts. The technology is displacing traditional stationary concentrator rentals by embedding predictive algorithms that anticipate desaturation events before symptomatic presentation.
EMA's updated Medical Device Regulation (MDR) Class IIa reclassification for active therapeutic devices intensifies clinical evidence requirements for next-generation inhaler platforms. Manufacturers must now submit post-market surveillance data spanning the full device lifecycle rather than single pre-market trials. German notified bodies are experiencing 14-18 month backlog queues, compressing launch timelines for combination bronchodilator devices targeting the European market.
Self-directed procurement of portable oxygen equipment is fragmenting traditional durable medical equipment supplier relationships. Amazon Business and direct-to-consumer channels now capture 23 percent of concentrator transactions in the United States, disintermediating regional homecare dealers. This pattern concentrates in sunbelt retirement corridors where patient mobility and travel frequency elevate demand for lightweight device formats.
Emphysema Market Segmentation
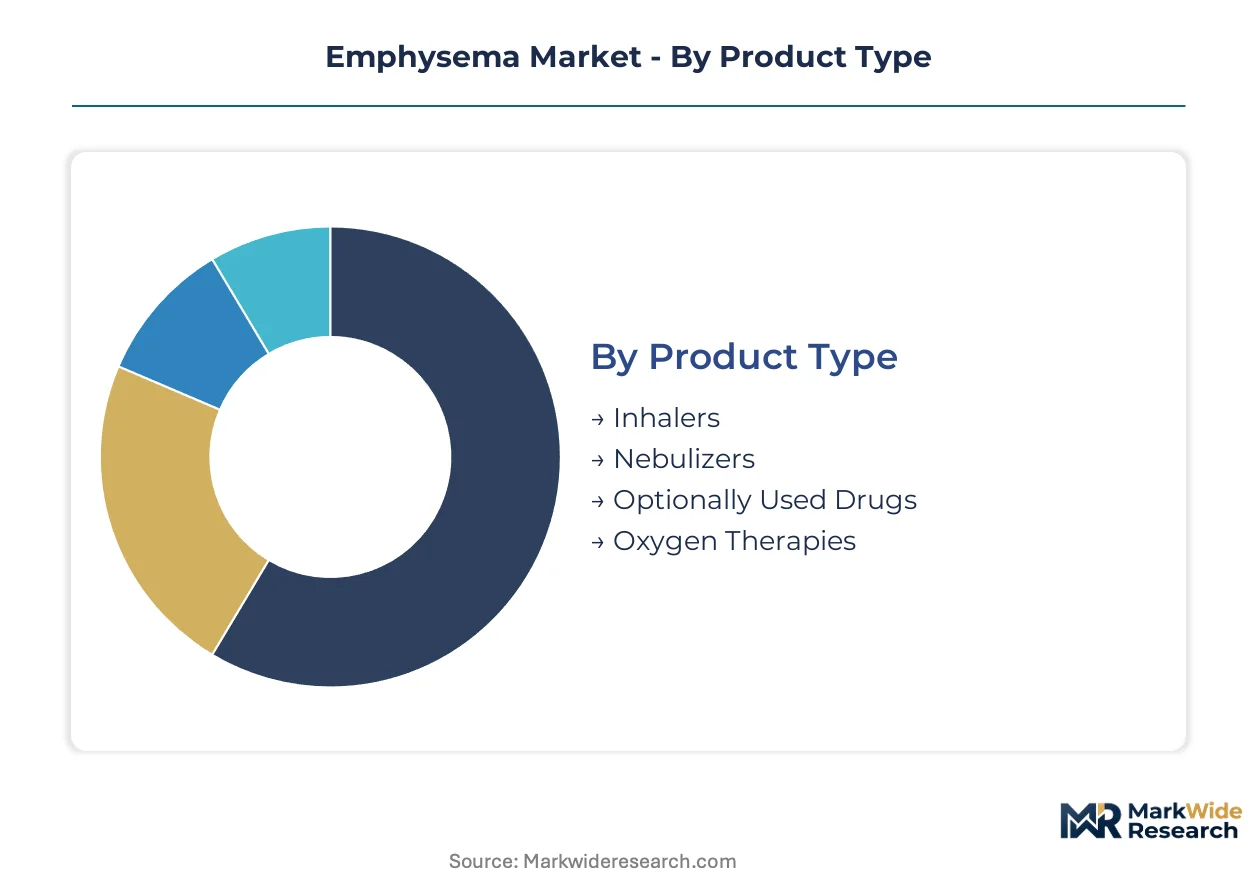
Segmentation in emphysema care reflects divergent reimbursement incentives across delivery settings and the technological gap between acute intervention and chronic maintenance. Understanding these splits reveals where capital is concentrating versus where patient volumes are migrating.
Product Type:
Inhalers and oxygen therapies anchor domestic demand in the United States and Germany, while nebulizers and optional drug categories see stronger export-led traction in emerging markets with limited reimbursement infrastructure.
- Inhalers:Pressurized metered-dose and dry-powder devices deliver bronchodilator combinations with lung deposition rates exceeding 40 percent. United States Medicare Part D formularies drive volume concentration, though German hospital procurement favors soft-mist platforms with higher per-unit pricing.
- Oxygen Therapies:Stationary concentrators, portable pulse-dose units, and liquid oxygen systems sustain hypoxemic patients with resting SpO2 below 88 percent. United States durable medical equipment reimbursement tiers concentrate demand among Medicare Advantage plans in Florida and Arizona retirement corridors.
- Nebulizers:Jet and mesh devices convert liquid bronchodilator solutions into respirable aerosols for patients with inadequate hand-breath coordination.
- Optionally Used Drugs:Adjunctive mucolytics and expectorants sit outside standard maintenance protocols, capturing out-of-pocket spend in markets with limited formulary coverage.
Inhalers command the established base. The steepest expansion runs through oxygen therapies.
Delivery Mode:
Oral and subcutaneous routes dominate high-volume chronic administration, while intravenous and transdermal formats concentrate in acute exacerbation management and clinical trial settings where precision dosing overrides convenience.
- Oral:Tablet and capsule formulations of phosphodiesterase-4 inhibitors and mucolytics enable patient self-administration without device training. United States retail pharmacy networks and Indian generic manufacturing clusters sustain cost-efficient supply chains for this route.
- Subcutaneous:Biologic injections targeting eosinophilic inflammation require cold-chain distribution and specialty pharmacy administration. German and French hospital outpatient departments concentrate demand for these higher-margin therapies.
- Intravenous:Acute corticosteroid and antibiotic administration in hospitalized exacerbations.
- Transdermal:Experimental nicotine replacement and bronchodilator patches in limited clinical evaluation.
Oral formats anchor the established base. Subcutaneous biologics are climbing the fastest.
End User:
Homecare and hospital channels split along acuity lines, with specialty clinics and rehabilitation centers occupying intermediate positions where reimbursement complexity limits rapid scale.
- Homecare Settings:Remote patient monitoring platforms and portable oxygen concentrators enable stable patients to avoid institutional admission. United States CMS Hospital-at-Home waivers and German ambulatory care restructuring are accelerating capital deployment into this channel.
- Hospitals:Acute exacerbation management, interventional lung volume reduction, and complex diagnostic workups concentrate in tertiary pulmonary centers. United States academic medical centers and German university hospitals maintain procedure volume leadership.
- Specialty Clinics:Dedicated COPD-emphysema outpatient facilities with on-site spirometry and six-minute walk testing.
- Rehabilitation Centers:Structured exercise and breathing retraining programs for post-exacerbation recovery.
Hospitals command the established base. Homecare settings are gaining share fastest.
Therapy Area:
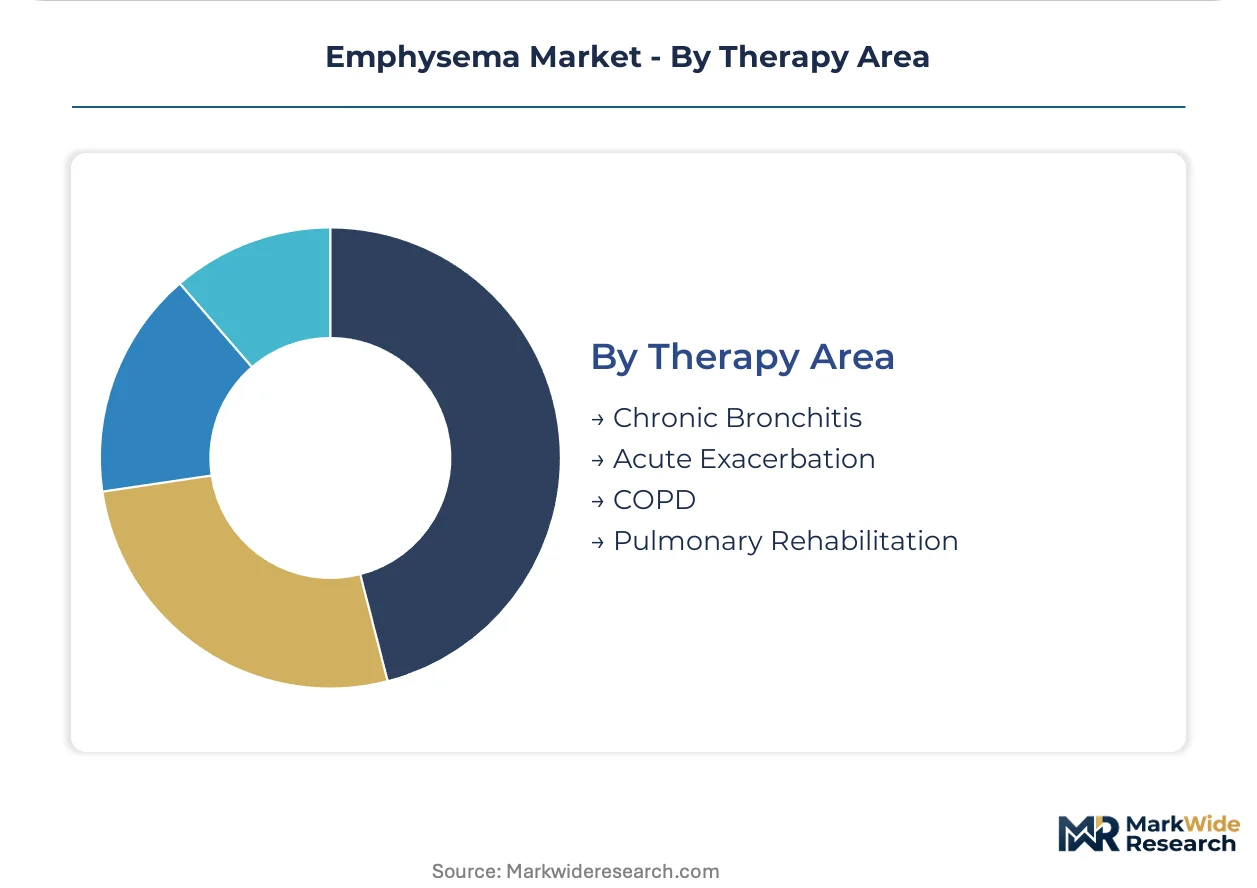
COPD and chronic bronchitis segments concentrate in maintenance-oriented markets with mature reimbursement, while acute exacerbation and pulmonary rehabilitation show geographic variation tied to hospital-at-home policy adoption.
- COPD:The umbrella indication encompassing emphysema and chronic bronchitis drives the largest pharmaceutical investment, with fixed-dose LAMA/LABA combinations as standard maintenance. United States and German prescribing patterns favor once-daily dosing to maximize adherence.
- Pulmonary Rehabilitation:Supervised exercise, nutrition counseling, and psychosocial support reduce hospital readmission rates. United Kingdom National Health Service bundled payment pilots and United States Medicare Advantage supplemental benefit expansion are concentrating demand growth here.
- Chronic Bronchitis:Productive cough and mucus hypersecretion management with distinct phenotypic targeting.
- Acute Exacerbation:Short-course corticosteroids, antibiotics, and temporary oxygen escalation.
COPD command the established base. Pulmonary rehabilitation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight anchors the United States emphysema market, where Medicare reimbursement structures and pulmonologist concentration patterns create distinct regional demand clusters across North America, Europe, and Asia-Pacific.
United States
CMS Hospital-at-Home waivers accelerate remote patient monitoring deployment among Medicare Advantage plans in Florida and Arizona retirement corridors. FDA twelve-month exacerbation endpoint requirements elevate clinical trial costs for long-acting bronchodilator developers. The Cleveland Clinic and Mayo Clinic pulmonary centers concentrate interventional lung volume reduction procedure volumes.
Germany
EMA MDR Class IIa reclassification for active therapeutic devices extends notified body review queues to 14-18 months for combination inhaler platforms. German hospital procurement systems favor soft-mist inhaler technology with superior lung deposition rates over traditional pressurized devices. The Ruhr industrial region and Bavarian medical technology clusters host refurbishment networks for circular oxygen concentrator deployment.
China
NMPA priority review voucher compression reduces regulatory timelines for innovative respiratory delivery systems targeting domestic manufacturing scale. Dual carbon goals under MEE oversight reshape medical device production standards for portable concentrator exports. The Yangtze River Delta medical device manufacturing belt concentrates domestic inhaler component supply chains.
United Kingdom
NHS bundled payment pilots for pulmonary rehabilitation redirect post-exacerbation care from acute hospitals toward community-based exercise programs. NICE technology appraisals apply cost-effectiveness thresholds that favor generic bronchodilator substitution over patent-protected combinations. London and Manchester academic medical centers maintain clinical trial site density for COPD-emphysema overlap phenotypes.
India
CDSCO accelerated approval pathways for respiratory devices address underdiagnosis rates exceeding 70 percent in Bihar and Uttar Pradesh rural districts. PLI scheme incentives attract portable oxygen concentrator assembly operations for price-sensitive distribution networks. The Maharashtra pharmaceutical manufacturing corridor and Karnataka medical device parks concentrate domestic production capacity.
Emphysema Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the emphysema therapeutic landscape. Large-cap pharmaceutical conglomerates with respiratory divisions dominate fixed-dose combination inhaler portfolios through patent-protected LAMA/LABA molecules. Mid-scale device specialists concentrate on soft-mist delivery platforms and portable oxygen concentrator engineering. Generic manufacturers compete on price for mature bronchodilator molecules with expired exclusivity. Consolidation pressures intensify as FDA trial duration requirements squeeze venture-funded development programs and EMA MDR compliance costs favor scaled quality management systems.
Within the large-cap pharmaceutical tier, Boehringer Ingelheim GmbH, GlaxoSmithKline plc, and AstraZeneca plc exemplify divergent strategic positioning. The German family-owned structure of Boehringer Ingelheim GmbH supports long-horizon device platform investment exemplified by the Respimat soft-mist system. GlaxoSmithKline plc, as a UK-based public limited company, occupies a position anchored in fixed-dose combination breadth across multiple continents. AstraZeneca plc represents the biologic-specialist archetype with pipeline concentration on eosinophilic inflammation subsets. These three entities collectively illustrate how geographic origin and corporate governance structure shape competitive approach without requiring identical strategic moves.
| Leading Market Players |
|---|
| Boehringer Ingelheim GmbH |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Verona Pharma plc |
| Others |
Supply Flow & Price Mechanics
Respimat-platform manufacturing scale at Boehringer Ingelheim GmbH facilities creates steep unit-cost curves that compress price floors for soft-mist inhalers while elevating barriers for device competitors. This concentration of production know-how in German and United States manufacturing clusters simultaneously anchors premium pricing for patented combinations and squeezes margin headroom for generic pressurized metered-dose alternatives.
Pricing Analysis
United States Medicare Part D formularies command 40-60 percent discounts below German hospital procurement rates for identical LAMA/LABA molecules. Three-tier pricing structure across premium, standard, and economy levels separates patented Respimat devices from authorized generics and Indian-manufactured dry-powder alternatives. Pricing pressure stems from anti-IL5 biologics diverting payer budgets toward eosinophilic COPD subsets. Price-sensitive buyers cluster in rural Indian districts where out-of-pocket spend dominates, while German sickness funds exhibit lowest sensitivity due to reference pricing mechanisms.
Supply Chain Analysis
Inventory buffers for portable oxygen concentrators stretch 8-12 weeks as semiconductor lead times for pulse-dose valves fluctuate. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta hosting 60 percent of mesh nebulizer component fabrication. Raw material dependencies span medical-grade aluminum for compressor housings, lithium-ion cells for battery packs, and palladium catalysts for oxygen separation membranes. Single-source vulnerability concentrates in Qatar and United States helium refining for MRI-guided lung volume reduction coil procedures. Distribution runs through Medicare durable medical equipment regional suppliers and Amazon Business direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as anti-IL5 and anti-IL13 biologics capture eosinophilic COPD-emphysema overlap patients previously managed with maintenance inhalers.
For Market Incumbents: Secure formulary positioning for fixed-dose LAMA/LABA combinations through real-world evidence generation on exacerbation reduction. Deepen backward integration into soft-mist device component manufacturing to protect Respimat-platform margins from generic device entrants. Anchor hospital system partnerships in Florida and Arizona retirement corridors where Medicare Advantage concentration is accelerating. For New Entrants and Emerging Players: NMPA priority review voucher fast-tracks compress regulatory timelines for innovative respiratory delivery systems targeting Chinese domestic manufacturing scale. White-space opportunities concentrate in Bihar and Uttar Pradesh rural districts where underdiagnosis exceeds 70 percent and portable oxygen concentrator distribution networks remain unbuilt. Telemedicine-integrated rehabilitation subscriptions offer asset-light entry outside traditional clinic infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors device-platform specialists with captive soft-mist engineering capabilities over molecule-centric pharmaceutical portfolios. Long-term viability across the projection horizon hinges on reimbursement strategy execution in hospital-at-home channels. Signal to watch: CMS waiver permanence beyond pilot status for acute-level homecare services.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Execution | CMS Hospital-at-Home waiver permanence determines addressable market expansion for remote monitoring platforms. |
| Regulatory Approval Pathway | FDA twelve-month exacerbation endpoint requirements elevate clinical trial costs and compress venture-funded development timelines. |
| Manufacturing Scale-Up | Yangtze River Delta concentrator assembly operations leverage NMPA priority review for domestic market penetration. |
| Platform Integration | Closed-loop oxygen titration with SpO2 sensor feedback automates manual flow-rate adjustments in Medicare Advantage plans. |
| CE Marking Pathway | EMA MDR Class IIa reclassification extends German notified body review queues to 14-18 months for combination inhaler devices. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Primary interviews engaged pulmonologists, hospital procurement managers, durable medical equipment supplier executives, and payer formulary directors across United States, German, and Chinese markets. Bottom-up patient-volume modeling triangulates against top-down pharmaceutical revenue segmentation.
Segmentation dimensions modeled span product type, delivery mode, end user channel, and therapy area across the projection horizon. CAGRs derive from patient population epidemiology, reimbursement trajectory assumptions, and technology substitution curves for closed-loop oxygen systems. Forecast inputs incorporate CMS waiver permanence probability and EMA MDR compliance cost escalations for active therapeutic devices.
Underlying assumptions cover stable helium supply for interventional procedures and sustained Medicare Advantage supplemental benefit expansion, with deviation risk concentrated in biologic substitution rates and pulmonologist workforce scarcity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Intensive Care Unit (ICU) Ventilators Market
Respiratory Care
Global Neonatal Intensive Care Respiratory Devices Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Global Respiratory Disposable Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Lung Injury Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Global Respiratory Care Devices Market