
 Lung Injury Market | 2026-2036
Lung Injury Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Injury Market Foresight
North American biopharmaceutical capacity is narrowing as developers prioritize respiratory precision medicine. GlaxoSmithKline plc leverages its inhaled corticosteroid platform to sustain leadership across hospital and ambulatory channels. Regeneron Pharmaceuticals, Inc. anchors its position through monoclonal antibody R&D targeting inflammatory lung pathways. AstraZeneca PLC differentiates via biologics development for severe acute lung injury subpopulations.
Lung injury encompasses acute and chronic damage to pulmonary parenchyma, vasculature, or pleura resulting from trauma, infection, toxic inhalation, or mechanical ventilation, with severity graded by PaO2/FiO2 ratios and radiographic opacity scores. Mechanical ventilators represent the most mature product segment, while oxygen therapy devices capture expanding home care demand following hospital discharge protocols. Pharmacological treatment approaches command the deepest margin pools due to biologic pricing and chronic administration requirements, whereas non-pharmacological modalities face reimbursement compression in public payer systems.
The FDA maintains stringent efficacy thresholds for acute respiratory distress syndrome drug approvals, while the EMA's MDR framework reclassifies high-risk ventilator and oxygen delivery systems under enhanced conformity assessment procedures. These dual regulatory tracks compel manufacturers to maintain parallel clinical and quality management systems. Stakeholders must monitor evolving post-market surveillance requirements for artificial intelligence-integrated diagnostic imaging platforms as predictive algorithms gain traction in early lung injury detection protocols.
Market Dynamics
The FDA's acute respiratory distress syndrome efficacy thresholds and the EMA's MDR reclassification of high-risk respiratory devices are forcing parallel clinical and quality management investments across manufacturers.
Growth Catalysts
- Hospital critical care expansion:Critical care units in Germany and the United States are expanding adoption of advanced respiratory support systems following post-acute discharge protocols.
- EMA MDR framework alignment:Enhanced conformity assessment procedures for ventilator and oxygen delivery systems are accelerating quality infrastructure upgrades among European manufacturers.
- Pulmonary research infrastructure:Reimbursement frameworks for innovative lung therapies in Germany are concentrating demand for precision respiratory interventions.
Market Restraints
- Biologic input cost volatility:Monoclonal antibody production costs for inflammatory lung pathway targeting create margin pressure on pharmacological treatment developers.
- Reimbursement compression:Public payer systems in France and Italy are constraining margins for non-pharmacological respiratory modalities including mechanical ventilation support.
- Regulatory friction:The FDA's stringent ARDS drug approval thresholds extend development timelines and elevate clinical trial expenditure requirements.
Strategic Opportunities
- Home care oxygen therapy:Post-hospital discharge protocols in Japan and South Korea are creating channel expansion for portable oxygen delivery device manufacturers.
- AI-integrated diagnostic imaging:Predictive algorithm traction in early lung injury detection is virtualizing radiographic opacity scoring workflows across tertiary care centers.
- Biologics for severe subpopulations:Underpenetrated severe acute lung injury segments present formulation development white space for differentiated therapeutic platforms.
Industry Challenges
- Post-market surveillance integration:Artificial intelligence-integrated imaging platforms face evolving FDA and EMA surveillance requirements for algorithmic decision-support validation.
- Parallel quality system maintenance:Manufacturers must sustain dual clinical and quality management infrastructures to satisfy divergent FDA and EMA regulatory tracks simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Injury Market |
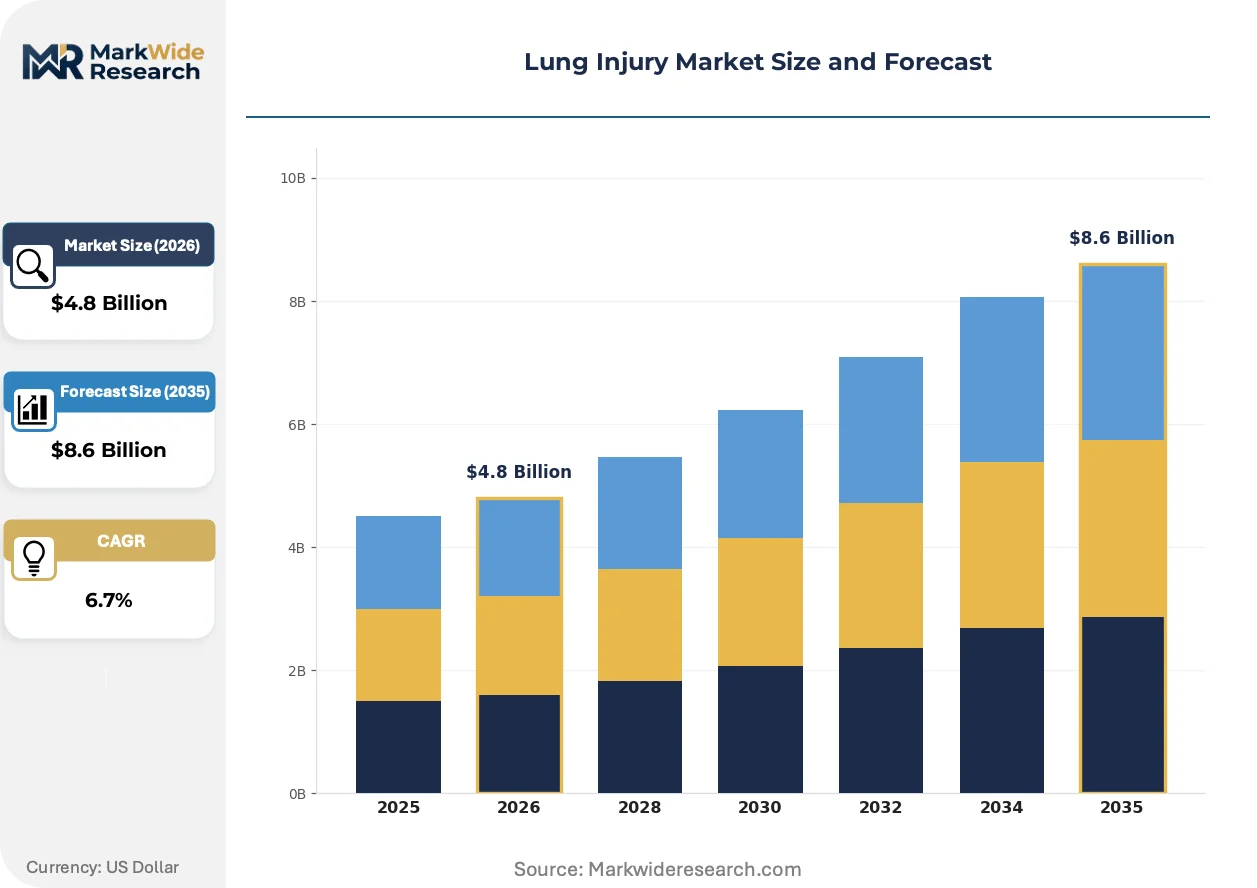
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Imaging, Mechanical Ventilators, Oxygen Therapy Devices, Corticosteroids Delivery Mode: Aerosol Inhalation, Intravenous, Oral Administration, Nasal Cannula End User: Hospitals, Home Care Settings, Rehabilitation Centers, Emergency Services Treatment Approach: Pharmacological, Non-Pharmacological, Surgical Intervention, Supportive Care |
| Companies Covered | GlaxoSmithKline plc, Regeneron Pharmaceuticals, Inc., Theravance Biopharma, Windtree Therapeutics, Inc., AstraZeneca PLC, Novartis International AG, Merck & Co., Inc., Pfizer Inc., Stemedica Cell Technologies, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Injury Market Shifts & Advancements
Respiratory precision medicine is displacing standardized ventilation protocols across hospital systems. Three interconnected developments are compressing development timelines and reshaping competitive positioning.
Digital twin modeling of pulmonary mechanics is virtualizing mechanical ventilation parameter optimization. Intensive care units at academic medical centers in the United States and Germany are deploying these simulations to reduce ventilator-induced lung injury incidence. The technology is compressing reliance on empirical tidal volume protocols by enabling patient-specific respiratory compliance predictions.
The EMA's Medical Device Regulation framework is reclassifying high-risk oxygen delivery systems under enhanced conformity assessment procedures. Manufacturers face extended notified body review timelines and expanded clinical evidence requirements. European ventilator producers are responding by consolidating technical documentation and post-market clinical follow-up systems.
Critical care procurement is consolidating around value-based contracting frameworks that bundle device acquisition with outcomes guarantees. Hospital purchasing coalitions in France and the Netherlands are replacing transactional equipment procurement with multi-year respiratory support service agreements. This behavioral shift is most visible in integrated delivery networks where total cost of care metrics govern supplier selection.
Lung Injury Market Segmentation
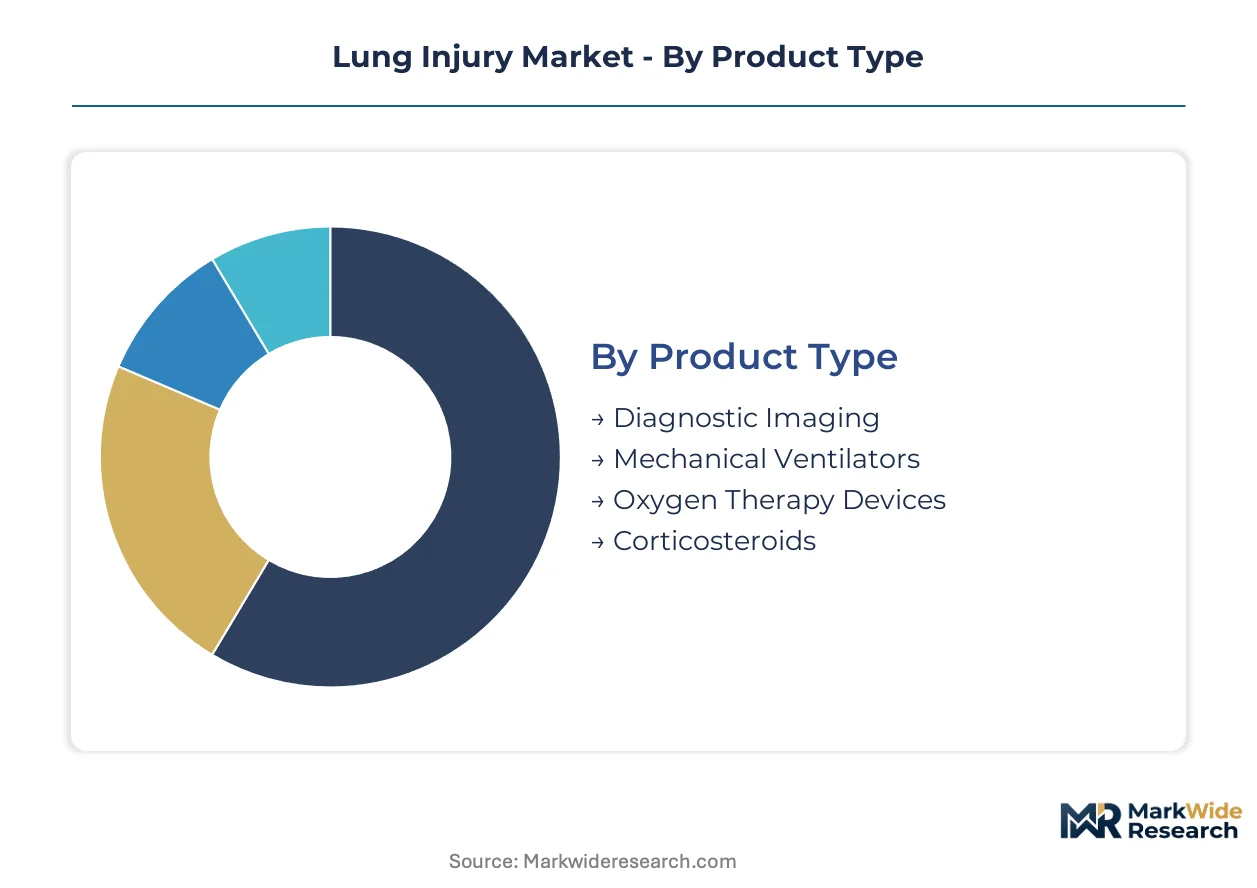
Segmentation in lung injury management reveals how treatment complexity fragments across acute intervention, chronic maintenance, and transitional care pathways. Each dimension — product type, delivery mode, end user, and treatment philosophy — carries distinct margin profiles and regulatory requirements that shape manufacturer resource allocation.
Product Type:
Diagnostic imaging and mechanical ventilation anchor hospital procurement budgets, while oxygen therapy and corticosteroids capture divergent cost-recovery models across inpatient and ambulatory channels.
- Diagnostic Imaging:Computed tomography and chest radiography systems grade lung injury severity through radiographic opacity scoring. Demand concentrates in United States tertiary care centers where AI-integrated platforms are virtualizing early detection workflows.
- Mechanical Ventilators:Positive-pressure systems with lung-protective tidal volume protocols represent the most mature hardware segment. German critical care units are expanding adoption of advanced respiratory support systems following post-acute discharge protocols.
- Oxygen Therapy Devices:Portable concentrators and high-flow nasal cannula systems bridge hospital-to-home transitions. Japanese and South Korean post-discharge protocols are creating channel expansion for portable oxygen delivery manufacturers.
- Corticosteroids:Inhaled and systemic anti-inflammatory formulations target inflammatory lung pathways. Biologic pricing and chronic administration requirements command the deepest margin pools in pharmacological treatment.
The dominant share belongs to mechanical ventilators, while oxygen therapy devices are closing the gap fastest.
Delivery Mode:
Route selection depends on injury acuity, patient respiratory compliance, and reimbursement tier — with aerosol and intravenous commanding premium positioning over oral and nasal alternatives.
- Aerosol Inhalation:Nebulized and metered-dose delivery achieves direct alveolar deposition for corticosteroid and bronchodilator administration. Home care settings in Germany favor this modality for post-hospital maintenance therapy.
- Intravenous:Systemic antibiotic and anti-inflammatory infusion addresses severe acute lung injury requiring rapid therapeutic onset. Hospital critical care units absorb the highest volume of IV delivery for ARDS management.
- Oral Administration:Tablet and liquid formulations enable outpatient chronic management. Rehabilitation centers leverage oral corticosteroid tapers during pulmonary recovery protocols.
- Nasal Cannula:Low-flow and high-flow oxygen delivery provides non-invasive respiratory support. Emergency services deploy portable nasal systems for pre-hospital stabilization.
Aerosol inhalation captures the largest installed base, though intravenous delivery shows the steepest expansion trajectory in acute care.
End User:
Facility type determines reimbursement pathway, device sophistication requirements, and patient acuity thresholds — with hospitals and home care representing opposite poles of the care continuum.
- Hospitals:Tertiary and community acute care facilities manage the full spectrum from emergency intubation to step-down ventilation weaning. United States hospital purchasing coalitions are consolidating procurement around value-based contracting frameworks.
- Home Care Settings:Durable medical equipment suppliers and visiting nurse services manage long-term oxygen therapy and non-invasive ventilation. Japan's aging demographic is expanding home care channel demand for portable respiratory devices.
- Rehabilitation Centers:Post-acute facilities specialize in ventilator weaning and pulmonary function recovery. German reimbursement frameworks for innovative lung therapies support extended rehabilitation stays.
- Emergency Services:Pre-hospital and inter-facility transport teams require ruggedized portable systems. Urban emergency medical services in the United States are upgrading fleet oxygen delivery capabilities.
Hospitals retain the dominant share, while home care settings are expanding most quickly following discharge protocol standardization.
Treatment Approach:
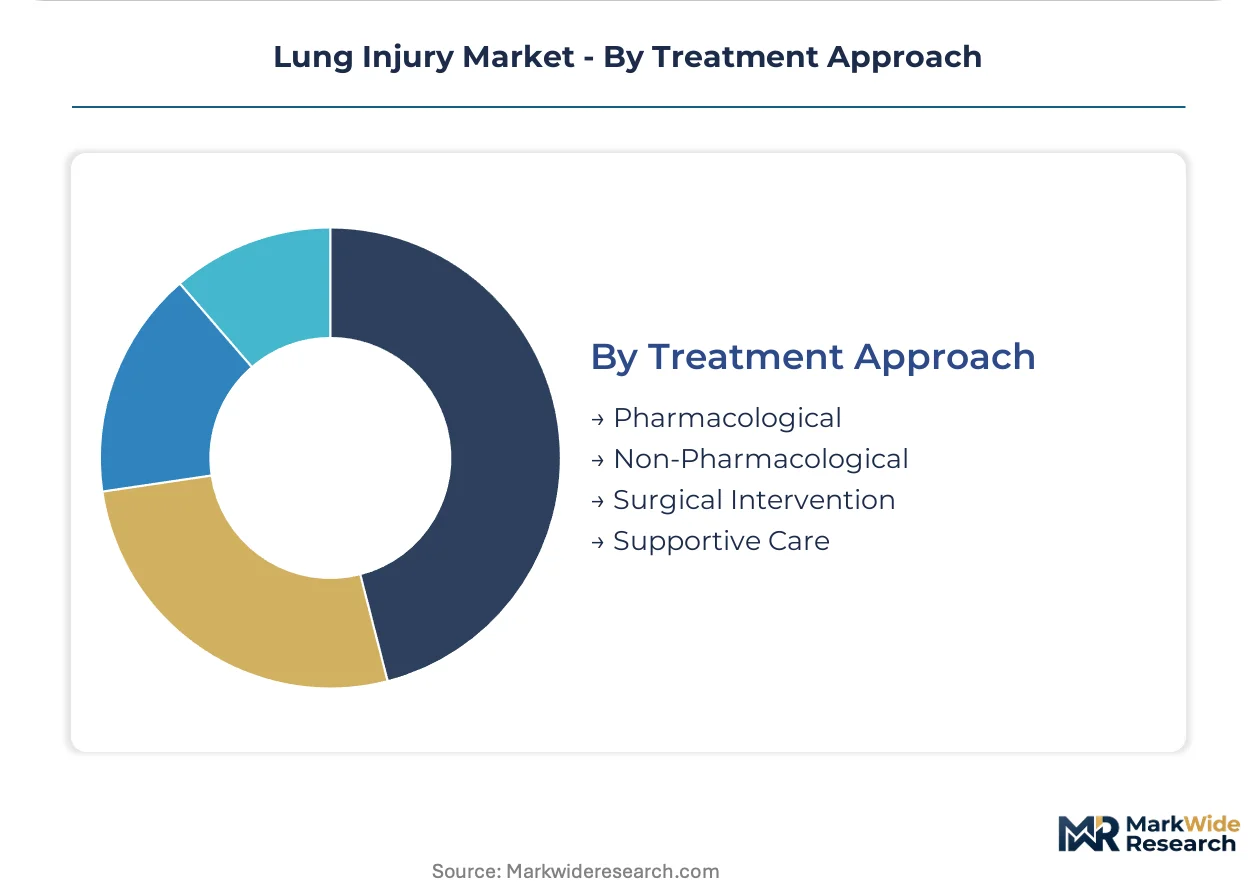
Philosophical positioning across pharmacological, device-based, and procedural interventions creates distinct competitive arenas with divergent R&D investment requirements and regulatory scrutiny levels.
- Pharmacological:Biologics and small-molecule therapies targeting inflammatory lung pathways require FDA stringent efficacy thresholds for ARDS drug approvals. Monoclonal antibody R&D anchors developer pipelines despite production cost volatility.
- Non-Pharmacological:Mechanical ventilation, oxygen therapy, and physical rehabilitation modalities face reimbursement compression in French and Italian public payer systems. EMA MDR reclassification is accelerating quality infrastructure upgrades among European device manufacturers.
- Surgical Intervention:Thoracic procedures including lung volume reduction and pleural drainage address structural complications. Tertiary centers in Germany and the United States concentrate specialized surgical volume.
- Supportive Care:Prone positioning, fluid management, and nutritional support protocols complement primary therapy. Critical care units are integrating digital twin modeling of pulmonary mechanics to optimize supportive parameter selection.
Pharmacological approaches command the deepest margins, while non-pharmacological modalities are gaining share fastest through home care channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pulmonary research infrastructure and United States hospital purchasing coalitions concentrate supply-side investment in advanced respiratory support systems. FDA efficacy thresholds and EMA MDR reclassification create parallel compliance burdens that fragment manufacturing footprints across Atlantic markets. Reimbursement frameworks in Japan and South Korea are accelerating home care channel development for portable oxygen delivery.
United States
Hospital purchasing coalitions in Illinois and Texas are consolidating procurement around value-based contracting frameworks for mechanical ventilation systems. FDA stringent efficacy thresholds for ARDS drug approvals extend development timelines and elevate clinical trial expenditure requirements. Tertiary care centers in Massachusetts and California are deploying AI-integrated diagnostic imaging platforms for early lung injury detection protocols.
Germany
Critical care units in Bavaria and North Rhine-Westphalia are expanding adoption of advanced respiratory support systems following post-acute discharge protocols. EMA MDR framework reclassification of high-risk ventilator systems under enhanced conformity assessment procedures accelerates quality infrastructure upgrades. Pulmonary research clusters in Heidelberg and Berlin concentrate monoclonal antibody R&D for inflammatory lung pathway targeting.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas are expanding home care channel demand for portable oxygen concentrators and high-flow nasal cannula systems. METI industrial policy supports domestic manufacturing of respiratory devices through targeted subsidy programs. Medical device distributors in Kansai region are building logistics networks for post-hospital discharge oxygen therapy delivery.
South Korea
National health insurance reimbursement for home oxygen therapy is creating channel expansion for portable delivery device manufacturers in Seoul Capital Area. MFDS regulatory harmonization with FDA standards accelerates approval pathways for innovative lung injury therapeutics. Biotech incubators in Daejeon-Sejong corridor are attracting venture capital for severe acute lung injury subpopulation targeting.
United Kingdom
NHS procurement frameworks in London and Manchester are bundling ventilator acquisition with outcomes guarantees under respiratory support service agreements. MHRA post-Brexit regulatory autonomy is diverging from EMA MDR implementation timelines for oxygen delivery systems. Academic medical centers in Scotland are pioneering digital twin modeling of pulmonary mechanics for ventilator parameter optimization.
Lung Injury Market Competitive Landscape
Integrated pharmaceutical conglomerates and respiratory device specialists split the market across pharmacological and non-pharmacological intervention domains. The competitive structure consolidates around three strategic archetypes: biologics developers targeting inflammatory pathways, inhaled corticosteroid platform sustainers, and mechanical ventilation hardware manufacturers. Dominant competitive moves include strategic partnerships for AI-integrated diagnostic imaging and portfolio diversification into home care oxygen therapy channels.
Within the biologics development tier, Regeneron Pharmaceuticals, Inc. and AstraZeneca PLC exemplify monoclonal antibody R&D anchoring for severe acute lung injury subpopulations. GlaxoSmithKline plc occupies a position representing inhaled corticosteroid platform sustainers across hospital and ambulatory channels. These three entities represent the strategic archetypes that manufacturers must benchmark against for positioning within FDA-stringent and EMA-MDR-parallel regulatory environments.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Regeneron Pharmaceuticals, Inc. |
| Theravance Biopharma |
| Windtree Therapeutics, Inc. |
| AstraZeneca PLC |
| Novartis International AG |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Stemedica Cell Technologies, Inc |
| Others |
Supply & Pricing Matrix
Undercapacity in German precision ventilator component manufacturing compresses supplier bargaining power while amplifying price premiums for EMA MDR-certified respiratory systems. This utilization squeeze forces buyers into longer-term offtake commitments and tiered service bundling that obscures pure equipment pricing.
Pricing Analysis
FDA stringent efficacy thresholds for ARDS drug approvals dictate the pricing tier structure across pharmacological interventions, separating biologic developers with full approval pathways from those stalled in Phase II validation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and post-market surveillance commitment. Cost compression in non-pharmacological modalities is intensifying because French and Italian public payer systems are constraining mechanical ventilation reimbursement rates. Hospital purchasing coalitions demonstrate the highest price sensitivity, while academic medical centers absorb premium positioning for AI-integrated diagnostic platforms.
Supply Chain Analysis
Export-control restrictions on semiconductor components for ventilator control systems limit flows from Taiwanese and South Korean foundries into European respiratory device assembly. Supply concentration in German precision machining, Chinese polymer molding, and United States sensor fabrication creates multi-node vulnerability. Raw material dependencies span medical-grade aluminum alloys, silicone membranes, and ASIC controllers. Single-source vulnerability sits with German notified body capacity for EMA MDR conformity assessments. Distribution runs through hospital purchasing coalitions and GPO contracts in the United States, direct tender processes in Germany, and durable medical equipment suppliers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-integrated diagnostic imaging platforms that virtualize radiographic opacity scoring and compress demand for traditional mechanical ventilation hardware.
For Market Incumbents: Pre-empt algorithmic displacement by embedding digital twin modeling capabilities into ventilator parameter optimization systems. Secure backward integration into German precision component supply to buffer EMA MDR notified body bottlenecks. Anchor hospital purchasing coalitions through multi-year respiratory support service agreements that bundle hardware with outcomes guarantees. For New Entrants and Emerging Players: Establish a beachhead in Japanese home care oxygen therapy channels where aging demographics and METI subsidy programs lower entry barriers. Target South Korean biotech incubators in the Daejeon-Sejong corridor for severe acute lung injury subpopulation formulations. Lead with portable concentrator platforms that satisfy post-hospital discharge protocols in Seoul Capital Area reimbursement frameworks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing for monoclonal antibody inflammatory lung pathway targeting. Five-to-ten year viability favors developers with FDA breakthrough therapy designation momentum and parallel EMA MDR quality system infrastructure. Signal to monitor: MFDS regulatory harmonization velocity with FDA standards as indicator of South Korean market access premium compression.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Diagnostic Imaging Development | Virtualizes radiographic opacity scoring workflows across United States tertiary care centers. |
| EMA MDR Quality System Consolidation | Accelerates notified body readiness for German ventilator manufacturers facing enhanced conformity assessments. |
| Home Care Channel Partnership | Captures Japanese aging demographic demand for portable oxygen concentrator logistics networks. |
| Biologics Pipeline Diversification | Addresses underpenetrated severe acute lung injury subpopulations through monoclonal antibody R&D. |
| Value-Based Contracting Framework | Bundles mechanical ventilator acquisition with outcomes guarantees under French and Dutch hospital purchasing coalitions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA ARDS drug approval filings, EMA MDR technical documentation, and hospital procurement database records. Intensive care unit directors, regulatory affairs leads at respiratory device manufacturers, GPO contracts managers, and biomedical engineers at German academic medical centers provided structured input. ClinicalTrials.gov registries, CMS Medicare reimbursement schedules, and Japanese METI industrial policy disclosures furnished validation anchors. Bottom-up segmentation sizing and top-down macroeconomic calibration were cross-checked for convergence.
Forecast inputs span treatment approach stratification, end-user facility type, and regional regulatory cluster differentiation across the projection horizon. Pharmacological versus non-pharmacological intervention splits, hospital versus home care delivery mode trajectories, and aerosol versus intravenous route preferences were modeled. CAGRs were derived from segment-level volume and value buildups validated against macroeconomic health expenditure growth assumptions. Industry-specific inputs incorporated FDA breakthrough therapy designation velocity and EMA notified body capacity constraints.
Stress conditions across biologic input cost volatility, German precision manufacturing capacity utilization, and Japanese home care reimbursement policy stability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and payer behavior continuity. Material shifts in FDA ARDS efficacy threshold stringency or EMA MDR implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Lower Respiratory Tract Infection Treatment Market
Respiratory Care
Global Respiratory Care Devices Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Global Chronic Obstructive Pulmonary Disease Market
Respiratory Care
Respiratory Distress Syndrome Management Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Asthma and COPD Drugs Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Pulmonary Edema Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
Global Respiratory Heaters Market