
 Global Basal Insulin Market | 2026-2036
Global Basal Insulin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Basal Insulin Market Foresight
Multi-source API procurement is consolidating around vertically integrated manufacturers with captive fermentation capacity. Novo Nordisk leverages its recombinant DNA platform to sustain cost leadership in active pharmaceutical ingredient production. Sanofi anchors European supply through its biotechnology manufacturing network in France. Eli Lilly and Company competes on analog formulation expertise, while Biocon differentiates through biosimilar development capabilities.
Basal insulin denotes long-acting or ultra-long-acting recombinant human insulin analogs engineered for steady 18-42 hour pharmacokinetic profiles, typically produced via microbial fermentation in Escherichia coli or Saccharomyces cerevisiae followed by chromatographic purification and zinc crystallization. Its primary commercial purpose is mimicking physiologic basal glucose suppression in diabetic patients requiring background insulin coverage between meals and overnight. Ultra-long-acting analogs command premium positioning due to reduced nocturnal hypoglycemia risk, while biosimilar segments expand through health system procurement tenders. Home care delivery through insulin pens dominates volume, though pump-compatible formulations capture higher per-unit value in intensive insulin management.
FDA bioequivalence standards for biosimilar interchangeability and EMA biosimilar quality guidelines shape product development roadmaps and market access timelines. WHO prequalification requirements influence procurement eligibility in low- and middle-income country tenders. Stakeholders must monitor evolving interchangeability designation criteria and their impact on pharmacy-level substitution policies.
Market Dynamics
Biosimilar interchangeability designations by FDA and EMA are fragmenting pricing power across the basal insulin value chain, forcing originators to defend formulary position through device-drug bundling rather than molecule exclusivity alone.
Growth Catalysts
- Type 2 diabetes home care expansion:Patients managing background glucose suppression outside clinical settings drive volume through pen-based delivery systems. Germany and Japan subsidize home monitoring infrastructure.
- WHO prequalification pathways:Low- and middle-income country tenders now accept prequalified biosimilars, expanding addressable patient populations in sub-Saharan Africa and Southeast Asia procurement pools.
- Ultra-long-acting analog development:Recombinant DNA platform advances enable 42-hour pharmacokinetic profiles that reduce nocturnal hypoglycemia events. Endocrinology practices in the United States prioritize these formulations for elderly polypharmacy patients.
Market Restraints
- API supply concentration:Captive fermentation capacity concentrates among three vertically integrated manufacturers. Any disruption at Danish or French biotechnology facilities propagates through global finished-dose supply.
- FDA interchangeability study costs:Switching studies required for pharmacy-level substitution add 18-24 months to biosimilar timelines. Development capital locks up longer than in EMA jurisdictions.
- GLP-1 receptor agonist substitution:Semaglutide and tirzepatide therapies displace insulin initiation in early Type 2 diabetes. Endocrinologists delay basal insulin prescribing where cardiovascular risk reduction is prioritized.
Strategic Opportunities
- Connected pen ecosystem convergence:Bluetooth-enabled dose capture integrated with continuous glucose monitors closes feedback loops for intensive insulin management. Germany's DiGA fast-track reimburses such digital therapeutics.
- Indian biosimilar export acceleration:CDSCO-approved facilities with WHO prequalification capture African and Latin American tender volumes previously served by European originators.
- Pump-compatible formulation whitespace:U-300 and U-500 concentrations optimized for insulin pump pharmacokinetics command premium positioning in United States intensive management practices.
Industry Challenges
- Cold chain integrity across last-mile distribution:Temperature excursions in ambient storage conditions degrade zinc-crystallized insulin stability. Logistics providers in tropical climates lack validated packaging for 42-hour transit windows.
- EMA/FDA divergence on immunogenicity thresholds:Discordant analytical similarity requirements force duplicate analytical development. Biosimilar sponsors absorb redundant characterization costs.
- Legacy pen platform interoperability:Needle thread and cartridge dimensions vary across originator devices. Patients switching biosimilars face retraining friction and dosing error risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Basal Insulin Market |
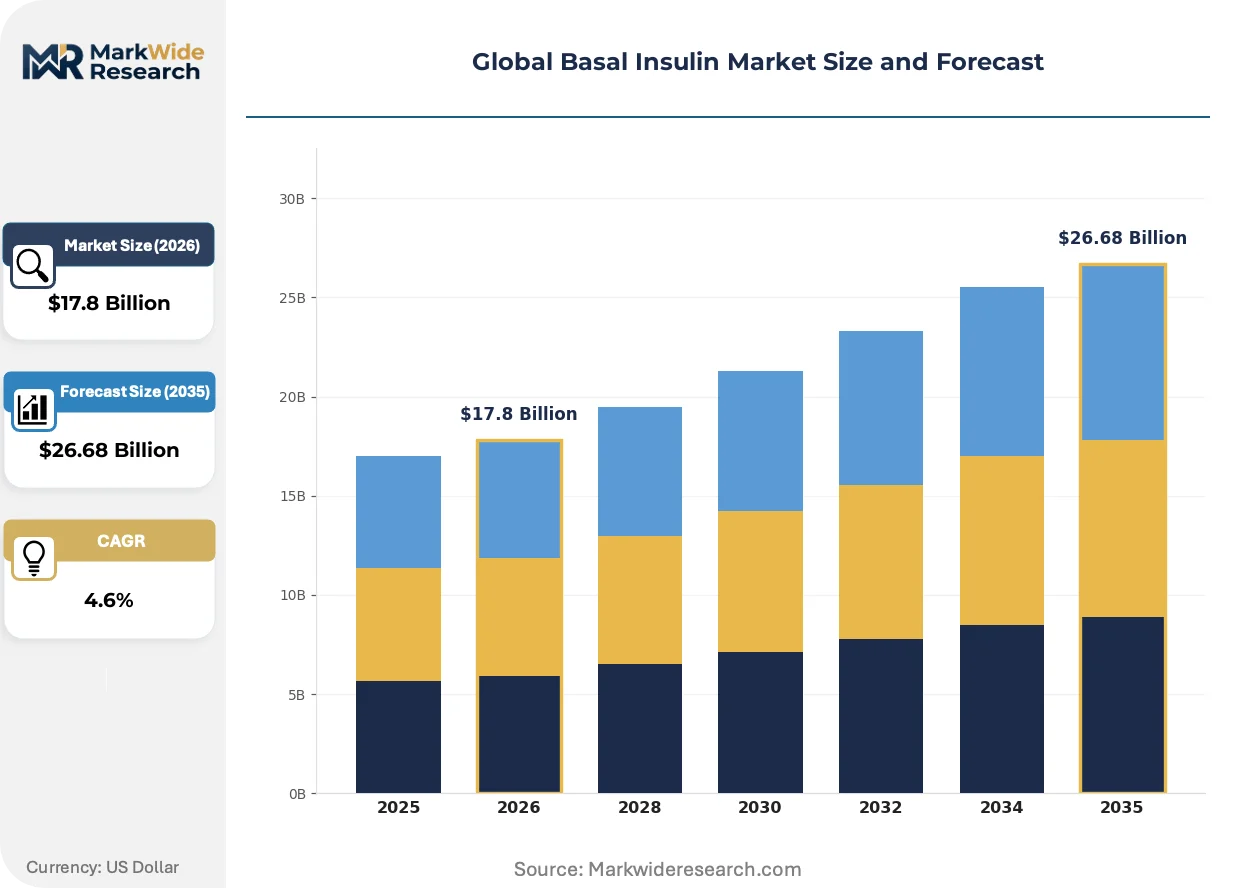
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long-Acting, Ultra-Long-Acting, Intermediate-Acting, Combination, Biosimilar Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes, Insulin Resistance End User: Hospitals, Diabetes Clinics, Home Care, Specialty Pharmacies, Endocrinology Centers Delivery Mode: Insulin Pens, Vials, Pumps, Inhalers, Pre-Filled Syringes |
| Companies Covered | Biocon, Tonghua Dongbao Pharmaceutical, Novo Nordisk, Merck, United Laboratories, Sanofi, Gan & Lee Pharmaceuticals, Wockhardt, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Basal Insulin Market Shifts & Advancements
Recombinant protein engineering and digital delivery systems are converging to redefine how basal insulin achieves physiological glucose suppression, with regulatory science racing to keep pace with platform innovation.
Microbial expression systems with optimized codon usage are rewriting the economics of long-acting analog production. Contract development organizations in South Korea and India deploy CRISPR-edited Saccharomyces cerevisiae strains that boost titer yields 40% above legacy platforms. CDMOs with captive downstream purification capacity capture formulation partnerships from originators seeking cost parity against biosimilar entrants.
EMA's revised biosimilar quality guidelines now mandate enhanced immunogenicity surveillance for products with modified glycosylation patterns. Manufacturers must maintain 24-month post-approval safety databases before interchangeability designation. French and German health technology assessment bodies weigh these surveillance costs heavily in tender scoring algorithms.
Hospital procurement consortia in the United States are consolidating insulin purchasing through 340B program eligibility expansion. Specialty pharmacies now manage prior authorization and patient assistance coordination that previously fragmented across retail channels. This channel compression concentrates volume with distributors holding cold-chain validation credentials across all 50 states.
Global Basal Insulin Market Segmentation
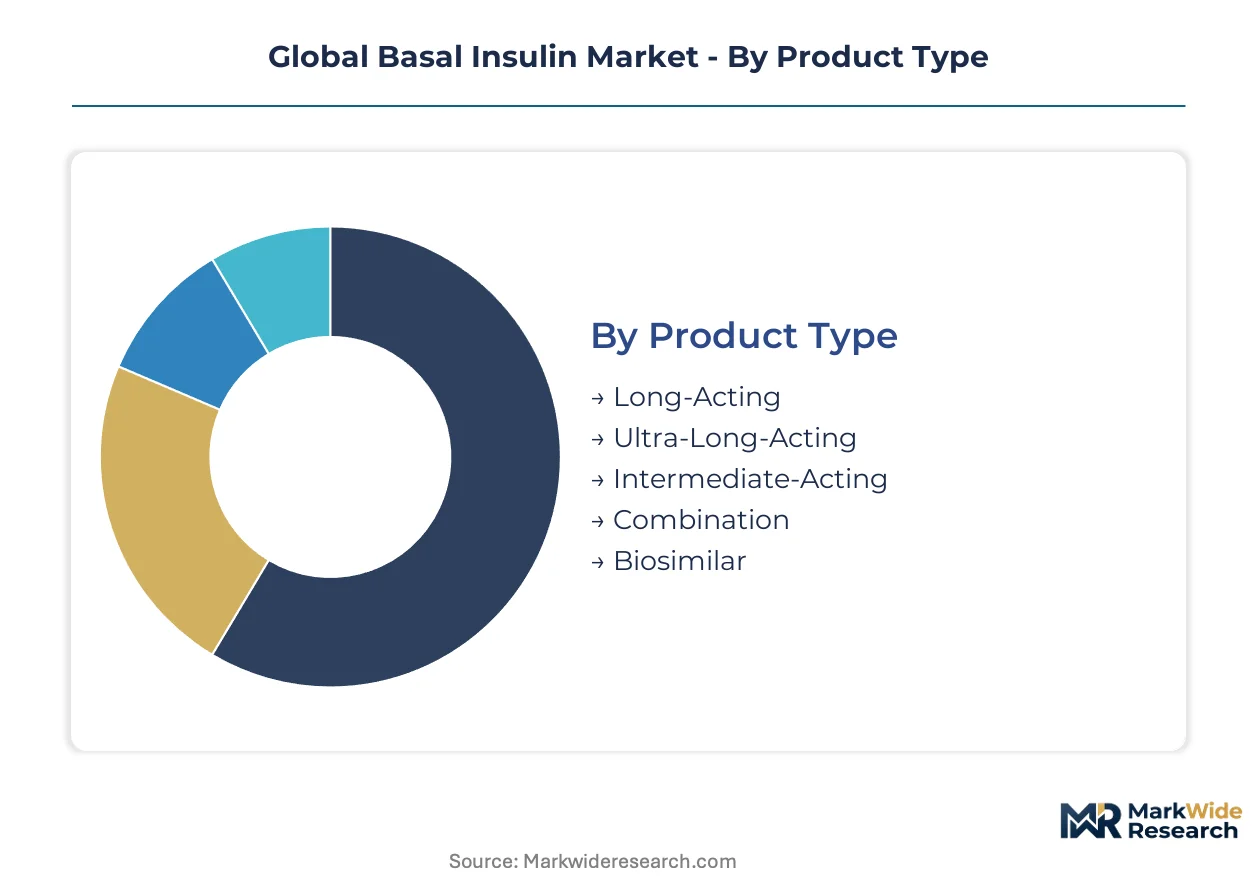
Segmentation in the basal insulin market determines which products qualify for pharmacy-level substitution under FDA interchangeability rules and which require specialized distribution infrastructure. Each dimension carries distinct regulatory burdens, cold-chain requirements, and reimbursement pathways that shape commercial strategy.
Product Type:
Ultra-long-acting and biosimilar segments face the steepest certification requirements, with FDA interchangeability studies adding 18-24 months to development timelines for products seeking automatic substitution status.
- Ultra-Long-Acting:Recombinant DNA-engineered analogs deliver 42-hour pharmacokinetic profiles through albumin-binding fatty acid acylation. United States endocrinology practices prioritize these formulations for elderly patients with nocturnal hypoglycemia risk, though zinc crystallization complexity raises manufacturing costs.
- Biosimilar:Follow-on products must demonstrate analytical similarity and immunogenicity equivalence to reference listed drugs under EMA quality guidelines and FDA bioequivalence standards. WHO prequalification unlocks procurement eligibility in sub-Saharan Africa and Southeast Asia tenders.
- Long-Acting:Glargine and detemir analogs dominate volume through established pen-based delivery systems.
- Intermediate-Acting:NPH insulin retains formulary position in cost-constrained health systems.
- Combination:Fixed-ratio basal-bolus or basal-GLP-1 products target polypharmacy reduction.
Long-acting formulations sit at the top of the volume ranking, with biosimilars climbing the fastest as health system procurement tenders expand.
Application:
Patient phenotype determines reimbursement tier and device bundling strategy, with Type 2 diabetes commanding home care infrastructure investment while Type 1 requires intensive management protocols.
- Type 2 Diabetes:Represents the dominant addressable population, with background insulin initiation typically delayed until oral antihyperglycemic failure. Germany and Japan subsidize home monitoring infrastructure that drives pen-based volume.
- Type 1 Diabetes:Requires absolute insulin deficiency coverage with pump-compatible formulations capturing premium positioning. United States intensive management practices prioritize U-300 and U-500 concentrations for insulin pump pharmacokinetics.
- Gestational Diabetes:Necessitates pregnancy safety databases and placental transfer studies.
- Prediabetes:Limited approved indications constrain commercial opportunity.
- Insulin Resistance:U-500 formulations address severe cases in metabolic syndrome patients.
Type 2 diabetes commands the largest patient base, while Type 1 applications show the steepest expansion trajectory in pump-compatible segments.
End User:
Channel selection dictates cold-chain validation requirements and patient assistance program design, with home care and specialty pharmacy segments consolidating volume through 340B program expansion.
- Home Care:Pen-based delivery dominates volume through patient self-administration outside clinical settings. Bluetooth-enabled dose capture devices integrate with continuous glucose monitors under Germany's DiGA fast-track reimbursement.
- Specialty Pharmacies:Consolidate prior authorization and patient assistance coordination previously fragmented across retail channels. United States distributors with cold-chain credentials across all 50 states capture this channel compression.
- Hospitals:Require formulary management and glycemic control protocols.
- Diabetes Clinics:Focus on insulin initiation and dose titration education.
- Endocrinology Centers:Manage complex cases with pump therapy and continuous monitoring.
Home care sits at the top of the volume ranking, with specialty pharmacies climbing the fastest as channel compression accelerates.
Delivery Mode:
Device-drug bundling intensity varies by delivery mechanism, with pumps requiring proprietary cartridge geometries that lock in formulation suppliers.
- Insulin Pens:Disposable and reusable devices dominate global volume through patient familiarity and dose precision. Needle thread and cartridge dimension variations across originator platforms create retraining friction for patients switching biosimilars.
- Pumps:Tubed and patch pump systems command premium per-unit value in intensive insulin management. Formulation optimization for pump pharmacokinetics requires U-300 and U-500 concentration development.
- Vials:Retain position in institutional settings and cost-sensitive markets.
- Pre-Filled Syringes:Serve acute care and emergency departments.
- Inhalers:Limited commercial presence due to pulmonary delivery challenges.
Insulin pens sit at the top of the volume ranking, with pumps climbing the fastest in United States intensive management practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copenhagen-based Novo Nordisk anchors fermentation capacity for recombinant insulin analogs. Paris clusters host Sanofi's biotechnology manufacturing. Indianapolis drives Eli Lilly's analog formulation expertise.
United States
Endocrinology practices in Indianapolis and Boston prioritize ultra-long-acting analogs for elderly polypharmacy patients. FDA interchangeability studies extend biosimilar timelines by 18-24 months. Specialty pharmacies consolidate insulin purchasing through 340B program expansion.
Germany
Home care infrastructure subsidies drive pen-based delivery volume in Bavaria and North Rhine-Westphalia. DiGA fast-track reimburses Bluetooth-enabled dose capture devices. Frankfurt procurement consortia weigh immunogenicity surveillance costs in tender scoring.
Japan
PMDA guidelines shape ultra-long-acting analog approval pathways for nocturnal hypoglycemia reduction. Tokyo and Osaka diabetes clinics emphasize pump-compatible U-300 formulations. METI subsidizes continuous glucose monitor integration with insulin delivery.
India
CDSCO-approved facilities with WHO prequalification capture African tender volumes from Bangalore and Hyderabad clusters. Biocon and domestic manufacturers export biosimilars to sub-Saharan procurement pools. DGFT trade facilitation accelerates cold-chain logistics partnerships.
France
Sanofi's biotechnology network in the Paris-Saclay cluster supplies European finished-dose demand. ANSM immunogenicity thresholds diverge from FDA standards, forcing duplicate analytical development. Lyon health technology assessment bodies evaluate biosimilar substitution policies.
Global Basal Insulin Market Competitive Landscape
Global majors compete with regional champions across recombinant DNA platforms and fermentation capacity. Three vertically integrated manufacturers control captive API supply, while mid-scale biosimilar specialists exploit regulatory pathway differences. Danish and French originators anchor premium-tier positioning through device-drug bundling. Indian and Chinese manufacturers capture tender volume through WHO prequalification. Competitive moves concentrate on M&A for purification technology and strategic partnerships for digital delivery ecosystems.
Within the originator tier, Novo Nordisk and Sanofi occupy positions defined by microbial expression platform control and European manufacturing concentration. Eli Lilly and Company exemplifies analog formulation expertise in the United States market. Among biosimilar specialists, Biocon represents Indian export acceleration into African and Latin American procurement pools, while Tonghua Dongbao Pharmaceutical and Gan & Lee Pharmaceuticals anchor Chinese domestic capacity expansion.
| Leading Market Players |
|---|
| Biocon |
| Tonghua Dongbao Pharmaceutical |
| Novo Nordisk |
| Merck |
| United Laboratories |
| Sanofi |
| Gan & Lee Pharmaceuticals |
| Wockhardt |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Vertically integrated originators with captive fermentation capacity anchor pricing discipline through in-house API production, insulating premium-tier formulations from biosimilar cost compression while forcing contract manufacturers to absorb zinc-crystallization yield losses in competitive tenders.
Pricing Analysis
Fermentation titer yields and chromatographic purification costs pass directly into finished-dose pricing, with albumin-binding fatty acid acylation complexity driving premium-mid-economy pricing differentiation across ultra-long-acting, long-acting, and biosimilar tiers. FDA interchangeability study burdens compress margins for biosimilar entrants seeking pharmacy-level substitution, while originators defend device-drug bundling premiums in United States intensive management practices. Pricing pressure stems from GLP-1 receptor agonist substitution delaying insulin initiation in early Type 2 diabetes. Health system procurement managers exhibit highest price sensitivity; endocrinology practices prescribing for elderly polypharmacy patients show lowest.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised insulin shipments remain underdeveloped across last-mile distribution networks, with ambient storage excursions in tropical climates forcing product destruction rather than refurbishment. Captive fermentation capacity concentrates in Denmark, France, and the United States, drawing from recombinant DNA platform inputs, zinc crystallization reagents, and single-use bioreactor components. Single-source vulnerability at biotechnology manufacturing clusters propagates disruption through global finished-dose supply. Distribution runs through cold-chain-validated specialty pharmacy networks consolidating volume under 340B program expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with patient phenotype stratification and nocturnal hypoglycemia risk reduction driving demand-shift toward ultra-long-acting analog specifications.
For Market Incumbents: Deploy device-drug bundling as the primary defensive lever, locking formulation suppliers into proprietary pump cartridge geometries while accelerating Bluetooth-enabled dose capture integration with continuous glucose monitors. Fortify captive fermentation capacity in Danish and French clusters against biosimilar cost parity threats. Deepen backward integration into microbial expression platform control to sustain API cost leadership. For New Entrants and Emerging Players: Enter via WHO prequalification pathways capturing sub-Saharan African and Southeast Asian tender volumes previously served by European originators, exploiting EMA-FDA regulatory divergence to compress development timelines. Target pump-compatible U-300 and U-500 formulation whitespace in United States intensive management practices. Pursue CDSCO-approved facility partnerships with established Indian biosimilar exporters as the fastest go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale biosimilar specialists with WHO prequalification and African tender relationships but limited device ecosystem integration. Long-term viability hinges on interchangeability designation capture and digital delivery platform partnerships rather than molecule commoditization alone. Monitor EMA-FDA immunogenicity threshold convergence as the critical signal for biosimilar development cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Interchangeability Designation | Pharmacy-level substitution rights unlock automatic formulary access in United States health systems. |
| Connected Pen Ecosystem Development | Bluetooth-enabled dose capture integration with continuous glucose monitors closes intensive management feedback loops. |
| WHO Prequalification Pathway | Low- and middle-income country tender eligibility expands addressable patient populations in sub-Saharan Africa. |
| Pump-Compatible Formulation Scale-Up | U-300 and U-500 concentration optimization commands premium positioning in United States intensive practices. |
| Microbial Expression Platform Licensing | CRISPR-edited Saccharomyces cerevisiae strains boost titer yields 40% above legacy fermentation platforms. |
Research Methodology
Bottom-up patient population modeling reconciled against top-down fermentation capacity tracking forms the analytical core, combining primary interviews with formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Input-output matrix framing maps recombinant DNA platform capacity, zinc crystallization throughput, and finished-dose formulation output across the projection horizon, with segmentation dimensions spanning product type, patient phenotype, delivery mode, and regional regulatory cluster. CAGRs derive from patient volume trajectories, pricing elasticity assumptions, and biosimilar penetration curves calibrated against historical interchangeability designation timelines. Forecast inputs incorporate GLP-1 substitution effects and cold-chain infrastructure expansion rates.
The model holds under stable regulatory equivalence standards and continued insulin pump adoption; deviation in EMA-FDA immunogenicity threshold divergence or accelerated GLP-1 cardiovascular outcome trial publication would shift volume and value trajectories. Practitioners should monitor biosimilar interchangeability designation grants and continuous glucose monitor reimbursement policy changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Xanthine Oxidase Inhibitors Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
North America Dipeptide Peptidase 4 (Dpp-4) Inhibitors Market
Pharmaceuticals
Azathioprine API Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Depression Drugs Market