
 Insomnia Market | 2026-2036
Insomnia Market Size, Share, and Industry Trends Forecast 2026-2036
Insomnia Market Intelligence
Geriatric care facilities is decoupling from psychiatric centers as the dominant end-use channel for insomnia interventions, with aging populations driving protocol shifts toward integrated sleep management. Pfizer Inc. leverages its established primary care infrastructure to sustain prescription drug distribution across diverse clinical settings. Merck & Co Inc. anchors its position through specialized R&D intensity in orexin receptor antagonist development. Sanofi S.A. competes in over-the-counter segments through channel control in European pharmacy networks.
Insomnia constitutes a clinical sleep disorder characterized by persistent difficulty initiating or maintaining sleep despite adequate opportunity, measured against polysomnographic thresholds of sleep latency exceeding thirty minutes or wake-after-sleep-onset surpassing twenty minutes. The condition impairs daytime functioning and elevates risk for cardiovascular, metabolic, and psychiatric comorbidities across industrial and commercial healthcare systems. Prescription drugs occupy the largest value pool within product type segmentation, though cognitive behavioral therapy demonstrates the fastest structural expansion as payer coverage broadens. Sleep devices concentrate margin capture in direct-to-consumer platforms, where subscription models reshape traditional distribution economics.
FDA oversees pharmacologic insomnia treatments through New Drug Application pathways and Risk Evaluation and Mitigation Strategies for controlled substances, while EMA applies MDR frameworks to emerging sleep devices and digital therapeutics entering European markets. Japan's PMDA maintains distinct pharmacovigilance requirements for hypnotic agents that influence regional product registration timelines. Stakeholders must monitor evolving reimbursement decisions for digital cognitive behavioral therapy platforms across multiple national health technology assessment bodies.
Market Dynamics
FDA REMS protocol revisions for hypnotic agents are compressing development timelines for orexin receptor antagonists while simultaneously expanding reimbursement pathways for digital cognitive behavioral therapy platforms across commercial payers.
Growth Catalysts
- Behavioral Sleep Medicine Coverage:CMS and commercial insurers in the United States are establishing distinct reimbursement codes for cognitive behavioral therapy for insomnia, redirecting patient flows from pharmacologic to non-pharmacologic interventions.
- Geriatric Protocol Shifts:Long-term care facilities are adopting integrated sleep management programs as primary intervention sites, decoupling from psychiatric centers as the dominant channel for insomnia treatment delivery.
- EMA MDR Frameworks:European Medical Device Regulation pathways for sleep devices are clarifying market entry requirements, enabling direct-to-consumer platforms to scale subscription-based distribution models across Germany, France, and the Netherlands.
Market Restraints
- Controlled Substance Scheduling:DEA Schedule IV classification for benzodiazepine receptor agonists imposes dispensing limits and prescriber registration requirements that constrain volume expansion in retail pharmacy channels.
- Clinical Trial Complexity:Polysomnographic endpoint validation for novel hypnotics requires specialized sleep center infrastructure concentrated in major metropolitan areas, limiting investigator site availability.
- Generic Erosion:Patent expirations for zolpidem formulations have commoditized immediate-release segments, compressing margin pools available for incremental innovation investment.
Strategic Opportunities
- Japan PMDA Pharmacovigilance Pathways:Distinct post-market surveillance requirements for hypnotic agents create first-mover advantages for companies establishing localized safety databases ahead of competitor entries.
- Digital Therapeutic Convergence:Integration of wearable sleep staging with algorithmic CBT delivery is opening prescription-to-consumer channel bridges previously separated by regulatory classification boundaries.
- Employer-Sponsored Programs:Self-insured corporations are contracting directly with behavioral sleep medicine platforms, bypassing traditional payer intermediaries and capturing productivity-related ROI metrics.
Industry Challenges
- Sleep Specialist Workforce Constraints:Board-certified behavioral sleep medicine practitioners remain concentrated in academic medical centers, creating access bottlenecks for CBT-I delivery at scale.
- Legacy EHR Integration:Digital therapeutic platforms face technical friction connecting with Epic and Cerner deployments, delaying provider adoption despite demonstrated clinical efficacy.
- Cross-Border Data Governance:GDPR compliance for sleep data collected via European consumer devices imposes architectural constraints on cloud infrastructure that increase operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insomnia Market |
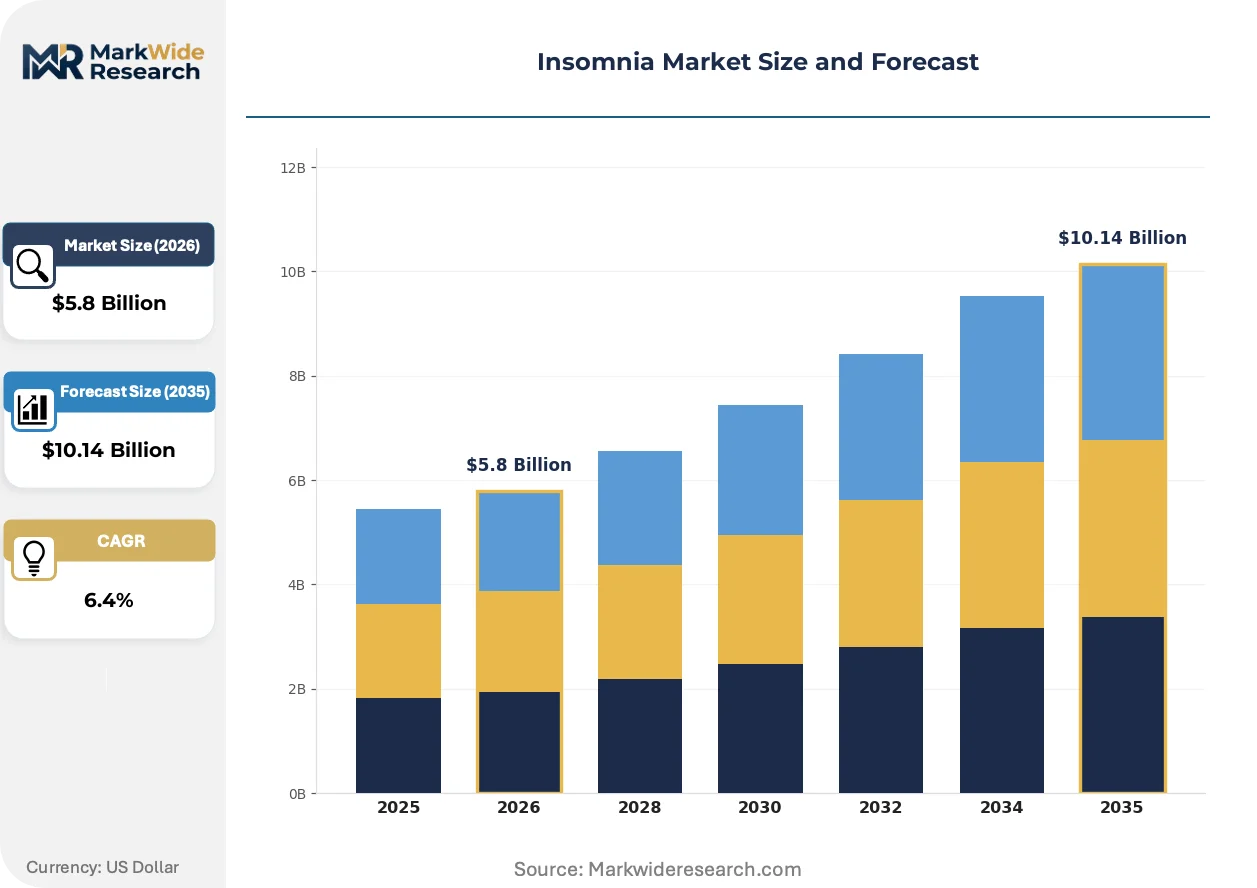
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Herbal Supplements, Cognitive Behavioral Therapy, Sleep Devices Therapy Area: Primary Insomnia, Secondary Insomnia, Sleep-Onset Insomnia, Sleep Maintenance Insomnia, Transient Insomnia End User: Sleep Clinics, Psychiatric Centers, Neurology Clinics, Wellness Centers, Geriatric Care Facilities Distribution Channel: Pharmacies, Online Retailers, Hospitals, Specialty Sleep Centers, Direct-to-Consumer Platforms |
| Companies Covered | Pfizer Inc., Merck & Co Inc., Sanofi S.A., Takeda Pharmaceutical Company Limited, GlaxoSmithKline plc., Eisai Co. Ltd., Jazz Pharmaceuticals plc, Viatris Inc., ResMed Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insomnia Market Strategic Shifts & Innovations
Product architecture and distribution economics are undergoing parallel transformation as prescription-digital hybrid models displace monolithic therapeutic categories and channel control shifts toward platform operators.
Closed-loop neurostimulation systems for insomnia are modularizing hardware, algorithm, and service components into separately upgradable elements. Sleep disorder centers in the United States are piloting these systems as alternatives to continuous positive airway pressure for comorbid insomnia-sleep apnea presentations. This modularization is compressing capital commitment requirements for provider adoption and enabling software-based feature expansion without device replacement cycles.
EMA's Medical Device Regulation implementation for software-as-medical-device classifications is restructuring European market entry economics for sleep applications. Manufacturers must now maintain quality management systems certified by notified bodies, raising fixed compliance costs that favor scaled platform operators over point-solution developers. Digital CBT-I providers targeting German and French markets are consolidating to spread these fixed costs across larger installed bases.
Self-directed purchasing through employer wellness portals is displacing traditional physician-referral pathways for behavioral sleep interventions. Human resources departments at technology and financial services firms are contracting directly with sleep coaching platforms, removing primary care gatekeepers from the acquisition chain. This pattern concentrates in the United States where self-insured employers command sufficient leverage to design benefit carve-outs outside standard medical plan structures.
Insomnia Market Segmentation
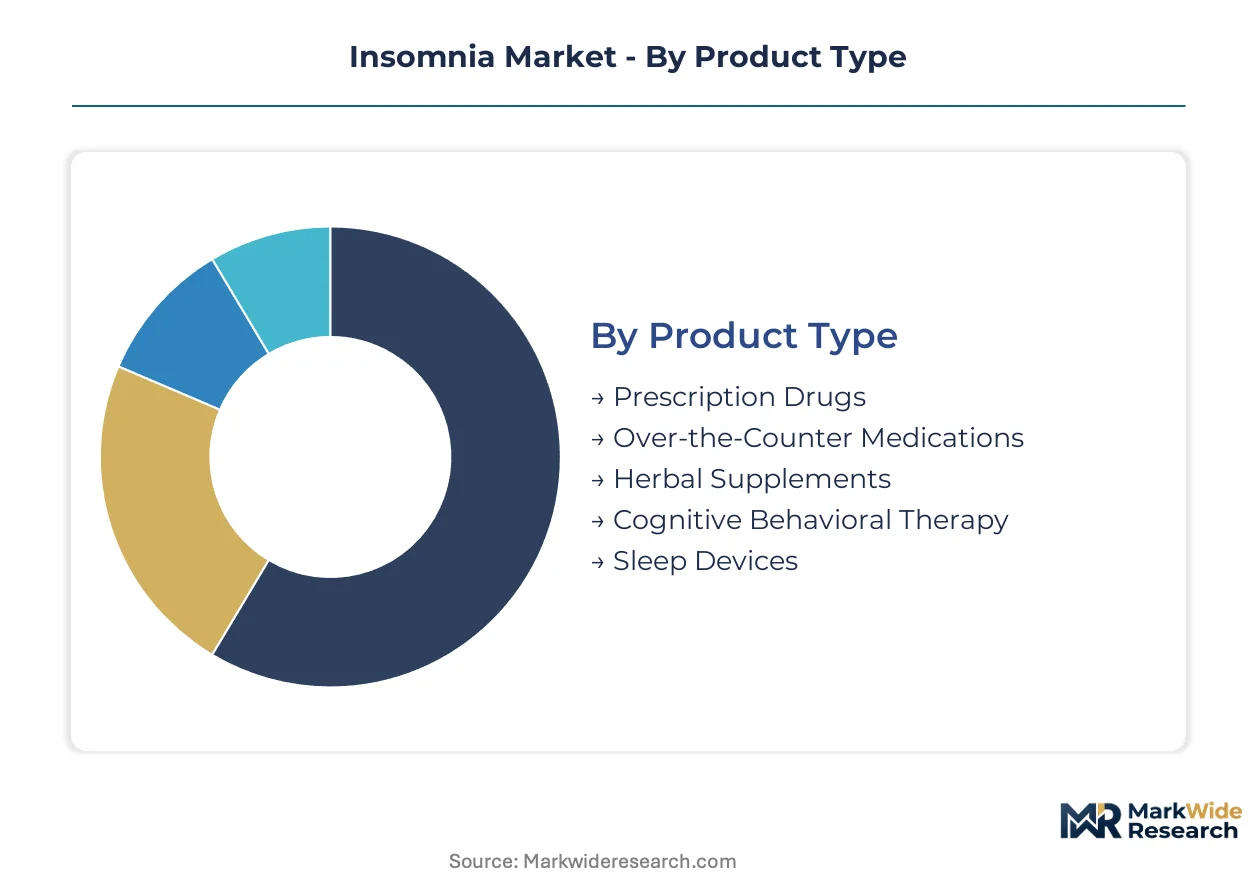
Insomnia market segmentation reflects divergent reimbursement pathways and channel economics. Product type determines margin structure, while end-user selection shapes protocol standardization and clinical trial design.
Product Type:
Cost tier separates institutional buyers from self-directed consumers across pharmacologic and non-pharmacologic options.
- Prescription Drugs:Orexin receptor antagonists and benzodiazepine receptor agonists dominate hospital formularies. Demand concentrates in the United States and Germany where commercial payers maintain distinct prior authorization tiers for hypnotic agents.
- Cognitive Behavioral Therapy:Structured protocols delivered via telehealth platforms or certified practitioners. United States employers are contracting directly with CBT-I providers, bypassing traditional payer intermediaries and capturing productivity-related ROI metrics.
- Over-the-Counter Medications:Diphenhydramine and doxylamine formulations command shelf space in European pharmacy networks.
- Herbal Supplements:Melatonin and valerian root products face variable regulatory classification across national health authorities.
- Sleep Devices:Wearable sleep trackers and closed-loop neurostimulation systems deploy subscription models through direct-to-consumer platforms.
Volume sits with prescription drugs; growth tilts toward cognitive behavioral therapy.
Therapy Area:
Application context determines whether interventions target isolated sleep disturbance or comorbid conditions.
- Primary Insomnia:Sleep disturbance without underlying medical or psychiatric cause. CBT-I protocols demonstrate durable efficacy in this population, driving payer investment in behavioral sleep medicine infrastructure.
- Sleep Maintenance Insomnia:Characterized by fragmented sleep architecture with multiple nocturnal awakenings. Japan's PMDA maintains distinct pharmacovigilance requirements for hypnotic agents targeting this presentation, influencing regional product registration timelines.
- Secondary Insomnia:Sleep disturbance attributable to medical conditions, substance use, or psychiatric disorders.
- Sleep-Onset Insomnia:Delayed sleep latency exceeding thirty minutes on polysomnography.
- Transient Insomnia:Acute sleep disturbance lasting less than one month, often stress-triggered.
Clinical trial complexity clusters around primary insomnia; real-world volume distributes across secondary presentations.
End User:
Customer type dictates whether interventions deploy through medical infrastructure or wellness channels.
- Geriatric Care Facilities:Long-term care operators are adopting integrated sleep management programs as primary intervention sites. Aging populations in Japan and Germany are driving protocol shifts toward non-pharmacologic first-line approaches.
- Sleep Clinics:Accredited centers with polysomnography capabilities serve as gatekeepers for device prescriptions and complex pharmacologic regimens.
- Psychiatric Centers:Traditional channel for insomnia comorbid with mood and anxiety disorders.
- Neurology Clinics:Specialized sites for insomnia associated with neurodegenerative conditions.
- Wellness Centers:Consumer-facing platforms for behavioral interventions outside medical reimbursement structures.
Psychiatric centers retain legacy volume; geriatric care facilities are climbing the fastest.
Distribution Channel:
Supply concentration separates regulated medical channels from platform-mediated consumer access.
- Direct-to-Consumer Platforms:Subscription models for digital CBT-I and wearable sleep devices reshape traditional distribution economics. EMA MDR frameworks for software-as-medical-device classifications favor scaled platform operators over point-solution developers.
- Pharmacies:DEA Schedule IV classification for controlled hypnotics imposes dispensing limits and prescriber registration requirements that constrain volume expansion in retail channels.
- Online Retailers:E-commerce penetration for OTC sleep aids and supplements varies by national regulatory classification.
- Hospitals:Inpatient sleep medicine services concentrate in academic medical centers with specialized infrastructure.
- Specialty Sleep Centers:Polysomnographic endpoint validation for novel hypnotics requires sleep center infrastructure concentrated in major metropolitan areas.
Pharmacies anchor current volume; direct-to-consumer platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal Opportunity Zones in Baltimore and Pittsburgh are concentrating digital therapeutic development for behavioral sleep medicine, drawing venture investment away from traditional pharmaceutical corridors toward Medicaid-adjacent service delivery models.
United States
CMS reimbursement codes for cognitive behavioral therapy for insomnia redirect patient flows from pharmacologic to non-pharmacologic interventions. FDA REMS protocol revisions compress development timelines for orexin receptor antagonists. Pittsburgh's sleep technology corridor hosts closed-loop neurostimulation pilot programs at UPMC as alternatives to CPAP for comorbid presentations.
Germany
EMA Medical Device Regulation frameworks clarify market entry requirements for sleep devices, enabling subscription-based distribution models. Statutory health insurance funds in Bavaria and Baden-Württemberg are piloting direct reimbursement for digital CBT-I platforms. Berlin's health technology cluster sees consolidation among software-as-medical-device developers spreading fixed compliance costs across larger installed bases.
Japan
Aging populations in Kansai and Chubu regions drive protocol shifts toward non-pharmacologic first-line approaches in geriatric care facilities. PMDA maintains distinct pharmacovigilance requirements for hypnotic agents targeting sleep maintenance insomnia, influencing regional product registration timelines. Osaka's pharmaceutical corridor anchors post-market surveillance database development for first-mover safety infrastructure.
United Kingdom
NICE technology appraisals for digital therapeutics reshape commissioning decisions across integrated care systems. MHRA operates transitional arrangements for medical device software following EU MDR divergence. London's behavioral sleep medicine training programs at Guy's and St Thomas' NHS Foundation Trust address workforce constraints limiting CBT-I delivery at scale.
France
ANSM pharmacovigilance requirements for hypnotic agents intersect with CNIL data governance for sleep data collected via consumer devices. HAS evaluation pathways for digital therapeutics determine reimbursement eligibility in statutory health insurance. Paris-Saclay's neurotechnology cluster advances wearable sleep staging integration with algorithmic intervention delivery.
Insomnia Market Key Industry Players
Top-tier vendors anchor prescription drug distribution through established primary care infrastructure, while mid-tier specialists concentrate on orexin receptor antagonist R&D and over-the-counter channel control. The competitive terrain stratifies across three archetypes: pharmaceutical incumbents with primary care reach, specialized R&D-intensive developers of novel mechanisms, and platform operators scaling direct-to-consumer subscription models. Dominant competitive moves include strategic partnerships bridging prescription-to-consumer regulatory boundaries and portfolio diversification into digital therapeutic convergence.
Within the pharmaceutical incumbent tier, Pfizer Inc. and Merck & Co Inc. occupy positions reflecting contrasting strategic emphases—Pfizer leveraging broad primary care infrastructure, Merck anchoring specialized development intensity. Sanofi S.A. exemplifies the over-the-counter channel control archetype through European pharmacy network presence. These three represent the structural poles around which competitive positioning organizes: scale-driven prescription distribution, mechanism-focused innovation, and consumer-access platform economics.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co Inc. |
| Sanofi S.A. |
| Takeda Pharmaceutical Company Limited |
| GlaxoSmithKline plc. |
| Eisai Co. Ltd. |
| Jazz Pharmaceuticals plc |
| Viatris Inc. |
| ResMed Inc. |
| Others |
Cost & Logistics Intelligence
Closed-loop neurostimulation hardware modularization compresses capital commitment requirements for provider adoption while simultaneously fragmenting component sourcing across multiple specialized tiers. This production-method transition enables software-based feature expansion without device replacement cycles, concentrating margin capture in subscription platforms rather than discrete hardware transactions.
Pricing Analysis
Short lead-time premiums apply to closed-loop neurostimulation systems delivered within contracted implementation windows, while spot inventory of legacy sleep devices trades at discounts in secondary markets. Three-tier pricing structure across premium algorithm-integrated systems, standard wearable trackers, and economy OTC sleep aids reflects certification grade differentiation. Cost compression in prescription hypnotic segments is intensifying because generic zolpidem formulations have commoditized immediate-release categories. Self-insured employers demonstrate lowest price sensitivity through direct platform contracting, whereas retail pharmacy channels face highest sensitivity due to DEA Schedule IV dispensing constraints.
Supply Chain Analysis
Dual-sourcing requirements for orexin receptor antagonist active pharmaceutical ingredients mandate multi-supplier qualification across FDA-registered and EMA-certified manufacturing sites. Supply concentration centers on the United States, Germany, and Japan for finished pharmaceutical formulations, with India and China anchoring intermediate chemical synthesis. Raw material dependencies include specialized polysomnography sensors, algorithm training datasets, and melatonin precursor compounds. Single-source vulnerability runs through concentrated wearable sensor foundry capacity. Distribution runs through direct-to-consumer platforms for sleep devices and hospital formularies for prescription hypnotics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insomnia market operates as a supply-constrained environment where board-certified behavioral sleep medicine practitioner scarcity props pricing for CBT-I delivery. Capacity bottlenecks in specialized sleep center infrastructure limit polysomnographic endpoint validation throughput for novel hypnotic development.
For Market Incumbents: Extend primary care infrastructure into employer-sponsored wellness portals before digital therapeutic platforms capture direct contracting relationships. Consolidate orexin receptor antagonist development pipelines through specialized R&D intensity rather than dispersed indication expansion. Defensive moves require backward integration into algorithm training data assets and certification investment in FDA software-as-medical-device pathways.
For New Entrants and Emerging Players: Geriatric care facilities in Japan and Germany represent underserved buyer archetypes seeking non-pharmacologic first-line protocols without psychiatric center referral dependencies. White-space targets include closed-loop neurostimulation for comorbid insomnia-sleep apnea presentations and wearable-integrated CBT-I for sleep maintenance insomnia. Go-to-market positioning through statutory health insurance pilot programs in Bavaria and Baden-Württemberg offers fastest reimbursement pathway traction.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform operator acquisitions by pharmaceutical incumbents seeking prescription-to-consumer channel bridges. Long-term viability favors scaled digital therapeutic providers with installed bases sufficient to spread EMA MDR fixed compliance costs. Acquisition target archetypes include CBT-I platforms with Epic and Cerner integration capabilities. The signal to watch is CMS reimbursement code expansion for behavioral sleep medicine beyond current geographic pilot constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | EMA MDR compliance enables subscription model scaling across German and French markets. |
| Employer Wellness Portal Partnership | Direct contracting with self-insured corporations bypasses traditional payer intermediaries. |
| Closed-Loop Neurostimulation Modularization | Hardware-software separation compresses provider capital commitment requirements. |
| Post-Market Surveillance Database Development | PMDA pharmacovigilance infrastructure creates first-mover advantages in Japan. |
| EHR Integration Certification Investment | Epic and Cerner connectivity reduces technical friction delaying provider adoption. |
Research Approach
Independent corroboration across FDA REMS documentation, EMA MDR submission filings, and PMDA pharmacovigilance reports underwrites the qualitative findings on regulatory pathway evolution. Primary interviews with drug development executives at orexin receptor antagonist specialists, formulary directors at integrated delivery networks, and behavioral sleep medicine practitioners at academic medical centers combined with secondary validation from ClinicalTrials.gov entries, CMS reimbursement code determinations, and hospital procurement database analysis. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored segmentation estimates.
Rate-of-change decomposition across the analysis window isolates volume shifts from pricing dynamics in prescription drugs versus cognitive behavioral therapy versus sleep devices. Segmentation dimensions modeled include product type, therapy area presentation, end-user facility category, and distribution channel regulatory classification. CAGRs were derived through logistic diffusion curves for digital therapeutic adoption and epidemiological prevalence projections for pharmacologic demand. Forecast inputs incorporate polysomnography capacity constraints and board-certified practitioner supply growth rates.
Revisions become necessary when FDA REMS protocol modifications, EMA MDR implementation delays, or PMDA safety signal escalations materialize beyond current regulatory baselines. Deviation in CMS reimbursement code expansion timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Americas Insomnia Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Sleep Disorders Treatment Market