
 Sleep Disorder Market | 2026-2036
Sleep Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Disorder Market Analysis
Direct-to-patient channels is tilting toward connected care platforms that bypass traditional sleep clinic gatekeepers. ResMed Inc. leverages cloud-based adherence monitoring to sustain recurring revenue streams from its device-installed base. Philips Respironics anchors hospital procurement networks across North America and Western Europe through long-term service contracts. Fisher & Paykel Healthcare competes on mask comfort technologies that reduce patient dropout rates during CPAP titration.
Sleep disorders encompass clinically diagnosed conditions including obstructive sleep apnea, insomnia, narcolepsy, and restless leg syndrome that disrupt normal sleep architecture and daytime functioning; polysomnography remains the diagnostic gold standard, though home sleep apnea testing devices now capture respiratory effort, airflow, and oxygen saturation data through portable fingertip and nasal cannula sensors. CPAP machines occupy the largest product value pool given mandatory replacement cycles and consumable mask revenues, while sleep monitors represent the fastest-growing product type as wrist-worn photoplethysmography sensors achieve clinical-grade accuracy. Behavioral therapy segments command premium pricing in employer wellness contracts where absenteeism reduction justifies per-employee expenditures.
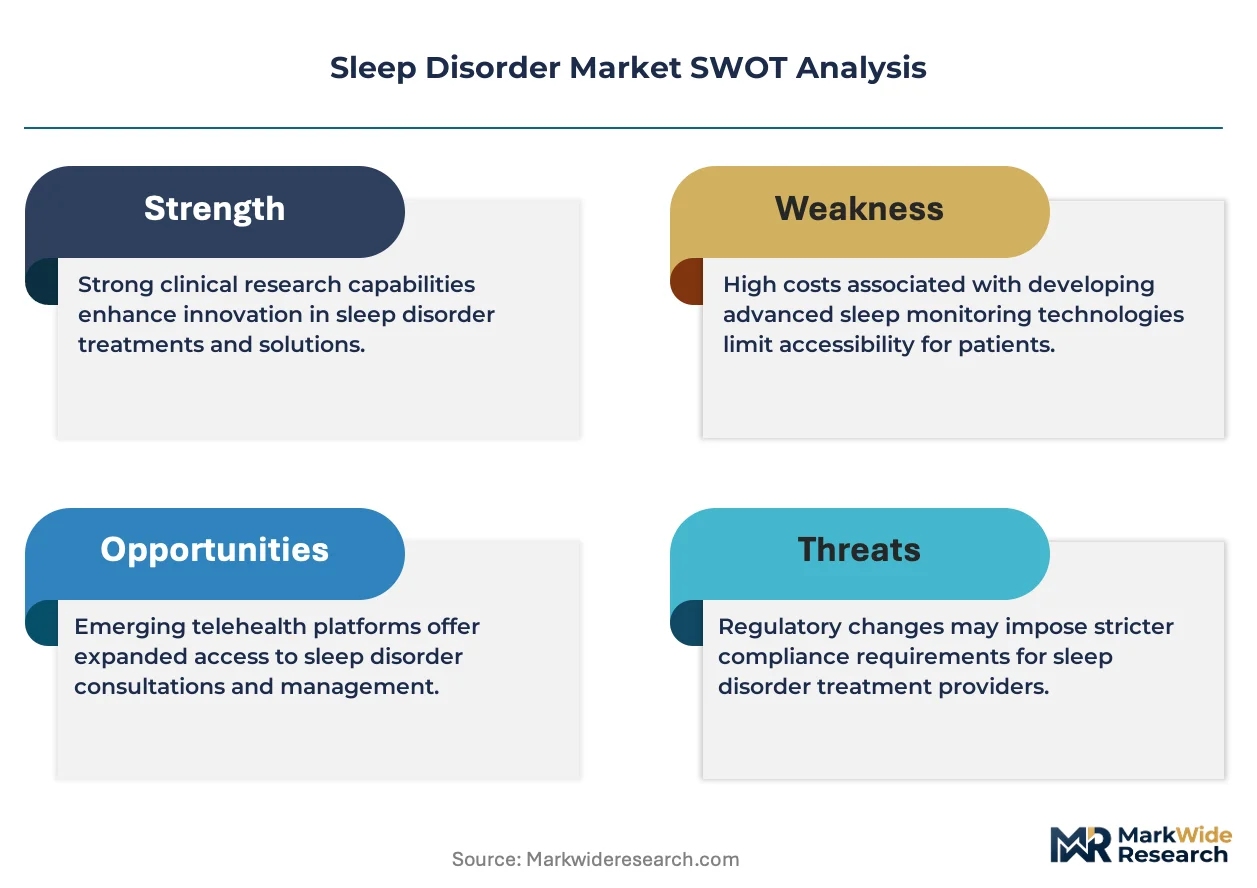
FDA regulates sleep disorder devices as Class II medical products requiring 510(k) premarket notification, while the EU MDR imposes strengthened clinical evidence requirements for software-as-a-medical-device sleep applications. HIPAA compliance constraints shape data architecture decisions for cloud-connected sleep therapy platforms operating across United States jurisdictions. Stakeholders must monitor evolving reimbursement coding for remote therapeutic monitoring as payors recalibrate coverage policies for digital sleep interventions.
Market Dynamics
Remote patient monitoring infrastructure is compressing the diagnostic pathway from sleep clinic referral to therapy initiation, collapsing traditional gatekeeper economics and redistributing value capture toward platform operators with cloud-connected device fleets.
Growth Catalysts
- Remote Therapeutic Monitoring (RTM) reimbursement codes:CMS coverage expansion in the United States validates home-based sleep apnea management and accelerates provider adoption of connected care workflows.
- Photoplethysmography sensor miniaturization:Wrist-worn optical sensors now achieve clinical-grade oxygen saturation correlation, enabling consumer electronics manufacturers to enter diagnostic-grade sleep monitoring.
- Aging demographics in Japan and Germany:Population cohorts over 65 exhibit sleep apnea prevalence rates exceeding 20 percent, concentrating device demand in reimbursement-protected markets with established CPAP infrastructure.
Market Restraints
- Semiconductor supply concentration in Taiwan:Microcontroller and sensor fabrication bottlenecks constrain production scaling for pulse oximetry modules and CPAP blower motors.
- EU MDR clinical evidence requirements:Software-as-a-medical-device sleep applications face extended conformity assessment timelines and elevated notified body fees compared to legacy device categories.
- Behavioral therapy substitution:Cognitive behavioral therapy for insomnia (CBT-I) delivered through employer wellness contracts displaces pharmacological sleep aid prescriptions and reduces addressable market for hypnotic medications.
Strategic Opportunities
- Underpenetrated employer wellness channels in India:Corporate health programs lack sleep disorder screening protocols, creating first-mover advantage for diagnostic platform vendors targeting IT services and manufacturing sectors.
- FDA breakthrough device designation pathway:Expedited review for AI-enabled polysomnography interpretation compresses time-to-revenue for algorithmic diagnostic tools.
- Convergence of CPAP adherence data with electronic health records:Bidirectional data integration with Epic and Cerner systems enables population health management contracts with accountable care organizations.
Industry Challenges
- Polysomnography technologist certification bottlenecks:American Academy of Sleep Medicine accreditation requirements limit diagnostic lab throughput and create regional access disparities.
- Legacy device cybersecurity retrofit costs:FDA post-market guidance on networked device security imposes firmware update obligations on installed bases of first-generation cloud-connected CPAP machines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Disorder Market |
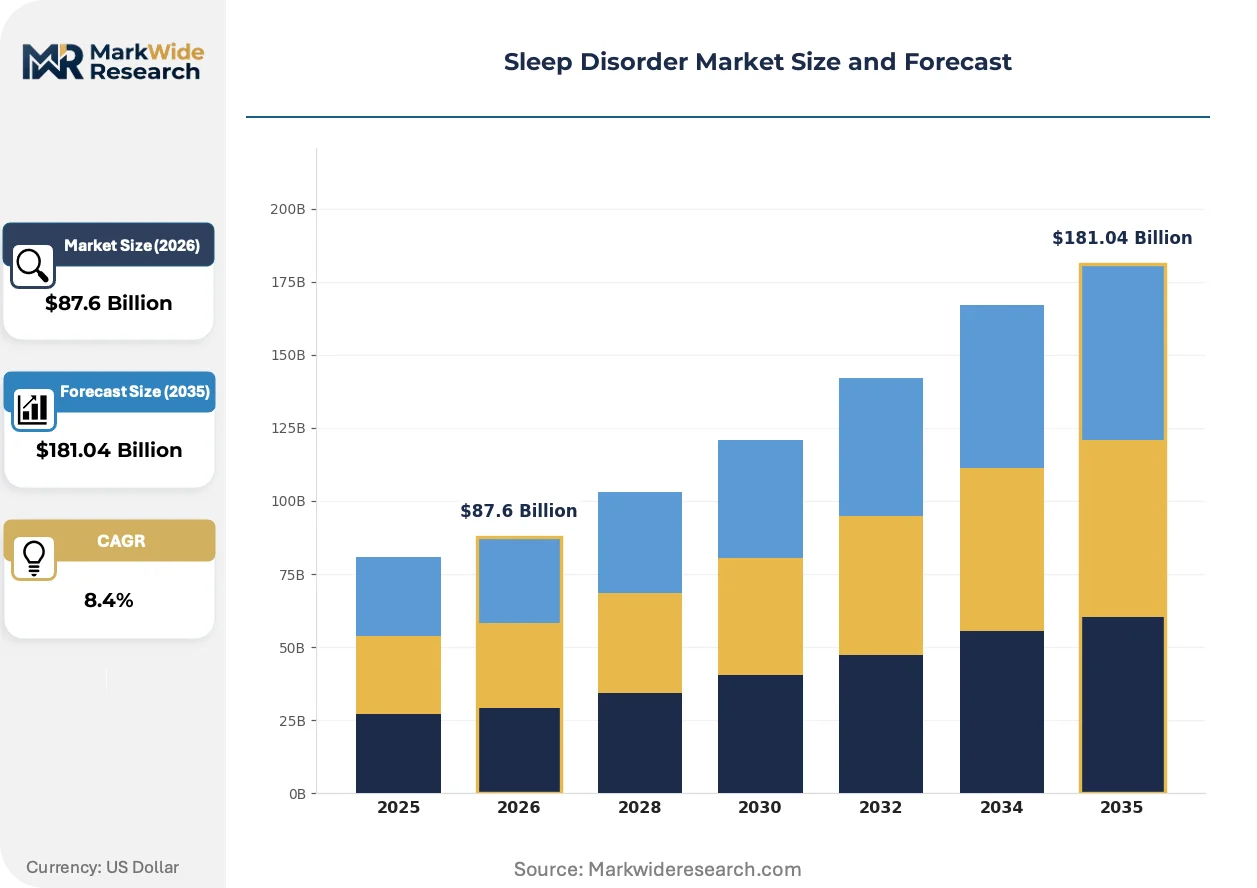
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $181.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sleep Apnea Devices, CPAP Machines, Sleep Monitors, Sleep Medications Treatment Type: Behavioral Therapy, Pharmacological Therapy, Cognitive Behavioral Therapy, Lifestyle Changes End User: Hospitals, Homecare Settings, Sleep Clinics, Rehabilitation Centers Disorder Type: Insomnia, Sleep Apnea, Narcolepsy, Restless Leg Syndrome |
| Companies Covered | BMC Medical Co., Ltd, Compumedics Limited, ResMed Inc., Itamar Medical Ltd., Natus Medical Inc., Philips Respironics, Drive DeVilbiss Healthcare, Nihon Kohden Corporation, Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Disorder Market Emerging Trajectories
Artificial intelligence inference at the edge is restructuring how sleep architecture is classified, shifting analytical workloads from centralized sleep labs to distributed sensor nodes and enabling real-time therapeutic adjustments.
Photoplethysmography signal processing is hybridizing with accelerometer-derived sleep staging algorithms, creating multi-modal classification systems that match polysomnography agreement rates above 85 percent for apnea-hypopnea index estimation. Sleep medicine practices in the United States and Australia are adopting these hybrid systems for home diagnostic pathways, reducing in-lab study backlogs and compressing time-to-diagnosis from weeks to days. This convergence is enabling direct-to-consumer channels that bypass traditional physician referral networks and capture patient acquisition costs previously absorbed by sleep clinic marketing.
EU MDR software classification guidance is redefining clinical evidence requirements for algorithm-based sleep diagnostics, mandating prospective validation studies for machine learning models that adjust therapy parameters. Notified bodies in Germany and the Netherlands are applying heightened scrutiny to training dataset representativeness, particularly for pediatric and geriatric subpopulations. Device manufacturers are responding by establishing European clinical trial infrastructure and pre-submission engagement with BSI and DEKRA to de-risk conformity assessment timelines.
Subscription-based adherence monitoring is displacing transactional device sales in employer-contracted sleep wellness programs, unbundling hardware procurement from ongoing coaching and data analytics services. Large self-insured employers in the United States are consolidating vendor relationships with platform operators that guarantee minimum therapy adherence rates, transferring outcome risk from payors to technology providers. This model concentrates contract value with vendors possessing integrated device-cloud-service architectures and proven actuarial validation of absenteeism reduction claims.
Sleep Disorder Market Segmentation
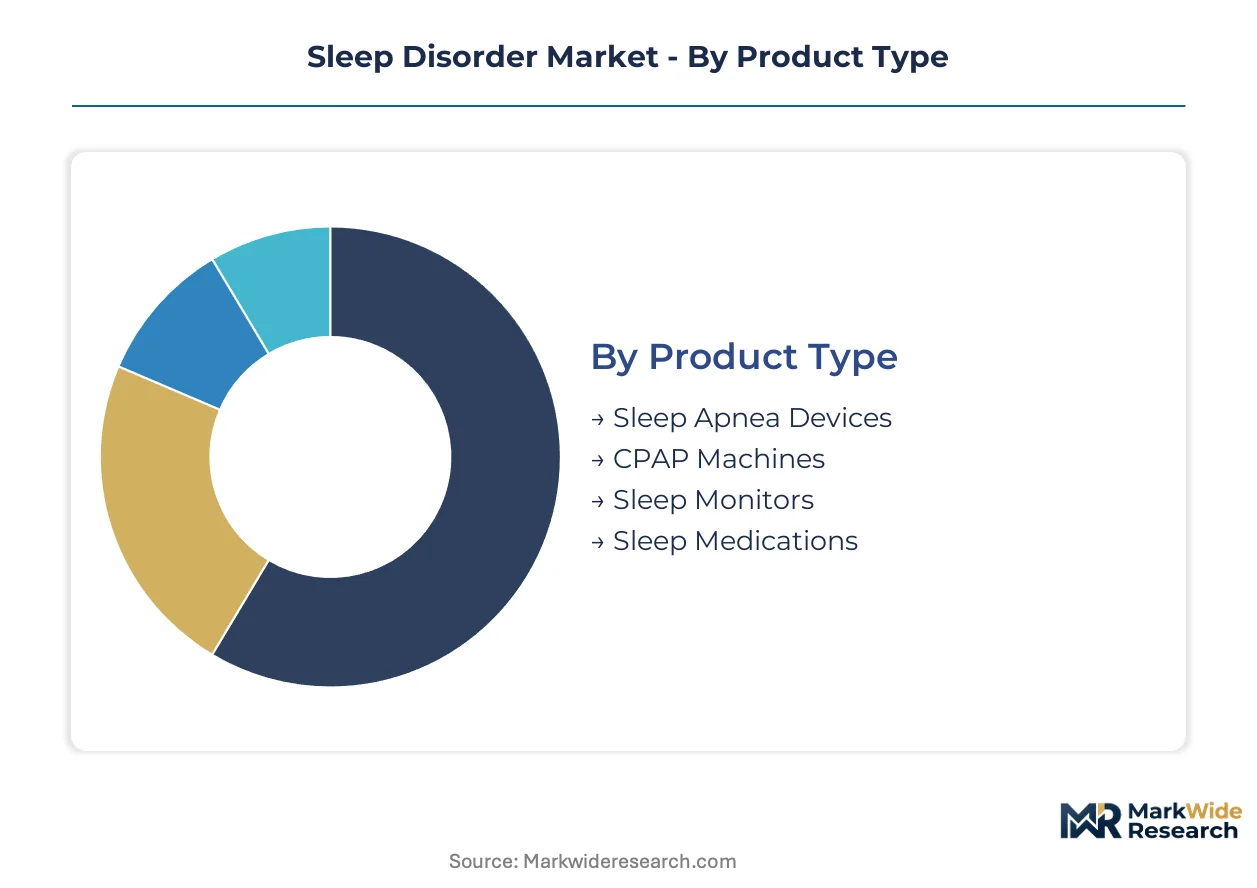
Sleep disorder market segmentation reveals distinct value pools shaped by reimbursement pathways, patient acuity, and technology readiness. Each dimension carries specific regulatory and commercial imperatives that determine competitive positioning and margin capture.
Product Type:
Use-case spectrum spans acute intervention through longitudinal monitoring, with reimbursement codes and replacement cycles defining revenue durability across each tier.
- Sleep Apnea Devices:Therapeutic hardware including mandibular advancement devices and positional therapy systems. Demand concentrates in Medicare-reimbursed homecare channels where prior authorization requirements favor established suppliers with dedicated reimbursement teams.
- CPAP Machines:Positive airway pressure systems with integrated humidification and cloud connectivity. United States volume leadership reflects mandatory five-year replacement cycles and consumable mask revenues that sustain recurring income streams.
- Sleep Monitors:Wearable photoplethysmography sensors achieving clinical-grade accuracy. Wrist-worn form factors from consumer electronics manufacturers are penetrating diagnostic-grade applications through FDA 510(k) clearances.
- Sleep Medications:Prescription hypnotics and wakefulness-promoting agents. Employer wellness contract displacement by CBT-I platforms is compressing addressable market for pharmacological interventions.
The dominant share belongs to CPAP Machines, while Sleep Monitors are closing the gap fastest.
Treatment Type:
Cost tier stratification separates high-touch clinical interventions from scalable digital delivery, with pricing power correlating to outcome measurability and payor contract structures.
- Behavioral Therapy:Sleep hygiene education and stimulus control protocols delivered through employer wellness programs. Premium pricing in self-insured employer contracts where absenteeism reduction justifies per-employee expenditures.
- Pharmacological Therapy:Benzodiazepine receptor agonists and orexin antagonists prescribed through sleep medicine specialists. Reimbursement compression from generic substitution is eroding branded medication margins.
- Cognitive Behavioral Therapy:Structured CBT-I protocols delivered via telehealth and digital therapeutic platforms. Scalable delivery models are capturing share from in-person sleep psychology practices.
- Lifestyle Changes:Circadian rhythm modification and weight management interventions. Integration with chronic disease management programs is expanding addressable population through primary care referral pathways.
Behavioral Therapy commands the highest margin per treated patient, though Cognitive Behavioral Therapy is expanding most quickly through digital health reimbursement codes.
End User:
Customer type determines procurement authority, with hospital networks favoring capital equipment leases and homecare channels prioritizing disposable replenishment economics.
- Hospitals:Inpatient sleep disorder diagnosis and acute intervention capabilities. Philips Respironics anchors procurement networks through long-term service contracts covering equipment maintenance and staff training.
- Homecare Settings:Remote monitoring and therapy adherence management. CMS Remote Therapeutic Monitoring reimbursement expansion is validating home-based sleep apnea management workflows.
- Sleep Clinics:Diagnostic testing and CPAP titration services. Polysomnography technologist certification bottlenecks limit throughput and create regional access disparities.
- Rehabilitation Centers:Post-acute sleep disorder management for stroke and traumatic brain injury patients. Bundled payment models concentrate contract value with platforms demonstrating readmission reduction.
Homecare Settings are gaining share fastest as remote monitoring infrastructure compresses diagnostic pathways, while Hospitals retain the largest installed base.
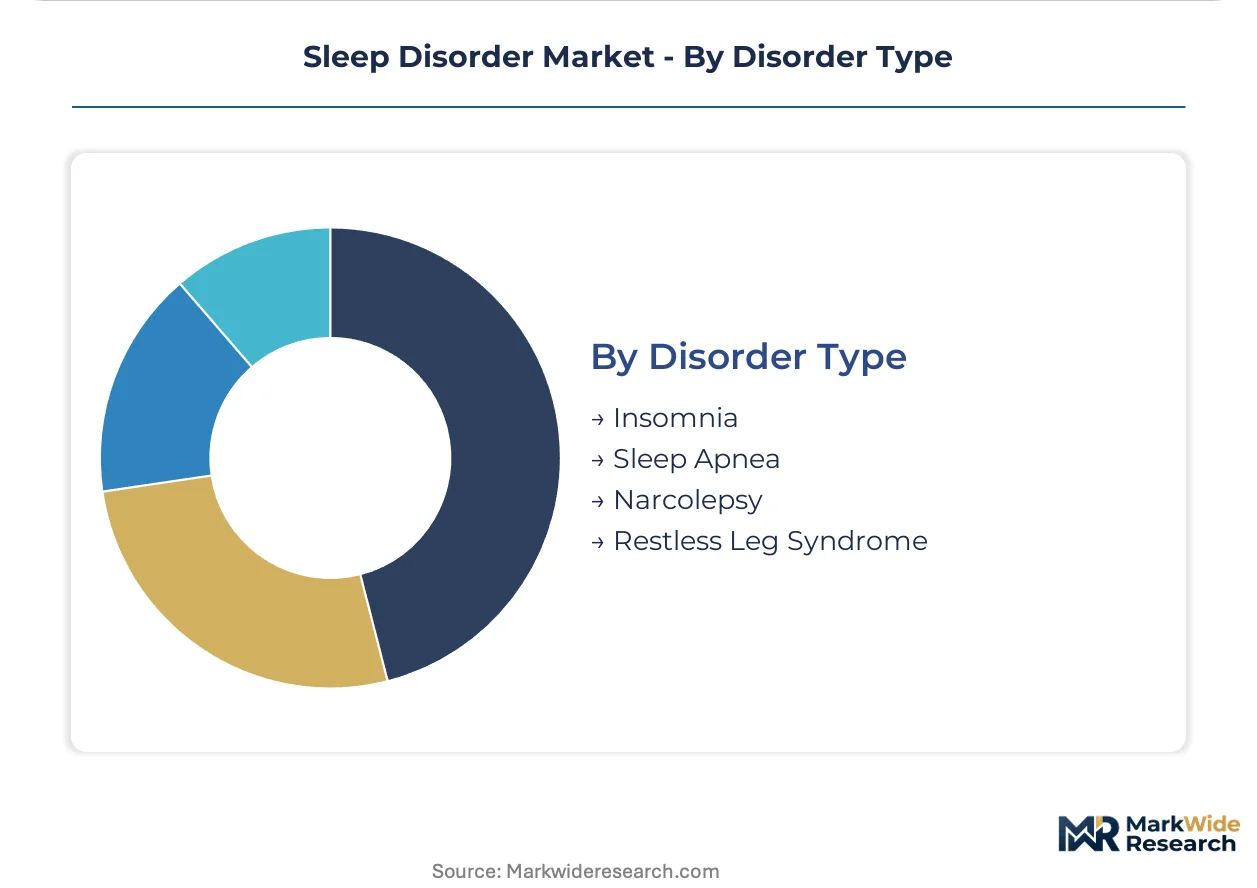
Disorder Type:
Prevalence and diagnostic clarity determine market maturity, with well-coded conditions attracting technology investment and ambiguous presentations facing reimbursement uncertainty.
- Insomnia:Difficulty initiating or maintaining sleep with daytime impairment. Digital CBT-I platforms are displacing pharmacological prescriptions through employer wellness channels.
- Sleep Apnea:Recurrent upper airway collapse during sleep with oxygen desaturation. Home sleep apnea testing devices now capture respiratory effort, airflow, and oxygen saturation data through portable sensors.
- Narcolepsy:Excessive daytime sleepiness with cataplexy or hypocretin deficiency. Specialty pharmacy distribution and prior authorization requirements limit addressable market expansion.
- Restless Leg Syndrome:Urge to move legs with uncomfortable sensations during rest. Dopaminergic agent prescriptions face generic competition with limited pipeline innovation.
Sleep Apnea holds the dominant share given established reimbursement infrastructure, while Insomnia management is climbing the fastest through digital therapeutic adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where reimbursement density sustains premium device economics, while cost-sensitive procurement in India and Brazil compresses margins for identical hardware specifications. This asymmetry shapes regional investment priorities and partnership structures.
United States
Medicare Remote Therapeutic Monitoring expansion and employer wellness contract consolidation drive demand concentration. FDA 510(k) pathways for wearable diagnostics compress clearance timelines. Minneapolis and San Diego host device manufacturing clusters where cloud-connected CPAP platforms integrate with Epic electronic health records.
Germany
Aging demographics exceeding 20 percent sleep apnea prevalence in cohorts over 65 sustain volume leadership. EU MDR notified bodies BSI and DEKRA impose strengthened clinical evidence requirements for software-as-medical-device sleep applications. Munich and Hamburg concentrate diagnostic platform development addressing pediatric and geriatric validation datasets.
Japan
Super-aged population structure and established CPAP infrastructure create replacement cycle demand. METI standards for home medical devices align with PMDA quality management requirements. Osaka and Tokyo metropolitan areas concentrate sleep clinic networks adopting photoplethysmography-based home testing.
India
Corporate health program underpenetration in IT services and manufacturing sectors creates first-mover screening opportunities. CDSCO medical device rules classify sleep monitors as Class A/B products with streamlined import registration. Bangalore and Hyderabad clusters attract diagnostic platform vendors targeting employer wellness channels.
Australia
Public hospital sleep lab backlogs accelerate home diagnostic pathway adoption. TGA conformity assessment for software-based sleep staging algorithms requires local clinical validation studies. Melbourne and Sydney concentrate sleep medicine practices deploying hybrid photoplethysmography-accelerometer systems.
Sleep Disorder Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, blowers, and mask interfaces. The vendor base organizes around three tiers: multinational device-cloud-service architectures, regional reimbursement specialists, and component OEMs. Consolidation pressures concentrate contract value with operators possessing integrated adherence monitoring and proven actuarial validation. Dominant competitive moves include strategic partnerships with electronic health record vendors and backward integration into sensor fabrication.
Among Asia-Pacific-based manufacturers, BMC Medical Co., Ltd. and Nihon Kohden Corporation occupy positions within the component-to-system value chain, while ResMed Inc. anchors the integrated platform tier with cloud-connected device fleets. These three exemplify divergent strategic postures: component supply depth, regional reimbursement specialization, and full-stack service unbundling respectively.
| Leading Market Players |
|---|
| BMC Medical Co., Ltd |
| Compumedics Limited |
| ResMed Inc. |
| Itamar Medical Ltd. |
| Natus Medical Inc. |
| Philips Respironics |
| Drive DeVilbiss Healthcare |
| Nihon Kohden Corporation |
| Fisher & Paykel Healthcare |
| Others |
Supply Flow & Price Mechanics
Taipei semiconductor fabrication clusters constrain pulse oximetry module availability, translating microcontroller scarcity into CPAP blower motor pricing volatility that compresses margins for device assemblers lacking captive sensor supply.
Pricing Analysis
The customization-premium spread between cloud-connected CPAP platforms and standard home sleep testing devices spans three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) certification tier and therapy adherence data bundling as primary differentiation drivers. Cost compression in economy-tier monitors is intensifying because consumer electronics manufacturers achieve clinical-grade photoplethysmography accuracy at scale. Homecare procurement committees exhibit highest price sensitivity, while hospital networks purchasing through long-term service contracts demonstrate lowest elasticity.
Supply Chain Analysis
Upstream feedstock for photoplethysmography sensors draws from Taiwan microcontroller foundries, Japanese optical component specialists, and German precision molding operations, with semiconductor wafer and medical-grade silicone as critical inputs. Single-source vulnerability in Taiwan semiconductor fabrication poses structural risk given geographic concentration of pulse oximetry ASIC production. Distribution runs through durable medical equipment suppliers into Medicare-reimbursed homecare channels and direct-to-employer wellness contract platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote Therapeutic Monitoring reimbursement expansion represents a regulatory inflection validating platform-based sleep disorder management as a high-growth disruption displacing traditional sleep clinic gatekeeper economics.
For Market Incumbents: Entrench cloud-connected device fleets through backward integration into photoplethysmography sensor fabrication, securing supply against Taiwan semiconductor bottlenecks while expanding Epic and Cerner EHR bidirectional data integration to lock in accountable care organization population health contracts against emerging diagnostic platform competitors.
For New Entrants and Emerging Players: India's underpenetrated employer wellness channels in Bangalore and Hyderabad IT services clusters offer white-space targeting through CDSCO Class A/B streamlined import registration, with corporate health program sleep screening protocols as the most penetrable entry vector and direct-to-patient telehealth platforms as the go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated device-cloud-service architectures with proven actuarial validation of therapy adherence guarantees, where long-term viability across the projection horizon hinges on AI-enabled polysomnography interpretation capabilities, with FDA breakthrough device designation awards as the signal to watch for algorithmic diagnostic tool inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates wearable diagnostic market entry against legacy polysomnography lab networks. |
| Cloud Platform Integration | Enables recurring adherence monitoring revenue from CPAP device-installed bases. |
| Hospital System Partnership | Secures long-term service contracts covering equipment maintenance and staff training. |
| Software Companion Development | Supports EU MDR clinical evidence requirements for algorithm-based sleep diagnostics. |
| Reimbursement Strategy | Captures CMS Remote Therapeutic Monitoring codes for home-based sleep apnea management. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with sleep medicine clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up and top-down triangulation reconciled device shipment estimates with payer claims data.
Forecast inputs considered product type segmentation across CPAP machines, sleep monitors, and therapeutic platforms; treatment type across behavioral, pharmacological, and cognitive behavioral modalities; and end-user channels spanning homecare settings, hospitals, and sleep clinics. CAGRs were derived from regression analysis against aging demographic projections and reimbursement code expansion timelines, with photoplethysmography sensor miniaturization curves and RTM adoption rates as industry-specific forecast inputs across the modeling period.
Practitioners should monitor FDA post-market cybersecurity guidance revisions and EU MDR software classification enforcement patterns for early signals of compliance cost escalation that could revise hardware margin assumptions. Cross-checking against CMS Medicare claims data benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Insomnia Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Home Sleep Screening Devices Market