
 Asia Pacific Sleep Tech Devices Market | 2026-2036
Asia Pacific Sleep Tech Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Sleep Tech Devices Market Insights
China's manufacturing corridor for consumer electronics is rewriting component economics for sleep tech assembly across the region. Xiaomi leverages its supply chain density to dominate price-accessible wearable trackers in Southeast Asian markets. Huawei Technologies Co., Ltd. sustains proprietary sensor development that anchors its sleep monitor line in domestic hospital procurement channels. ResMed competes through clinical-grade CPAP specialization that extends its footprint into Australian sleep center networks.
Asia Pacific sleep tech devices encompass instruments that capture physiological signals—heart rate variability, blood oxygen saturation, respiratory flow, and sleep stage architecture—to generate actionable sleep quality assessments for consumers and clinicians. These systems integrate photoplethysmography sensors, accelerometers, and machine learning inference engines to distinguish REM from deep sleep with clinical-grade fidelity. Wearable trackers and CPAP machines represent the largest installed base, though AI-driven technology segments attract disproportionate R&D allocation as algorithmic diagnostic accuracy improves. Smart pillows occupy a narrower but defensible niche where premium pricing aligns with integrated temperature regulation and positional therapy functions.
Japan's PMDA governs software-as-medical-device approvals for sleep diagnostics, while Australia's TGA enforces post-market surveillance that shapes product liability exposure for cloud-connected monitors. India's CDSCO medical device rules are forcing foreign manufacturers to localize technical documentation and quality management systems. Stakeholders must monitor how China's NMPA reconciles consumer wellness claims with evolving medical device boundaries, as this determination will reshape market access requirements and channel strategy across the region.
Market Dynamics
China's NMPA is tightening the boundary between consumer wellness claims and medical device classifications, forcing manufacturers to recalibrate their regulatory pathways and channel strategies across the Asia Pacific sleep tech landscape.
Growth Catalysts
- Japan's PMDA software-as-medical-device pathway:Sleep clinics in Tokyo and Osaka are accelerating procurement of diagnostic wearables cleared under this framework, expanding the addressable clinical market for algorithmic sleep monitors.
- Photoplethysmography sensor miniaturization:Component advances are enabling continuous SpO2 and heart rate variability tracking in form factors that bypass traditional sleep lab infrastructure.
- Tier-one city wellness spending:Consumer expenditure on health optimization in Shanghai, Beijing, and Shenzhen is creating premium price acceptance for integrated sleep systems.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fabs control the advanced node production for biosensor ASICs, exposing manufacturers to allocation volatility.
- India's CDSCO technical documentation mandates:Foreign manufacturers face 18-24 month localization timelines for quality management system certification, delaying market entry.
- Clinical validation costs:Polysomnography correlation studies required for medical-grade claims impose six-figure expenditure burdens on algorithm developers.
Strategic Opportunities
- Indonesia's underpenetrated archipelago:Telemedicine infrastructure expansion creates first-mover potential for cloud-connected diagnostic wearables in secondary cities.
- AI-driven sleep stage inference:Machine learning architectures trained on Asian demographic sleep architecture datasets offer differentiation against Western-calibrated competitors.
- Hospital-at-home reimbursement pilots:Australia's TGA is enabling remote patient monitoring codes that subsidize home sleep apnea testing devices.
Industry Challenges
- Firmware-hardware co-certification complexity:Australia's TGA post-market surveillance requirements for cloud-connected monitors create ongoing compliance engineering burdens.
- Cross-border data residency mandates:China's cybersecurity law and India's data localization rules fragment cloud architecture strategies for multi-country deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Sleep Tech Devices Market |
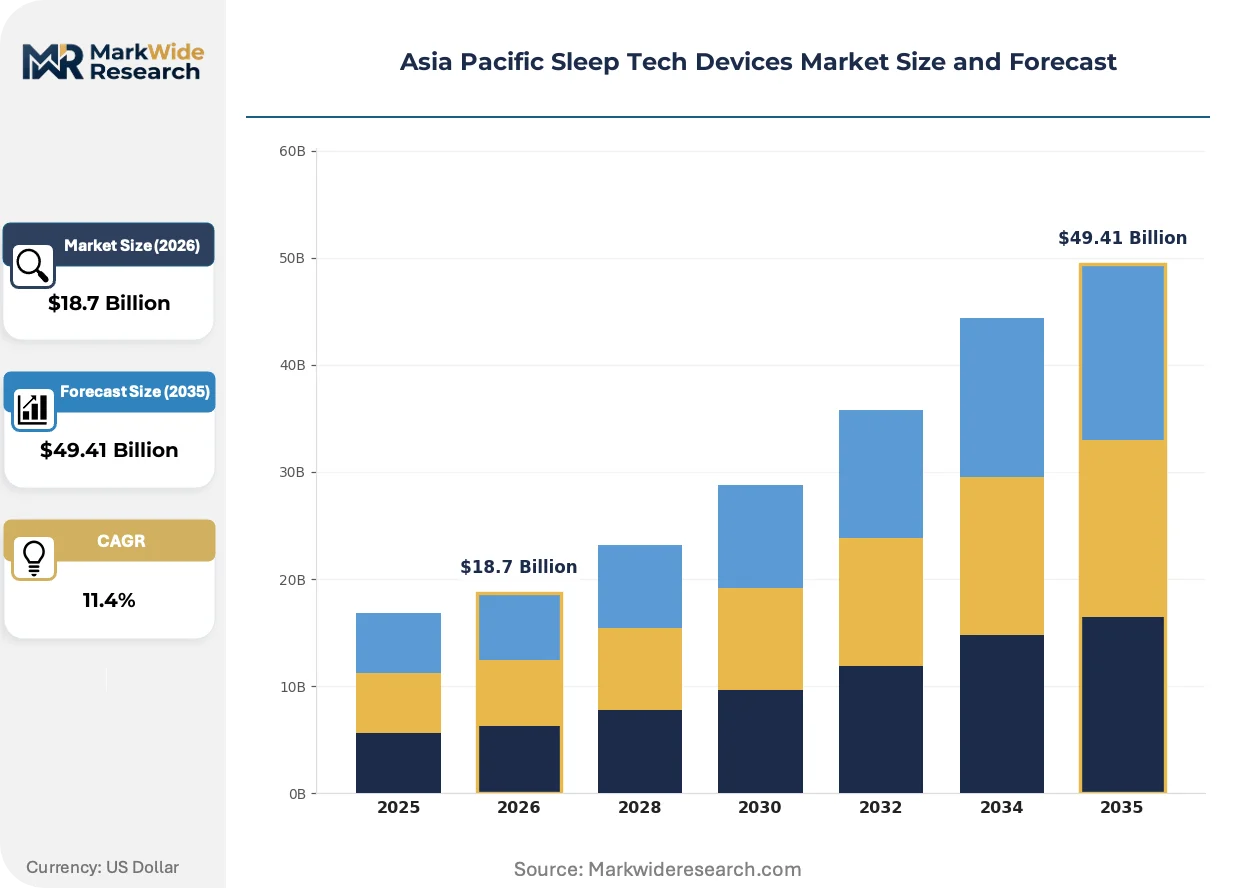
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Trackers, CPAP Machines, Smart Pillows, Sleep Monitors Technology: Sensor-based, AI-driven, Bluetooth-enabled, Cloud-connected End User: Individuals, Clinics, Hospitals, Sleep Centers Distribution Channel: Online Retail, Offline Stores, Direct Sales, Medical Suppliers |
| Companies Covered | Koninklijke Philips N.V., Wakefit, Compumedics Limited, Fitbit, Xiaomi, Huawei Technologies Co., Ltd., ResMed, Oura Health, Nihon Kohden Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Sleep Tech Devices Market Trends and Innovations
Algorithmic diagnostic engines are displacing hardware-centric competitive moats across the Asia Pacific sleep tech sector, compressing R&D cycles and elevating software engineering capabilities above traditional manufacturing scale.
Photoplethysmography arrays are hybridizing with accelerometer fusion algorithms to enable sleep stage classification without electroencephalography electrode placement. Sleep clinics in Japan and South Korea are piloting these systems for home diagnostic workflows, reducing in-lab bottlenecks. The technology is hybridizing the economic model of sleep medicine by shifting revenue capture from facility-based testing to recurring software subscriptions.
Australia's TGA has issued updated guidance on software-as-medical-device post-market surveillance that mandates adverse event reporting for cloud-connected sleep monitors. This regulatory shift is elevating cybersecurity engineering requirements and liability exposure for device manufacturers. Australian sleep center networks are responding by consolidating procurement around vendors with established quality management system certifications.
Hospital procurement committees in China are unbundling after-sales service contracts from device purchases, creating standalone recurring revenue streams for technical support and algorithm updates. This behavioral shift is compressing upfront hardware margins while extending customer lifetime value calculations. The pattern is most visible in tier-one city public hospital tenders where total cost of ownership frameworks dominate evaluation criteria.
Asia Pacific Sleep Tech Devices Market Segmentation
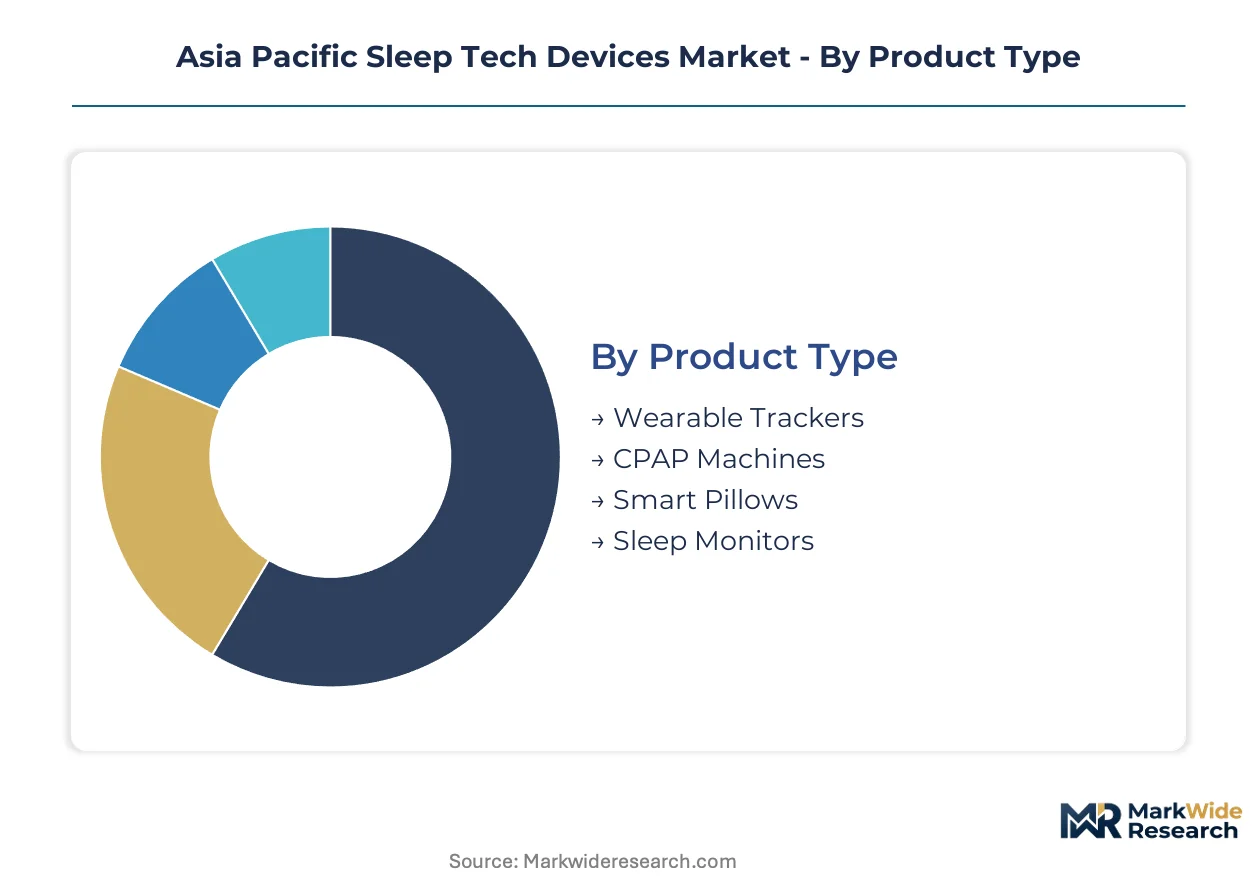
Sleep tech devices fragment across four dimensions that determine pricing power and channel strategy. Product type dictates hardware margins and service attachment rates. Technology tier separates wellness consumers from clinical procurement pathways. Understanding these splits reveals where vendors can extract recurring revenue versus one-time hardware sales.
Product Type:
After-sales service intensity varies dramatically across form factors, with clinical-grade systems demanding multi-year technical support contracts while consumer wearables rely on minimal warranty coverage.
- Wearable Trackers:Wrist-worn or ring-form devices integrating photoplethysmography sensors and accelerometers for continuous SpO2 and heart rate variability capture. Demand concentrates in China's tier-one cities where Xiaomi and Huawei compete on supply chain density and proprietary algorithm development.
- CPAP Machines:Positive airway pressure systems with heated humidification and cloud-connected compliance monitoring. Sleep clinics across Japan and Australia anchor procurement, with ResMed competing through clinical-grade specialization and hospital network penetration.
- Smart Pillows:Integrated temperature regulation and positional therapy systems with embedded pressure sensors. Premium pricing aligns with integrated wellness functions in Shanghai and Beijing consumer markets.
- Sleep Monitors:Non-contact bedside or under-mattress systems using radar or pressure array technology for sleep stage inference. Home diagnostic workflows in Tokyo and Osaka are piloting these for reduced in-lab bottlenecks.
By volume, Wearable Trackers leads. By growth pace, Sleep Monitors is expanding most quickly as algorithmic accuracy improves.
Technology:
Technology tier determines regulatory pathway complexity and R&D allocation intensity across the Asia Pacific landscape.
- AI-driven:Machine learning inference engines trained on demographic-specific sleep architecture datasets for REM and deep sleep classification. Japan's PMDA software-as-medical-device pathway is accelerating clinical procurement of these systems.
- Sensor-based:Photoplethysmography and accelerometer fusion without algorithmic sleep stage inference. Component miniaturization from Taiwan and South Korea fabs enables form factors that bypass traditional sleep lab infrastructure.
- Cloud-connected:Continuous data transmission to clinical dashboards with adverse event reporting mandates. Australia's TGA post-market surveillance requirements elevate cybersecurity engineering burdens and liability exposure.
- Bluetooth-enabled:Local device-to-smartphone pairing without persistent cloud connectivity. Consumer wellness markets in Southeast Asia favor these for data privacy and lower subscription costs.
By installed base, Sensor-based dominates. By R&D investment share, AI-driven is climbing the fastest.
End User:
End user type shapes procurement authority, evaluation criteria, and contract structure across regional markets.
- Hospitals:Public and private tertiary care facilities with total cost of ownership frameworks and unbundled after-sales service contracts. Tier-one city procurement committees in China are separating technical support from device purchases.
- Sleep Centers:Dedicated diagnostic facilities with polysomnography correlation requirements and medical-grade algorithm validation. Australian networks are consolidating vendor selection around established quality management certifications.
- Clinics:Outpatient and community-based facilities with lighter infrastructure and telemedicine integration. Indonesia's archipelago expansion creates first-mover potential for cloud-connected diagnostic wearables in secondary cities.
- Individuals:Direct-to-consumer purchasers through e-commerce and retail channels. Wellness spending acceleration in Shanghai, Beijing, and Shenzhen supports premium price acceptance for integrated systems.
By revenue concentration, Hospitals leads. By addressable market expansion, Individuals shows the steepest trajectory.
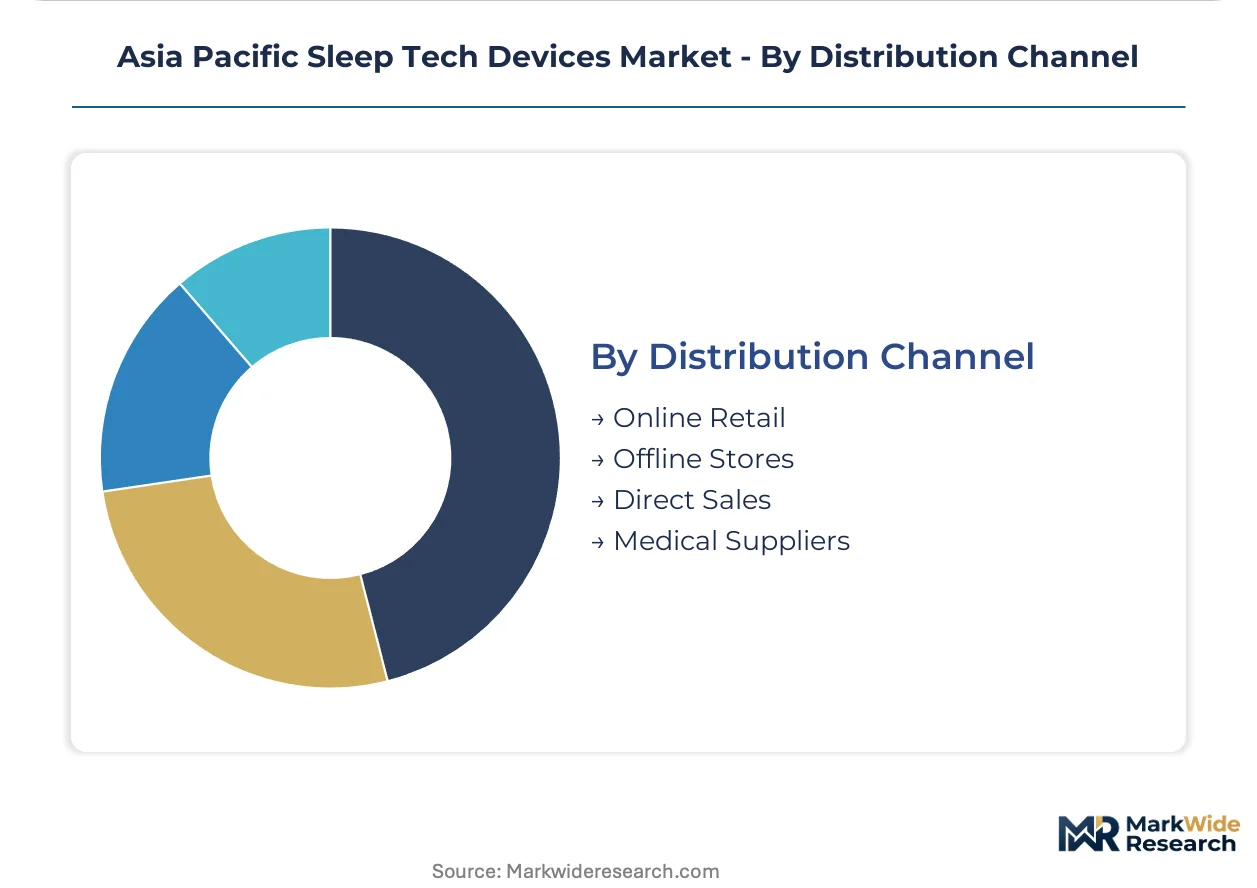
Distribution Channel:
Channel selection determines margin capture, customer acquisition cost, and regulatory compliance burden across national boundaries.
- Medical Suppliers:Specialized distributors with quality management system certifications and hospital tender participation. India's CDSCO technical documentation mandates force foreign manufacturers through 18-24 month localization timelines.
- Direct Sales:Manufacturer-controlled clinical specialist teams for complex system integration and training. ResMed deploys this model for CPAP specialization in Australian sleep center networks.
- Online Retail:E-commerce platforms with consumer wellness positioning and price-accessible tiers. Xiaomi leverages supply chain density to dominate Southeast Asian markets through this channel.
- Offline Stores:Electronics retailers and pharmacy chains with physical demonstration and immediate fulfillment. Huawei anchors domestic presence through hospital procurement channels alongside consumer retail.
By transaction volume, Online Retail leads. By margin retention, Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced node semiconductor fabrication concentrates in Taiwan and South Korea, exposing sleep tech manufacturers to allocation volatility while China's consumer electronics corridor rewrites component economics for regional assembly.
China
Shanghai and Shenzhen wellness spending accelerates demand for integrated sleep systems. NMPA tightens boundaries between consumer wellness claims and medical device classifications, forcing pathway recalibration. The Yangtze River Delta manufacturing cluster supplies photoplethysmography sensor modules to regional assemblers.
Japan
Tokyo and Osaka sleep clinics expand procurement of diagnostic wearables. PMDA governs software-as-medical-device approvals for algorithmic sleep monitors. The Kanto region anchors hospital procurement networks for clinical-grade systems.
India
CDSCO technical documentation mandates force foreign manufacturers through 18-24 month quality management system localization. Maharashtra and Karnataka medical device corridors attract technical documentation service providers. Secondary cities present telemedicine-integrated deployment opportunities.
Australia
TGA post-market surveillance requirements elevate cybersecurity engineering burdens for cloud-connected monitors. TGA enables remote patient monitoring reimbursement codes subsidizing home sleep apnea testing. Sydney and Melbourne sleep center networks consolidate procurement around certified vendors.
South Korea
MFDS regulatory frameworks align with software-as-medical-device pathways for AI-driven diagnostics. Seoul Capital Area hospitals pilot photoplethysmography-accelerometer fusion systems for home diagnostic workflows. The Busan-Ulsan corridor supplies biosensor ASIC components to regional manufacturers.
Asia Pacific Sleep Tech Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The market structures around three tiers: multinational clinical-grade specialists, regional consumer electronics platforms, and algorithm-focused software vendors. Consolidation pressures concentrate in the clinical segment where quality management certifications create switching costs. Dominant competitive moves include strategic partnerships for algorithm licensing and geographic expansion through regulatory pathway optimization.
Within the clinical-grade tier, ResMed and Koninklijke Philips N.V. exemplify specialization strategies. Xiaomi and Huawei Technologies Co., Ltd. occupy positions in the consumer platform segment. Oura Health represents the algorithm-native archetype. These anchors illustrate how competitive positioning splits across hardware scale, regulatory certification depth, and software inference capability.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Wakefit |
| Compumedics Limited |
| Fitbit |
| Xiaomi |
| Huawei Technologies Co., Ltd. |
| ResMed |
| Oura Health |
| Nihon Kohden Corporation |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's container cost dynamics compress hardware margins for sleep tech assemblers while amplifying price differentiation between clinical-grade and wellness-tier devices across Asia Pacific distribution networks.
Pricing Analysis
NMPA's software-as-medical-device classification dictates the pricing tier structure across the region, separating cloud-connected diagnostic systems with adverse event reporting obligations from Bluetooth-enabled wellness trackers. Certification-grade differentiation separates hospital procurement channels with unbundled service contracts from direct-to-consumer retail with minimal warranty coverage. Pricing pressure stems from semiconductor allocation volatility as Taiwan and South Korea fabs constrain biosensor ASIC supply. Individual consumers in Southeast Asian markets exhibit highest price sensitivity, while Japanese sleep clinics demonstrate lowest sensitivity due to reimbursement-adjacent procurement frameworks.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Pegatron, and BYD Electronics for final assembly, while Taiwan Semiconductor Manufacturing and Samsung Foundry hold advanced node capacity for photoplethysmography sensor ASICs. Component sourcing draws from China's Yangtze River Delta for sensor modules, South Korea's Busan-Ulsan corridor for memory chips, and Japan's Kanto region for precision components. Single-source vulnerability concentrates in Taiwan's 7nm and below fabrication capacity for machine learning inference engines. Distribution runs through medical suppliers with quality management certifications in regulated markets and online retail platforms in consumer wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sleep tech is approaching a platform-economics inflection where algorithmic inference engines displace hardware-centric competitive moats, with interoperability standards across Japan's PMDA-cleared devices and Australia's TGA-monitored systems creating ecosystem lock-in effects.
For Market Incumbents: Entrench clinical-grade certification depth as a switching cost barrier against algorithm-native entrants by accelerating PMDA software-as-medical-device submissions and consolidating Australian sleep center procurement through quality management system investments. Firmware-hardware co-certification complexity under TGA post-market surveillance requirements creates defensive moats that consumer electronics platforms cannot easily replicate. For New Entrants and Emerging Players: Build out telemedicine-integrated deployment in Indonesia's secondary cities where cloud-connected diagnostic wearables face minimal incumbent saturation and CDSCO localization timelines have not yet created entrenched foreign manufacturer positions. Target clinic-tier procurement with lighter infrastructure requirements rather than hospital tender participation. For Investors and Strategic Acquirers: Carve-out targets emerge from consumer electronics conglomerates with dormant sleep tech divisions lacking clinical regulatory pathways. Long-term viability hinges on algorithm training data moats specific to Asian demographic sleep architecture rather than Western-calibrated competitors. Watch for TGA reimbursement code expansion for home sleep apnea testing as inflection signal for remote patient monitoring valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Submission | Unlocks hospital procurement channels in Japan's Kanto region with recurring service contract potential. |
| Photoplethysmography Sensor ASIC Partnership | Secures allocation priority from Taiwan and South Korea fabs amid semiconductor supply volatility. |
| Indonesia Telemedicine Channel Expansion | Captures first-mover positioning in archipelago secondary cities with minimal incumbent presence. |
| AI Sleep Stage Inference Engine Development | Differentiates against Western-calibrated algorithms through Asian demographic training datasets. |
| CDSCO Quality Management Localization | Accelerates 18-24 month market entry timeline for India's Maharashtra and Karnataka corridors. |
Research Methodology
A standing panel of sleep medicine clinicians, hospital procurement committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from PMDA approval databases, TGA adverse event reporting systems, CDSCO technical documentation registries, and NMPA classification guidance documents. Bottom-up sleep clinic and hospital procurement surveys triangulated with top-down semiconductor trade flow analysis and component bill-of-materials estimation.
Scenario-bracketing framed projections across the analysis window, modeling product type segmentation by hardware margin and service attachment intensity, technology tier by regulatory pathway complexity, end user by procurement authority, and distribution channel by margin retention. CAGRs derived from weighted average of clinician adoption curve slopes, semiconductor capacity expansion announcements, and reimbursement code expansion probabilities. Forecast inputs incorporated photoplethysmography sensor miniaturization curves and machine learning diagnostic accuracy improvement rates.
Stress conditions across NMPA classification boundary shifts, Taiwan fab allocation volatility, and Australian TGA cybersecurity mandate stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about algorithmic diagnostic correlation with polysomnography gold standards and telemedicine infrastructure deployment cadence. Quarterly review of PMDA software-as-medical-device approval velocity and CDSCO localization timeline compression is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Hypoventilation Management Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Americas Insomnia Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Global Sleep Tech Devices Market