
 Oral Sleep Apnea Market | 2026-2036
Oral Sleep Apnea Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Sleep Apnea Market Analytics
The home sleep testing segment is pivoting toward oral appliance therapy as first-line intervention for mild-to-moderate obstructive sleep apnea. ResMed leverages its diagnostic-to-therapy ecosystem to sustain channel control across both CPAP and oral device portfolios. SomnoMed anchors geographic dominance through direct dental lab networks spanning North America and Europe. ProSomnus Sleep Technologies differentiates via precision-manufactured, digitally designed mandibular advancement devices with sub-millimeter titration accuracy.
Oral sleep apnea devices are custom-fabricated intraoral appliances that mechanically advance the mandible or retain the tongue to maintain patent upper airway patency during sleep, typically requiring 3D oral scanning and CAD/CAM milling or printing to achieve patient-specific fit within 0.5mm tolerance. Their primary commercial purpose is to reduce apnea-hypopnea index scores in patients who fail or reject positive airway pressure therapy. Mandibular advancement devices occupy the dominant revenue position due to established efficacy data and broad dental prescriber familiarity, while thermoplastic materials capture volume share through boil-and-bite entry-level pricing that expands access in direct-to-consumer channels. Silicone and nylon segments are gaining structural momentum as digital workflows enable thinner, more durable biocompatible designs that improve long-term compliance rates.
FDA 510(k) premarket notification requirements govern oral appliance safety and efficacy claims in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for mandibular advancement devices sold in European markets. Medicare's durable medical equipment fee schedule and evolving prior authorization criteria directly shape patient out-of-pocket exposure and dental practice revenue models. Stakeholders must monitor reimbursement parity developments between oral appliances and CPAP therapy, as payer policy shifts will determine whether dental sleep medicine expands beyond specialty practices into general dentistry workflows.
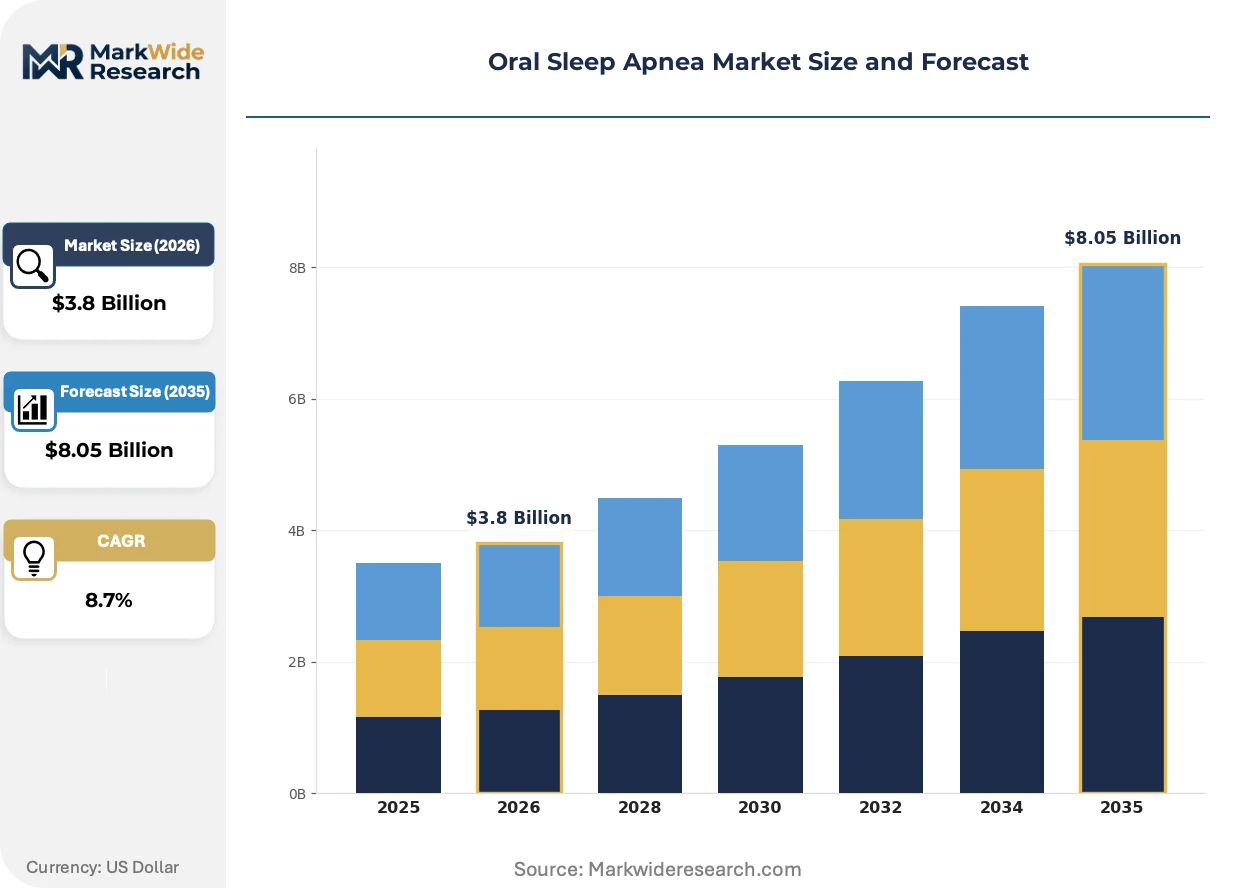
Market Dynamics
CPAP intolerance among diagnosed adults is forcing a structural pivot toward mandibular advancement devices as first-line therapy, reshaping prescriber networks and reimbursement flows across dental sleep medicine.
Growth Catalysts
- Medicare DME Fee Schedule Expansion:CMS reimbursement codes for oral appliances are unlocking patient access in US metropolitan sleep centers, converting previously self-pay dental workflows into billable medical encounters.
- Home Sleep Testing Protocols:Diagnostic decentralization is routing mild-to-moderate OSA patients directly to dental practices before CPAP trial, compressing time-to-treatment and expanding addressable device volume.
- Nylon and Silicone Material Science:Biocompatible polymer advances are enabling thinner, more durable device architectures that improve overnight compliance rates and extend replacement cycles.
Market Restraints
- CAD/CAM Equipment Capital Intensity:Digital intraoral scanners and milling systems require substantial upfront investment, concentrating fabrication capacity within larger dental group practices and specialized sleep labs.
- EU MDR Clinical Evidence Burden:The European Medical Device Regulation's stricter documentation requirements for mandibular advancement devices are extending time-to-market and elevating compliance costs for manufacturers seeking CE marking.
- Thermoplastic Boil-and-Bite Substitution:Low-cost direct-to-consumer entry devices are capturing price-sensitive segments, pressuring margins on prescription-grade custom appliances despite inferior efficacy data.
Strategic Opportunities
- General Dentistry Workflow Integration:Untapped referral channels exist among non-specialist dental practices in US suburban and rural markets where sleep medicine penetration remains minimal.
- FDA 510(k) Predicate Pathway Optimization:Streamlined premarket notification routes for incremental device modifications are accelerating product iteration cycles and enabling faster feature differentiation.
- Telehealth-Fitted Remote Delivery:Direct-to-patient impression kits combined with virtual titration protocols are emerging as a channel innovation that bypasses traditional dental office visits.
Industry Challenges
- Dental Sleep Medicine Credentialing:Shortage of dentists with American Academy of Dental Sleep Medicine certification is bottlenecking prescription capacity in high-demand metropolitan corridors.
- Prior Authorization Administrative Burden:Variable Medicare Advantage and commercial payer documentation requirements are creating reimbursement friction that delays device dispensing and elevates practice overhead.
- Legacy CPAP Manufacturer Channel Defense:ResMed and Philips Respironics are leveraging established durable medical equipment relationships to slow dental referral momentum through integrated diagnostic-to-therapy bundling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Sleep Apnea Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Mandibular Advancement Device, Tongue Retaining Device, CPAP, BiPAP Material: Thermoplastic, Silicone, Acrylic, Nylon Distribution Channel: Hospital, Retail, E-Commerce, Clinics End User: Adults, Children, Seniors, Healthcare Providers |
| Companies Covered | SomnoMed, ResMed, ProSomnus Sleep Technologies, Whole You, Oventus Medical, Panthera Dental, Airway Management, DynaFlex, Vivos Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Sleep Apnea Market Evolving Landscape
Digital fabrication workflows and regulatory pathway refinements are compressing device development cycles while patient acquisition models shift away from traditional sleep center gatekeeping.
Intraoral scanning and chairside CAD/CAM production is consolidating control over device fit precision within dental practices equipped with digital infrastructure. Sleep clinics lacking in-house fabrication partnerships are ceding margin to dental labs that capture both diagnostic referral and manufacturing revenue. This technology compression is displacing conventional alginate impression and outsourced casting workflows that dominated the prior decade.
EU MDR implementation is elevating clinical evidence standards for mandibular advancement devices marketed in European Economic Area jurisdictions. Manufacturers must now submit prospective trial data rather than predicate-based equivalence arguments, extending regulatory timelines by 12-18 months. German and French notified bodies are applying the strictest interpretation, forcing portfolio prioritization toward higher-volume SKUs.
Patient acquisition is fragmenting across direct-to-consumer, telehealth-integrated, and traditional dental referral channels simultaneously. Direct channels leverage social media advertising and home impression kits to reach CPAP-intolerant searchers, while sleep centers defend volume through exclusive dental network contracts. The United States exhibits the most pronounced channel experimentation, with California and Texas markets hosting multiple competing fulfillment models.
Oral Sleep Apnea Market Segmentation
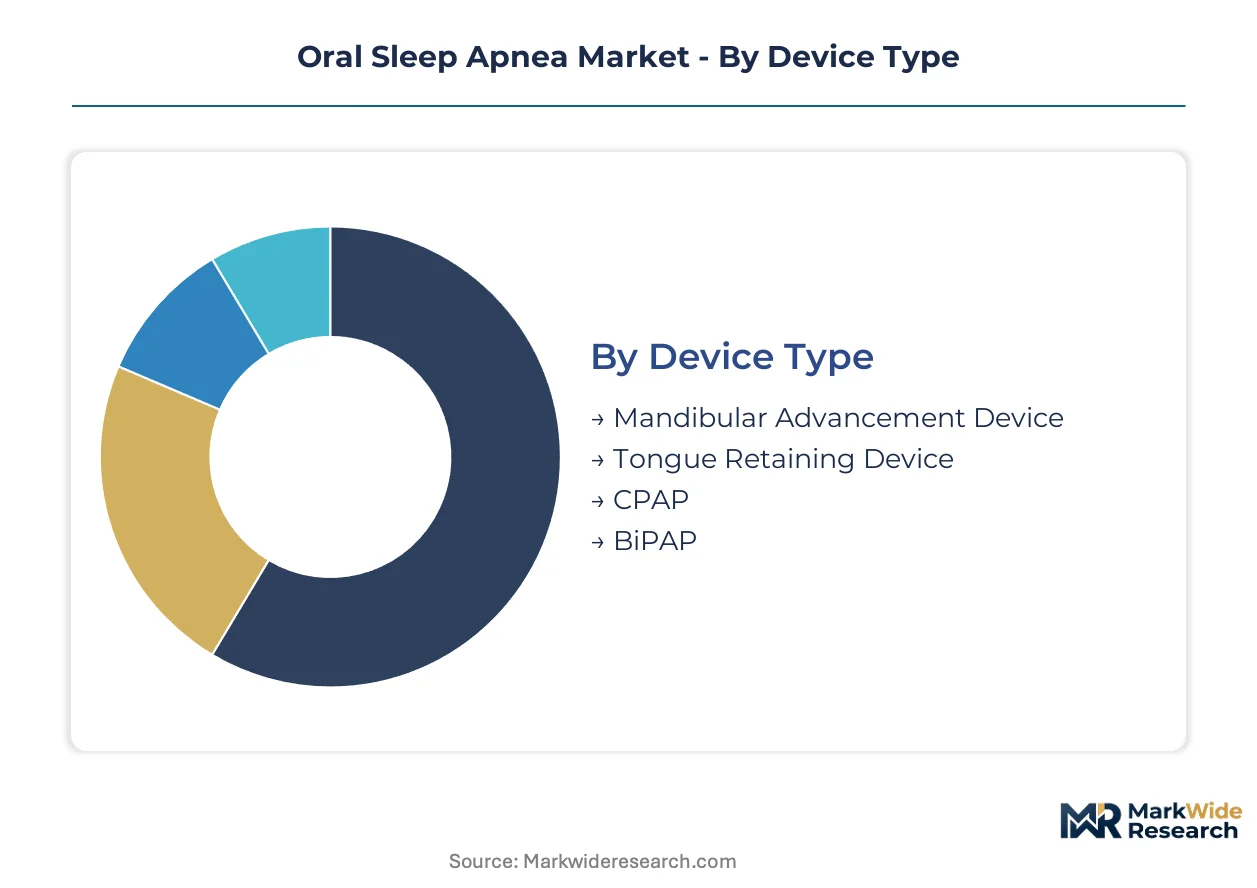
Oral sleep apnea device segmentation reveals divergent capital requirements across fabrication methods, material science tiers, and patient access channels. Each dimension shapes margin structures, regulatory pathways, and competitive moats differently.
Device Type:
Mandibular advancement devices demand the heaviest upfront investment in digital intraoral scanners, CAD/CAM milling systems, and dental sleep medicine credentialing. CPAP and BiPAP systems require substantial manufacturing infrastructure but flow through distinct durable medical equipment channels with established reimbursement machinery.
- Mandibular Advancement Device:Custom-fabricated intraoral appliances mechanically advance the mandible to maintain upper airway patency, requiring 3D oral scanning and precision milling within 0.5mm tolerance. Demand concentrates in US metropolitan sleep center networks where Medicare DME reimbursement codes have converted self-pay dental workflows into billable medical encounters. FDA 510(k) clearance pathways and rising CPAP intolerance among diagnosed adults are accelerating dental prescriber adoption.
- CPAP:Positive airway pressure systems deliver continuous pressurized airflow via mask interface, representing the historical clinical standard with extensive efficacy documentation. ResMed and Philips Respironics dominate supply through integrated diagnostic-to-therapy bundling that defends channel relationships against dental referral momentum. Patient noncompliance rates exceeding 50% are forcing structural pivot toward oral alternatives in mild-to-moderate obstructive sleep apnea cases.
- Tongue Retaining Device:Suction-based appliances retain the tongue in forward position without mandibular advancement, suited for patients with dental contraindications.
- BiPAP:Bilevel positive airway pressure systems alternate inspiratory and expiratory pressure settings, primarily serving complex or central sleep apnea presentations.
Most installed capacity flows through Mandibular Advancement Device fabrication networks. Expansion is steepest in Tongue Retaining Device segments addressing CPAP-intolerant patients with edentulism or periodontal limitations.
Material:
Material selection determines manufacturing workflow, biocompatibility certification burden, and long-term compliance economics. Nylon and silicone variants command premium positioning through thinner, more durable architectures that extend replacement cycles and improve overnight tolerance.
- Nylon:Biocompatible polymer enabling digitally designed, precision-manufactured devices with sub-millimeter titration accuracy and extended durability. German and French notified bodies apply strictest EU MDR interpretation to nylon mandibular advancement devices, forcing manufacturers toward higher-volume SKUs with prospective trial data rather than predicate equivalence.
- Silicone:Flexible, hypoallergenic material permitting thinner device profiles that reduce oral cavity intrusion and improve long-term compliance rates. ProSomnus Sleep Technologies leverages silicone in digitally designed architectures targeting CPAP-intolerant patients seeking premium comfort positioning.
- Thermoplastic:Boil-and-bite entry material capturing price-sensitive volume through direct-to-consumer channels despite inferior efficacy data.
- Acrylic:Conventional rigid polymer displaced by advanced alternatives but retained in budget-tier prescription workflows.
Silicone and nylon together capture the highest-margin prescription volume. Thermoplastic segments face margin compression from low-cost direct-to-consumer substitution.
Distribution Channel:
Channel structure determines patient acquisition cost, reimbursement friction, and prescriber relationship depth. Dental practices and sleep clinics are consolidating control through exclusive network contracts and in-house fabrication partnerships.
- Clinics:Dental sleep medicine practices and hospital-affiliated sleep centers with direct fabrication partnerships capture both diagnostic referral and manufacturing margin. Home sleep testing protocols are routing mild-to-moderate OSA patients directly to these channels before CPAP trial.
- Hospital:Academic medical centers and integrated delivery networks with credentialing infrastructure for complex or comorbid presentations.
- E-Commerce:Direct-to-patient platforms leveraging social media advertising and home impression kits to reach CPAP-intolerant searchers.
- Retail:Limited pharmacy and medical supply store presence for entry-level thermoplastic devices.
Clinic channels command the highest patient lifetime value. E-commerce segments are gaining share fastest among younger, digitally native demographics.
End User:
Patient demographics dictate device sizing, titration protocols, and compliance support requirements. Adult segments dominate commercial volume while pediatric and senior applications present distinct regulatory and reimbursement complexities.
- Adults:Primary commercial segment encompassing employed adults with commercial insurance or Medicare eligibility, representing the core addressable market for mandibular advancement therapy. CPAP intolerance rates among diagnosed adults are forcing prescriber network expansion into general dentistry workflows beyond specialty sleep practices.
- Seniors:Medicare-eligible population with elevated obstructive sleep apnea prevalence and strong DME reimbursement coverage, though dental edentulism complicates mandibular advancement candidacy.
- Children:Pediatric applications limited by craniofacial growth considerations and restricted FDA labeling for most oral appliances.
- Healthcare Providers:Institutional procurement for sleep center inventory and dental group practice standardization.
Adult segments absorb the majority of manufacturing capacity. Senior applications are expanding most quickly as Medicare Advantage plans broaden oral appliance coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EU MDR compliance costs push fabrication capacity toward jurisdictions with streamlined premarket pathways. Device makers now optimize location strategies around reimbursement density rather than labor arbitrage alone.
United States
Medicare DME fee schedule expansion and rising CPAP intolerance are routing mild-to-moderate OSA patients toward dental sleep medicine practices. FDA 510(k) clearance pathways enable faster product iteration than European equivalents. Metropolitan sleep center networks in California and Texas concentrate prescriber capacity and fabrication partnerships.
Germany
Notified bodies apply the strictest EU MDR interpretation to mandibular advancement devices, forcing manufacturers toward prospective trial data. Bavaria hosts specialized dental sleep medicine clusters with direct lab integration. German dental practices capture manufacturing margin through in-house CAD/CAM production partnerships.
Japan
PMDA regulatory frameworks maintain rigorous clinical evidence standards for oral appliances while aging demographics expand addressable patient pools. METI industrial policy supports precision manufacturing capabilities in medical device polymers. Osaka-Kansai dental lab networks specialize in digitally fabricated mandibular advancement devices for export markets.
Australia
TGA oversight aligns with international harmonization initiatives, reducing duplication for manufacturers with FDA or CE marking. Home sleep testing protocol adoption routes patients directly to dental practices before CPAP trial. Sydney and Melbourne sleep centers anchor prescriber networks with integrated fabrication partnerships.
Canada
Health Canada medical device regulations provide intermediate stringency between FDA and EU MDR pathways, attracting regional headquarters functions. Provincial reimbursement variation creates patchwork access patterns for oral appliance therapy. Ontario and Quebec dental group practices consolidate fabrication capacity through shared digital infrastructure.
Oral Sleep Apnea Market Competitive Landscape
Strategic partnerships dominate the current landscape as device makers secure dental lab networks and diagnostic referral channels. The vendor base concentrates around three tiers: integrated diagnostic-to-therapy ecosystems, specialized mandibular advancement fabricators, and direct-to-consumer platforms. Archetypes include sleep technology conglomerates defending CPAP-adjacent positions, digitally native dental device specialists, and telehealth-integrated remote delivery platforms. M&A activity and exclusive network contracting represent the primary competitive moves reshaping channel control.
Among digitally focused fabricators, ProSomnus Sleep Technologies and SomnoMed occupy positions exemplifying precision-manufactured and direct dental lab network strategies respectively. ResMed represents the integrated ecosystem archetype with diagnostic-to-therapy bundling capabilities. These three anchors illustrate divergent responses to CPAP intolerance trends: specialized oral appliance depth versus portfolio breadth spanning positive airway pressure alternatives.
| Leading Market Players |
|---|
| SomnoMed |
| ResMed |
| ProSomnus Sleep Technologies |
| Whole You |
| Oventus Medical |
| Panthera Dental |
| Airway Management |
| DynaFlex |
| Vivos Therapeutics |
| Others |
Value Network & Pricing Analysis
CPAP intolerance among diagnosed adults is forcing dental sleep medicine practices to absorb fabrication capacity investments that were previously outsourced, compressing channel margins while elevating pricing power for practices with in-house CAD/CAM infrastructure. This demand-side consolidation around direct dental lab networks is reshaping how device economics flow through prescriber relationships.
Pricing Analysis
Dental lab markups on outsourced mandibular advancement devices typically range from forty to sixty percent above raw polymer and milling costs, though in-house CAD/CAM production at larger group practices captures this margin internally. Three-tier pricing structure across premium silicone-nylon hybrids, standard acrylic appliances, and economy thermoplastic boil-and-bite devices reflects material certification grade and titration precision. Pricing pressure stems from direct-to-consumer thermoplastic substitution in price-sensitive segments despite inferior clinical outcomes. Medicare Advantage plans exhibit the highest price sensitivity due to variable prior authorization burdens, while cash-pay patients at metropolitan sleep centers demonstrate lowest sensitivity when CPAP intolerance is acute.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Australia anchor hub-and-spoke fulfillment patterns for precision-milled mandibular advancement devices, with satellite dental labs in Canada and Japan handling localized finishing workflows. Biocompatible nylon polymer feedstock draws primarily from German chemical suppliers and Japanese precision polymer manufacturers, while intraoral scanner hardware sources from Taiwanese and South Korean electronics clusters. Single-source vulnerability concentrates in EU MDR-certified polymer grades where notified body approvals create qualification bottlenecks. Distribution runs through exclusive dental network contracts that bundle diagnostic referral with fabrication revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in oral sleep apnea devices rests on digital workflow compression that eliminates outsourced dental lab intermediaries, coupled with premium-tier shift toward silicone-nylon hybrids that command replacement cycle premiums.
For Market Incumbents: Extend control over fabrication capacity through backward integration into CAD/CAM milling infrastructure at affiliated dental group practices, defending against direct-to-consumer thermoplastic substitution by emphasizing FDA 510(k) clearance differentiation and Medicare reimbursement access. Prioritize certification investment in EU MDR predicate pathways to maintain European market presence amid clinical evidence burden escalation. For New Entrants and Emerging Players: Capture telehealth-integrated remote delivery white space among CPAP-intolerant patients in US suburban and rural markets where dental sleep medicine penetration remains minimal, leveraging home impression kits and virtual titration protocols to bypass traditional sleep center gatekeeping. Target general dentistry workflows as the most penetrable prescriber segment, using direct-to-patient social media acquisition to route volume toward affiliated fabrication partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with digitally native dental device specialists possessing proprietary CAD/CAM workflows and exclusive dental lab network contracts, given five-to-ten year reimbursement parity momentum between oral appliances and CPAP therapy. Acquisition target archetype: mid-scale fabricators with Medicare DME billing infrastructure and nylon-silicone material science capabilities. Signal to watch: CMS prior authorization simplification for oral appliances as inflection indicator for addressable volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates product iteration cycles for mandibular advancement devices against EU MDR timelines. |
| Dental Lab Network Partnership | Captures fabrication margin and diagnostic referral revenue through exclusive prescriber contracts. |
| Reimbursement Strategy | Unlocks Medicare DME fee schedule access and reduces patient out-of-pocket friction. |
| Software Companion Development | Enables remote titration monitoring and compliance tracking for telehealth-integrated delivery. |
| CE Marking Pathway | Maintains European Economic Area access amid stricter clinical evidence requirements. |
Research Methodology
Bottom-up dental practice and sleep clinic modeling reconciled against top-down polymer supply and intraoral scanner shipment tracking forms the analytical core of this study. Primary interviews with dental sleep medicine practitioners, biomedical engineers at mandibular advancement device manufacturers, Medicare reimbursement specialists, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CMS Medicare data, EU MDR notified body registers, and dental lab industry association reports. Triangulation across these sources ensures segmentation outputs align with observed prescriber behavior and fabrication capacity deployment.
Historical trendline analysis of mandibular advancement device volumes, CPAP discontinuation rates, and dental sleep medicine credentialing expansion established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include device type, material science tier, distribution channel structure, and end-user demographic cluster, with CAGRs derived from regression against home sleep testing protocol adoption and Medicare DME fee schedule evolution. Forecast inputs incorporate intraoral scanner penetration rates at dental group practices and EU MDR implementation timelines for notified body re-certification.
Regulatory pathway delays, reimbursement policy reversals, and thermoplastic direct-to-consumer substitution acceleration are the dominant revision risks that could alter volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Americas Insomnia Market
Sleep Medicine
Insomnia Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Excessive Daytime Sleepiness Market