
 Americas Insomnia Market | 2026-2036
Americas Insomnia Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Insomnia Market Analysis
Aftermarket patient support and adherence monitoring revenue is fragmenting across digital platforms and traditional pharmacy networks. Sanofi S.A. leverages its established primary care infrastructure to sustain prescription refill volumes. Teva Pharmaceutical Industries Ltd. competes through generic sleep medication portfolios that anchor cost-sensitive segments.
Americas insomnia encompasses chronic and acute sleep initiation or maintenance disorders diagnosed through polysomnography, actigraphy, or clinical interview criteria, treated via pharmacologic or behavioral interventions to restore sleep architecture and daytime functioning. Prescription medications occupy the dominant margin pool, while cognitive behavioral therapy represents the fastest-growing structural segment as payers prioritize non-pharmacologic first-line protocols. Oral delivery mode maintains volume leadership, though transdermal formats are gaining formulary placement for elderly populations with polypharmacy risks.
FDA bioequivalence standards and Health Canada ICH-GCP frameworks govern new molecular entity approvals and clinical trial conduct, directly shaping product development timelines and market access conditions. The Drug Enforcement Administration schedules controlled substances for insomnia, constraining manufacturing quotas and distribution channel eligibility for certain hypnotic classes. Stakeholders must monitor evolving FDA guidance on digital therapeutics and state-level telehealth prescribing rules that could redraw competitive boundaries between pharmaceutical and device-based sleep interventions.
Market Dynamics
FDA guidance on digital therapeutics is compressing development timelines for software-based sleep interventions while DEA scheduling quotas constrain controlled-substance manufacturing capacity across the United States.
Growth Catalysts
- Cognitive behavioral therapy protocols:Health Canada and US payers now mandate non-pharmacologic first-line treatment for chronic insomnia, expanding reimbursement for behavioral sleep medicine specialists and digital CBT-I platforms.
- Transdermal delivery systems:Elderly populations with polypharmacy risks are driving formulary placement of patch-based hypnotics that bypass first-pass hepatic metabolism and reduce drug-drug interaction potential.
- Actigraphy and home sleep testing:Portable diagnostic devices are displacing in-lab polysomnography for uncomplicated insomnia cases, lowering diagnostic barriers and accelerating treatment initiation in primary care settings.
Market Restraints
- Controlled substance quotas:DEA manufacturing limits on Schedule IV hypnotics create periodic supply shortages and force prescribers toward non-controlled alternatives with inferior efficacy profiles.
- Generic price erosion:Patent expirations for zolpidem and eszopiclone have compressed margins in the oral hypnotic segment, redirecting R&D investment toward novel mechanisms with higher clinical development risk.
- Residual sedation liability:Next-day impairment concerns limit dosing flexibility for GABA-A modulators, particularly in safety-sensitive occupational categories regulated by DOT and OSHA guidelines.
Strategic Opportunities
- Brazil and Mexico expansion:Underpenetrated Latin American markets present whitespace for insomnia diagnostics as private health insurance penetration rises and sleep medicine specialist training programs expand.
- Orexin receptor antagonists:Dual orexin receptor antagonists with distinct pharmacokinetic profiles are capturing treatment-resistant segments seeking alternatives to GABA-A modulation.
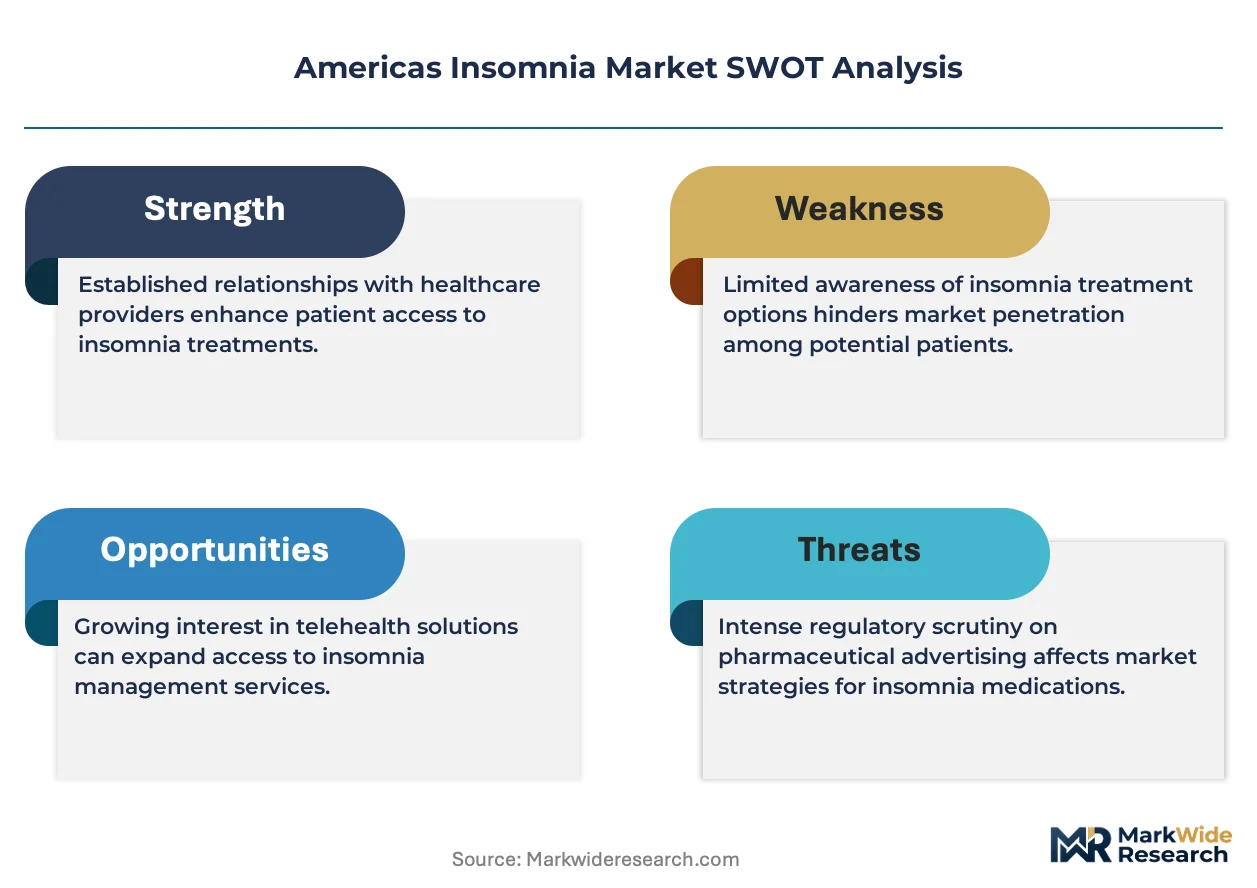
- Telehealth prescribing channels:State-level telehealth parity laws are enabling direct-to-patient digital therapeutic distribution, bypassing traditional pharmacy networks for prescription digital therapeutics.
Industry Challenges
- Sleep medicine specialist scarcity:Board-certified behavioral sleep medicine practitioners remain concentrated in major metropolitan academic centers, creating access bottlenecks for CBT-I delivery.
- Digital therapeutic validation:Randomized controlled trial requirements for FDA Software as a Medical Device designation demand substantial upfront investment with uncertain reimbursement coding outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Insomnia Market |
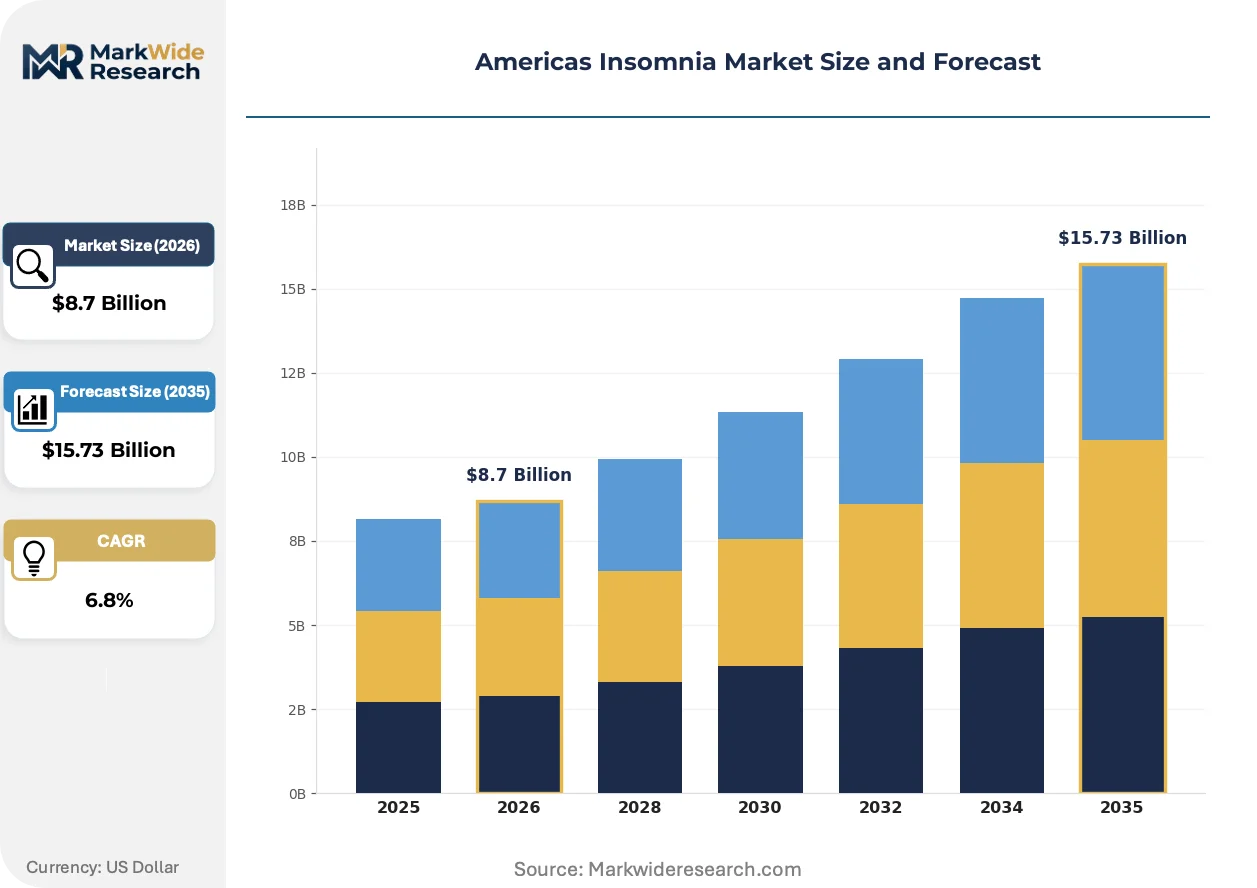
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, Over-the-Counter Medications, Herbal Supplements, Cognitive Behavioral Therapy Delivery Mode: Oral, Transdermal, Injectable, Inhalable End User: Adults, Elderly, Pediatric, Healthcare Providers Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospitals, Clinics |
| Companies Covered | Sanofi S.A., Teva Pharmaceutical Industries Ltd., Pfizer Inc., Johnson & Johnson, AstraZeneca PLC, Merck & Co., Takeda Pharmaceutical Company Ltd., Novartis AG, Eli Lilly and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Insomnia Market Emerging Trajectories
Pharmaceutical and device-based insomnia interventions are converging around personalized sleep architecture targets rather than universal hypnotic endpoints, reshaping product development priorities across the Americas.
Dual orexin receptor antagonists are migrating from investigational status to standard-of-care positioning for sleep maintenance insomnia. Sleep specialists in the United States and Canada are adopting these agents for patients with comorbid obstructive sleep apnea who cannot tolerate traditional hypnotics. The technology is migrating from niche academic prescribing to broad formulary inclusion, compressing market share for benzodiazepine receptor agonists.
FDA draft guidance on prescription digital therapeutics is mandating randomized controlled trial evidence for software-based insomnia interventions. This regulatory bar is elevating development costs and extending time-to-market for digital CBT-I platforms while filtering out lower-evidence wellness applications. The policy shift most affects venture-backed digital health startups targeting employer and health plan channels.
Employer-sponsored health plans are unbundling sleep management from general behavioral health contracts and negotiating direct agreements with specialized digital therapeutic vendors. This procurement fragmentation is disrupting traditional pharmacy benefit manager control over insomnia medication spend. The pattern is most visible among Fortune 500 employers in technology and financial services sectors with self-insured arrangements.
Americas Insomnia Market Segmentation

Insomnia treatment pathways diverge sharply across product categories, with reimbursement protocols and patient risk profiles determining which segments capture volume. Delivery mode selection increasingly reflects age-related polypharmacy concerns and formulary placement strategies rather than efficacy alone.
Product Type:
Cost tier determines margin structure and R&D allocation across pharmacologic and non-pharmacologic insomnia interventions.
- Prescription Medications:GABA-A modulators, melatonin receptor agonists, and orexin receptor antagonists constitute the reimbursed core of insomnia pharmacotherapy. United States commercial payers and Medicare Part D plans concentrate spending here, though DEA scheduling quotas periodically constrain supply for controlled substances.
- Over-the-Counter Medications:Diphenhydramine and doxylamine formulations dominate self-directed sleep aid purchases without prescription requirements. Retail pharmacy chains across the United States and Canada move significant volume through front-of-store placement, particularly among cost-conscious working-age adults without diagnosed chronic insomnia.
- Herbal Supplements:Melatonin, valerian root, and chamomile extracts occupy the unregulated periphery of sleep support.
- Cognitive Behavioral Therapy:CBT-I protocols represent the fastest-expanding structural segment as US and Canadian payers mandate non-pharmacologic first-line treatment for chronic cases.
Prescription medications hold installed capacity. Cognitive Behavioral Therapy is rotating up the share rankings.
Delivery Mode:
Application context—age demographics, comorbidity burden, and safety sensitivity—drives selection among administration routes.
- Oral:Tablets and capsules remain the default formulation for hypnotic agents across all patient populations. Manufacturing scale and pharmacy dispensing infrastructure favor this mode, though first-pass hepatic metabolism limits bioavailability for certain compounds.
- Transdermal:Patch-based delivery bypasses gastrointestinal absorption and enables steady-state plasma concentrations ideal for elderly patients with polypharmacy risks. Formulary committees at US Medicare Advantage plans and Canadian provincial drug programs increasingly favor these formats for patients over 65.
- Injectable:Parenteral administration serves acute inpatient settings and perioperative sleep management.
- Inhalable:Nasal spray formulations target rapid sleep onset for specific clinical scenarios.
Oral formats maintain volume leadership. Transdermal systems are climbing the fastest as geriatric formularies expand.
End User:
Customer type segmentation reveals divergent treatment intensities and reimbursement pathways across age and care setting.
- Adults:Working-age patients aged 18-64 generate the majority of insomnia diagnoses tied to occupational stress, shift work, and anxiety comorbidities. Employer-sponsored health plans in the United States drive demand for both pharmacologic and digital therapeutic solutions in this cohort.
- Elderly:Patients over 65 face heightened fall risk and cognitive impairment from traditional hypnotics, prompting formulary restrictions and heightened monitoring. Medicare Part D plans and Canadian provincial drug programs apply prior authorization requirements that constrain benzodiazepine receptor agonist use.
- Pediatric:Children and adolescents receive insomnia diagnoses less frequently, with behavioral interventions preferred over pharmacotherapy.
- Healthcare Providers:Sleep medicine specialists, primary care physicians, and behavioral health practitioners constitute the prescriber base whose protocol preferences shape product uptake.
Adults hold installed capacity. Elderly segments are rotating up the share rankings.
Distribution Channel:
Supply concentration varies by channel control, with pharmacy benefit managers and health system formularies exerting divergent influence over product access.
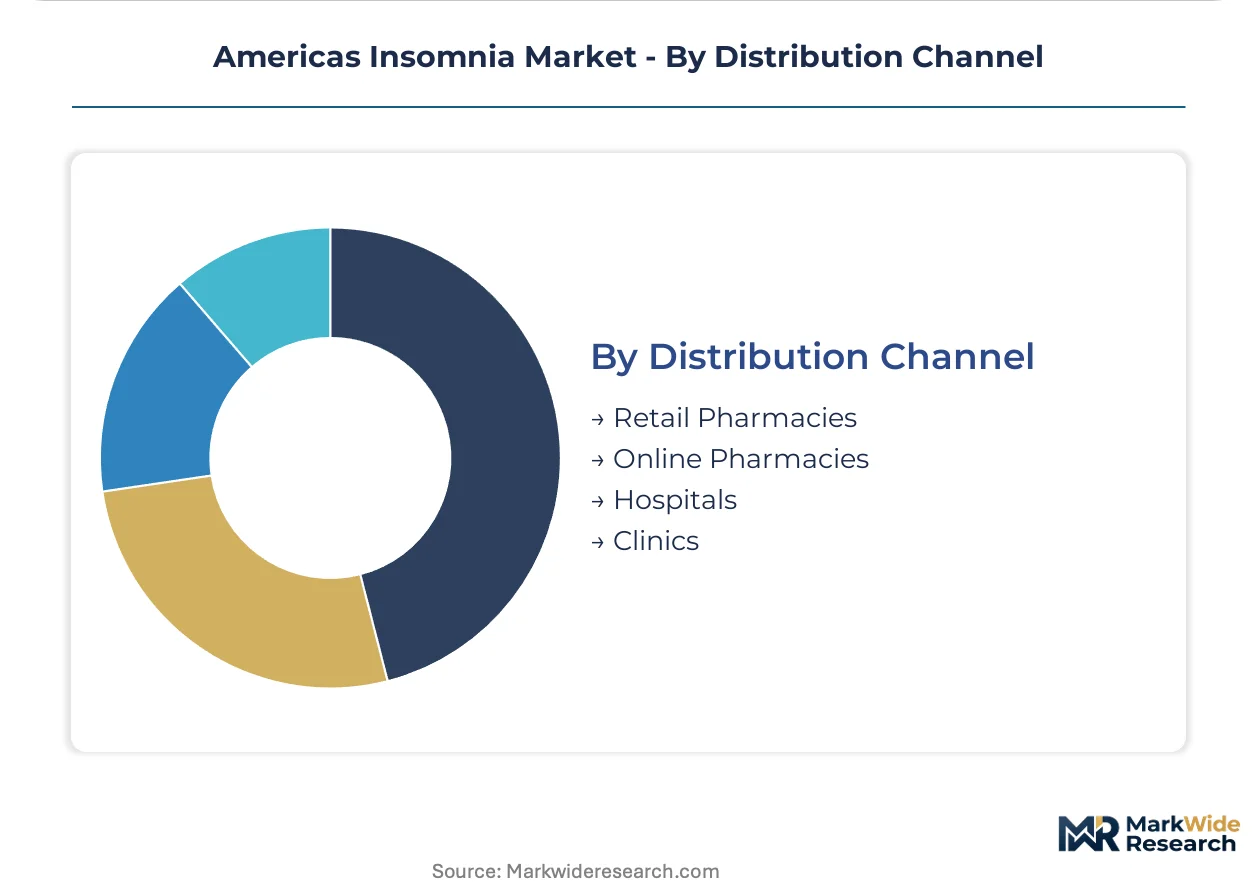
- Retail Pharmacies:Chain and independent pharmacies dispense the majority of prescription hypnotics and over-the-counter sleep aids. CVS Health, Walgreens, and Loblaw Companies Limited networks across the United States and Canada maintain category management agreements that determine shelf placement and generic substitution protocols.
- Online Pharmacies:Mail-order and digital-first dispensers capture 90-day supply volumes for maintenance insomnia medications. Amazon Pharmacy and Capsule have entered this space, though controlled substance regulations limit their addressable market.
- Hospitals:Inpatient formularies stock hypnotics for acute sleep disruption in surgical and critical care settings.
- Clinics:Sleep medicine centers and primary care practices with in-house dispensing capabilities bypass traditional pharmacy networks for certain therapeutic categories.
Retail pharmacies hold installed capacity. Online pharmacies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Americas. United States commercial payers absorb premium orexin antagonist pricing while Mexican and Brazilian patients face out-of-pocket constraints that favor generic benzodiazepine receptor agonists.
United States
Employer-sponsored health plans drive insomnia medication spend through pharmacy benefit managers. FDA DEA scheduling quotas constrain manufacturing capacity for Schedule IV hypnotics. Sleep medicine specialists concentrate in Boston, New York, and San Francisco metropolitan areas where academic medical centers anchor behavioral sleep medicine training programs.
Canada
Provincial drug programs apply prior authorization requirements that limit benzodiazepine receptor agonist use in elderly populations. Health Canada ICH-GCP frameworks govern clinical trial conduct for novel hypnotic mechanisms. Toronto and Vancouver house the majority of board-certified behavioral sleep medicine practitioners.
Brazil
Private health insurance expansion creates addressable market growth for insomnia diagnostics beyond the public Sistema Único de Saúde. ANVISA regulates pharmaceutical imports and local manufacturing licensing. São Paulo anchors sleep medicine specialist training and private clinic concentration in the Southeast region.
Mexico
Out-of-pocket payment dominates insomnia treatment access outside formal employment sectors with private insurance. COFEPRIS oversees pharmaceutical registration and bioequivalence requirements. Mexico City metropolitan area concentrates the limited supply of polysomnography-equipped sleep centers.
Argentina
Economic volatility compresses purchasing power for patented hypnotics and redirects demand toward OTC antihistamines. ANMAT regulates pharmaceutical quality and import licensing. Buenos Aires maintains the highest density of sleep medicine specialists relative to other Argentine provinces.
Americas Insomnia Market Vendor Landscape
Multinational pharmaceutical conglomerates and generic manufacturers split the market along patent-status lines. Structure consolidates around prescription medication development while fragmenting across over-the-counter and digital therapeutic delivery. Three archetypes dominate: primary-care-anchored innovators, cost-sensitive generic suppliers, and behavioral health platform operators. Competitive moves center on formulary placement negotiations and digital therapeutic FDA clearance acquisition.
Within the primary-care-anchored tier, Sanofi S.A. and Pfizer Inc. occupy positions reflecting established physician detailing infrastructure and historical hypnotic development pipelines. Takeda Pharmaceutical Company Ltd. represents the orexin antagonist specialization vector that has captured treatment-resistant insomnia segments seeking alternatives to GABA-A modulation.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Johnson & Johnson |
| AstraZeneca PLC |
| Merck & Co. |
| Takeda Pharmaceutical Company Ltd. |
| Novartis AG |
| Eli Lilly and Company |
| Others |
Supply Flow & Price Mechanics
Boston's concentration of academic medical centers and behavioral sleep medicine training programs anchors formulary negotiation power for orexin receptor antagonists across United States commercial payers. This geographic clustering of prescriber influence translates directly into pricing leverage for novel hypnotic mechanisms seeking premium reimbursement positioning against generic benzodiazepine receptor agonists.
Pricing Analysis
Aftermarket adherence monitoring and patient support services now drive lifetime value capture for insomnia therapeutics. Three-tier pricing structure across premium orexin antagonists, standard melatonin agonists, and economy generic hypnotics reflects DEA scheduling status and clinical differentiation. Pricing pressure stems from Medicare Part D prior authorization requirements that constrain benzodiazepine use in elderly populations. Employer-sponsored health plans demonstrate lowest price sensitivity for digital CBT-I platforms, while out-of-pocket Mexican patients face highest cost constraints.
Supply Chain Analysis
Contract manufacturing for active pharmaceutical ingredients concentrates among Indian and Chinese facilities serving generic hypnotic production, with United States-based facilities handling final formulation for controlled substances. Active pharmaceutical ingredients for GABA-A modulators and melatonin derivatives draw from chemical synthesis clusters in India and China, with packaging materials sourced domestically. Single-source vulnerability exists for orexin antagonist raw materials given limited qualified suppliers. Distribution runs through pharmacy benefit manager-controlled retail networks for prescription products, with direct-to-patient channels emerging for digital therapeutics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas insomnia market represents early-cycle expansion as employer health plans unbundle sleep management from general behavioral health contracts. This procurement fragmentation creates new vendor entry points independent of traditional pharmacy benefit manager gatekeepers.
For Market Incumbents: Insulate formulary position by deepening vertical integration into digital therapeutic platforms before FDA Software as a Medical Device designations mature. Acquire specialized CBT-I delivery capabilities to offset generic price erosion in oral hypnotic segments. Prioritize certification investment for transdermal manufacturing capacity serving Medicare Advantage geriatric formularies.
For New Entrants and Emerging Players: Brazil's private health insurance expansion offers whitespace for polysomnography diagnostics and sleep medicine specialist networks beyond Sistema Único de Saúde coverage. Mexico's out-of-pocket payment environment favors affordable OTC antihistamine alternatives and telehealth prescribing platforms bypassing traditional pharmacy networks. Target direct employer contracting for digital CBT-I solutions in self-insured Fortune 500 technology and financial services sectors.
For Investors and Strategic Acquirers: Long-term, this sits as a behavioral health platform consolidation play because sleep medicine specialist scarcity creates acquisition targets with captive prescriber relationships. Monitor FDA draft guidance finalization on prescription digital therapeutics as inflection signal for reimbursement coding clarity and venture-backed startup valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Therapeutic FDA Clearance | Secures prescription status and employer reimbursement for CBT-I platforms competing against pharmaceutical alternatives. |
| Transdermal Manufacturing Scale-Up | Captures Medicare Advantage formulary preference for elderly populations with polypharmacy risk profiles. |
| Latin American Diagnostic Expansion | Addresses underpenetrated Brazilian and Mexican markets as private insurance penetration accelerates. |
| Orexin Antagonist Pipeline Diversification | Builds treatment-resistant insomnia portfolio distinct from commoditized GABA-A modulator generics. |
| Telehealth Prescribing Infrastructure | Enables direct-to-patient distribution bypassing pharmacy benefit manager controlled-substance restrictions. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with sleep medicine specialists, formulary directors at pharmacy benefit managers, regulatory affairs leads, and digital health platform executives; and secondary validation through FDA approval databases, Health Canada ICH-GCP filings, ClinicalTrials.gov entries, and Medicare Part D spending reports. Bottom-up prescription volume modeling and top-down payer expenditure triangulation anchored market size estimation across the analysis window.
Forecast inputs included treatment line positioning, dosage form preference shifts, administration route adoption curves, patient age demographics, and regional regulatory cluster variations. CAGRs derived from segmented volume projections weighted by reimbursement pathway maturity. Industry-specific inputs incorporated DEA manufacturing quota trajectories for Schedule IV hypnotics and digital therapeutic FDA Software as a Medical Device designation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by orexin antagonist specialists or digital therapeutic pure-plays would shift outcomes beyond modeled ranges. Quarterly review of FDA digital therapeutics guidance updates, DEA quota announcements, and employer health plan procurement unbundling announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Hypoventilation Management Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Sleep Studies Market