
 Postpartum Health Supplements Market | 2026-2036
Postpartum Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Postpartum Health Supplements Market Intelligence
Market Context
Certified lactation consultants and perinatal nutrition specialists are reorganizing how new mothers access evidence-based supplementation, shifting recommendations from generic multivitamins toward targeted postnatal formulations. Nestlé S.A. leverages its pediatric nutrition heritage to anchor trust among hospital discharge planners, while Nordic Naturals specializes in omega-3 DHA products for lactating women. Abbott Laboratories extends its clinical nutrition credibility into postpartum channels through healthcare practitioner networks.
Technical Definition and Segment Structure
Postpartum health supplements constitute targeted nutritional formulations designed to replenish maternal micronutrient stores depleted during gestation and lactation, typically containing iron, choline, DHA, vitamin D, and B-complex compounds at dosages exceeding standard adult recommendations. These products serve the dual commercial purpose of supporting maternal recovery and ensuring breast milk nutritional adequacy for infant development. Vitamin and mineral combinations dominate current revenue pools due to established clinical validation and insurance-adjacent reimbursement pathways, while herbal supplements such as fenugreek and moringa represent the fastest-growing category as Ayurvedic and traditional Chinese medicine influences permeate Western wellness retail. Gummy formulations are capturing disproportionate growth among millennial and Gen Z mothers prioritizing palatability and convenience adherence.
Regulatory Framework and Outlook
The FDA's Current Good Manufacturing Practice regulations for dietary supplements and the FTC's substantiation requirements for health claims jointly determine market access thresholds for postpartum product entrants, with third-party USP verification increasingly serving as a de facto retail gatekeeper. The EU's EFSA health claims regulation and Novel Food catalog restrictions constrain how European marketers position postpartum botanical ingredients, creating divergent formulation strategies across Atlantic markets. Stakeholders must monitor whether postpartum-specific nutrient reference values emerge from national maternal health guidelines, as such standards would reshape competitive formulation targets and labeling requirements.
Market Dynamics
Medicaid maternal health expansions across multiple US states are reconfiguring how postpartum supplements reach new mothers, embedding these products into hospital discharge protocols and lactation consultant workflows.
Growth Catalysts
- Lactation Consultant Networks:Certified specialists in US hospital systems are standardizing targeted postnatal formulations over generic multivitamins, creating institutional pull-through demand.
- USP Verification Requirements:Third-party quality certification is becoming a de facto retail gatekeeper, elevating compliant manufacturers above commodity competitors in pharmacy and e-commerce channels.
- Ayurvedic Ingredient Migration:Fenugreek and moringa extracts from traditional medicine systems are capturing shelf space in Western wellness retail, expanding the addressable consumer base beyond conventional supplement users.
Market Restraints
- Algal DHA Supply Concentration:Marine omega-3 sourcing depends on limited cold-water fisheries and controlled-environment algae cultivation, exposing formulations to raw material volatility.
- EFSA Novel Food Restrictions:European marketers face constrained positioning for postpartum botanical ingredients, forcing divergent formulation strategies that raise compliance costs for multinational portfolios.
- Iron Formulation Bioavailability Limits:Ferrous salt variants cause gastrointestinal intolerance in significant user segments, capping adherence rates and repeat purchase velocity.
Strategic Opportunities
- Telehealth Lactation Platforms:Virtual consultation services are creating direct-to-consumer supplement recommendation pathways that bypass traditional retail markup structures.
- Subscription Compliance Models:Recurring delivery formats aligned with 12-week postpartum recovery windows address adherence drop-off through automated replenishment.
- Medicaid Formulary Inclusion:State-level maternal health benefit expansions present reimbursement-adjacent positioning opportunities for clinically validated formulations.
Industry Challenges
- Perinatal Nutrition Specialist Shortage:The limited pipeline of credentialed professionals capable of translating micronutrient science into consumer guidance constrains category education at point of care.
- CGMP Compliance Timelines:FDA Current Good Manufacturing Practice enforcement is extending facility qualification periods for new market entrants, delaying revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postpartum Health Supplements Market |
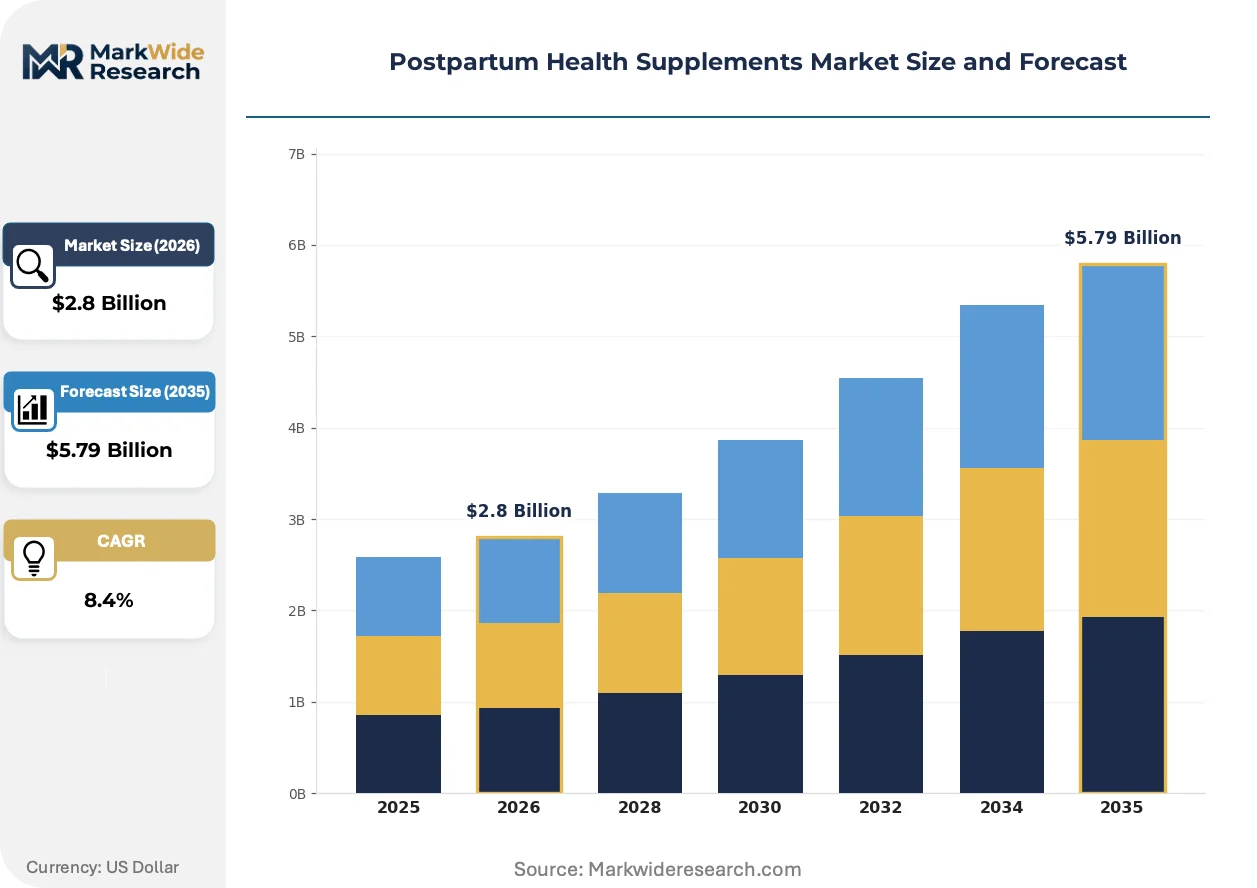
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Supplements, Protein Powders Formulation: Pills, Powders, Gummies, Liquids Distribution Channel: Online Retailers, Pharmacies, Health Stores, Supermarkets Target Audience: New Mothers, Expecting Mothers, Caregivers, Health Professionals |
| Companies Covered | New Chapter, Inc., Nature's Bounty Co., Nestlé S.A., Glanbia plc, Nordic Naturals, Abbott Laboratories, The Honest Company, Inc., Danone S.A., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postpartum Health Supplements Market Strategic Shifts & Innovations
Gummy delivery formats and personalized micronutrient profiling are actively fragmenting how postpartum supplements are formulated, positioned, and consumed across generational cohorts.
Personalized nutrition platforms using at-home micronutrient testing are decomposing the one-size-fits-all prenatal-to-postnatal transition model. Millennial and Gen Z mothers in direct-to-consumer channels are adopting these services faster than traditional retail buyers. This technology is decomposing brand loyalty toward legacy multivitamin architectures by enabling precise dosing adjustments based on individual depletion patterns.
EFSA's evolving health claims substantiation requirements for maternal nutrition are tightening evidentiary thresholds for botanical ingredient marketing. European formulators must now navigate Novel Food catalog restrictions alongside traditional supplement regulations. Postpartum herbal categories face the steepest compliance burden, with fenugreek and moringa positioning requiring reformulation for cross-border commercialization.
Hospital discharge planners are consolidating supplement recommendations around evidence-based protocols rather than patient self-selection. Lactation consultants in US health systems are displacing retail-driven purchasing with practitioner-guided regimens. This channel compression is most visible in states with expanded Medicaid maternal health benefits, where institutional procurement is replacing individual consumer decision-making.
Postpartum Health Supplements Market Segmentation
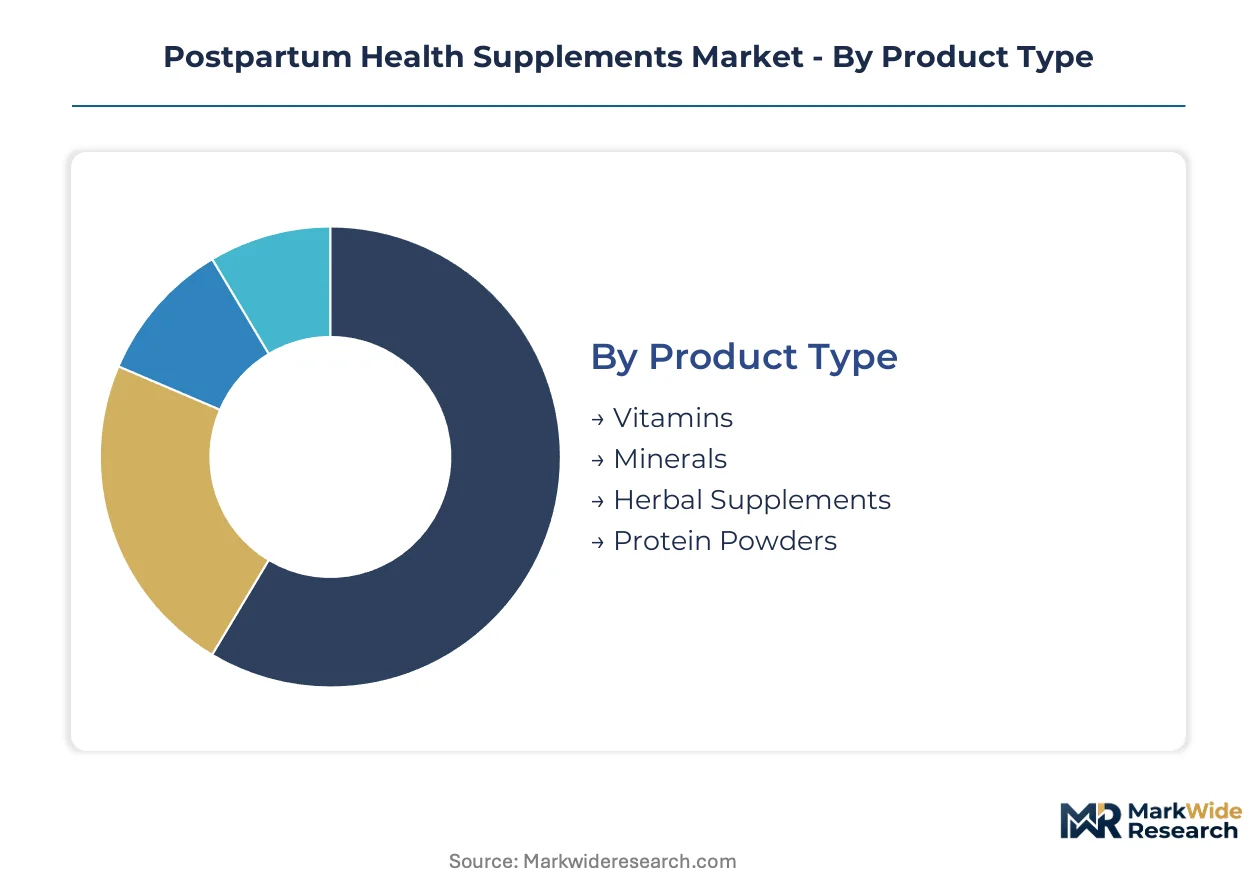
Postpartum supplement purchasing patterns fragment sharply across delivery format preferences and channel access points, with millennial mothers driving divergence from legacy multivitamin architectures. Formulation innovation and distribution pathway selection now determine competitive positioning more than brand heritage alone.
Product Type:
Premium margin pools concentrate in clinically validated micronutrient combinations that secure USP verification and lactation consultant endorsement.
- Vitamins:Targeted postnatal formulations containing DHA, choline, and B-complex compounds at elevated dosages address maternal depletion during lactation. Hospital discharge programs in the United States favor these products over generic alternatives, embedding them into institutional procurement workflows.
- Herbal Supplements:Fenugreek and moringa extracts from Ayurvedic and traditional Chinese medicine systems are capturing shelf space in wellness retail. European marketers face EFSA Novel Food catalog constraints that force reformulation for cross-border commercialization.
- Minerals:Iron and calcium variants support maternal recovery, though ferrous salt bioavailability limits adherence rates among sensitive users.
- Protein Powders:Lactation-supporting formulations with added galactagogues serve nursing mothers seeking convenient macronutrient supplementation.
The dominant share belongs to Vitamins, while Herbal Supplements are expanding most quickly as traditional medicine influences permeate Western markets.
Formulation:
Palatability-driven delivery formats command price premiums and improve compliance adherence among younger maternal cohorts.
- Gummies:Millennial and Gen Z mothers prioritize these chewable formats for convenience and taste masking, driving disproportionate growth in direct-to-consumer channels. Palatability advantages offset higher per-dose manufacturing costs.
- Pills:Traditional tablet and capsule formats dominate pharmacy and hospital procurement due to established stability profiles and lower unit economics. US Medicaid maternal health expansions reinforce institutional preference for these cost-controlled options.
- Powders:Flexible dosing formats appeal to mothers integrating supplements into smoothies or beverages, though portability constraints limit on-the-go usage.
- Liquids:Rapid absorption claims support positioning for mothers with digestive sensitivities, requiring refrigerated supply chains that constrain distribution reach.
Pills retain institutional dominance, yet Gummies are climbing the fastest as generational preferences reshape retail demand.
Distribution Channel:
Channel selection determines reimbursement proximity and education intensity at the point of purchase decision.
- Online Retailers:Subscription models and personalized nutrition platforms bypass traditional markup structures. Telehealth lactation services direct mothers to these channels with practitioner-validated recommendations.
- Pharmacies:USP-verified products concentrate here due to quality gatekeeping functions and insurance-adjacent positioning. Third-party certification elevates compliant manufacturers above commodity competitors.
- Health Stores:Ayurvedic and botanical ingredients find dedicated shelf space targeting wellness-oriented consumers outside conventional medical pathways.
- Supermarkets:Mass-market accessibility supports trial purchases, though limited staff education constrains conversion to regimen adherence.
Pharmacies anchor volume, while Online Retailers gain share fastest through subscription compliance models aligned with 12-week recovery windows.
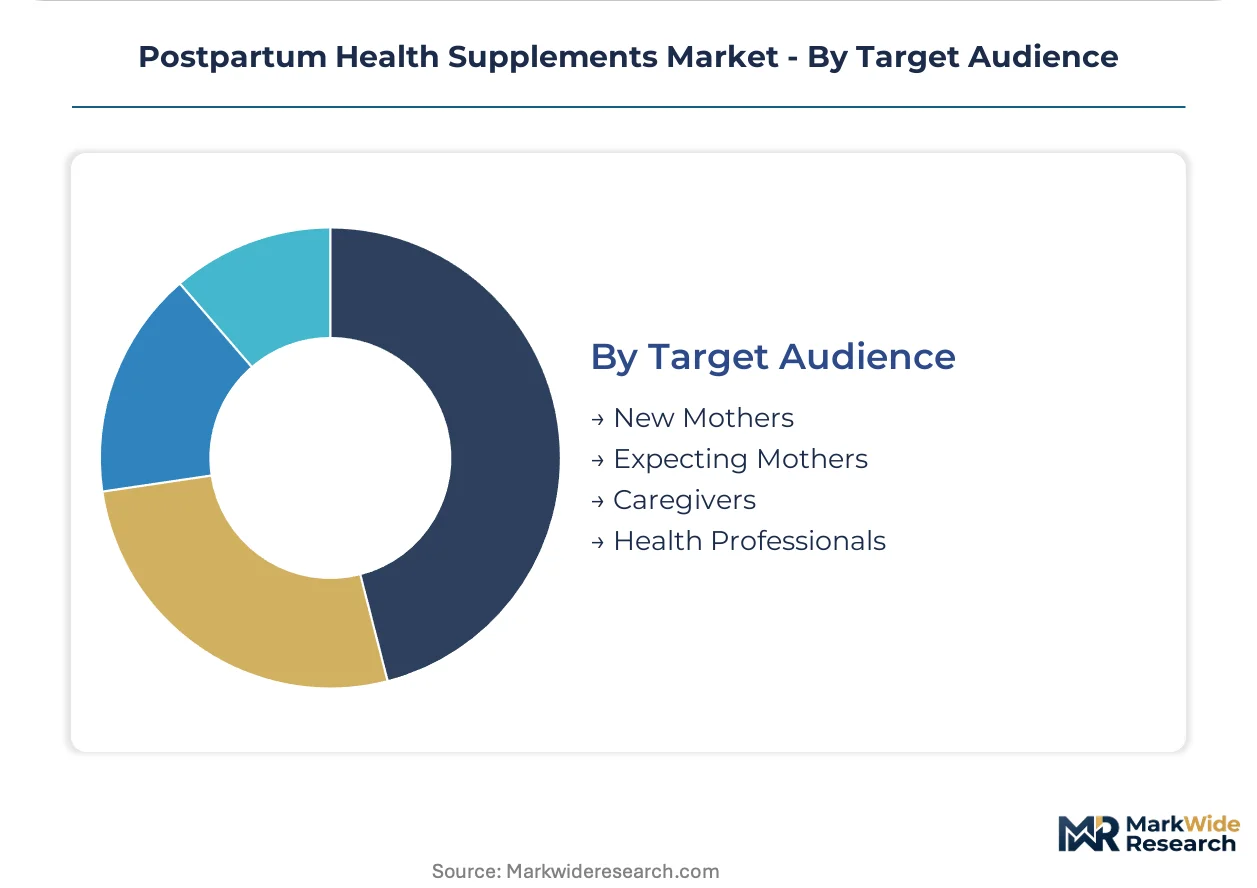
Target Audience:
Audience segmentation maps to information-seeking behavior and decision authority in supplement selection.
- New Mothers:First-time mothers in hospital discharge programs demonstrate highest adherence to lactation consultant protocols and evidence-based regimens.
- Health Professionals:Certified lactation consultants and perinatal nutrition specialists function as gatekeepers, standardizing recommendations across institutional settings.
- Expecting Mothers:Anticipatory purchasing begins in third trimester, with brand selection influenced by prenatal supplement continuity.
- Caregivers:Grandmothers and partners purchase on behalf of mothers, prioritizing accessibility and familiar retail formats over formulation sophistication.
New Mothers represent the core revenue base, while Health Professionals are extending influence fastest as institutional pathways displace self-directed purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European markets absorb compliance premiums from EFSA Novel Food catalog restrictions. Medicaid maternal health expansions across US states embed supplements into institutional procurement, whereas German and French formulators navigate stricter botanical substantiation requirements.
United States
Hospital discharge programs and lactation consultant networks drive institutional demand for USP-verified postnatal formulations. The FDA's Current Good Manufacturing Practice enforcement elevates quality benchmarks for perinatal products entering pharmacy channels. California and New York health systems pilot subscription-based supplement protocols through telehealth lactation platforms.
Germany
EFSA health claims substantiation requirements constrain how marketers position fenugreek and moringa extracts for postpartum consumers. The country's national pharmaceutical regulator maintains strict Novel Food catalog enforcement for Ayurvedic ingredient imports. Bavaria-based formulators concentrate on clinically validated micronutrient combinations targeting pharmacy distribution.
China
Domestic demand for postpartum recovery supplements draws from traditional Chinese medicine heritage and rising caesarean birth rates. The National Medical Products Administration oversees dietary supplement registration under dual-track regulatory pathways. Yangtze River Delta manufacturers scale algae-derived DHA cultivation to reduce marine omega-3 sourcing dependence.
United Kingdom
NHS maternal health guidelines increasingly reference targeted postnatal nutrition, though reimbursement remains limited to prescription iron and vitamin D. The Medicines and Healthcare products Regulatory Agency coordinates with trading standards on supplement quality enforcement. London-based direct-to-consumer brands leverage subscription models to capture millennial mother segments.
India
Ayurvedic postpartum traditions create natural demand migration toward fenugreek, shatavari, and ashwagandha formulations in organized retail. The Food Safety and Standards Authority of India regulates health claims under nutraceutical and functional food categories. Maharashtra and Gujarat manufacturing clusters supply both domestic consumption and export markets for herbal postpartum ingredients.
Postpartum Health Supplements Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the postpartum supplement value chain. The market structure consolidates around three tiers: multinational nutrition conglomerates with pediatric heritage, specialized omega-3 and botanical extract houses, and direct-to-consumer wellness startups leveraging subscription mechanics. Strategic moves concentrate on USP verification acquisition for retail gatekeeping access, and backward integration into algae DHA cultivation to secure raw material supply.
Within the multinational nutrition tier, Nestlé S.A. and Abbott Laboratories anchor institutional channel penetration through hospital discharge relationships and lactation consultant networks. Nordic Naturals occupies a specialist position in marine and algae-derived DHA for lactating women. Among European pharmaceutical-origin competitors, Bayer AG and Danone S.A. exemplify the convergence of clinical credibility with consumer wellness positioning.
| Leading Market Players |
|---|
| New Chapter, Inc. |
| Nature's Bounty Co. |
| Nestlé S.A. |
| Glanbia plc |
| Nordic Naturals |
| Abbott Laboratories |
| The Honest Company, Inc. |
| Danone S.A. |
| Bayer AG |
| Others |
Cost & Logistics Intelligence
Ninety-day algae cultivation cycles for DHA feedstock create inventory buffers that simultaneously constrain formulation flexibility and concentrate pricing power among vertically integrated suppliers. This lead-time architecture rewards manufacturers with captive cultivation facilities while exposing commodity assemblers to raw material volatility.
Pricing Analysis
The customization-premium spread between USP-verified practitioner-grade formulations and mass-market alternatives spans three quality tiers anchored by certification investment. Subscription models for 12-week postpartum recovery windows command recurring revenue premiums over transactional retail purchases. Price differentiation rests on third-party verification status and lactation consultant endorsement networks. Cost compression in economy-tier gummies is intensifying as contract manufacturers compete for supermarket shelf space, while Medicaid-adjacent institutional procurement demonstrates lowest price sensitivity due to reimbursement pathway insulation.
Supply Chain Analysis
Peruvian anchovy fishery quotas and Yangtze River Delta algae cultivation facilities constitute chokepoints that tether marine omega-3 availability to seasonal harvest variability and controlled-environment production capacity. Raw material sourcing draws from cold-water fisheries, controlled algae bioreactors, and Ayurvedic botanical extraction clusters in Maharashtra and Gujarat. Single-source vulnerability concentrates in algal DHA strains patented by limited cultivation houses. Distribution runs through pharmacy wholesale networks for institutional procurement and direct-to-consumer fulfillment centers for subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
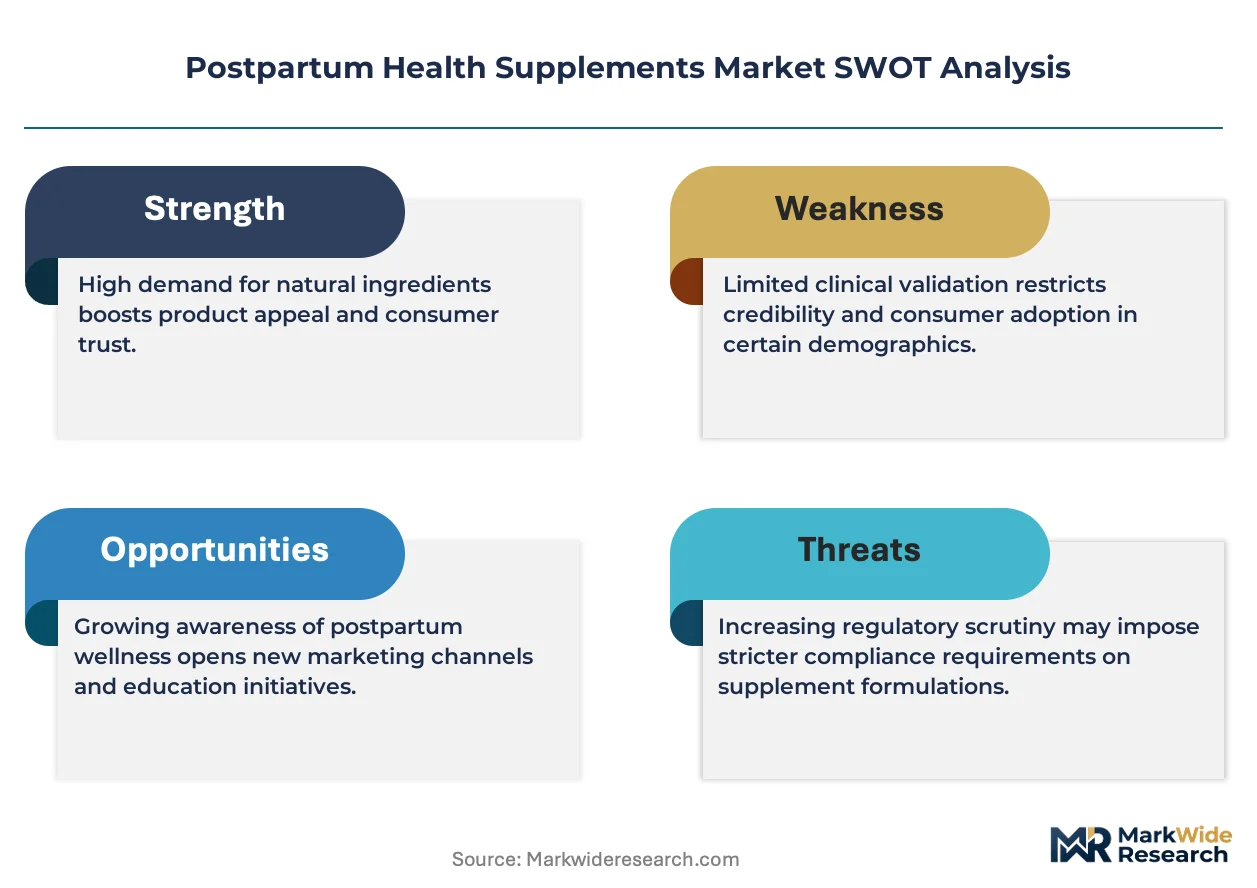
This market functions as a regulatory entrenchment moat where USP verification and FDA CGMP compliance create switching costs that institutional buyers cannot easily circumvent. Network effects among lactation consultant recommendation protocols further cement incumbent positioning.
For Market Incumbents: Secure backward integration into algae DHA cultivation to neutralize raw material volatility and patent-protected strain dependencies. Deepen channel control through exclusive formulary arrangements with Medicaid maternal health expansion states, insulating against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Lead with telehealth lactation platform partnerships that bypass pharmacy markup structures and capture millennial mother segments through personalized micronutrient profiling. Target white-space in Ayurvedic-botanical gummy formats where EFSA Novel Food restrictions have deterred European multinational entry. For Investors and Strategic Acquirers: Carve-out targets emerge from pediatric nutrition divisions of conglomerates seeking portfolio streamlining, particularly those with dormant USP verification assets and underutilized lactation consultant networks. Watch for Medicaid formulary inclusion decisions as inflection indicators for reimbursement-adjacent valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Acquisition | Third-party certification unlocks pharmacy channel access and institutional procurement workflows. |
| Algae DHA Cultivation Integration | Captive bioreactor capacity insulates formulations from Peruvian fishery quota volatility. |
| Telehealth Platform Partnership | Virtual lactation consultations create direct-to-consumer recommendation bypassing retail markup. |
| Medicaid Formulary Positioning | State-level maternal health benefit expansions enable reimbursement-adjacent volume capture. |
| Ayurvedic Botanical Line Extension | Fenugreek and moringa extracts access wellness retail channels outside conventional medical pathways. |
Research Approach
Desk research of FDA warning letters, USP verification databases, and state Medicaid formulary filings preceded structured interviews with certified lactation consultants, hospital discharge planners, perinatal nutrition specialists, and dietary supplement procurement managers. Secondary validation drew from FTC substantiation filings, clinical trial registries, and pharmacy distribution data. Bottom-up demand modeling triangulated against top-down market sizing across formulation types and channel structures.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics within each segmentation dimension. The analytical framework models product type, formulation format, distribution channel, and target audience cohort as independent forecast dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating Medicaid expansion timelines, USP verification adoption curves, and generational format preference shifts.
Forecasts assume regulatory continuity in FDA CGMP enforcement and EFSA Novel Food catalog restrictions; material policy shifts would require re-modeling. Specific risk factors include algal DHA supply disruption, iron formulation bioavailability litigation, and telehealth prescribing authority changes. Revision becomes warranted when USP verification adoption among top pharmacy chains crosses threshold penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Australia Nicotine Replacement Therapy Market
Dietary Supplements
Global Melatonin Market
Dietary Supplements
Herbal Tincture Market
Dietary Supplements
Eye Care Supplements Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Global Effervescent Tablet Market
Dietary Supplements
Global Nicotine Lozenges Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Pet Allergy Immune Supplements Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Nootropic Products Market