
 Home Sleep Apnea Testing Market | 2026-2036
Home Sleep Apnea Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Home Sleep Apnea Testing Market Foresight
China is reconfiguring regional manufacturing capacity for home diagnostic electronics, with Shenzhen and Suzhou clusters adding cleanroom assembly lines for wearable sleep monitors. ResMed leverages vertical integration across sensor fabrication and cloud analytics to sustain margin control in premium wearable monitors. Philips anchors European distribution through specialized sleep therapy channels, while Nihon Kohden dominates technical support networks across East Asian homecare settings.
Home sleep apnea testing encompasses portable and wearable diagnostic systems that measure respiratory effort, blood oxygen saturation, heart rhythm, and sleep architecture through integrated oximetry, actigraphy, and limited electroencephalography channels, typically recording five to seven physiological parameters over one to three nights to screen for obstructive sleep apnea outside clinical facilities. Portable devices incorporating finger-worn pulse oximeters and nasal pressure transducers capture the bulk of unit volume, while polysomnography devices command higher reimbursement tiers due to multi-channel EEG and limb movement detection capability. Telehealth services as a delivery mode are expanding fastest as remote physician interpretation of home-recorded data reduces specialist bottlenecks, though retail pharmacies still control the largest patient access point for initial device dispensing.
The FDA regulates home sleep apnea testing devices as Class II medical devices under 510(k) premarket notification pathways, with Software as a Medical Device guidance increasingly governing algorithm-based scoring systems that auto-interpret respiratory event indices. EMA's Medical Device Regulation enforces clinical evidence requirements for wireless data transmission security and diagnostic accuracy claims across European Economic Area markets. Stakeholders must monitor divergence between FDA and EMA validation standards for artificial intelligence-assisted sleep staging, as asynchronous regulatory timelines could fragment product development roadmaps and delay multi-region launches.
Market Dynamics
Telehealth reimbursement parity is compressing the traditional sleep lab channel, forcing diagnostic volume toward residential settings and algorithm-interpreted home recordings.
Growth Catalysts
- FDA Software as a Medical Device guidance:Accelerated validation pathways for AI-assisted respiratory event scoring reduce regulatory lag between algorithm development and clinical deployment.
- Japan METI telehealth infrastructure:Government-backed residential monitoring programs shift apnea diagnosis from hospital sleep labs to home-based settings among aging demographics.
- Cloud-native data architectures:Real-time synchronization between wearable sensors and remote physician dashboards enables asynchronous interpretation models that bypass specialist bottlenecks.
Market Restraints
- Sensor fabrication concentration:Cleanroom assembly capacity for pulse oximetry and pressure transducers clusters in Shenzhen and Suzhou, creating single-region supply vulnerability.
- EMA-FDA divergence on AI validation:Asynchronous regulatory timelines for machine learning-based sleep staging fragment product development roadmaps and delay multi-region launches.
- Polysomnography substitution pressure:Limited-channel portable monitors capture standard screening volume, compressing reimbursement tiers for multi-channel EEG systems.
Strategic Opportunities
- Retail pharmacy dispensing channels:Initial device access points outside clinical settings capture patient populations that bypass traditional sleep medicine referrals.
- Actigraphy-oximetry convergence:Integration of movement-based sleep architecture detection with oxygen saturation monitoring creates single-device screening alternatives.
- German remote patient monitoring expansion:Diagnostic sleep clinics in this market are scaling residential programs that outsource data interpretation to centralized cardiopulmonary specialists.
Industry Challenges
- Algorithm training data scarcity:Diverse phenotypic representation in respiratory event databases remains uneven, constraining generalization across demographic subgroups.
- Wireless transmission security certification:EMA Medical Device Regulation clinical evidence requirements for data integrity claims extend validation timelines for cloud-connected devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Sleep Apnea Testing Market |
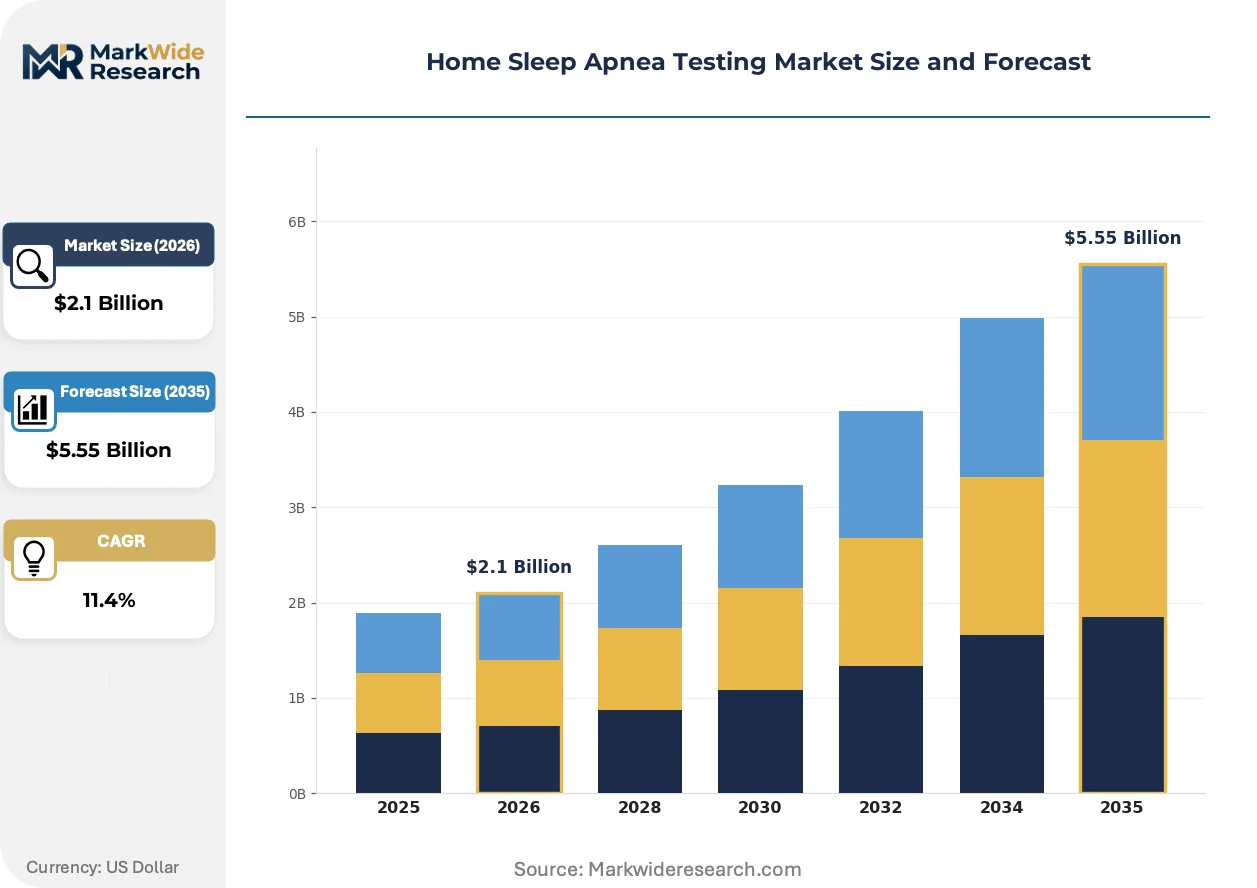
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Polysomnography Devices, Wearable Monitors, Home Monitoring Kits End User: Homecare Settings, Sleep Clinics, Hospitals, Diagnostic Labs Technology: Actigraphy, ECG Monitoring, Oximetry, Neurotechnology Delivery Mode: Direct-to-Consumer, Telehealth Services, Retail Pharmacies, Internet Sales |
| Companies Covered | Natus Medical, Compumedics, ResMed, SOMNOmedics, Nox Medical, Koninklijke Philips, ZOLL Itamar, CleveMed, Nihon Kohden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Sleep Apnea Testing Market Shifts & Advancements
Diagnostic methodology is bifurcating between minimalist screening tools and comprehensive multi-parameter systems, with reimbursement structures determining which modality dominates specific patient pathways.
Multi-channel polysomnography is migrating from hospital-based sleep laboratories to residential environments through portable EEG and limb movement detection systems. Sleep medicine practices in Germany and Japan are adopting these platforms for high-acuity cases that previously required overnight facility admission. This migration from institutional to residential settings compresses per-test infrastructure costs while maintaining diagnostic equivalence for complex apnea phenotypes.
EMA's Medical Device Regulation enforces explicit clinical evidence requirements for wireless data transmission security and diagnostic accuracy claims across European Economic Area markets. Manufacturers must document algorithm performance across diverse patient populations before CE marking approval. Sleep technology developers are responding by front-loading clinical validation studies to preempt regulatory scrutiny of machine learning-based respiratory event indices.
Patients are bypassing traditional specialist referral pathways through direct-to-consumer screening purchases at retail pharmacies and online channels. This channel disintermediation shifts initial device dispensing away from sleep medicine clinics toward consumer-accessible points of sale. Japan's METI-backed telehealth infrastructure accelerates this behavioral shift by enabling remote physician interpretation of home-recorded data without physical consultation.
Home Sleep Apnea Testing Market Segmentation
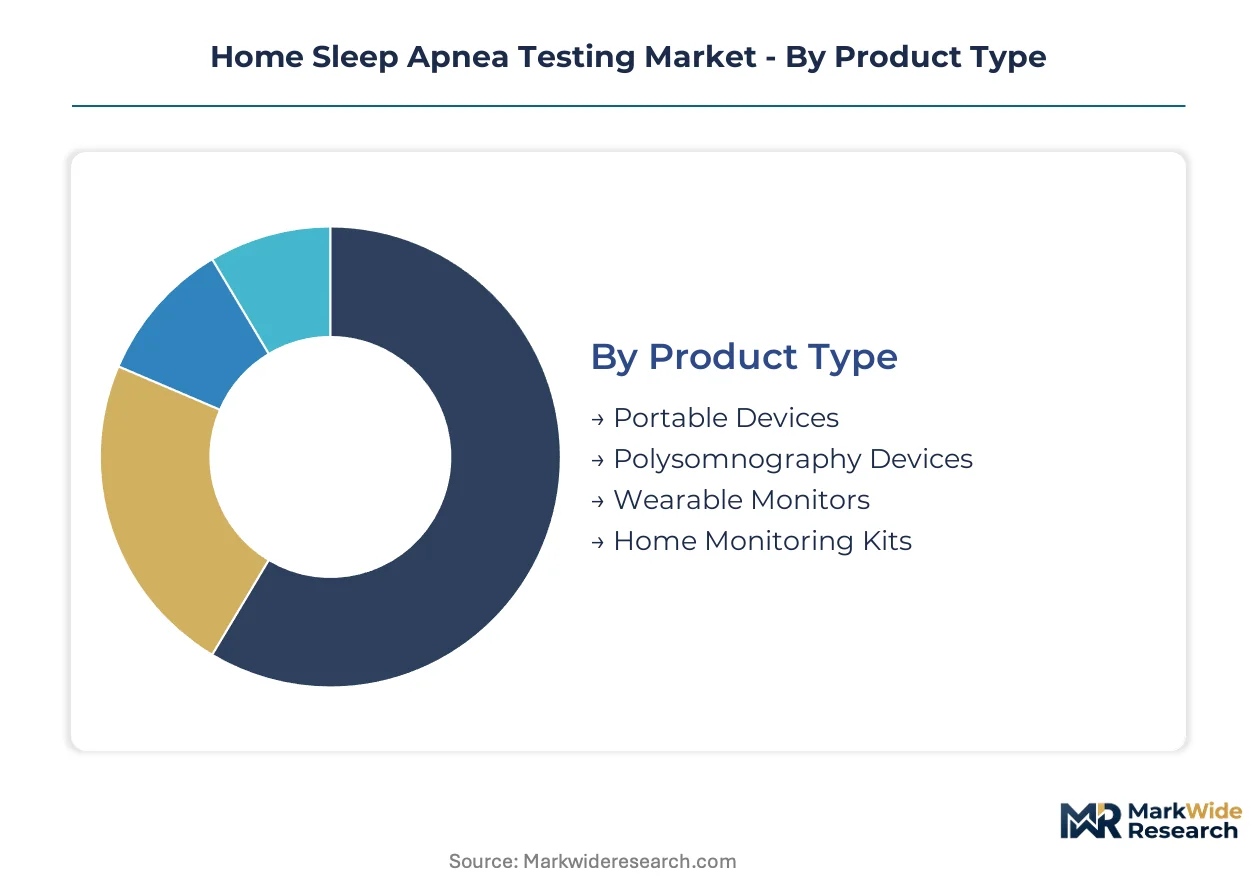
Home sleep apnea testing segments diverge sharply across device complexity, care setting, and patient access pathway. Reimbursement tiers and regulatory validation requirements determine which configurations dominate specific clinical workflows versus direct-to-consumer channels.
Product Type:
Mature portable configurations coexist with emerging multi-channel polysomnography systems migrating from hospital sleep labs.
- Portable Devices:Finger-worn pulse oximeters and nasal pressure transducers capture respiratory effort and oxygen saturation through limited-channel architectures. Demand concentrates in retail pharmacy dispensing channels across Japan and Germany where initial screening bypasses specialist referrals. Reimbursement parity for home-based testing accelerates volume against institutional polysomnography.
- Polysomnography Devices:Multi-channel EEG, limb movement detection, and expanded physiological monitoring replicate laboratory diagnostic equivalence in residential settings. Sleep clinics in Germany and Japan deploy these platforms for complex apnea phenotypes requiring sleep architecture differentiation. Higher reimbursement tiers sustain margin despite per-test infrastructure compression.
- Wearable Monitors:Wrist-worn or chest-strap form factors integrate accelerometry with photoplethysmography for continuous overnight recording.
- Home Monitoring Kits:Pre-configured disposable sensor assemblies with cloud synchronization simplify patient self-administration.
Portable devices retain volume leadership; polysomnography devices hold the steepest expansion curve as clinical-grade diagnostics migrate residential.
End User:
Cost tier stratification separates institutional reimbursement from out-of-pocket residential access.
- Homecare Settings:Patients administer testing independently with remote physician interpretation replacing physical consultation. METI-backed infrastructure in Japan and expanding German remote monitoring programs concentrate demand here. Telehealth reimbursement parity eliminates traditional sleep lab bottlenecks.
- Sleep Clinics:Specialized practices retain high-acuity cases requiring polysomnography-grade differentiation and manage therapy titration. Diagnostic sleep clinics in Germany scale residential programs while outsourcing interpretation to centralized cardiopulmonary specialists. Channel compression forces hybrid models blending facility oversight with home recording.
- Hospitals:Institutional sleep laboratories face volume displacement as residential alternatives achieve diagnostic equivalence.
- Diagnostic Labs:Centralized interpretation services process data streams from distributed home recording devices.
Homecare settings command the volume advantage; sleep clinics maintain the steepest capability upgrade trajectory.
Technology:
Application-specific sensing modalities converge toward multi-parameter integration.
- Oximetry:Photoplethysmography-based blood oxygen saturation monitoring provides the foundational screening parameter for apnea-hypopnea index calculation. Pulse oximetry sensor fabrication concentrates in Shenzhen and Suzhou manufacturing clusters. FDA 510(k) pathways govern finger-worn and wrist-worn implementations.
- Actigraphy:Accelerometer-derived movement patterns estimate sleep-wake states and sleep architecture without EEG electrode application. Integration with oximetry creates single-device screening alternatives capturing both respiratory events and sleep timing. Algorithm training data scarcity constrains generalization across demographic subgroups.
- ECG Monitoring:Single-lead or multi-lead cardiac rhythm detection identifies arrhythmias complicating sleep-disordered breathing.
- Neurotechnology:Limited-channel EEG acquisition enables sleep staging and arousal detection in portable form factors.
Oximetry retains volume leadership; actigraphy-oximetry convergence holds the steepest integration trajectory.
Delivery Mode:
Customer type fragmentation separates clinical referral pathways from consumer-direct access.
- Telehealth Services:Remote physician interpretation of home-recorded data enables asynchronous diagnostic workflows eliminating specialist appointment bottlenecks. Cloud-native data architectures synchronize wearable sensors with physician dashboards in real time. Japan's METI infrastructure and German diagnostic clinic expansions accelerate this channel.
- Retail Pharmacies:Physical dispensing locations capture patient populations bypassing traditional sleep medicine referrals through direct accessibility. Initial device access points outside clinical settings expand screening penetration among undiagnosed populations. Channel disintermediation shifts volume from sleep clinics toward consumer-accessible points of sale.
- Direct-to-Consumer:Online and retail purchases without physician involvement enable screening initiation outside reimbursement systems.
- Internet Sales:E-commerce platforms aggregate device distribution with variable clinical oversight integration.
Retail pharmacies retain volume leadership; telehealth services gain share fastest through reimbursement parity and infrastructure backing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleanroom assembly capacity for pulse oximetry sensors clusters in Shenzhen and Suzhou, while algorithm development and regulatory validation concentrate across three distinct jurisdictions. Demand generation patterns diverge sharply between aging-population markets and reimbursement-expansion territories.
United States
FDA Software as a Medical Device guidance accelerates validation pathways for AI-assisted respiratory event scoring. Sleep medicine practices in Florida and Texas expand remote patient monitoring programs as telehealth reimbursement parity eliminates specialist bottlenecks. Boston and San Francisco anchor algorithm development clusters for machine learning-based sleep staging systems.
Germany
Diagnostic sleep clinics in Bavaria and North Rhine-Westphalia scale residential monitoring programs that outsource data interpretation to centralized cardiopulmonary specialists. EMA Medical Device Regulation enforces clinical evidence requirements for wireless data transmission security across European Economic Area markets. Munich and Berlin host technical validation laboratories for cloud-connected polysomnography systems.
Japan
METI-backed telehealth infrastructure shifts apnea diagnosis from hospital sleep labs in Tokyo and Osaka to residential settings among aging demographics. PMDA oversight governs 510(k)-equivalent premarket notification pathways for wearable sleep monitors. Nagoya and Fukuoka concentrate manufacturing partnerships for disposable sensor assemblies with cloud synchronization.
China
NMPA regulatory timelines for Software as a Medical Device lag FDA and EMA trajectories, fragmenting product development roadmaps for multi-region launches. Shenzhen and Suzhou clusters add cleanroom assembly lines for wearable sleep monitors serving domestic and export markets. Shanghai anchors clinical validation partnerships for algorithm training across diverse phenotypic databases.
Home Sleep Apnea Testing Market Competitive Landscape
Vertically integrated device manufacturers and specialized diagnostic platform developers split the market across premium and volume tiers. Consolidation pressure intensifies as reimbursement compression favors scale economies in cloud analytics and sensor fabrication. Three archetypes dominate: diversified medical technology conglomerates with sleep therapy channels, focused polysomnography specialists with technical support networks, and emerging wearable-native platforms with direct-to-consumer distribution. Competitive moves concentrate on backward integration into pulse oximetry sensor fabrication and strategic partnerships with telehealth interpretation services.
Among diversified medical technology conglomerates, ResMed and Koninklijke Philips occupy positions spanning sensor fabrication through cloud analytics and European distribution channels. Nihon Kohden exemplifies the specialized diagnostic archetype with technical support network density across East Asian homecare settings. These three anchors represent distinct strategic postures: captive supply chain control, specialized sleep therapy channel leverage, and regional technical service infrastructure.
| Leading Market Players |
|---|
| Natus Medical |
| Compumedics |
| ResMed |
| SOMNOmedics |
| Nox Medical |
| Koninklijke Philips |
| ZOLL Itamar |
| CleveMed |
| Nihon Kohden |
| Others |
Supply & Pricing Matrix
Shenzhen and Suzhou manufacturing clusters control pulse oximetry sensor fabrication capacity, concentrating upstream supply power among vertically integrated device manufacturers who capture margin through captive production. This geographic concentration amplifies pricing leverage for ResMed and Philips while squeezing mid-tier competitors dependent on outsourced component sourcing.
Pricing Analysis
FDA 510(k) premarket notification pathways dictate the pricing tier structure across home sleep apnea testing devices, separating Class II-cleared multi-channel polysomnography systems from limited-channel portable monitors. Premium-mid-economy pricing differentiation rests on EEG channel count, algorithm sophistication, and cloud analytics bundling. Cost compression in portable segments is intensifying because retail pharmacy dispensing channels prioritize unit economics over clinical feature depth. Sleep clinics demonstrate the lowest price sensitivity, while direct-to-consumer purchasers drive standard-tier volume through online channels.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for wearable sleep monitor manufacturers. Cleanroom assembly capacity concentrates in Shenzhen, Suzhou, and Nagoya, drawing from photoplethysmography sensors, pressure transducers, and disposable adhesive electrodes. Single-region vulnerability in pulse oximetry chip fabrication threatens production continuity. Distribution runs through specialized sleep therapy channels in Europe, telehealth-integrated platforms in Japan, and retail pharmacy networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent device manufacturers face acute substitution pressure from algorithm-native entrants who bypass hardware margins through Software as a Medical Device pathways. Defense requires locking sensor fabrication capacity and securing telehealth interpretation partnerships before reimbursement parity fully commoditizes diagnostic hardware.
For Market Incumbents: Entrench through backward integration into photoplethysmography sensor production at Shenzhen facilities and exclusive cloud analytics partnerships with German diagnostic sleep clinics. Algorithm-native competitors threaten margin erosion through SaaS-only respiratory event scoring. Captive supply of pulse oximetry components and locked telehealth channel relationships form the critical defensive perimeter. For New Entrants and Emerging Players: Direct-to-consumer retail pharmacy channels in Japan represent the most penetrable entry point, bypassing entrenched hospital sleep lab relationships. White-space opportunity concentrates in actigraphy-oximetry convergence devices for undiagnosed aging populations. Go-to-market execution should anchor on METI-backed telehealth infrastructure integration rather than clinical sales force builds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized polysomnography platform developers with technical support network density across East Asian homecare settings. Long-term viability hinges on regulatory validation velocity across FDA, EMA, and PMDA jurisdictions. Watch algorithm training data diversity as the inflection signal for generalization capability and multi-region approval success.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Accelerated validation pathways compress time-to-revenue for AI-assisted respiratory scoring systems. |
| CE Marking Pathway under MDR | EMA clinical evidence requirements for wireless security govern European market access timelines. |
| Hospital System Partnership | German diagnostic sleep clinics outsource interpretation to centralized specialists, creating platform demand. |
| Software Companion Development | Cloud-native dashboards enable asynchronous physician review that bypasses specialist appointment bottlenecks. |
| Reimbursement Strategy | Telehealth parity in Japan and the United States shifts volume from facility-based to home-based testing. |
Research Methodology
A standing panel of sleep medicine clinicians, biomedical engineers at device manufacturers, GPO contracts managers, and telehealth platform operators provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, PMDA premarket notification databases, EMA Medical Device Regulation guidance documents, and hospital procurement contract disclosures. Bottom-up unit shipment estimates triangulated against top-down reimbursement expenditure analysis.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeled by device complexity tier, care setting, patient access pathway, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates. Forecast inputs incorporated METI telehealth infrastructure deployment schedules and EMA-FDA divergence timelines for AI validation.
Macroeconomic conditions sit as an overlay; deviation in telehealth reimbursement policy, trade tariff regimes, or semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions about regulatory approval velocity and algorithm performance generalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Americas Insomnia Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Asia Pacific Insomnia Market