
 Global Sleep Aids Market | 2026-2036
Global Sleep Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sleep Aids Market Foresight
Asset-light licensing and royalty-based partnerships is narrowing the competitive field for smaller entrants in the sleep aids sector. Pfizer Inc. leverages its established psychiatric drug infrastructure to sustain dominance in prescription hypnotics. ResMed Inc. anchors the device-assisted segment with continuous positive airway pressure systems and connected sleep diagnostics. Sanofi competes through over-the-counter brand strength in pharmacy retail channels across European and North American markets.
Sleep aids encompass pharmacological agents, mechanical devices, and behavioral interventions engineered to reduce sleep latency, prolong sleep duration, or improve sleep architecture through modulation of GABA receptors, melatonin pathways, or airway patency. Prescription hypnotics retain the largest revenue pool despite safety warnings, while melatonin supplements represent the fastest-expanding category driven by consumer preference for non-habit-forming alternatives. Online retailers capture growing volume as direct-to-consumer distribution bypasses traditional pharmacy gatekeepers, though pharmacy retail maintains higher margins on reimbursed prescription products.
The FDA maintains stringent REMS requirements for certain sedative-hypnotics, while the EMA's pharmacovigilance framework shapes product labeling and market withdrawal decisions across Europe. Japan's PMDA imposes distinct clinical trial requirements that delay entry for foreign melatonin brands, creating protected windows for domestic players like Eisai Co., Ltd. Stakeholders must monitor evolving digital therapeutics classifications as regulators determine whether app-based cognitive behavioral therapy for insomnia qualifies for reimbursement alongside pharmaceutical and device interventions.
Market Dynamics
The sleep aids sector is bifurcating sharply between pharmacological and non-pharmacological pathways as regulators impose divergent approval standards and reimbursement frameworks across major markets.
Growth Catalysts
- FDA REMS modifications:Streamlined risk evaluation and mitigation strategies for certain sedative-hypnotics are accelerating formulary access in managed care networks while maintaining safety surveillance.
- Aging demographics in Japan and Germany:Diagnosed insomnia and sleep apnea prevalence among populations over 65 is expanding addressable patient pools for prescription devices and supplements.
- Connected diagnostic platforms:Integration of polysomnography data with cloud-based analytics is enabling remote therapeutic monitoring and expanding reimbursable service models.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of eszopiclone and zolpidem precursors depends on a limited supplier base concentrated in Zhejiang Province, exposing manufacturers to supply disruptions.
- EMA pharmacovigilance stringency:Post-market surveillance requirements for hypnotics impose substantial compliance costs and label restriction risks that compress margins.
- Behavioral intervention substitution:Digital cognitive behavioral therapy for insomnia delivered via smartphone applications is displacing pharmaceutical first-line treatment in employer wellness programs.
Strategic Opportunities
- Underpenetrated Indian market:Low diagnosis rates for obstructive sleep apnea combined with expanding private insurance coverage create whitespace for home sleep testing devices.
- EU Green Deal alignment:Sustainable packaging mandates and carbon footprint disclosure requirements favor suppliers with certified environmental management systems in pharmacy retail channels.
- Convergence of melatonin and precision nutrition:Formulations combining circadian rhythm modulation with microbiome-targeting ingredients are opening premium positioning in direct-to-consumer channels.
Industry Challenges
- Clinical trial recruitment bottlenecks:Sleep disorder studies require extended washout periods and specialized facilities, elongating development timelines and inflating per-patient costs.
- Legacy device integration friction:CPAP manufacturers face technical complexity connecting new cloud-enabled platforms with installed base hardware that lacks standardized data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sleep Aids Market |
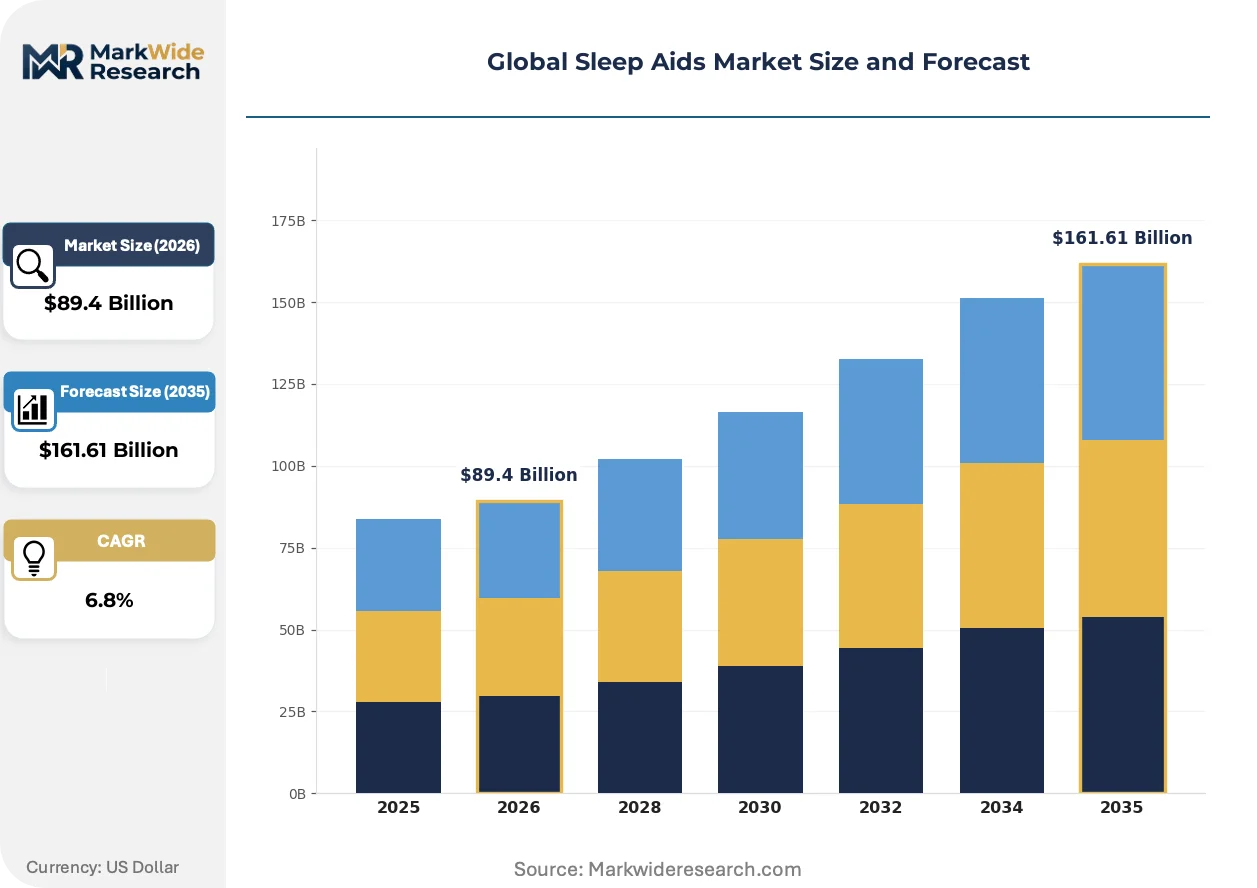
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $161.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Melatonin Supplements, Prescription Hypnotics, OTC Sleep Aids, Herbal Remedies, Weighted Blankets Therapy Area: Insomnia, Circadian Rhythm Disorders, Parasomnias, Restless Leg Syndrome, Sleep Apnea End User: Sleep Clinics, Pharmacies, Wellness Centers, Online Retailers, Home Healthcare Providers Distribution Channel: Pharmacy Retail, Online E-commerce, Specialty Stores, Healthcare Providers, Direct-to-Consumer |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline plc, ResMed Inc., Koninklijke Philips N.V., Johnson & Johnson, Sanofi, AstraZeneca, Eisai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sleep Aids Market Shifts & Advancements
Digital therapeutics and biometric monitoring are compressing the traditional boundary between diagnosis and treatment, forcing established players to reconfigure service delivery models around continuous patient engagement rather than discrete product transactions.
Closed-loop neurostimulation systems that detect sleep-stage transitions and deliver targeted acoustic or electrical intervention are collapsing the distinction between passive monitoring and active therapy. Sleep clinics in the United States and Switzerland are piloting these platforms for chronic insomnia patients who have failed pharmacological treatment. The technology is compressing revenue capture from device sales into subscription-based outcomes contracts that tie payment to objective sleep metric improvements.
REACH restrictions on certain solvent residues in pharmaceutical manufacturing are forcing reformulation of extended-release hypnotic coatings across European production facilities. The industrial consequence is accelerated migration to aqueous-based coating technologies that require capital retrofitting but eliminate regulatory exposure. Generic manufacturers with operations in Germany and Ireland are responding fastest, securing first-mover advantage in EMA abbreviated new drug application pathways.
Direct purchasing by large self-insured employers is disintermediating traditional pharmacy benefit managers for behavioral sleep interventions. Fortune 500 companies with headquarters in California and Texas are contracting directly with digital therapeutic platforms to bundle cognitive behavioral therapy with biometric tracking. This channel shift is most visible in technology and financial services verticals where employee wellness budgets exceed specialty pharmacy allocations.
Global Sleep Aids Market Segmentation
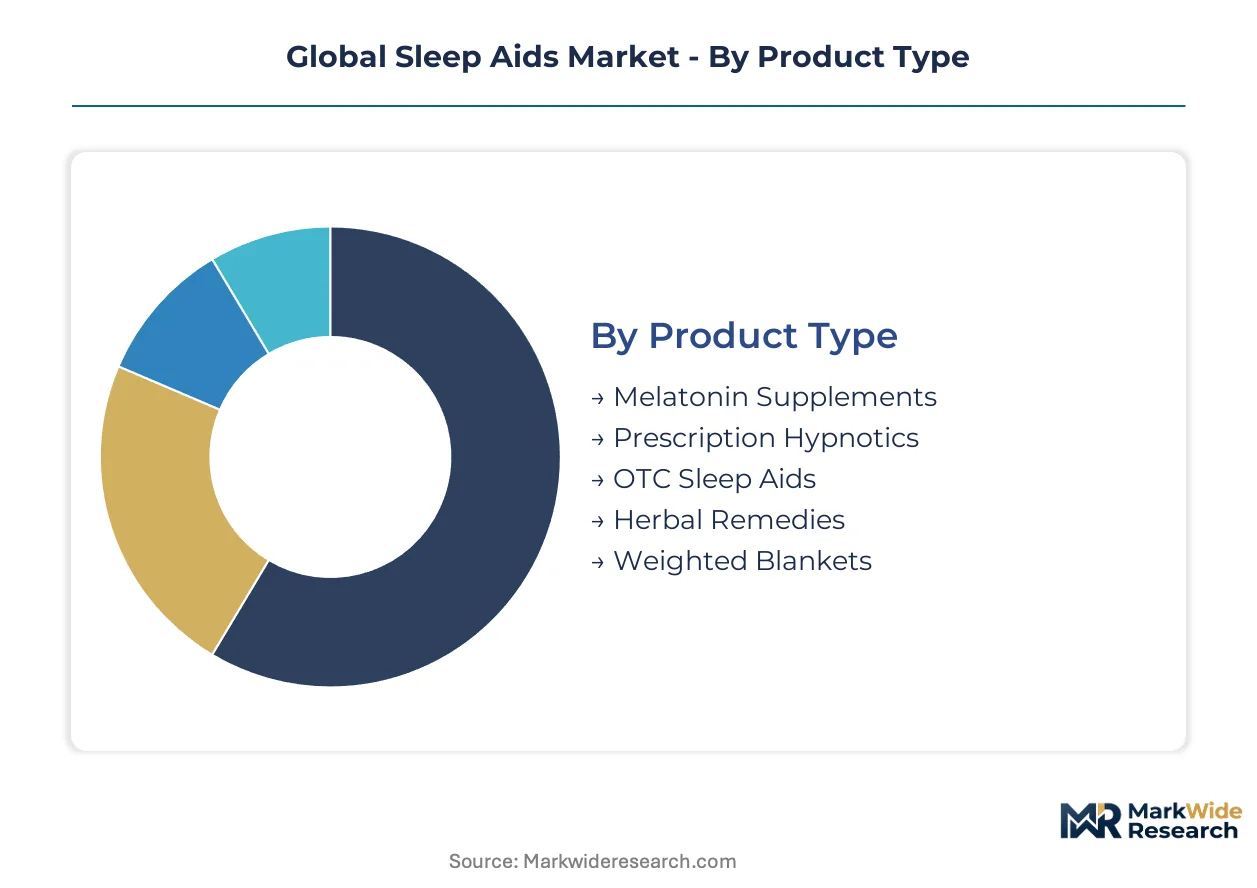
Sleep aids span pharmacological, mechanical, and behavioral modalities with divergent margin profiles and regulatory pathways. Understanding segment turnover velocity illuminates where capital efficiency concentrates versus where patient acquisition costs erode returns.
Product Type:
Inventory velocity varies dramatically across this category, with consumable supplements turning monthly while durable weighted blankets cycle annually.
- Prescription Hypnotics:GABA-A receptor modulators including eszopiclone and zolpidem derivatives carry REMS-mandated distribution controls and 30-day dispensing limits. Managed care formularies in the United States and Germany concentrate demand while safety surveillance requirements compress prescriber willingness.
- Melatonin Supplements:Synthetic and pineal-derived formulations targeting MT1/MT2 receptors circulate through direct-to-consumer channels with minimal regulatory friction. Japan's PMDA maintains distinct purity standards that delay foreign entry, protecting domestic manufacturers.
- OTC Sleep Aids:Antihistamine-based formulations dominate pharmacy retail shelves with quarterly promotional cycles driving volume.
- Herbal Remedies:Valerian root and passionflower extracts compete on sustainability credentials in European pharmacy channels.
- Weighted Blankets:Deep pressure stimulation devices require minimal regulatory clearance but face higher return rates due to subjective efficacy.
Prescription hypnotics dominate installed base. Melatonin supplements are where expansion concentrates.
Therapy Area:
Reimbursement intensity and diagnostic code specificity separate high-margin intervention targets from self-pay wellness categories.
- Sleep Apnea:Obstructive and central variants drive durable medical equipment prescriptions with home sleep testing expanding addressable diagnosis. ResMed and Philips Respironics compete on cloud-connected CPAP platforms with Medicare and private payers mandating compliance data for continued reimbursement.
- Insomnia:Chronic and acute presentations span pharmacological first-line treatment and emerging digital therapeutic substitutes. Employer wellness programs in California and Texas are displacing pharmaceutical spend with app-based cognitive behavioral therapy contracts.
- Circadian Rhythm Disorders:Shift work and delayed sleep phase conditions concentrate demand among transportation and healthcare worker populations.
- Restless Leg Syndrome:Dopaminergic and alpha-2-delta ligand prescriptions face generic erosion in mature markets.
- Parasomnias:REM behavior disorder and sleepwalking interventions remain niche with limited approved pharmacological options.
Sleep apnea captures the steepest expansion trajectory. Insomnia maintains the broadest addressable patient pool.
End User:
Channel control and patient data ownership differentiate vertically integrated service models from transactional product vendors.
- Sleep Clinics:Polysomnography and home sleep testing facilities in the United States and Switzerland pilot closed-loop neurostimulation subscriptions. Outcomes-based contracting ties payment to objective sleep metric improvements rather than device shipment.
- Online Retailers:Amazon and specialized platforms bypass pharmacy gatekeepers with melatonin and herbal supplement direct distribution. California-headquartered technology employers contract directly for bundled behavioral interventions.
- Pharmacies:Community and chain retail maintain higher margins on reimbursed prescription hypnotics despite volume migration.
- Wellness Centers:Spa and hospitality-integrated sleep programs in Germany emphasize non-pharmacological intervention adoption.
- Home Healthcare Providers:Durable medical equipment suppliers manage CPAP compliance monitoring and resupply logistics.
Pharmacies dominate installed base. Online retailers are where expansion concentrates.
Distribution Channel:
Margin capture and regulatory exposure separate controlled-substance pathways from supplement commerce.
- Pharmacy Retail:Brick-and-mortar chains in Germany and Japan maintain formulary influence and pharmacist counseling reimbursement. EMA pharmacovigilance requirements shape hypnotic stocking decisions.
- Direct-to-Consumer:Subscription models for melatonin and precision nutrition combinations bypass wholesale markups. EU Green Deal packaging mandates favor certified environmental management systems.
- Online E-commerce:Platform algorithms and review systems concentrate discovery for unregulated supplement categories.
- Specialty Stores:Sleep-focused retail in urban Japan clusters near diagnostic centers.
- Healthcare Providers:Hospital discharge and specialist prescribing maintains prescription hypnotic volume.
Pharmacy retail dominates installed base. Direct-to-consumer is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and self-insured employers in the United States, Germany, and Japan concentrate procurement authority for prescription hypnotics and connected diagnostic platforms. Aging demographics and diagnosed sleep disorder prevalence in these markets expand addressable patient pools fastest.
United States
FDA REMS requirements for sedative-hypnotics shape distribution controls and 30-day dispensing limits across managed care networks. Medicare mandates compliance data for CPAP reimbursement, accelerating cloud-connected platform adoption. Sleep clinics in California and Texas pilot closed-loop neurostimulation subscriptions tied to objective sleep metric outcomes.
Germany
EMA pharmacovigilance frameworks impose post-market surveillance costs that compress margins on hypnotic formulations. REACH restrictions on solvent residues force aqueous-based coating retrofits at production facilities in Hesse and North Rhine-Westphalia. Pharmacy retail chains maintain formulary influence through pharmacist counseling reimbursement.
Japan
PMDA clinical trial requirements delay foreign melatonin entry, protecting domestic manufacturers like Eisai Co., Ltd. Diagnosed insomnia prevalence among populations over 65 expands device and supplement demand. Specialty retail clusters near diagnostic centers in Tokyo and Osaka concentrate sleep-focused commerce.
India
Low obstructive sleep apnea diagnosis rates combined with expanding private insurance coverage create whitespace for home sleep testing devices. CDSCO regulatory pathways for medical devices streamline faster than pharmaceutical approvals. Manufacturing clusters in Maharashtra and Karnataka assemble CPAP components for regional distribution.
Switzerland
Swissmedic oversight of digital therapeutics classifications determines reimbursement eligibility for app-based cognitive behavioral therapy. Sleep clinics in Zurich and Geneva pilot subscription-based outcomes contracts for chronic insomnia patients. Precision nutrition convergence with circadian modulation attracts premium positioning in direct-to-consumer channels.
Global Sleep Aids Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin profiles and regulatory exposure levels. The sector structures around three tiers: multinational pharmaceutical conglomerates with psychiatric drug infrastructure, device manufacturers with cloud-connected diagnostic platforms, and supplement specialists with direct-to-consumer distribution. Consolidation concentrates among prescription hypnotic and CPAP device segments while melatonin and herbal categories fragment. Dominant competitive moves include strategic licensing partnerships and vertical integration into diagnostic service delivery.
Within the pharmaceutical archetype, Pfizer Inc. and Merck & Co., Inc. occupy positions sustained by established psychiatric drug infrastructure and managed care formulary relationships. ResMed Inc. anchors the device-assisted segment, exemplifying the convergence of hardware manufacturing with cloud-based therapeutic monitoring. Sanofi represents over-the-counter brand strength across European and North American pharmacy retail channels. Eisai Co., Ltd. sits within a protected competitive window created by Japan's distinct regulatory requirements for melatonin purity standards.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| ResMed Inc. |
| Koninklijke Philips N.V. |
| Johnson & Johnson |
| Sanofi |
| AstraZeneca |
| Eisai Co., Ltd. |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight rate volatility transmits directly into melatonin supplement landed costs, compressing margins for European direct-to-consumer brands while amplifying price differentiation between aqueous-coated domestic hypnotics and solvent-dependent imports. This logistics chokepoint concentrates pricing power among generic manufacturers with German and Irish production facilities who have completed REACH-mandated coating retrofits.
Pricing Analysis
Cost-plus contracts with API suppliers index to solvent feedstock benchmarks, embedding commodity volatility into hypnotic manufacturing economics. Three-tier pricing structure across premium REMS-controlled formulations, standard generic hypnotics, and economy antihistamine sleep aids separates insured prescription channels from self-pay supplement commerce. Pricing pressure stems from employer wellness programs substituting digital CBT-I subscriptions for pharmaceutical first-line treatment. Hospital procurement committees exhibit highest price sensitivity; sleep clinics piloting closed-loop neurostimulation show lowest sensitivity due to outcomes-based contracting models.
Supply Chain Analysis
Upstream feedstock concentration for eszopiclone and zolpidem precursors centers on Zhejiang Province manufacturing clusters, with secondary synthesis capacity in India and Germany. Active pharmaceutical ingredient production draws from specialized solvent suppliers, melatonin fermentation substrates, and aqueous coating polymer feedstocks. Single-source vulnerability in Zhejiang precursor synthesis exposes manufacturers to regional environmental enforcement actions. Distribution runs through pharmacy retail chains for controlled substances, direct-to-consumer platforms for supplements, and hospital discharge for acute insomnia prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—FDA REMS distribution controls and Japan's PMDA purity standards—creates durable incumbent protection against commoditization.
For Market Incumbents: Harden formulary position through backward integration into diagnostic service delivery, converting ResMed-style device relationships into continuous patient engagement platforms. Expand cloud-connected CPAP compliance monitoring to capture resupply logistics. Counter digital therapeutic substitution by embedding pharmacological protocols within employer wellness program RFPs.
For New Entrants and Emerging Players: India's sub-5% obstructive sleep apnea diagnosis rate offers whitespace for home sleep testing devices with private insurance contracting. Target CDSCO-registered medical device pathways ahead of pharmaceutical approvals. Pursue white-label manufacturing for European melatonin brands blocked by PMDA clinical trial requirements.
For Investors and Strategic Acquirers: Device manufacturers with FDA-cleared diagnostic platforms and installed base cloud connectivity represent the priority acquisition archetype. Long-term viability hinges on convergence toward subscription-based outcomes contracting rather than transactional hardware sales. Watch for Swissmedic reimbursement determinations on app-based CBT-I as inflection signal for digital therapeutic valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | CMS compliance data mandates for CPAP reimbursement accelerate cloud platform adoption among Medicare suppliers. |
| Regulatory Approval Pathway | EMA aqueous coating retrofits at German facilities secure first-mover advantage in abbreviated new drug applications. |
| Product Launch | Precision nutrition melatonin combinations with microbiome targeting capture premium positioning in California employer channels. |
| Strategic Partnership | Licensing agreements with Japanese domestic manufacturers bypass PMDA clinical trial barriers for foreign entrants. |
| Platform Integration | Closed-loop neurostimulation subscriptions tie payment to polysomnography metrics, collapsing diagnosis-treatment boundaries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA REMS documentation, EMA pharmacovigilance databases, and PMDA submission records, supplemented by hospital procurement database analysis and GPO contract review. Interviews with sleep clinic medical directors, formulary directors at managed care organizations, CPAP compliance monitoring specialists, and direct-to-consumer supplement brand managers inform qualitative assessments. Bottom-up patient population modeling triangulates against top-down pharmaceutical and device manufacturer revenue attribution.
Forecast inputs incorporate therapy area segmentation across sleep apnea, insomnia, circadian rhythm disorders, and restless leg syndrome; product type splits between prescription hypnotics, melatonin supplements, OTC antihistamines, and connected diagnostic devices; and regional regulatory cluster differentiation. CAGRs derive from log-linear trend fitting across historical volume data and elasticity-adjusted price projections. Modeled inputs include aging demographic curves, employer wellness program penetration rates, and digital therapeutic reimbursement determinations across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native digital therapeutic platforms or precision nutrition convergence players would shift outcomes beyond projected ranges. Cross-checking against CMS Medicare Part D formulary placement data and Swissmedic digital classification rulings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Sleep Movement Disorders Market