
 Parasomnia Treatment Market | 2026-2036
Parasomnia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Parasomnia Treatment Market Analytics
Specialty pharmacy distribution for parasomnia therapeutics is fragmenting as digital health platforms and direct-to-patient channels gain authorization. Pfizer Inc. leverages its established CNS portfolio to sustain wholesale relationships with hospital sleep centers. Jazz Pharmaceuticals plc differentiates through its orphan-drug expertise in narcolepsy-adjacent indications. Eisai Co., Ltd. anchors its position in Asia-Pacific markets through regulatory partnerships with national health technology assessment bodies.
Parasomnia treatment encompasses pharmacological interventions, behavioral modification protocols, and mechanical devices targeting abnormal sleep behaviors such as REM sleep behavior disorder, sleepwalking, and night terrors; standard formulations include benzodiazepine receptor agonists, melatonin analogs, and custom-fabricated mandibular advancement devices with titratable mechanisms. Medications occupy the largest revenue pool due to chronic prescribing patterns for persistent cases, while devices represent the fastest-expanding segment as home diagnostics replace polysomnography referrals. Online platforms within delivery mode are capturing margin previously held by in-hospital consultations, though telehealth reimbursement parity varies by jurisdiction.
The FDA regulates pharmacological parasomnia treatments through its Center for Drug Evaluation and Research, while the EPA monitors volatile organic compound emissions from device manufacturing facilities; CE marking under the EU Medical Device Regulation governs European market access for therapeutic appliances. Stakeholders must monitor evolving digital therapeutics classification at the FDA and corresponding software-as-medical-device determinations by European notified bodies. Payers and providers face decisions on coverage thresholds as at-home monitoring data quality approaches laboratory standards.
Market Dynamics
FDA clearance pathways for wearable diagnostic devices are compressing product development timelines from multi-year clinical validation cycles to accelerated 510(k) determinations, forcing incumbent pharmaceutical firms to recalibrate their device partnership strategies.
Growth Catalysts
- Home-based polysomnography alternatives:Wearable electroencephalography systems are capturing diagnostic data previously requiring overnight sleep center admissions, expanding addressable patient pools in rural catchment areas.
- Germany's integrated care pathways:Specialized sleep centers in Bavaria and Baden-Württemberg combine cognitive behavioral protocols with pharmacotherapy, creating template reimbursement models adopted by statutory health insurers.
- Digital therapeutics classification:FDA's evolving software-as-medical-device determinations are clarifying regulatory boundaries for prescription digital interventions targeting REM sleep behavior disorder.
Market Restraints
- Polysomnography equipment concentration:Diagnostic device manufacturing clusters in Massachusetts and Minnesota create supply vulnerability for electrode arrays and amplifier systems.
- Melatonin analog synthesis complexity:Precursor chemical sourcing for ramelteon and tasimelteon depends on contract manufacturers in Zhejiang province, exposing formulations to API cost volatility.
- CE marking friction under MDR:European notified bodies face backlogs for mandibular advancement device certifications, delaying market entry for custom-fabricated oral appliances.
Strategic Opportunities
- Direct-to-patient channel authorization:Digital health platforms in California and Texas are securing pharmacy benefit manager contracts for chronic parasomnia medication fulfillment, bypassing traditional wholesale distribution.
- Telehealth reimbursement parity:State-level Medicaid expansions in Illinois and Colorado now cover remote cognitive behavioral therapy for insomnia, creating precedent for parasomnia-adjacent coverage.
- Artificial intelligence and polysomnography convergence:Automated sleep stage scoring algorithms are reducing technician labor costs for diagnostic facilities in Ontario and British Columbia.
Industry Challenges
- Somnology technician certification bottlenecks:American Board of Sleep Medicine examination backlogs extend hiring timelines for polysomnography interpretation services.
- Legacy electronic health record integration:Sleep center workflows require custom API development to incorporate wearable-derived sleep architecture data into Epic and Cerner systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parasomnia Treatment Market |
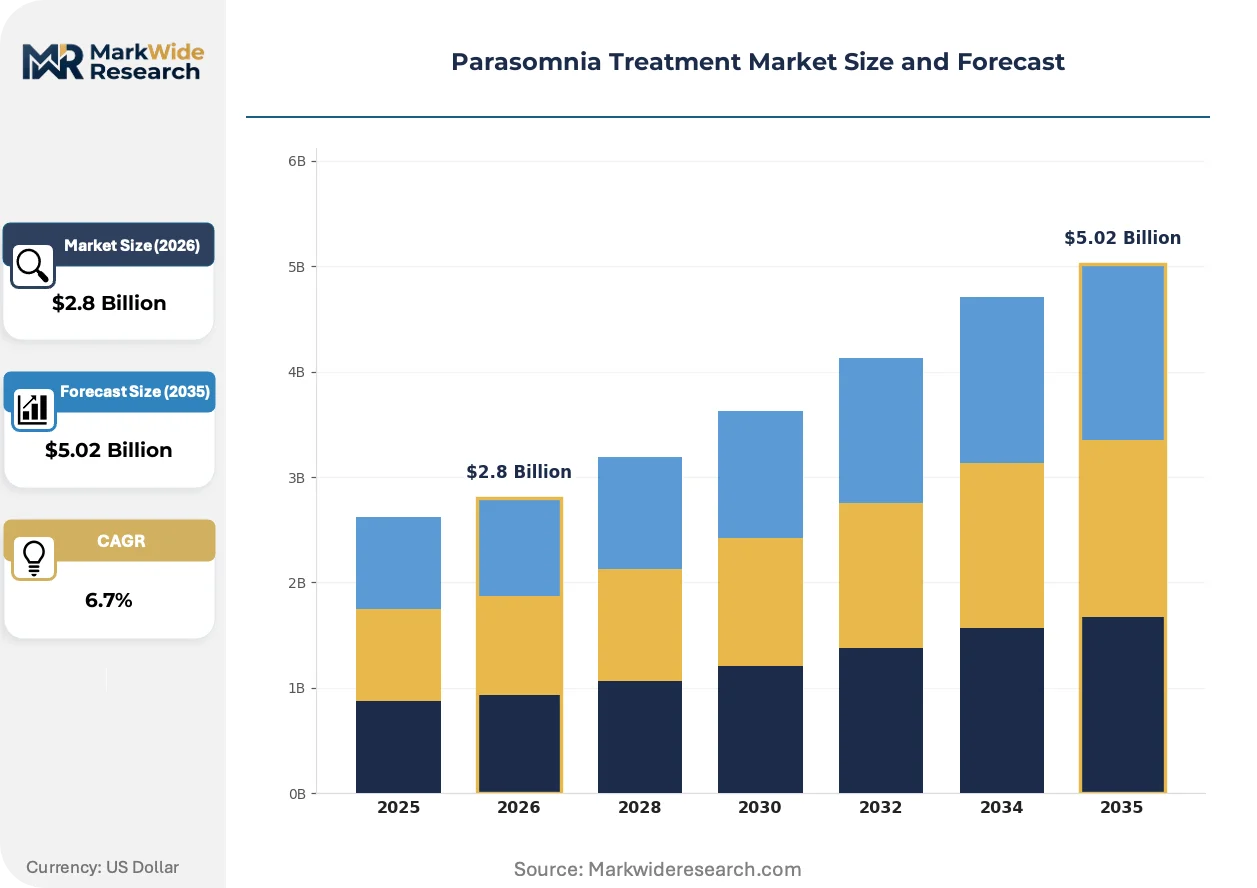
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Cognitive Behavioral Therapy, Sleep Hygiene Education, Devices Delivery Mode: In-Hospital, At-Home, Online Platforms, Telehealth Customer Type: Individuals, Caregivers, Healthcare Providers, Institutions End User: Adults, Children, Elderly, Patients |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sanofi SA, Novartis AG, GlaxoSmithKline plc, Jazz Pharmaceuticals plc, Eisai Co., Ltd., Merck & Co., Inc., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parasomnia Treatment Market Evolving Landscape
Diagnostic modality preferences are bifurcating between centralized polysomnography for complex cases and distributed wearable monitoring for longitudinal tracking, with reimbursement arbitrage driving adoption velocity in commercial payer markets.
Actigraphy combined with peripheral oxygen saturation monitoring is migrating from fitness-consumer applications into clinical-grade REM sleep behavior disorder screening. Neurology practices in Florida and Arizona are deploying these systems for home-based nocturnal video recording. The technology is compressing referral-to-diagnosis intervals from months to weeks for suspected parasomnia cases.
EPA enforcement of volatile organic compound emissions from mandibular advancement device manufacturing facilities is tightening material processing standards. Thermoplastic elastomer curing operations in Ohio and Pennsylvania face enhanced reporting requirements. Device producers are reformulating acrylic resins or relocating finishing operations to maintain production economics.
Hospital sleep centers are unbundling diagnostic interpretation from therapeutic management, creating standalone reading services for polysomnography data. Independent diagnostic testing facilities in Georgia and North Carolina now contract directly with employer health plans. This channel fragmentation is most visible in self-insured corporate populations seeking cost containment for sleep disorder benefits.
Parasomnia Treatment Market Segmentation
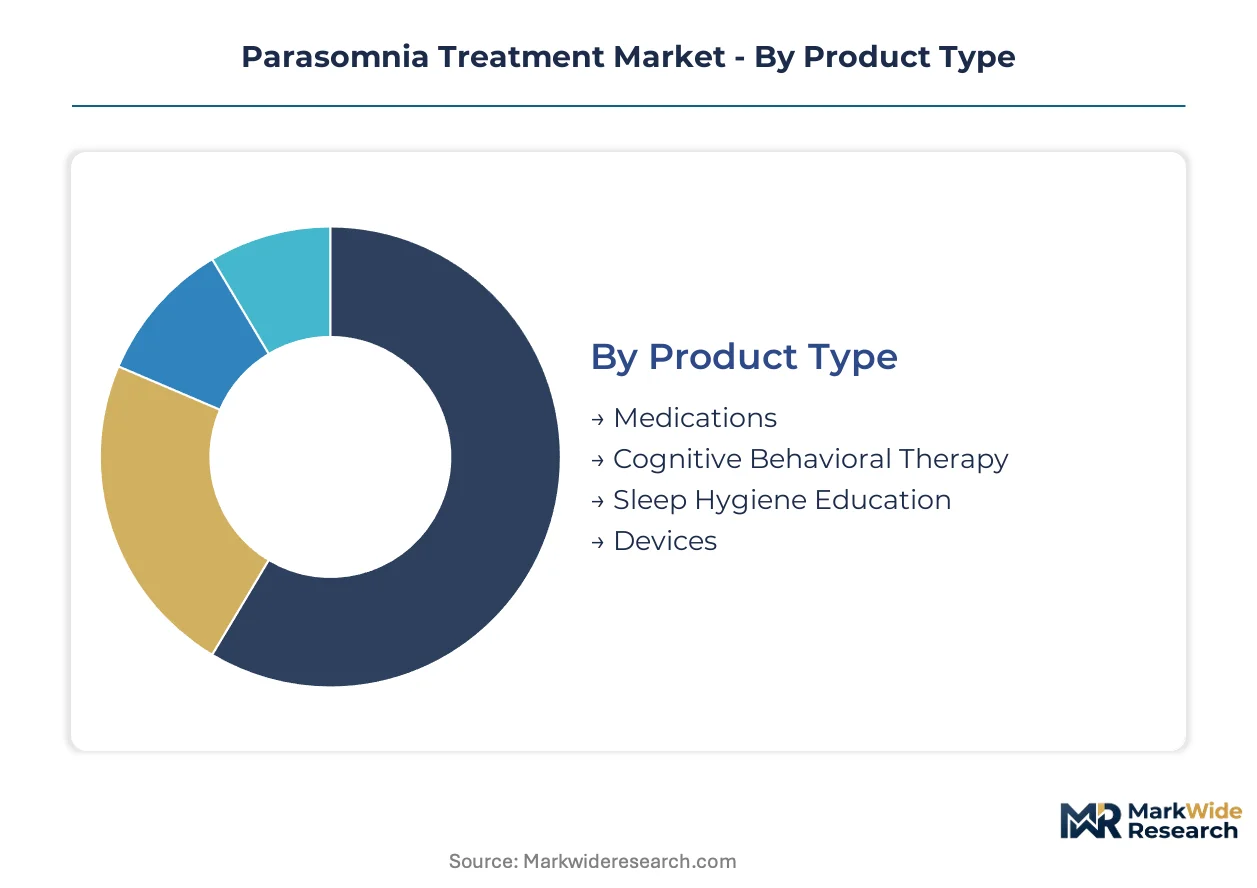
Parasomnia treatment modalities span pharmacological, behavioral, and mechanical interventions with divergent reimbursement pathways and patient access models. Segmentation reveals how chronic prescribing patterns concentrate revenue in established categories while emerging channels reshape distribution economics.
Product Type:
Maturity divides sharply between chronic medication maintenance and emerging device-based diagnostics.
- Medications:Benzodiazepine receptor agonists and melatonin analogs constitute the established revenue base, with chronic prescribing for persistent REM sleep behavior disorder and sleepwalking cases. German statutory health insurers anchor reimbursement volume through integrated care pathways in Bavaria and Baden-Württemberg.
- Devices:Custom-fabricated mandibular advancement devices with titratable mechanisms and wearable electroencephalography systems are displacing polysomnography referrals. FDA 510(k) clearance pathways are compressing development timelines for home diagnostic platforms.
- Cognitive Behavioral Therapy:Protocols targeting sleep-related behaviors show reimbursement traction where telehealth parity laws apply.
- Sleep Hygiene Education:Digital delivery platforms capture margin previously held by in-person consultation models.
Medications retain volume leadership; Devices hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates capital-intensive inpatient diagnostics from scalable remote monitoring.
- Online Platforms:Digital health platforms in California and Texas secure pharmacy benefit manager contracts for chronic medication fulfillment, bypassing traditional wholesale distribution. Direct-to-patient authorization concentrates where state-level telehealth parity laws create reimbursement precedent.
- Telehealth:Remote cognitive behavioral therapy coverage under Illinois and Colorado Medicaid expansions creates template for parasomnia-adjacent reimbursement.
- In-Hospital:Polysomnography interpretation services unbundle from therapeutic management in Georgia and North Carolina independent diagnostic testing facilities.
- At-Home:Wearable monitoring data quality approaches laboratory standards, pressuring payer coverage thresholds.
Online Platforms command the highest margin expansion; Telehealth shows the most volatile reimbursement trajectory.
Customer Type:
Application logic separates acute intervention purchasers from longitudinal care coordinators.
- Healthcare Providers:Neurology practices in Florida and Arizona deploy actigraphy combined with peripheral oxygen saturation monitoring for home-based REM sleep behavior disorder screening.
- Institutions:Hospital sleep centers expand medication and device procurement for non-REM parasomnia cases under expanding US clinic networks.
- Individuals:Self-insured corporate populations in employer health plans drive demand for cost containment in sleep disorder benefits.
- Caregivers:Pediatric and elderly parasomnia management falls to family coordinators navigating fragmented specialty pharmacy channels.
Healthcare Providers dominate clinical decision-making; Institutions control capital procurement volume.
End User:
Volume concentrates in adult chronic cases while pediatric and geriatric segments present distinct access barriers.
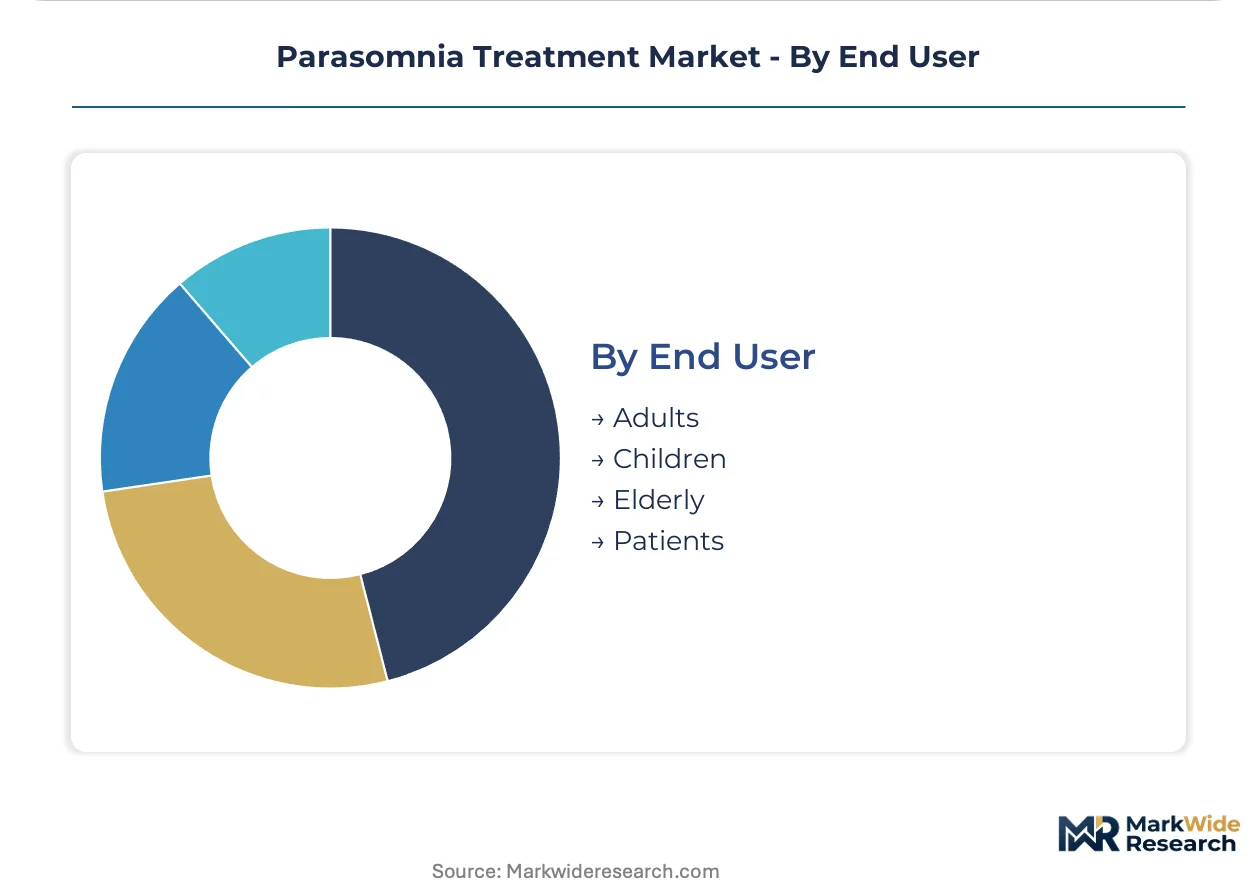
- Adults:Working-age patients with REM sleep behavior disorder sustain chronic prescribing patterns for benzodiazepine receptor agonists and drive wearable diagnostic adoption.
- Elderly:Polypharmacy interactions complicate melatonin analog therapy; Medicare Advantage plans in Arizona and Florida experiment with home-based monitoring incentives.
- Children:Sleepwalking and night terror cases concentrate demand for behavioral protocols with limited pharmacological options.
- Patients:Diagnostic category capturing complex comorbid cases requiring polysomnography confirmation.
Adults sustain the revenue base; Elderly users present the fastest-growing eligibility pool under aging demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic's sleep disorders network anchors North American parasomnia diagnostic capacity through its multi-state referral infrastructure. Germany's statutory health insurance framework underwrites integrated care pathways that combine cognitive behavioral protocols with pharmacotherapy. Japan's aging demographics concentrate demand for elderly-focused sleep disorder management in Kanto and Kansai metropolitan corridors.
United States
FDA 510(k) clearance pathways for wearable electroencephalography systems compress diagnostic device development timelines from multi-year cycles to accelerated determinations. The EPA enforces volatile organic compound emissions from mandibular advancement device manufacturing facilities in Ohio and Pennsylvania. Massachusetts and Minnesota host concentrated clusters of polysomnography equipment manufacturing for electrode arrays and amplifier systems.
Germany
Specialized sleep centers in Bavaria and Baden-Württemberg integrate cognitive behavioral protocols with pharmacotherapy under statutory health insurer reimbursement templates. CE marking under the EU Medical Device Regulation governs market access for therapeutic appliances with notified body backlogs delaying custom-fabricated oral appliance certifications. The Rhine-Main corridor concentrates pharmaceutical distribution infrastructure for melatonin analog formulations.
Japan
PMDA regulatory partnerships with national health technology assessment bodies anchor Eisai Co., Ltd.'s Asia-Pacific market position for narcolepsy-adjacent indications. METI standards coordination supports home-based monitoring device adoption among Medicare-equivalent elderly populations. The Osaka-Kobe manufacturing belt supplies precursor chemicals for benzodiazepine receptor agonist synthesis.
Canada
Health Canada regulates pharmacological parasomnia treatments through its Therapeutic Products Directorate with provincial variations in telehealth reimbursement parity. Automated sleep stage scoring algorithms reduce technician labor costs for diagnostic facilities in Ontario and British Columbia. The Toronto-Waterloo corridor hosts emerging digital health platform development for direct-to-patient medication fulfillment.
United Kingdom
NICE technology appraisals determine coverage thresholds for at-home monitoring data quality approaching laboratory standards. The MHRA post-Brexit regulatory framework creates divergence from EU MDR timelines for mandibular advancement device market entry. London's tertiary sleep centers unbundle polysomnography interpretation from therapeutic management for employer health plan contracts.
Parasomnia Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around pharmaceutical incumbents with established CNS portfolios and emerging digital health platforms securing direct-to-patient authorization. Three archetypes dominate: legacy pharmaceutical firms leveraging wholesale hospital relationships, orphan-drug specialists in narcolepsy-adjacent indications, and digital therapeutics developers pursuing software-as-medical-device classifications. Competitive moves center on strategic partnerships with wearable diagnostic manufacturers and geographic expansion through regulatory partnerships with national health technology assessment bodies.
Among North American pharmaceutical incumbents, Pfizer Inc. and Jazz Pharmaceuticals plc occupy positions reflecting divergent strategic anchors. Pfizer exemplifies the wholesale relationship archetype through sustained hospital sleep center procurement channels. Jazz Pharmaceuticals represents the orphan-drug specialization vector with expertise in adjacent sleep disorder indications. Eisai Co., Ltd. anchors the Asia-Pacific regulatory partnership model through its positioning with Japanese and broader regional health technology assessment frameworks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi SA |
| Novartis AG |
| GlaxoSmithKline plc |
| Jazz Pharmaceuticals plc |
| Eisai Co., Ltd. |
| Merck & Co., Inc. |
| Takeda Pharmaceutical Company Limited |
| Others |
Value Network & Pricing Analysis
Undercapacity in Zhejiang province's API synthesis facilities is tightening supplier leverage over melatonin analog formulations and forcing benzodiazepine receptor agonist producers into longer-term offtake commitments. This utilization squeeze concentrates pricing power among contract manufacturers while compressing margins for finished-dose packagers in North America and Europe.
Pricing Analysis
Volume-discount tiering separates wholesale hospital procurement from direct-to-patient digital channels. Pricing stratifies across premium, standard, and economy tiers based on FDA certification level and after-sales clinical support bundling. Cost compression in the standard tier is intensifying because PBM formulary exclusion pressures are narrowing reimbursement windows. Self-insured employer plans exhibit the highest price sensitivity; hospital sleep centers with GPO contracts demonstrate the lowest.
Supply Chain Analysis
Extended payment terms from Ohio and Pennsylvania device manufacturers to thermoplastic elastomer suppliers are stabilizing working capital through supply-chain finance facilities. Raw material sourcing draws from Zhejiang province for melatonin analog precursors, Massachusetts for polysomnography electrode arrays, and the Osaka-Kobe belt for benzodiazepine receptor agonist intermediates. Single-source vulnerability concentrates in FDA-cleared wearable EEG chipsets. Distribution runs through specialty pharmacy wholesalers for medications and direct-to-patient platforms for home diagnostic devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against digital therapeutics and consumer-grade sleep trackers that capture patient data before clinical referral. Incumbents must navigate this threat while preserving wholesale hospital relationships.
For Market Incumbents: Insulate wholesale formulary position by deepening backward integration into API synthesis for melatonin analogs, particularly in Zhejiang corridor partnerships. Secure FDA software-as-medical-device determinations for proprietary diagnostic algorithms before digital therapeutics platforms achieve prescription status. Channel control through GPO contracts remains the priority defensive lever against direct-to-patient disintermediation.
For New Entrants and Emerging Players: Build out telehealth reimbursement expertise in Illinois and Colorado Medicaid frameworks as the most penetrable entry vector. Target pediatric parasomnia behavioral protocols where pharmacological competition is sparse and caregiver payment willingness runs high. A go-to-market angle anchored in employer health plan cost containment contracts bypasses hospital procurement gatekeepers.
For Investors and Strategic Acquirers: Long-term, this sits as a chronic-disease management play because aging demographics expand the addressable elderly pool and Medicare Advantage experimentation with home monitoring creates sustainable reimbursement tailwinds. Acquisition targets should display orphan-drug regulatory expertise or wearable diagnostic FDA clearance pathways. The signal to watch is state-level telehealth parity expansion that validates direct-to-patient economics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates wearable EEG diagnostic timelines from multi-year cycles to expedited review. |
| CE Marking Under EU MDR | Governs mandibular advancement device access with notified body backlog risks. |
| Hospital System Partnership | Unbundles polysomnography interpretation from therapeutic management in Georgia and North Carolina. |
| Software Companion Development | Clarifies prescription digital intervention boundaries for REM sleep behavior disorder. |
| Reimbursement Strategy | Secures PBM contracts for chronic medication fulfillment in California and Texas. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across sleep disorder clinics, pharmaceutical regulatory affairs leads, hospital procurement managers, and PBM formulary directors. Secondary validation drew from FDA 510(k) filings, EMA submission databases, ClinicalTrials.gov entries, and statutory health insurer reimbursement templates in Germany. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Calibration against historical benzodiazepine receptor agonist prescribing patterns and wearable diagnostic adoption curves in Florida and Arizona informed trajectory assumptions across the projection horizon. Segmentation dimensions included product type, delivery mode, customer archetype, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to chronic medication maintenance and device replacement cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital therapeutics platforms or consumer wearable manufacturers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Insomnia Market
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Sleeping Bruxism Treatment Market