
 Sleep Studies Market | 2026-2036
Sleep Studies Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Studies Market Analytics
Subscription-based remote monitoring software is broadening what sleep study vendors monetize beyond hardware sales. ResMed leverages cloud-connected therapy platforms to sustain recurring revenue streams alongside device shipments. Koninklijke Philips NV anchors its competitive stance through integrated diagnostic-to-treatment workflows spanning hospital and home environments. Natus Medical Incorporated specializes in neurophysiology measurement systems that occupy the high-acuity polysomnography segment.
Sleep studies encompass the objective measurement, recording, and clinical interpretation of physiological parameters during sleep, typically capturing electroencephalography, electrooculography, electromyography, respiratory airflow, and oxygen saturation data through multi-channel acquisition systems to diagnose disorders such as obstructive sleep apnea, narcolepsy, and periodic limb movement disorder. Polysomnography devices retain the dominant revenue position due to their diagnostic gold-standard status for complex cases requiring attended laboratory evaluation, while home sleep testing kits represent the fastest-expanding category as payers mandate cost-effective ambulatory pathways for uncomplicated apnea suspicion. Wearable sensors and smartphone integration technologies are capturing margin pools through consumer-grade sleep quality assessment tools that blur clinical and wellness boundaries.
The FDA governs polysomnography devices and home sleep testing systems through 510(k) premarket notification pathways, while the Centers for Medicare and Medicaid Services reimbursement policies directly shape provider adoption economics for in-lab versus home-based testing. State-level professional licensing boards regulate technician credentialing requirements that affect laboratory operational scalability. Stakeholders must monitor evolving software-as-medical-device guidance and telehealth parity legislation to calibrate product portfolios and service delivery models.
Market Dynamics
Decentralized diagnostic pathways are restructuring competitive economics as CMS reimbursement policies tilt provider economics toward home sleep testing over attended polysomnography. This shift compresses capital requirements for market entry while elevating software and data analytics capabilities as differentiation vectors.
Growth Catalysts
- Telehealth Parity Legislation:CMS reimbursement parity for remote diagnostic interpretation is expanding addressable patient populations beyond metropolitan laboratory catchments.
- Chronic Disease Management Integration:Cardiovascular and diabetes care programs are embedding sleep disorder screening as a standard protocol, creating embedded demand pull.
- Machine Learning Scoring:FDA-cleared automated polysomnography interpretation algorithms are reducing technician labor intensity and accelerating report turnaround.
Market Restraints
- Semiconductor Component Volatility:Multi-channel acquisition systems depend on specialized analog-to-digital converters with concentrated foundry supply in East Asia.
- Reimbursement Compression:Medicare fee schedule reductions for in-lab polysomnography are compressing margins for hospital-based sleep centers.
- Home Testing Accuracy Limitations:Peripheral arterial tonometry devices generate false-negative rates for central sleep apnea that necessitate confirmatory laboratory study.
Strategic Opportunities
- Rural Health Clinic Expansion:Federally qualified health centers in underserved US counties lack on-site polysomnography capacity and represent deployable home testing infrastructure.
- Occupational Sleep Medicine:Commercial transportation and aviation sectors face regulatory mandates for sleep apnea screening that outstrip specialist availability.
- Wearable-PSG Convergence:Integration of consumer wrist-worn photoplethysmography with clinical-grade electroencephalography is creating hybrid diagnostic categories.
Industry Challenges
- Registered Polysomnographic Technologist Shortage:BRPT certification pathways produce insufficient credential holders to staff expanded home testing interpretation volumes.
- Legacy System Interoperability:Hospital electronic health record integration with proprietary sleep laboratory information systems requires costly interface engine development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Studies Market |
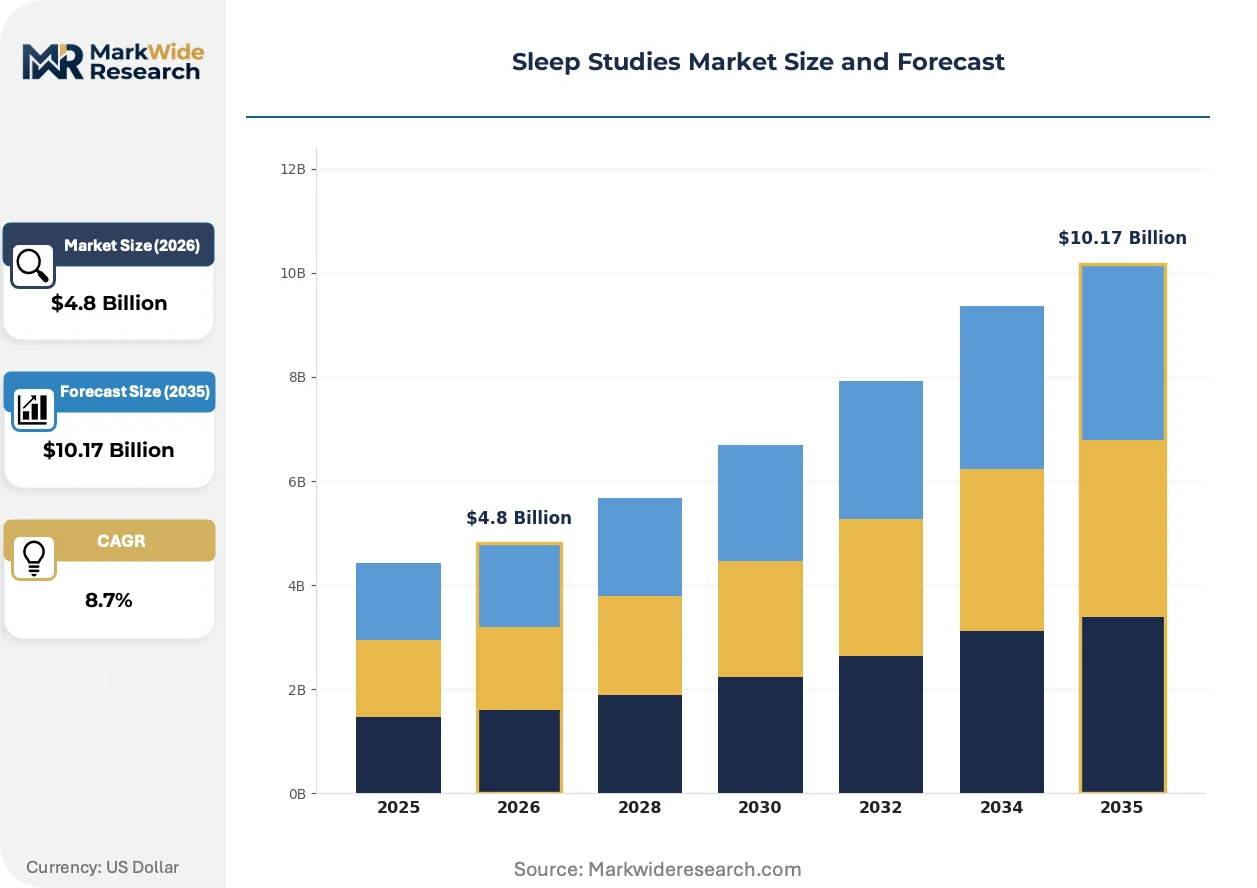
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polysomnography Devices, Home Sleep Testing Kits, Actigraphy Systems, Sleep Monitoring Apps End User: Hospitals, Sleep Clinics, Home Care Settings, Research Institutions Technology: Wearable Sensors, EEG Monitoring, Video Polysomnography, Smartphone Integration Application: Obstructive Sleep Apnea, Insomnia Management, Narcolepsy Diagnosis, Sleep Quality Assessment |
| Companies Covered | ResMed, Koninklijke Philips NV, Natus Medical Incorporated, Compumedics Limited, Nihon Kohden Corporation, Cadwell Industries Inc, SOMNOmedics AG, Itamar Medical Ltd, Onera Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Studies Market Evolving Landscape
Artificial intelligence is penetrating every layer of sleep study workflow from signal acquisition through clinical interpretation. Three distinct vectors are reshaping product architecture and service delivery models.
Deep learning algorithms trained on large polysomnography datasets are electrifying automated sleep staging and respiratory event detection. Academic medical centers and commercial laboratories are deploying these tools to reduce scorer variability and accelerate report generation. The technology is compressing labor cost structures while raising diagnostic throughput ceilings for high-volume operators.
The FDA's evolving software-as-medical-device guidance is reclassifying algorithm-based diagnostic tools that previously operated under enforcement discretion. Manufacturers must now navigate 510(k) pathways for machine learning models that adapt with continued training. Sleep study vendors with cloud-connected platforms are restructuring quality management systems to accommodate continuous learning regulatory frameworks.
Direct-to-consumer distribution is bypassing traditional physician referral channels for preliminary sleep apnea risk assessment. Retail pharmacy chains and employer wellness programs are contracting with diagnostic service organizations to provide home testing kits without specialist gatekeeping. This channel expansion is most advanced in employer-sponsored health plans seeking to reduce downstream cardiovascular claims through early identification.
Sleep Studies Market Segmentation
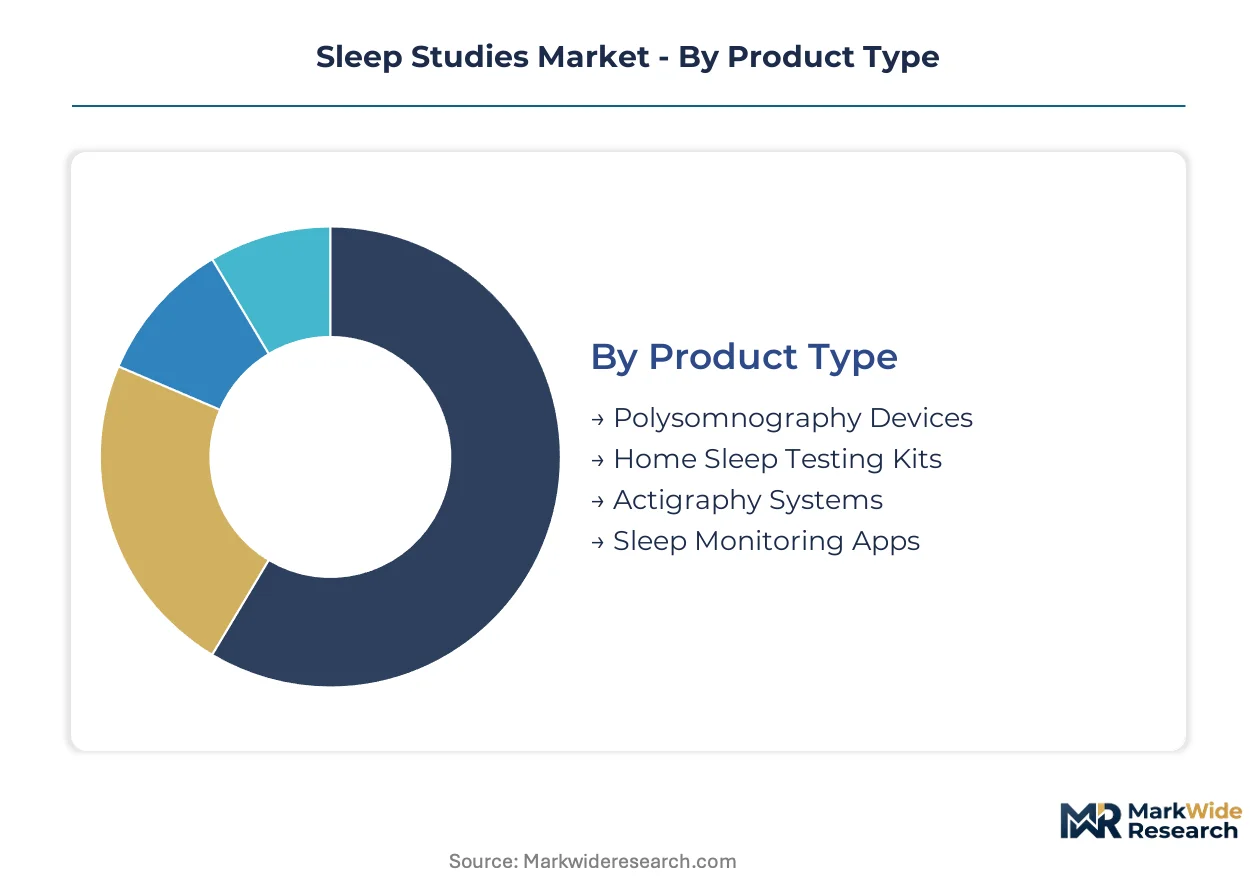
Sleep study market segmentation reflects a fundamental tension between diagnostic precision and care delivery accessibility. Product architecture choices determine whether vendors capture revenue through capital-intensive laboratory installations or recurring consumables in decentralized settings. Each segment carries distinct margin profiles, regulatory pathways, and customer concentration patterns that shape competitive strategy.
Product Type:
Integration depth varies sharply across this category, with standalone laboratory systems anchoring high-acuity workflows while embedded home-based modules expand point-of-care reach.
- Polysomnography Devices:Multi-channel acquisition systems capture electroencephalography, electrooculography, electromyography, and respiratory parameters through attended laboratory protocols. Hospital-based sleep centers in the United States concentrate procurement volumes as Medicare reimbursement policies sustain in-lab economics for complex diagnostic cases.
- Home Sleep Testing Kits:Peripheral arterial tonometry and nasal airflow devices enable unattended apnea screening in ambulatory settings. CMS reimbursement parity for home-based pathways is accelerating placement velocity among federally qualified health centers seeking to extend diagnostic access beyond metropolitan catchments.
- Actigraphy Systems:Wrist-worn accelerometers measure movement patterns to infer sleep-wake cycles through algorithmic interpretation.
- Sleep Monitoring Apps:Smartphone-based photoplethysmography and accelerometer applications deliver consumer-grade sleep quality metrics outside clinical reimbursement frameworks.
Volume placements concentrate in polysomnography devices; the faster expansion belongs to home sleep testing kits.
End User:
Customer type determines purchasing authority, with institutional procurement committees favoring integrated vendor relationships while individual consumers prioritize price accessibility.
- Hospitals:Academic medical centers and community hospital systems operate centralized sleep laboratories requiring FDA-cleared polysomnography systems with electronic health record integration capabilities. These institutions face margin compression from Medicare fee schedule reductions for in-lab testing.
- Sleep Clinics:Independent diagnostic testing facilities specialize in attended and unattended sleep study interpretation, often operating under physician supervision with streamlined operational models.
- Home Care Settings:Patients receive diagnostic equipment through mail-order distribution or durable medical equipment suppliers, bypassing traditional facility-based encounters.
- Research Institutions:Academic investigators employ high-density electroencephalography montages and experimental wearable configurations for clinical trial endpoints and neurophysiology research protocols.
Procurement scale peaks with hospital systems; sleep clinics are climbing the fastest as independent operators capture redirected volume from compressed hospital margins.
Technology:
Technology selection trades measurement fidelity against patient burden, with invasive electrode configurations yielding superior signal quality at the cost of sleep disruption.
- Wearable Sensors:Photoplethysmography and accelerometer arrays embedded in wrist-worn or ring-form devices enable longitudinal sleep monitoring without clinical supervision. Employer wellness programs in the United States are embedding these tools into cardiovascular risk reduction initiatives.
- EEG Monitoring:Scalp electrode configurations measuring cortical electrical activity remain the diagnostic reference standard for sleep staging and arousal detection.
- Video Polysomnography:Synchronized audiovisual recording enables behavioral correlation with physiological signals for parasomnia evaluation and movement disorder characterization.
- Smartphone Integration:Device-agnostic software platforms aggregate data streams from multiple sensor modalities, creating unified patient-facing interfaces.
Deployment frequency favors EEG monitoring; wearable sensors are gaining share fastest as consumer electronics manufacturers enter clinical-adjacent market positions.
Application:
Application segmentation aligns with disease prevalence, comorbidity patterns, and the availability of pharmacological or device-based therapeutic interventions.
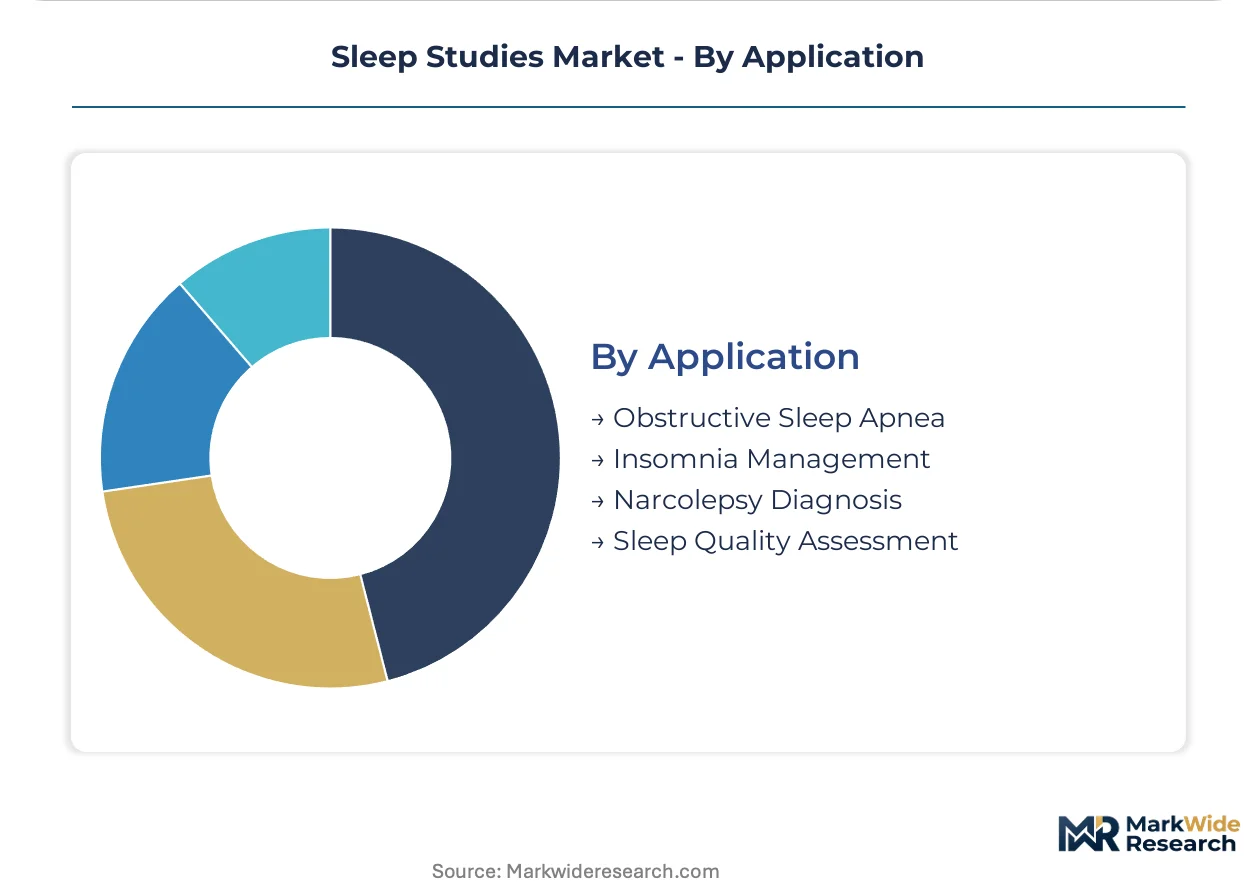
- Obstructive Sleep Apnea:Recurrent upper airway collapse during sleep necessitates airflow and oxygen saturation monitoring for diagnosis and therapy titration. Commercial transportation regulatory mandates in the United States are expanding screening obligations beyond traditional clinical suspicion pathways.
- Insomnia Management:Sleep-onset and maintenance difficulties require subjective validation through actigraphy or polysomnography when behavioral interventions prove insufficient.
- Narcolepsy Diagnosis:Hypocretin deficiency and rapid eye movement sleep abnormalities demand multiple sleep latency testing protocols available primarily in specialized referral centers.
- Sleep Quality Assessment:Non-specific sleep complaints drive wellness-oriented monitoring without diagnostic coding for reimbursement.
Testing volume concentrates in obstructive sleep apnea; sleep quality assessment is expanding most quickly as direct-to-consumer channels bypass physician gatekeeping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Germany, Japan, and the United States, while diagnostic service consumption tilts toward North American and Western European healthcare systems with established reimbursement frameworks for sleep disorder management.
United States
Medicare reimbursement parity for home sleep testing is redirecting diagnostic volume from hospital laboratories to ambulatory settings. The FDA's 510(k) pathway governs clearance for polysomnography devices and emerging software-as-medical-device platforms. Sleep medicine clusters in Boston, Stanford, and Pittsburgh anchor clinical trial activity for machine learning scoring algorithms.
Germany
Statutory health insurance coverage for sleep disorder diagnostics sustains steady demand for attended polysomnography in university hospital networks. The EU Medical Device Regulation (MDR) is extending conformity assessment timelines for multi-channel acquisition systems. Baden-Württemberg and Bavaria host precision electronics manufacturing supplying analog-to-digital converter components for diagnostic equipment.
Japan
Aging demographics and cardiovascular comorbidity screening protocols are expanding sleep apnea detection programs through employer health insurance associations. PMDA regulatory frameworks emphasize clinical validation requirements for automated scoring algorithms. Tokyo and Osaka metropolitan areas concentrate polysomnography laboratory capacity within integrated university hospital systems.
China
Domestic device manufacturers are capturing share in tier-two and tier-three city hospital procurement through cost-competitive home sleep testing systems. NMPA regulatory harmonization with international standards is accelerating market access for imported polysomnography platforms. The Yangtze River Delta and Pearl River Delta regions concentrate electronics manufacturing supporting sensor component supply chains.
Australia
Public hospital waiting list pressures are driving adoption of decentralized diagnostic pathways through primary care networks. TGA regulatory frameworks align with FDA precedents for software-based sleep staging tools. Melbourne and Sydney anchor academic sleep research programs generating clinical evidence for wearable-PSG convergence technologies.
Sleep Studies Market Competitive Landscape
Top-tier vendors anchor diagnostic-to-treatment workflow integration, while mid-tier specialists compete on modular hardware configurations and regional service density. The vendor base stratifies across three functional tiers: comprehensive platform providers, component specialists, and regional diagnostic service organizations. Dominant competitive moves include cloud-connected platform development and strategic partnerships with payers to secure preferred provider status in home testing networks.
Within the comprehensive platform tier, ResMed and Koninklijke Philips NV exemplify integrated device-to-software architectures that capture recurring revenue beyond initial hardware placement. Natus Medical Incorporated occupies a position representing specialized neurophysiology measurement systems for high-acuity polysomnography applications. These three entities collectively illustrate the competitive spectrum spanning consumer-accessible home testing through hospital-grade diagnostic infrastructure.
| Leading Market Players |
|---|
| ResMed |
| Koninklijke Philips NV |
| Natus Medical Incorporated |
| Compumedics Limited |
| Nihon Kohden Corporation |
| Cadwell Industries Inc |
| SOMNOmedics AG |
| Itamar Medical Ltd |
| Onera Health |
| Others |
Value Network & Pricing Analysis
The EU Medical Device Regulation's clinical evidence requirements gate qualified supply for polysomnography platforms and sustain premium-tier pricing access for manufacturers with notified body certifications. Compliance investment separates vendors capturing hospital procurement contracts from price-competitive home testing suppliers locked into lower-margin ambulatory pathways.
Pricing Analysis
Margin tightening in hospital-grade polysomnography reflects Medicare fee schedule compression and extended sales cycles through GPO contracts. Three-tier pricing structure across premium, standard, and economy levels tracks FDA clearance tier and EEG channel density. Cost-down pressure on home sleep testing accelerates because CMS reimbursement parity favors disposable peripheral arterial tonometry devices. Sleep clinics exhibit highest price sensitivity; academic medical centers prioritize integration depth over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for specialized analog-to-digital converters feeding multi-channel acquisition systems. Component sourcing draws from Germany for precision electrode manufacturing and China for consumer-grade wearable sensors. Semiconductor foundry concentration in East Asia creates tariff exposure under evolving trade frameworks. Distribution runs through durable medical equipment suppliers and direct-to-consumer pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's evolving software-as-medical-device guidance creates a cost-of-compliance moat that rewards cloud-connected platform vendors with continuous learning quality management systems.
For Market Incumbents: Lock in recurring revenue through therapy management software subscriptions that extend beyond hardware replacement cycles. Defend against home testing commoditization by deepening hospital EHR integration and securing preferred provider status with national payers. Invest in automated scoring R&D to reduce technician labor intensity and accelerate report turnaround. For New Entrants and Emerging Players: Enter via federally qualified health centers in rural US counties lacking on-site polysomnography capacity. Target occupational sleep medicine mandates in commercial transportation and aviation sectors facing regulatory screening obligations. Pursue direct-to-consumer pharmacy distribution partnerships that bypass specialist referral gatekeeping. For Investors and Strategic Acquirers: FDA clearance for machine learning-based polysomnography interpretation is the leading indicator that automated scoring platforms will consolidate diagnostic service economics. Long-term viability favors vendors with integrated diagnostic-to-treatment workflows spanning home and hospital settings. Monitor BRPT certification pipeline expansion as a signal for technician-constrained market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for ML Scoring | Automated sleep staging algorithms reduce labor costs and accelerate report generation for high-volume laboratories. |
| Cloud Platform Integration | ResMed and Philips leverage connected therapy platforms to sustain recurring revenue alongside device shipments. |
| Hospital System Partnership | EHR integration capabilities determine procurement decisions at academic medical centers and community hospital networks. |
| Home Testing Network Expansion | CMS reimbursement parity drives placement velocity among federally qualified health centers in underserved counties. |
| Wearable-PSG Convergence R&D | Integration of consumer photoplethysmography with clinical EEG creates hybrid diagnostic categories for longitudinal monitoring. |
Research Methodology
Document review covered FDA 510(k) filings, CMS Medicare fee schedules, and BRPT certification data, complemented by interviews with sleep medicine clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary sources included hospital procurement databases, medical device trade customs records, and regulatory guidance documents. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Market value outputs reflect segment-level price-volume analysis across the projection horizon, with CAGRs derived from logistic adoption curves fitted to reimbursement policy shifts and technology diffusion patterns. Segmentation dimensions modeled include diagnostic setting (laboratory versus home), device class (polysomnography versus home sleep testing versus actigraphy), and connectivity architecture (standalone versus cloud-integrated). Forecast inputs incorporated CMS reimbursement trajectory scenarios and FDA software-as-medical-device guidance evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or telehealth parity legislation rollback scenarios. Deviation in Medicare home sleep testing reimbursement rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Anti-Snoring Treatment Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Insomnia Treatment Market