
 Home Sleep Screening Devices Market | 2026-2036
Home Sleep Screening Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Home Sleep Screening Devices Market Intelligence
Direct-to-consumer online retail channels are reconfiguring market access for home sleep screening devices, shifting power from traditional medical suppliers. Established medical device firms like ResMed Inc. leverage their deep clinical ties and therapy ecosystems to maintain share. In contrast, consumer technology giants such as Apple Inc. and Garmin Ltd. compete on user experience and integration within broader personal wellness platforms.
Home sleep screening devices are non-invasive instruments that record physiological data to assess sleep quality and screen for disorders. These devices often measure key biometrics like blood oxygen saturation (SpO2), heart rate, and respiratory patterns. Wearable sensors are gaining significant traction over non-wearable monitors due to their convenience and continuous data collection capabilities. Sleep tracking algorithms, powered by machine learning, represent the core intellectual property differentiating performance across device technologies.
Market access for clinical-grade devices is governed by stringent regulatory approvals from bodies like the FDA in the United States and notified bodies for CE marking in Europe. These regulations establish standards for diagnostic accuracy and data security, shaping product development cycles. The primary strategic challenge for vendors is balancing the development of consumer-facing wellness features with the rigorous validation required for medical reimbursement.
Market Dynamics
The convergence of consumer wellness technology with regulated medical diagnostics is the central force shaping the market. This dynamic creates a fundamental tension between devices designed for personal health tracking and those validated for clinical screening, influencing go-to-market strategies and regulatory pathways.
Growth Catalysts
- Regulatory Pathways:Streamlined clearance processes, such as the FDA's 510(k) pathway in the United States, lower the barrier for new clinical-grade devices to enter the market with specific diagnostic claims for conditions like sleep apnea.
- Sensor Miniaturization:Advances in photoplethysmography (PPG) and accelerometer sensors enable the development of smaller, more comfortable wearable devices, like rings and patches, that facilitate long-term, unobtrusive data collection.
- Corporate Wellness Programs:Employers are increasingly incorporating sleep health into their wellness initiatives to improve productivity and reduce healthcare costs, creating a new B2B demand channel for screening devices.
Market Restraints
- Substitution from Software:The availability of low-cost or free smartphone applications offering basic sleep cycle tracking poses a significant substitution threat to dedicated hardware, particularly at the consumer wellness end of the market.
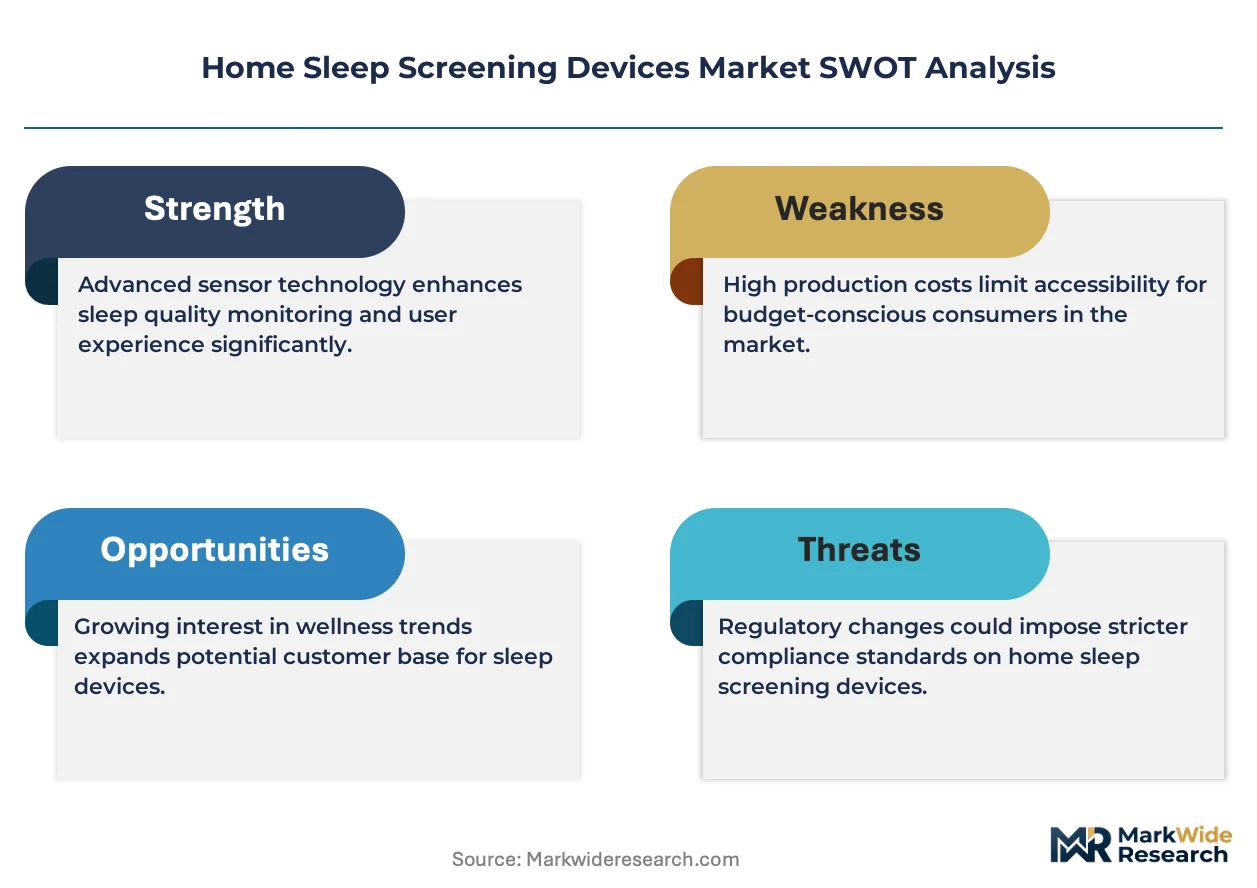
- Data Privacy Compliance:Stringent regulations like GDPR in Europe and HIPAA in the United States impose significant compliance costs and technical challenges for managing and securing sensitive personal health data.
- Diagnostic Accuracy Limitations:Many consumer-grade devices lack the validated accuracy to differentiate between obstructive and central sleep apnea, limiting their utility for clinical diagnosis and hindering physician acceptance.
Strategic Opportunities
- Underserved Geographies:Markets in Latin America and Southeast Asia with nascent healthcare infrastructure and a growing middle class represent significant white space for direct-to-consumer sales models that bypass traditional clinical channels.
- Pediatric Screening Applications:Developing devices and algorithms specifically validated for screening sleep-disordered breathing in children is a major opportunity, as this demographic is currently underserved by existing home screening solutions.
- Integration with Chronic Disease Management:Combining sleep data with metrics from continuous glucose monitors or blood pressure cuffs can create powerful platforms for managing chronic conditions like diabetes and hypertension.
Industry Challenges
- Clinical Validation Timelines:The lengthy and costly process of conducting clinical trials to secure regulatory approval from bodies like the FDA or achieve CE marking under the MDR delays time-to-market and favors incumbents.
- Data Interoperability:A lack of standardized data formats and APIs makes it difficult to integrate sleep screening data into Electronic Health Record (EHR) systems, creating a barrier to clinical workflow adoption.
- Interpretation Skill Gap:The raw data generated by screening devices requires interpretation by trained professionals, but a shortage of qualified sleep technicians and physicians creates a bottleneck in translating screening results into clinical action.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Sleep Screening Devices Market |
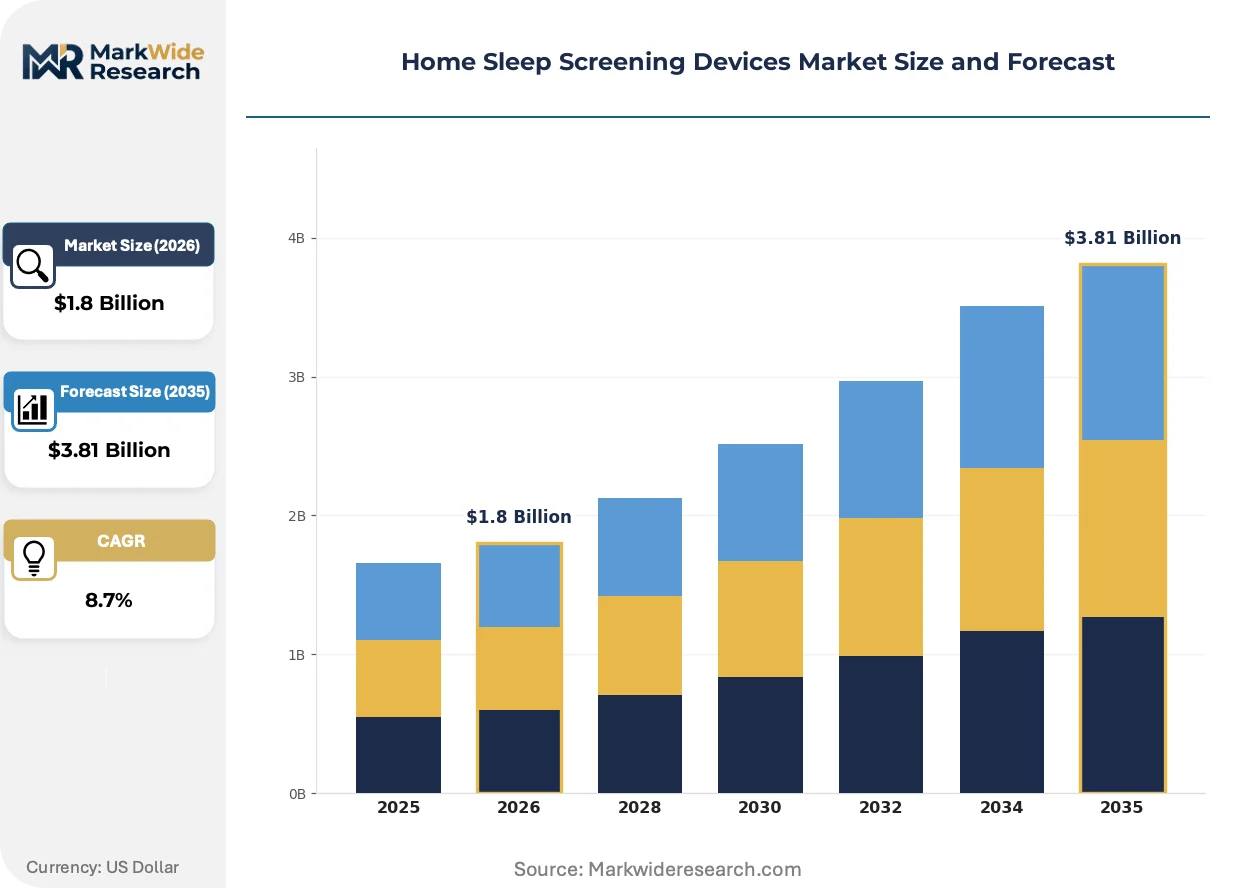
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Sensors, Non-Wearable Monitors, Handheld Devices, Smartphone Applications Technology: Polysomnography, Actigraphy, Biofeedback Mechanisms, Sleep Tracking Algorithms End User: Individuals, Sleep Clinics, Hospitals, Research Institutions Distribution Channel: Online Retail, Medical Supply Outlets, Direct Sales, Third-Party Distributors |
| Companies Covered | Itamar Medical Ltd., Withings, ResMed Inc., Apple Inc., Nox Medical, Koninklijke Philips N.V., Garmin Ltd., Fitbit Inc., Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Sleep Screening Devices Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from passive data collection toward the delivery of actionable, clinically relevant insights. This transformation is primarily driven by advancements in software, particularly machine learning, which are elevating the diagnostic potential of wearable sensors.
Machine learning algorithms represent the core enabling technology, analyzing complex physiological signals such as heart rate variability, blood oxygen levels, and respiratory patterns to identify signatures of sleep disorders. Both established medical device manufacturers and consumer technology firms are rapidly adopting these sophisticated algorithms. This software-centric approach is digitizing the entire workflow of sleep disorder screening, moving the primary source of value from the hardware to the analytical intellectual property.
Regulatory frameworks are becoming more stringent, directly influencing product design and market claims. The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on any device marketed with a medical purpose. This elevates the compliance burden for manufacturers, especially for devices claiming to screen for conditions like sleep apnea. Consequently, the segment of devices classified as medical is facing higher development costs and longer validation cycles.
A notable behavioral shift involves consumers moving from one-time hardware purchases toward subscription-based services that provide ongoing data analysis, personalized coaching, and telehealth consultations. This recurring revenue model is disrupting traditional distribution channels, particularly durable medical equipment suppliers, by fostering a direct relationship between vendors and end-users. The trend is most advanced in developed markets like the United States and Germany, where consumer comfort with digital health subscriptions is high.
Home Sleep Screening Devices Market Segmentation
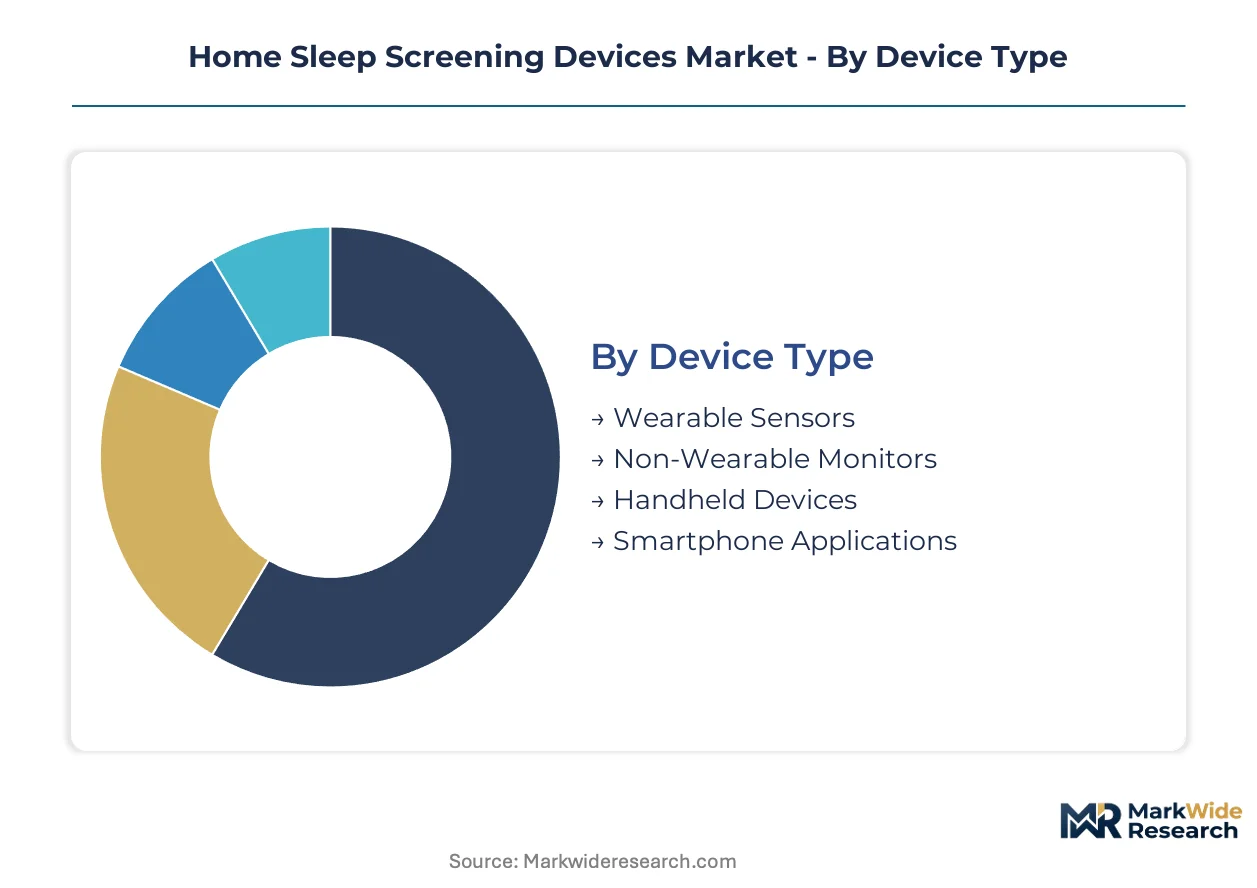
Market segmentation provides a granular view of the diverse product offerings and consumer needs shaping the home sleep screening devices landscape. Understanding these distinct segments is crucial for vendors to tailor product development, marketing strategies, and distribution channels effectively, addressing both wellness and clinical requirements.
Device Type:
The maturity spectrum within device types reveals established technologies alongside rapidly evolving innovations, each serving specific user preferences and diagnostic needs.
- Wearable Sensors:These compact devices attach to the body, continuously collecting physiological data like blood oxygen saturation and heart rate. Demand concentrates in developed markets, driven by consumer preference for unobtrusive, continuous monitoring solutions.
- Smartphone Applications:These software-based tools leverage phone sensors or external peripherals to track basic sleep cycles and patterns. They find demand among budget-conscious consumers seeking initial wellness insights, posing a substitution threat to dedicated hardware.
- Non-Wearable Monitors:These stationary devices, often placed bedside, capture sleep data without direct body contact.
- Handheld Devices:Portable instruments offer diagnostic capabilities, often used for targeted screening in clinical settings.
Non-Wearable Monitors retain volume leadership; Wearable Sensors hold the steepest expansion curve.
Technology:
Technology differentiation drives performance and cost structures across the market, influencing diagnostic accuracy and user experience.
- Polysomnography:This comprehensive diagnostic method records multiple physiological parameters simultaneously, including brain waves, blood oxygen, and heart rate. Demand is concentrated in clinical settings and for regulatory validation, ensuring high diagnostic accuracy.
- Sleep Tracking Algorithms:Machine learning models analyze raw physiological data from sensors to identify sleep stages and disorder patterns. These algorithms are critical intellectual property differentiating device performance and delivering actionable insights to users.
- Actigraphy:This method uses accelerometers to monitor activity and rest cycles, primarily for sleep-wake pattern assessment.
- Biofeedback Mechanisms:These technologies train individuals to control physiological responses, sometimes integrated into devices for sleep improvement.
Innovation in Sleep Tracking Algorithms reshapes device capabilities, while Polysomnography remains the clinical benchmark.
End User:
Customer types define distinct purchasing behaviors and product requirements within the market, ranging from personal wellness to professional medical applications.
- Individuals:These consumers purchase devices for personal health monitoring, wellness tracking, and initial screening for sleep issues. Demand is high in developed economies with strong consumer awareness and disposable income for health technology.
- Sleep Clinics:These specialized medical facilities utilize devices for patient diagnosis, treatment planning, and follow-up monitoring. Clinical validation and data interoperability are critical requirements for these professional end-users.
- Hospitals:Healthcare institutions deploy screening devices for inpatient monitoring and preliminary diagnosis in various departments.
- Research Institutions:Academic and corporate research bodies use these devices for scientific studies on sleep physiology and disorders.
The individual consumer segment drives significant volume, while clinical users demand rigorous validation.
Distribution Channel:
Distribution channels vary by market maturity, influencing consumer access and vendor strategies for reaching diverse customer segments.
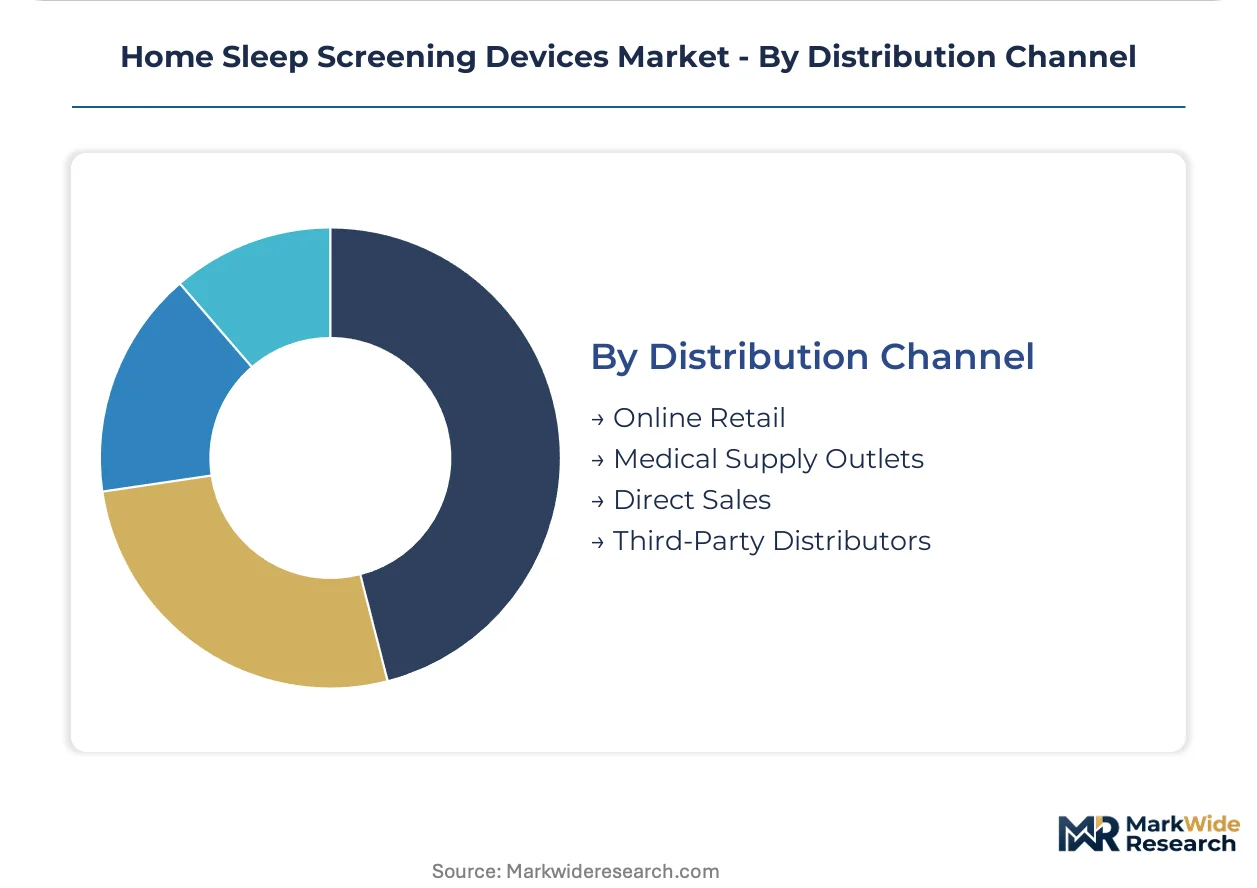
- Online Retail:E-commerce platforms provide direct-to-consumer access, reconfiguring market dynamics and reducing reliance on traditional medical channels. This channel is expanding rapidly in countries like the United States due to high digital adoption.
- Medical Supply Outlets:These traditional channels supply devices to healthcare providers and patients with prescriptions, often facilitating medical reimbursement. They remain critical for clinical-grade devices requiring professional guidance and support.
- Direct Sales:Manufacturers engage directly with large institutional buyers or corporate wellness programs, bypassing intermediaries.
- Third-Party Distributors:These entities manage logistics and sales for manufacturers, particularly in fragmented or geographically diverse markets.
Online Retail is rapidly gaining market share, while Medical Supply Outlets maintain a stable base for clinical devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Streamlined regulatory pathways, such as the FDA's 510(k) process, facilitate market entry for new clinical-grade home sleep screening devices. These frameworks encourage innovation and expand access. Corporate wellness programs also create new B2B demand channels.
United States
High consumer awareness and robust healthcare system integration drive significant demand for home sleep screening devices. The FDA's 510(k) pathway actively supports rapid market entry for new clinical-grade devices. Silicon Valley and Boston's biotech corridor are centers for advanced wearable sensor development.
Germany
Germany exhibits strong demand, fueled by consumer comfort with digital health subscriptions and its well-developed healthcare infrastructure. The European Union's Medical Device Regulation (MDR) imposes stringent requirements for clinical evidence. Cities like Munich and Berlin emerge as hubs for digital health startups, attracting investment in sleep technology.
Japan
An aging population and high technological adoption rates contribute to demand for unobtrusive sleep monitoring devices. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees product approvals, ensuring diagnostic accuracy. Tokyo and Osaka serve as key innovation centers, where consumer electronics firms integrate sleep tracking into wellness platforms.
Australia
Strong public health initiatives focusing on chronic disease management and high disposable income drive device adoption. The Therapeutic Goods Administration (TGA) regulates medical devices, setting rigorous standards for safety and performance. Major cities like Sydney and Melbourne are seeing increased adoption of direct-to-consumer sales for health technology.
Canada
Canada's publicly funded healthcare system and growing awareness of sleep-related health issues generate consistent demand. Health Canada provides regulatory oversight for medical devices, focusing on safety and efficacy. Toronto and Vancouver develop as hubs for digital health innovation, fostering partnerships between tech companies and medical institutions.
Home Sleep Screening Devices Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing established medical device firms and agile consumer technology giants. Established players leverage deep clinical ties, while consumer tech companies compete on user experience and platform integration. Key strategic archetypes include clinical-grade device manufacturers, consumer wellness platform providers, and specialized algorithm developers. Dominant competitive moves involve strategic partnerships for data integration and continuous portfolio diversification into adjacent health monitoring.
Within the established medical device segment, ResMed Inc. and Koninklijke Philips N.V. exemplify firms leveraging their deep clinical ties and therapy ecosystems. These companies anchor the market for devices requiring rigorous regulatory validation and medical reimbursement. In contrast, Apple Inc. occupies a position among consumer technology giants, competing on user experience and integration within broader personal wellness platforms. This firm represents the push towards seamless integration of sleep data into everyday digital health monitoring.
| Leading Market Players |
|---|
| Itamar Medical Ltd. |
| Withings |
| ResMed Inc. |
| Apple Inc. |
| Nox Medical |
| Koninklijke Philips N.V. |
| Garmin Ltd. |
| Fitbit Inc. |
| Fisher & Paykel Healthcare |
| Others |
Cost & Logistics Intelligence
Undercapacity in clinical-grade sensor production influences both supplier behavior and the pricing posture for advanced home sleep screening devices. This dynamic creates a cost advantage for vertically integrated manufacturers with in-house sensor capabilities, allowing for more aggressive market strategies.
Pricing Analysis
Premium-mid-economy pricing differentiation characterizes the home sleep screening devices market, reflecting varied device capabilities and regulatory clearances. Price differentiation stems from factors like FDA clearance for diagnostic claims and the integration of sophisticated sleep tracking algorithms. Pricing softness reflects increasing competition from consumer technology firms entering the wellness segment. Individuals purchasing for personal wellness are generally more price-sensitive, while sleep clinics prioritize validated accuracy and data interoperability over cost.
Supply Chain Analysis
Named export controls limiting flows of specialized microcontrollers and advanced sensor components influence the supply chain for home sleep screening devices. Geographic supply concentration for these critical components centers in countries like China and Taiwan. The industry relies heavily on advanced MEMS sensors and specialized plastics. Single-source vulnerability for specific diagnostic-grade sensors represents a structural risk. Distribution runs through both direct-to-consumer online retail and established medical supply outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home sleep screening devices market presents a fragmentation opportunity, as rising consumer awareness of sleep health creates distinct niches for specialized solutions.
For Market Incumbents: Harden clinical validation processes for new device iterations to counter the threat from consumer tech giants. Integrate deeper into therapy ecosystems, offering comprehensive solutions beyond screening to maintain market share. Invest in R&D for next-generation biometric sensors to extend competitive advantage in diagnostic accuracy. Leverage existing clinical ties to secure medical reimbursement for advanced devices.
For New Entrants and Emerging Players: Underserved geographies like Latin America and Southeast Asia represent the most penetrable entry point for direct-to-consumer sales models. Pediatric screening applications offer a significant white space, requiring devices and algorithms specifically validated for children. A go-to-market angle focusing on corporate wellness programs can establish early B2B traction and recurring revenue streams. Prioritize user experience and seamless integration within broader wellness platforms.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms offering subscription-based data analysis and personalized coaching services. The long-term viability of this market over the next five to ten years remains strong, driven by aging populations and chronic disease management needs. Acquisition targets should include specialized algorithm developers with robust intellectual property in machine learning for sleep analysis. The signal to watch is broader healthcare system integration of home-generated sleep data.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Acceleration | Expedites market entry for clinical-grade devices, securing diagnostic claims and reimbursement pathways. |
| Platform Integration with EHRs | Enhances clinical workflow adoption by allowing seamless data flow into Electronic Health Record systems. |
| Strategic Partnership with Telehealth Providers | Expands reach and offers comprehensive patient management, from screening to remote consultation. |
| Geographic Expansion into Underserved Markets | Captures new customer segments in regions with nascent healthcare infrastructure and growing middle classes. |
| Software Companion Development | Creates recurring revenue streams through subscription services for data analysis and personalized insights. |
Research Approach
Desk research of scientific journals, regulatory filings, and market reports preceded structured interviews with sleep clinicians, medical device engineers, and consumer health product managers. This approach combined primary insights with secondary validation to ensure a comprehensive market understanding. Bottom-up and top-down triangulation methods were applied to reconcile data discrepancies and confirm market sizing across various segments.
The analytical framework assumed stable regulatory environments and consistent consumer health-seeking behaviors across the analysis window. Segmentation dimensions modeled included device type, technology, end user, distribution channel, and regional regulatory approval status. Compound annual growth rates were derived by projecting historical trends and incorporating anticipated technological advancements. Key forecast inputs included the prevalence rates of sleep disorders and wearable device adoption rates.
Practitioners should monitor major regulatory changes, breakthrough sensor technology, and shifts in healthcare reimbursement policies for early signals of market disruption. Forecasts reflect assumptions documented at the time of analysis. Material shifts in global economic conditions or public health priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Insomnia Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Global Sleep Tech Devices Market