
 Insomnia Treatment Market | 2026-2036
Insomnia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Insomnia Treatment Market Outlook
FDA 510(k) clearance requirements for digital therapeutics is hardening the cost-of-entry calculus for insomnia app developers seeking prescription status. Pfizer Inc leverages its established psychiatric portfolio to sustain commercial traction in the prescription sleep drug segment. Takeda Pharmaceutical Company Ltd anchors its position through deep specialization in orexin receptor antagonists, a mechanism that differentiates its offerings from traditional GABA-targeting agents. Idorsia Ltd competes in the same mechanistic class, navigating European and Japanese regulatory pathways with a distinct formulation strategy.
Insomnia treatment encompasses pharmacological, behavioral, and device-based interventions designed to restore sleep onset, maintenance, or architecture through modulation of neurotransmitter systems, circadian entrainment, or conditioned arousal reduction. Prescription drugs targeting orexin or melatonin pathways require precise receptor-binding profiles and demonstrated polysomnographic efficacy, while cognitive behavioral therapy protocols demand standardized clinician training and session fidelity to achieve durable remission rates. Prescription drugs occupy the largest value pool due to reimbursement density and chronic dosing patterns, though cognitive behavioral therapy represents the fastest-expanding segment as payers in Germany and Japan mandate stepped-care protocols that prioritize non-pharmacological first-line intervention. Over-the-Counter Medications face margin compression as pharmacy chains consolidate shelf-space decisions around private-label melatonin formulations.
The FDA, EMA, and Japan's PMDA collectively govern the evidentiary standards that determine whether insomnia interventions achieve prescription or wellness classification, with divergence in endpoints—polysomnography versus patient-reported outcomes—shaping regional development priorities. The EU MDR and FDA's Software as a Medical Device framework impose distinct quality-management burdens on digital therapeutic developers that lack pharmaceutical manufacturing infrastructure. Stakeholders must monitor how CMS and national health technology assessment bodies in France and England calibrate reimbursement for digital CBT against in-person delivery costs.
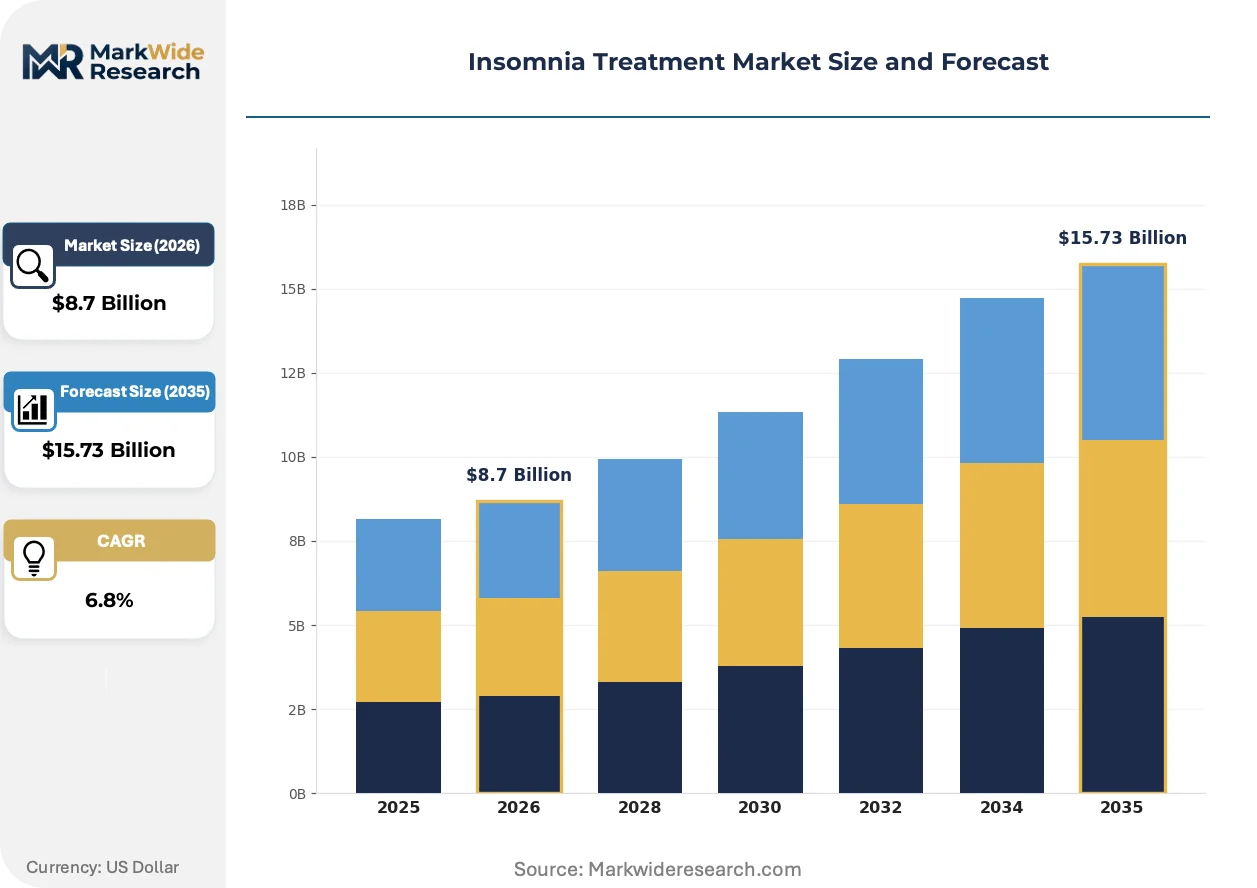
Market Dynamics
The FDA's Software as a Medical Device framework is hardening evidentiary requirements for prescription-grade digital therapeutics, forcing insomnia app developers to build pharmaceutical-grade clinical trial infrastructure that reshapes competitive entry economics.
Growth Catalysts
- Stepped-care mandates:Germany's statutory health insurers now require cognitive behavioral therapy as first-line intervention before reimbursing hypnotic drugs, expanding the addressable market for trained sleep specialists and digital platforms.
- Orexin receptor science:Advances in dual-orexin antagonist pharmacology are creating a mechanistic alternative to GABA-targeting agents with cleaner morning-after profiles.
- Employer wellness bundling:Integrated US health systems are packaging sleep disorder management into corporate contracts, creating institutional procurement channels that bypass traditional pharmacy benefit structures.
Market Restraints
- Clinical trial cost inflation:Polysomnography endpoints required by FDA and EMA demand expensive overnight facility monitoring that burdens digital therapeutic developers lacking pharmaceutical capital reserves.
- Active ingredient concentration:Melatonin API production clusters in China, exposing OTC formulation supply chains to export license volatility and quality inconsistency.
- Reimbursement lag:CMS has not established distinct billing codes for asynchronous digital CBT delivery, compressing margins for platforms competing against in-person therapy rates.
Strategic Opportunities
- Japan's aging demographic:PMDA's streamlined pathway for geriatric-targeted sleep interventions creates regulatory tailwind for orexin antagonists with demonstrated fall-risk advantages over benzodiazepine-class alternatives.
- Consumer wearable convergence:Integration of actigraphy-validated sleep staging with prescription app dosing algorithms enables closed-loop therapeutic adjustment previously impossible with standalone pharmaceuticals.
- Pharmacy channel bypass:Direct-to-patient distribution models for prescription digital therapeutics circumvent retail shelf-space consolidation that is squeezing OTC melatonin margins.
Industry Challenges
- Clinician training bottlenecks:Standardized CBT-I certification programs face capacity constraints that limit the supply of qualified therapists needed to fulfill payer mandates in Germany and England.
- Legacy EHR integration:Sleep clinic workflows require bidirectional data exchange with electronic health record systems that lack standardized APIs for digital therapeutic outcome reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insomnia Treatment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Herbal Supplements, Cognitive Behavioral Therapy End User: Hospitals, Clinics, Homecare, Telehealth Services Treatment Modality: Medication, Therapy, Lifestyle Changes, Relaxation Techniques Age Group: Adults, Adolescents, Seniors, Children |
| Companies Covered | Pfizer Inc, Sanofi SA, Takeda Pharmaceutical Company Ltd, Merck & Co Inc, Electromedical Products International Inc, Idorsia Ltd, Vanda Pharmaceuticals Inc, Teva Pharmaceutical Industries Ltd, Eisai Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insomnia Treatment Market Strategic Shifts
Digital measurement infrastructure is displacing subjective sleep diaries as the primary endpoint currency, forcing protocol redesign across both pharmaceutical and behavioral intervention developers.
Closed-loop neurostimulation devices that detect sleep-stage transitions and deliver calibrated acoustic or electrical intervention are rewriting the boundary between consumer wellness and prescription-grade therapy. Sleep disorder clinics in the United States are piloting these systems for treatment-resistant insomnia patients who have failed pharmacological and CBT protocols. The technology is compressing the traditional separation between diagnostic polysomnography and therapeutic delivery into a single reimbursable encounter.
EMA's Medical Device Regulation is imposing quality management system requirements on digital therapeutic developers that previously operated under lean software development methodologies. The regulation demands documented risk management and post-market surveillance infrastructure that mirrors pharmaceutical pharmacovigilance obligations. European insomnia app developers are responding by contracting with notified bodies earlier in development cycles, extending time-to-market timelines.
Employer-sponsored health plans are unbundling sleep management from general behavioral health contracts and negotiating standalone value-based arrangements with specialized digital CBT platforms. This procurement fragmentation is displacing the traditional primary care gatekeeper model for insomnia diagnosis and referral. The shift is most visible among self-insured Fortune 500 employers in the United States who bear direct pharmaceutical cost liability for chronic hypnotic prescribing.
Insomnia Treatment Market Segmentation
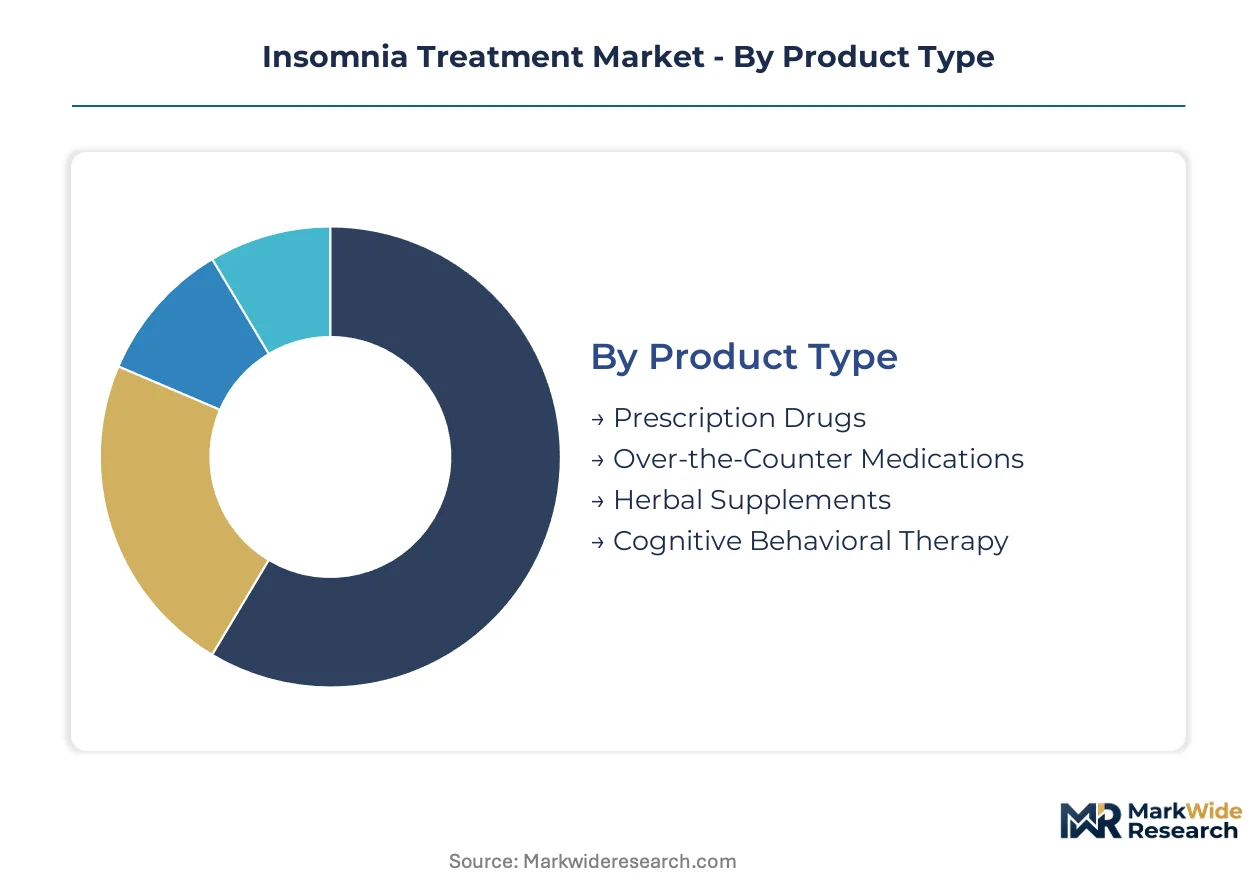
Insomnia treatment segmentation reflects divergent reimbursement densities and regulatory pathways. Prescription-grade interventions command premium pricing through pharmacy benefit structures, while behavioral and digital modalities reshape competitive entry economics.
Product Type:
Standardization dominates pharmacological segments with fixed-dose formulations, whereas behavioral interventions demand customization through clinician training intensity and protocol adaptation.
- Prescription Drugs:Orexin receptor antagonists and GABA-targeting hypnotics require polysomnography-validated efficacy endpoints for FDA and EMA approval. Demand concentrates in the United States through integrated health system formularies, constrained by CMS reimbursement lag for novel mechanisms.
- Cognitive Behavioral Therapy:Standardized CBT-I protocols with demonstrated session fidelity achieve durable remission rates superior to pharmacological maintenance. Germany's statutory insurers now mandate this first-line, expanding addressable market for trained specialists and digital platforms.
- Over-the-Counter Medications:Melatonin formulations face margin compression from pharmacy chain private-label consolidation and Chinese API supply volatility.
- Herbal Supplements:Valerian root and chamomile extracts occupy regulatory gray zones between wellness claims and therapeutic intent, limiting institutional procurement.
Leading the category by volume: Prescription Drugs. Growing fastest: Cognitive Behavioral Therapy.
End User:
Site-of-care migration from inpatient facilities to distributed delivery models reconfigures procurement authority and reimbursement mechanics.
- Telehealth Services:Asynchronous digital CBT platforms bypass geographic therapist scarcity, though CMS has not established distinct billing codes for this delivery mode. Employer wellness contracts in the United States increasingly bundle sleep management through these channels.
- Hospitals:Sleep disorder clinics within hospital systems anchor diagnostic infrastructure with polysomnography suites and specialist consultation. These facilities pilot closed-loop neurostimulation devices for treatment-resistant cases.
- Clinics:Outpatient sleep centers face EHR integration bottlenecks that complicate bidirectional data exchange with digital therapeutic platforms.
- Homecare:Direct-to-patient distribution of prescription digital therapeutics circumvents retail pharmacy consolidation affecting OTC segments.
Volume concentrates in Hospitals. Steepest expansion trajectory: Telehealth Services.
Treatment Modality:
Mechanistic differentiation between neurotransmitter modulation and conditioned arousal reduction shapes clinical trial design and regulatory evidence requirements.
- Medication:Dual-orexin antagonist pharmacology delivers cleaner morning-after profiles than legacy benzodiazepine-class alternatives, attracting development investment from Takeda and Idorsia.
- Therapy:CBT-I protocols require documented clinician certification and session fidelity to achieve payer-mandated outcomes in Germany and England.
- Lifestyle Changes:Sleep hygiene education lacks reimbursement density but supports stepped-care protocol compliance.
- Relaxation Techniques:Progressive muscle relaxation and guided imagery occupy consumer wellness markets with limited prescription classification pathways.
Medication dominates value capture. Therapy climbs the fastest on payer mandate tailwinds.
Age Group:
Regulatory pathways and safety profiles diverge sharply across developmental stages, with geriatric-focused interventions receiving streamlined PMDA review in Japan.
- Seniors:Fall-risk advantages of orexin antagonists over benzodiazepines drive PMDA regulatory prioritization in Japan's aging demographic. Polysomnography endpoints must demonstrate preserved sleep architecture without next-day impairment.
- Adults:Employer wellness bundling in the United States targets working-age populations with chronic sleep maintenance complaints.
- Adolescents:Pediatric insomnia indications face extended safety surveillance requirements that delay label expansion.
- Children:Behavioral interventions predominate given developmental concerns with pharmacological modulation of sleep systems.
Adults anchor commercial volume. Seniors gain share fastest on demographic and regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized health technology zones in Massachusetts and California concentrate insomnia treatment development, attracting venture capital into digital therapeutic platforms and neurostimulation device manufacturing.
United States
Integrated health systems bundle cognitive behavioral therapy into employer wellness contracts, bypassing traditional pharmacy benefit structures. FDA Software as a Medical Device framework imposes pharmaceutical-grade clinical trial requirements on prescription-grade sleep apps. Boston's medical device corridor pilots closed-loop neurostimulation systems for treatment-resistant patients.
Germany
Statutory health insurers mandate cognitive behavioral therapy as first-line intervention before reimbursing hypnotic drugs, expanding demand for trained sleep specialists. EU Medical Device Regulation imposes quality management obligations on digital therapeutic developers. Berlin's health technology cluster attracts notified body partnerships to accelerate certification timelines.
Japan
Aging demographics drive demand for fall-risk alternatives to benzodiazepine-class hypnotics among senior populations. PMDA maintains streamlined regulatory pathways for geriatric-targeted sleep interventions with demonstrated safety advantages. Osaka's pharmaceutical research corridor anchors orexin antagonist development programs.
United Kingdom
National Health Service stepped-care protocols prioritize non-pharmacological interventions, creating procurement channels for digital CBT platforms. National Institute for Health and Care Excellence evaluates digital therapeutic outcomes against in-person therapy costs. London's behavioral health technology cluster concentrates asynchronous therapy delivery infrastructure.
Switzerland
Specialized neurotechnology firms leverage precision manufacturing capabilities for sleep staging hardware components. Swissmedic maintains distinct evidentiary standards for prescription digital therapeutics that diverge from FDA polysomnography requirements. Basel's pharmaceutical research ecosystem supports dual-orexin antagonist formulation science.
Insomnia Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across mechanistic classes and delivery modalities. Market structure concentrates around pharmaceutical incumbents with psychiatric portfolios, biotechnology firms with receptor-specific expertise, and emerging digital therapeutic developers. Three archetypes dominate: established drug manufacturers with distribution infrastructure, specialized orexin pharmacology developers, and software-native platforms seeking prescription classification. Competitive moves center on regulatory pathway navigation and direct-to-patient distribution model construction.
Within the diversified pharmaceutical tier, Pfizer Inc and Takeda Pharmaceutical Company Ltd occupy positions reflecting distinct strategic orientations toward sleep disorder portfolios. Pfizer leverages established psychiatric drug infrastructure across multiple therapeutic categories. Takeda anchors its competitive stance through deep specialization in orexin receptor antagonist pharmacology, a mechanistic differentiation from traditional GABA-targeting agents. Idorsia Ltd represents the focused biotechnology archetype, navigating European and Japanese regulatory pathways with distinct formulation strategies in the same receptor class.
| Leading Market Players |
|---|
| Pfizer Inc |
| Sanofi SA |
| Takeda Pharmaceutical Company Ltd |
| Merck & Co Inc |
| Electromedical Products International Inc |
| Idorsia Ltd |
| Vanda Pharmaceuticals Inc |
| Teva Pharmaceutical Industries Ltd |
| Eisai Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Prescription-grade orexin antagonists command substantial premiums over legacy GABA-targeting hypnotics, a tier divergence that manifests in both pharmacy benefit reimbursement density and the capital-intensive polysomnography infrastructure required to demonstrate efficacy. This bifurcation concentrates pricing power with manufacturers possessing clinical trial capabilities while compressing margins for over-the-counter melatonin suppliers exposed to Chinese API volatility and retail consolidation.
Pricing Analysis
Short lead times for FDA-cleared digital therapeutics command premium pricing against asynchronous platforms facing CMS reimbursement lag. The market operates on a hybrid subscription-licensing structure, with price differentiation resting on certification tier (FDA 510(k) versus wellness classification) and session fidelity documentation. Pricing pressure intensifies in the OTC segment as pharmacy chains consolidate shelf-space decisions around private-label formulations. Employer wellness contracts exhibit lowest price sensitivity, while individual consumers purchasing melatonin supplements demonstrate highest elasticity.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA streamlined pathways are reshaping sourcing for geriatric-targeted sleep interventions, incentivizing local manufacturing partnerships. Active pharmaceutical ingredient production concentrates in China and India, with formulation science anchored in Switzerland and the United States. Melatonin API supply hinges on Chinese export license stability, exposing OTC manufacturers to quality inconsistency risks. Distribution runs through integrated health system formularies for prescription drugs, while digital therapeutics bypass retail pharmacy through direct-to-patient models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified CBT-I therapist scarcity constrains supply expansion across Germany and England, propping pricing for certified digital platforms capable of demonstrating session fidelity outcomes. This capacity bottleneck sustains premium reimbursement rates against uncertified wellness applications.
For Market Incumbents: Anticipate stepped-care mandate expansion by securing notified body partnerships under EU MDR before quality management deadlines harden. Orexin antagonist developers should deepen polysomnography infrastructure investments to defend against dual-mechanism entrants. Priority levers include backward integration into melatonin API supply and EHR integration capabilities that lock hospital system procurement. For New Entrants and Emerging Players: Closed-loop neurostimulation algorithms offer technology-first wedge positioning for treatment-resistant insomnia patients failing pharmacological and CBT protocols. White-space targets include Japan's geriatric segment under PMDA streamlined review and employer wellness contracts unbundling sleep from general behavioral health. Go-to-market execution should prioritize actigraphy-validated sleep staging partnerships with consumer wearable manufacturers. For Investors and Strategic Acquirers: Re-rating potential sits with digital therapeutic platforms possessing FDA prescription classification given CMS billing code establishment catalysts. Long-term viability across the analysis window favors developers with pharmaceutical-grade clinical trial infrastructure over lean software methodologies. Acquisition target archetype: asynchronous CBT platforms with demonstrated NICE evaluation outcomes. Signal to watch: employer-sponsored health plan procurement fragmentation displacing primary care gatekeeper models.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Prescription classification unlocks pharmacy benefit reimbursement density unavailable to wellness-tier competitors. |
| Notified Body Partnership | Early EU MDR engagement compresses certification timelines for digital therapeutic developers lacking pharmaceutical infrastructure. |
| Employer Wellness Contract | Direct procurement with Fortune 500 self-insured plans bypasses traditional formulary access barriers. |
| Polysomnography Infrastructure Investment | Overnight facility capabilities satisfy FDA and EMA evidentiary requirements for orexin antagonist approval. |
| Consumer Wearable Integration | Actigraphy-validated sleep staging enables closed-loop therapeutic adjustment previously impossible with standalone drugs. |
Study Parameters
Document review covered FDA 510(k) filings, EMA assessment reports, ClinicalTrials.gov registries, and statutory health insurer policy documents, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and digital health platform engineers. Secondary validation drew from CMS reimbursement databases, NICE technology appraisals, and PMDA review pathway disclosures. Bottom-up demand modeling and top-down market sizing were triangulated to establish segment boundaries.
Historical prescription volume trends were cross-referenced against panel input from payer access specialists and hospital procurement managers to anchor growth assumptions across the projection horizon. The analytical framework modeled segmentation across treatment modality, product type, end-user site-of-care, and regional regulatory cluster. CAGRs were derived from polynomial trend fitting adjusted for policy intervention timing and demographic shift trajectories. Forecast inputs incorporated stepped-care mandate diffusion rates and digital therapeutic billing code establishment probabilities.
Several conditions sit outside the modeled scope, including post-market safety surveillance outcomes affecting label expansion, unforeseen API supply disruptions from export license volatility, and regulatory divergence between FDA Software as a Medical Device framework and emerging EU AI Act provisions. Forecasts reflect documented assumptions regarding reimbursement policy stability and clinician training program capacity scaling. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Short Sleep Syndrome Treatment Market