
 Excessive Daytime Sleepiness Market | 2026-2036
Excessive Daytime Sleepiness Market Size, Share, and Industry Trends Forecast 2026-2036
Excessive Daytime Sleepiness Market Analysis
Project finance for late-stage clinical trials is reshaping competitive dynamics in excessive daytime sleepiness therapeutics. Jazz Pharmaceuticals leverages its vertically integrated rare-disease infrastructure to control specialty distribution channels. Teva Pharmaceutical Industries anchors its position through sustained R&D investment in generic modafinil formulations. Avadel Pharmaceuticals differentiates via proprietary drug-delivery technology that extends patent-protected revenue streams.
Excessive daytime sleepiness denotes a clinical syndrome of irrepressible sleep need during waking hours, quantified by Epworth Sleepiness Scale scores exceeding ten and objective measures such as mean sleep latency below eight minutes on the Multiple Sleep Latency Test. Its primary commercial purpose spans diagnostic device sales, prescription therapeutics, and employer-funded occupational health interventions. Wakefulness promoters lead prescription revenue pools due to superior efficacy in narcolepsy type 1, while behavioral therapy represents the fastest-expanding segment as payers mandate step-therapy protocols. Retail pharmacies dominate distribution volume, though online pharmacies capture margin expansion from direct-to-patient subscription models.
The FDA maintains stringent REMS requirements for sodium oxybate products, while the EMA's pharmacovigilance framework shapes post-market surveillance obligations across European markets. Japan's PMDA imposes additional ethnic bridging study requirements that delay product entry but elevate clinical evidence standards. Stakeholders must monitor evolving reimbursement criteria for digital therapeutics and home-based diagnostic platforms as payer cost-containment intensifies.
Market Dynamics
The FDA's tightened REMS protocols for sodium oxybate products are forcing manufacturers to rebuild distribution infrastructure around restricted pharmacy networks, while employer-funded occupational health screening expands the addressable patient pool beyond traditional sleep clinic referrals.
Growth Catalysts
- Commercial insurance expansion:Specialty therapy coverage in the United States now extends to narcolepsy type 2 and idiopathic hypersomnia diagnoses, broadening reimbursement eligibility for wakefulness-promoting agents.
- EMA pharmacovigilance harmonization:Standardized post-market surveillance obligations across European markets reduce regulatory duplication costs for multi-national trial sponsors.
- Epworth Sleepiness Scale digitization:Smartphone-based diagnostic tools integrated into primary care workflows accelerate patient identification and specialist referral velocity.
Market Restraints
- Sodium oxybate supply concentration:Single-source active pharmaceutical ingredient manufacturers in Western Europe create vulnerability to production disruptions and import delays.
- Generic modafinil price compression:Teva Pharmaceutical Industries and competing ANDA holders have driven unit economics below sustainable R&D recovery thresholds for novel formulations.
- Japan PMDA ethnic bridging requirements:Mandatory supplemental pharmacokinetic studies for CNS-acting agents add eighteen to twenty-four months to product launch timelines.
Strategic Opportunities
- Home-based diagnostic platforms:Wearable polysomnography devices bypass sleep center capacity constraints and capture patients in rural and underserved urban catchments.
- Digital therapeutics reimbursement:Germany's DiGA pathway and analogous frameworks in France and the Netherlands create precedent for prescription-grade behavioral intervention coverage.
- Dual orexin receptor antagonist expansion:Daridorexant and follow-on molecules are penetrating the non-narcoleptic excessive daytime sleepiness segment previously served only by off-label stimulants.
Industry Challenges
- Somnologist workforce scarcity:Fellowship-trained sleep medicine physicians concentrate in academic medical centers, creating bottlenecks for diagnostic confirmation and therapy initiation.
- REMS compliance infrastructure:Central pharmacy distribution mandates require substantial capital expenditure for cold-chain logistics and patient registry systems that generic competitors avoid.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Excessive Daytime Sleepiness Market |
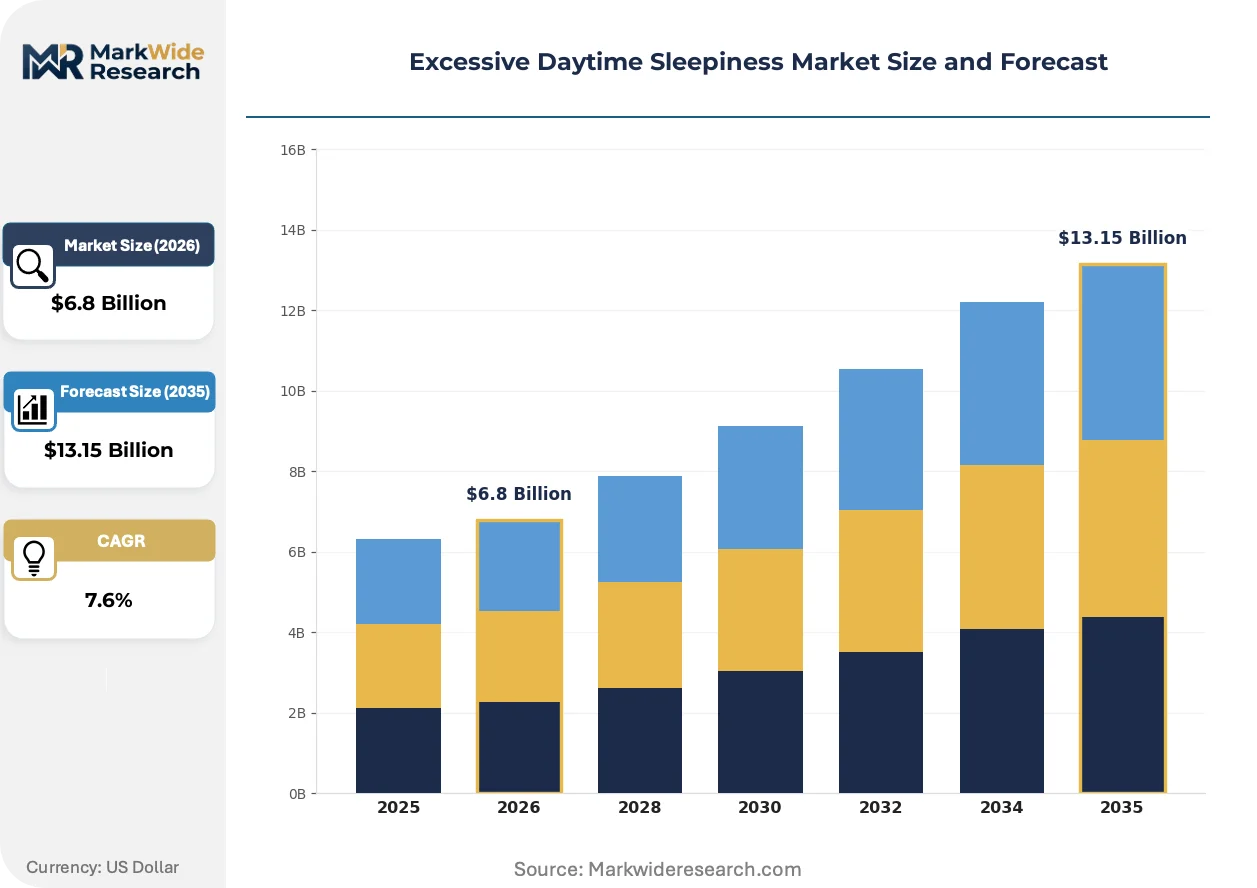
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulants, Antidepressants, Wakefulness Promoters, Melatonin Receptor Agonists Treatment Approach: Medication, Behavioral Therapy, Lifestyle Modification, Combination Therapy End User: Patients, Healthcare Providers, Caregivers, Employers Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospitals, Clinics |
| Companies Covered | Jazz Pharmaceuticals, Teva Pharmaceutical Industries, Avadel Pharmaceuticals, Axsome Therapeutics, Bioprojet Pharma, ResMed, Philips, GE Healthcare, Compumedics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Excessive Daytime Sleepiness Market Emerging Trajectories
Wakefulness therapeutics are fragmenting across mechanism-of-action categories as orexin-targeting small molecules and histamine H3 inverse agonists challenge the amphetamine-modafinil-oxybate hierarchy that dominated the prior two decades.
Once-nightly sodium oxybate formulations utilizing micropellet coating technology are collapsing the dosing frequency advantage that standard oxybate salts previously held over extended-release stimulants. Jazz Pharmaceuticals has secured priority review for its low-sodium variant, while Avadel's proprietary drug-delivery platform enables comparable pharmacokinetic profiles with reduced sodium load. Sleep specialists in the United States are accelerating adoption of these formulations to mitigate cardiovascular risk concerns and improve adherence metrics.
The EMA's revised pharmacovigilance framework for CNS-active substances now mandates real-world evidence collection through national health registries in France, Germany, and the Netherlands. This obligation compels manufacturers to fund multi-year post-authorization safety studies and integrate health technology assessment bodies earlier in clinical development. Small-cap developers without existing European infrastructure face partnership or divestiture pressures.
Employer procurement of sleep disorder screening has migrated from occupational health vendors to direct contracts with telemedicine platforms and at-home diagnostic kit providers. Large self-insured employers in the United States now subsidize Epworth Scale administration through benefits administration portals, bypassing primary care gatekeepers entirely. This channel shift concentrates volume with platforms capable of seamless electronic health record integration and same-week specialist scheduling.
Excessive Daytime Sleepiness Market Segmentation
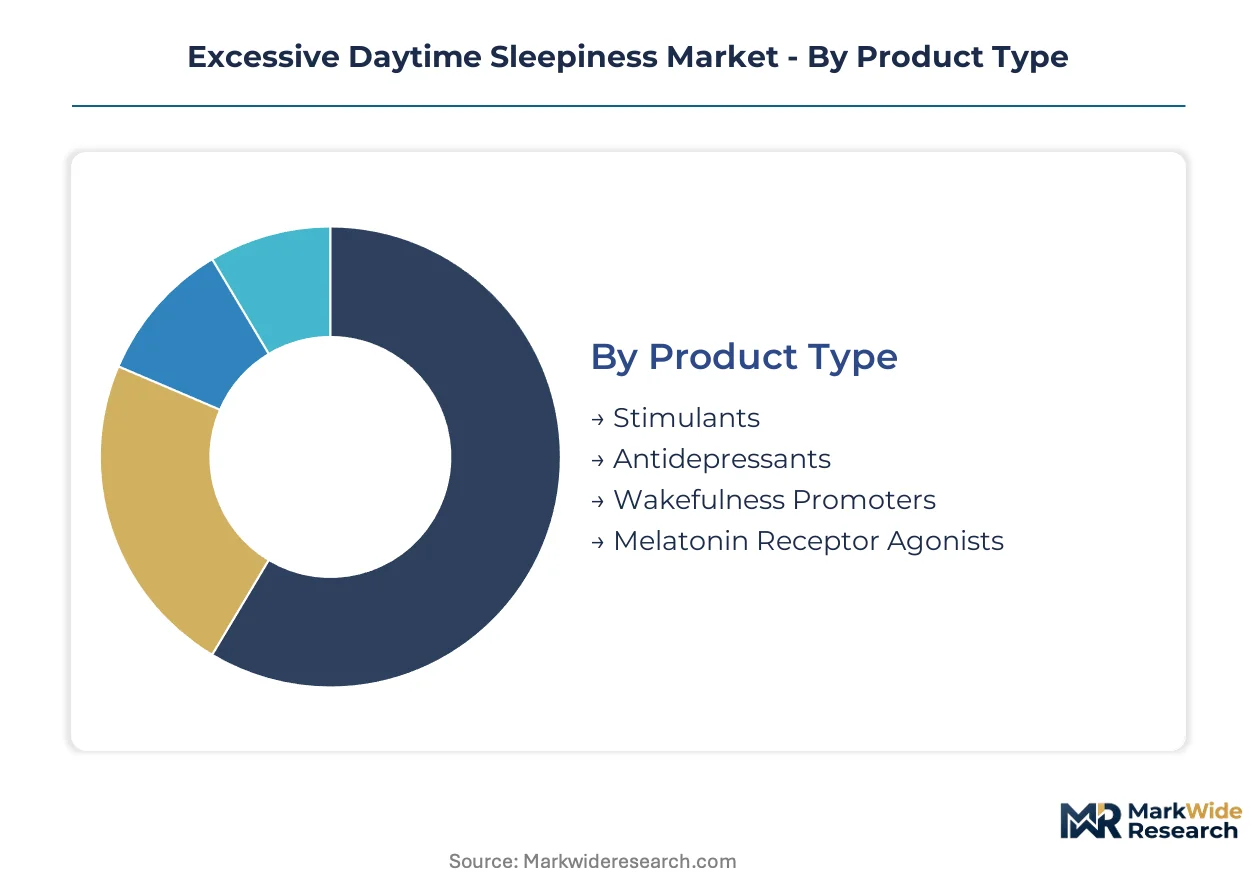
Segmentation in excessive daytime sleepiness therapeutics reveals divergent commercial strategies across mechanism classes and care delivery models. Pharmaceutical manufacturers optimize portfolio allocation between prescription stimulants and behavioral platforms, while distribution channel selection determines patient access velocity and reimbursement capture efficiency.
Product Type:
Wakefulness-promoting agents span four pharmacological classes with distinct receptor targets and regulatory profiles.
- Stimulants:Amphetamine-based compounds and methylphenidate derivatives activate dopaminergic and noradrenergic pathways to sustain cortical arousal. Demand concentrates in pediatric narcolepsy cases and residual symptom management in the United States, where DEA Schedule II classification restricts prescribing authority to specialists.
- Wakefulness Promoters:Modafinil and armodafinil operate through dopamine transporter inhibition with lower abuse liability than traditional stimulants. Prescription volume in the United States has expanded fastest among shift workers and military personnel requiring cognitive performance maintenance during extended duty cycles.
- Antidepressants:Selective serotonin reuptake inhibitors and tricyclic compounds address cataplexy and mood comorbidities in narcolepsy type 1. Venlafaxine and clomipramine dominate off-label utilization.
- Melatonin Receptor Agonists:Ramelteon and tasimelteon target circadian phase alignment rather than direct arousal enhancement. Prescribing concentrates among non-24-hour sleep-wake disorder patients with concurrent blindness.
The dominant share belongs to Wakefulness Promoters, while Melatonin Receptor Agonists are closing the gap fastest through circadian medicine expansion.
Treatment Approach:
Cost tier stratification separates reimbursed pharmaceuticals from out-of-pocket behavioral interventions.
- Medication:Prescription pharmacotherapy generates the majority of reimbursed expenditure across commercial and government payers in the United States. Sodium oxybate formulations command premium pricing through REMS-controlled distribution.
- Behavioral Therapy:Cognitive behavioral therapy for insomnia and scheduled napping protocols deliver durable symptom reduction without polypharmacy risks. Germany's DiGA pathway and analogous French reimbursement frameworks are accelerating digital therapeutic adoption.
- Lifestyle Modification:Sleep hygiene education and chronotherapy adjustment represent the lowest-cost entry point, often mandated as step-therapy prerequisites by United States commercial insurers.
- Combination Therapy:Integrated pharmacological and behavioral protocols optimize outcomes in treatment-resistant idiopathic hypersomnia. Academic medical centers in Boston and Stanford have published standardized protocols.
Medication retains the largest expenditure pool, though Behavioral Therapy is climbing the fastest as payer step-therapy mandates expand.
End User:
Customer type determines purchasing authority and decision-making criteria across the care continuum.
- Healthcare Providers:Somnologists, neurologists, and primary care physicians control prescription initiation and specialty referral patterns. Fellowship-trained sleep medicine physicians concentrate in academic medical centers, creating diagnostic bottlenecks.
- Patients:Direct-to-consumer diagnostic kit purchases and telemedicine consultations are rising among commercially insured populations seeking to bypass primary care gatekeepers.
- Caregivers:Family members of pediatric narcolepsy patients and elderly patients with neurodegenerative sleep disorders manage medication adherence and appointment scheduling.
- Employers:Self-insured corporations in the United States now fund occupational sleep disorder screening through benefits administration portals, bypassing traditional healthcare channels entirely.
Healthcare Providers command the dominant decision-making role, while Employers are gaining share fastest through direct procurement models.
Distribution Channel:
Supply concentration varies by regulatory complexity and cold-chain requirements.
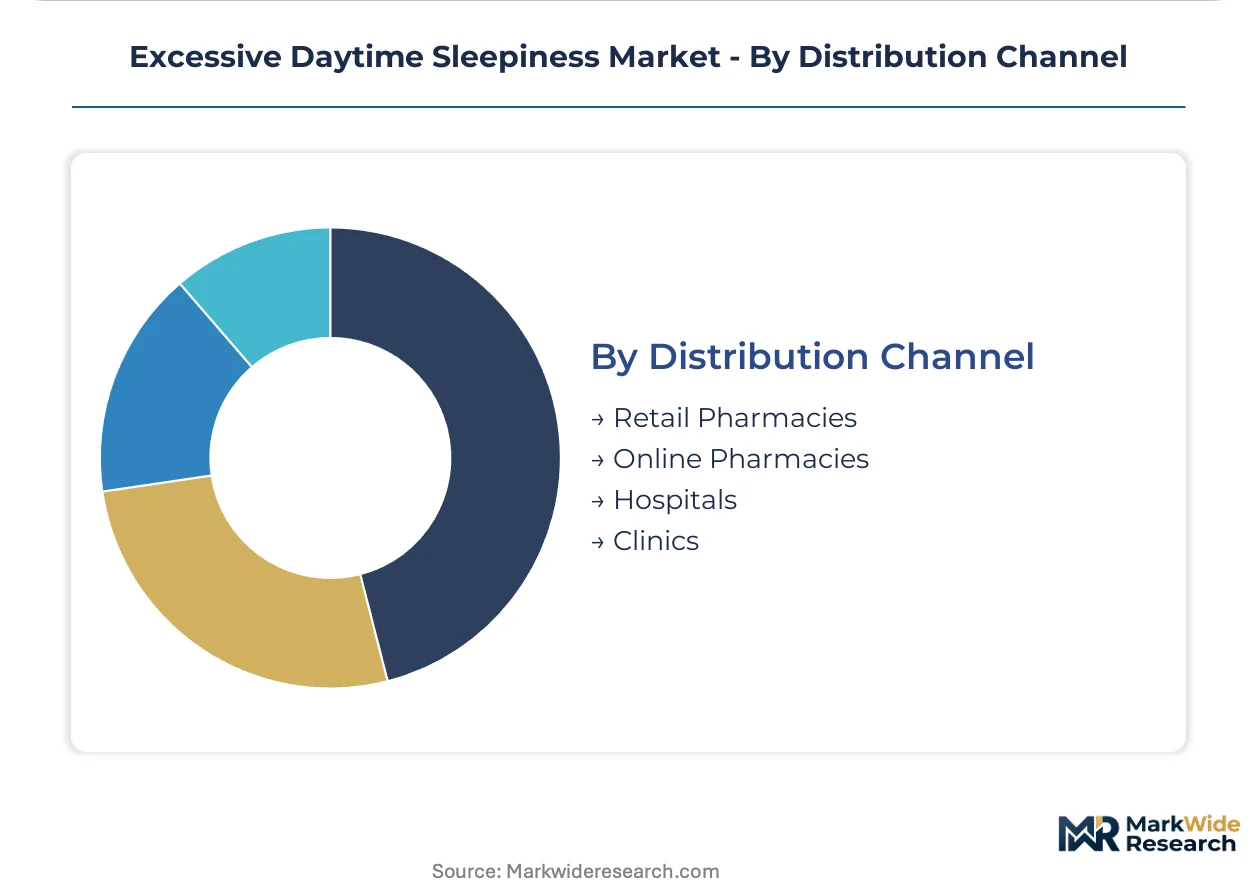
- Retail Pharmacies:Brick-and-mortar chains handle the majority of generic modafinil and antidepressant dispensing. CVS Health and Walgreens have integrated sleep health screening into MinuteClinic workflows.
- Hospitals:Inpatient sleep medicine units and academic medical center pharmacies manage sodium oxybate distribution under REMS-mandated centralized pharmacy networks.
- Online Pharmacies:Direct-to-patient subscription models capture margin expansion through automated refill management and home delivery. Ro Pharmacy and similar platforms have entered the wakefulness promoter segment.
- Clinics:Sleep center-affiliated dispensaries provide same-day therapy initiation following diagnostic confirmation. Independent sleep practices in Florida and Texas have pioneered this model.
Retail Pharmacies maintain volume leadership, while Online Pharmacies are expanding most quickly through subscription-based patient retention strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial insurance mandates and pharmacovigilance tightening are redrawing competitive boundaries across major markets. The United States concentrates premium pricing power through REMS-controlled distribution, while European harmonization reduces multi-national trial costs. Japan's ethnic bridging requirements delay entry but elevate evidence standards for orexin-targeting therapies.
United States
Employer-funded occupational health screening and expanded narcolepsy type 2 reimbursement are accelerating diagnostic velocity. The FDA maintains stringent REMS protocols for sodium oxybate products, forcing centralized pharmacy networks. Sleep medicine clusters in Boston and Stanford have pioneered standardized combination therapy protocols for treatment-resistant idiopathic hypersomnia.
Germany
DiGA pathway reimbursement for digital therapeutics is accelerating behavioral intervention adoption among statutory health insurers. The EMA's pharmacovigilance framework mandates real-world evidence collection through national health registries. Academic medical centers in Munich and Heidelberg anchor multi-year post-authorization safety studies for CNS-active substances.
Japan
PMDA ethnic bridging requirements for CNS-acting agents extend product launch timelines by eighteen to twenty-four months. The regulator's supplemental pharmacokinetic study mandates elevate clinical evidence standards for orexin-targeting molecules. Tokyo-based sleep medicine specialists increasingly coordinate with PMDA on adaptive trial designs to compress development cycles.
France
ANSM integration with EMA pharmacovigilance obligations streamlines post-market surveillance for multi-national sponsors. The country's national health registry infrastructure supports mandatory real-world evidence collection for wakefulness-promoting agents. Parisian sleep centers are piloting wearable polysomnography integration into primary care referral workflows.
United Kingdom
NHS England's specialized commissioning frameworks concentrate narcolepsy therapy initiation in designated tertiary centers. MHRA alignment with EMA pharmacovigilance standards reduces regulatory duplication for trial sponsors. London's Guy's and St Thomas' NHS Foundation Trust has established Europe's largest home-based diagnostic platform for excessive daytime sleepiness.
Excessive Daytime Sleepiness Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distribution infrastructure and formulation innovation. The market structures around three tiers: vertically integrated rare-disease platforms, sustained R&D investors in generic formulations, and proprietary drug-delivery technology developers. Strategic moves concentrate on REMS compliance infrastructure rebuilds and micropellet coating technology licensing. Partnership pressures mount for small-cap developers lacking European regulatory infrastructure.
Within the rare-disease platform tier, Jazz Pharmaceuticals exemplifies channel-controlling strategy through specialty distribution infrastructure. Teva Pharmaceutical Industries occupies a position among sustained R&D investors with generic modafinil formulation capabilities. Avadel Pharmaceuticals represents the proprietary technology archetype, extending patent-protected revenue through drug-delivery innovation.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Avadel Pharmaceuticals |
| Axsome Therapeutics |
| Bioprojet Pharma |
| ResMed |
| Philips |
| GE Healthcare |
| Compumedics |
| Others |
Supply Flow & Price Mechanics
Western European API manufacturers for sodium oxybate concentrate production capacity in Switzerland and Ireland, anchoring premium margin capture within REMS-mandated centralized pharmacy networks that generic modafinil distributors cannot access.
Pricing Analysis
REMS certification tier creates the primary spread between sodium oxybate formulations and standard wakefulness promoters. Subscription-based patient support programs dominate revenue models for controlled substances, while per-unit transactional pricing prevails in generic modafinil. Price differentiation rests on FDA REMS compliance infrastructure and cold-chain logistics capability. Cost compression in the generic stimulant tier intensifies as Teva and competing ANDA holders expand volume share. Commercial payers exhibit highest price sensitivity for behavioral therapy step-therapy prerequisites, while employer-funded occupational health programs show lowest sensitivity for diagnostic platform procurement.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates supply chain risk planning for sodium oxybate API sourcing. Manufacturing concentrates in Western Europe for controlled-substance precursors, South Korea for diagnostic device components, and India for generic modafinil active ingredients. Raw material dependencies include gamma-hydroxybutyrate sodium salt, polysomnography electrodes, and micropellet coating polymers. Single-source vulnerability in GHB precursor supply creates production disruption exposure. Distribution runs through REMS-certified specialty pharmacies for controlled substances, with retail chains handling generic volume and telemedicine platforms capturing direct-to-patient subscription growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as employer benefits portals integrate with telemedicine diagnostic workflows, collapsing traditional primary care gatekeeper functions into seamless digital referral ecosystems.
For Market Incumbents: Pre-empt generic erosion in modafinil by accelerating micropellet coating technology licensing to extend formulation patent protection. Secure backward integration into GHB precursor manufacturing to mitigate single-source API vulnerability. Reinforce REMS compliance infrastructure as a competitive moat against emerging entrants lacking capital for centralized pharmacy network buildout. For New Entrants and Emerging Players: Build out home-based diagnostic platform capabilities targeting rural and underserved urban catchments bypassed by academic medical center sleep medicine clusters. Penetrate the employer direct-procurement channel through EHR-integrated telemedicine workflows. Pursue Germany's DiGA reimbursement pathway as the most penetrable regulatory entry point for digital therapeutic behavioral interventions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rare-disease platforms possessing vertically integrated specialty distribution infrastructure. Five-to-ten year viability hinges on orexin-targeting pipeline depth and European pharmacovigilance compliance capability. Monitor FDA priority review designations for low-sodium oxybate formulations as the inflection signal for near-term revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Expansion | Centralized pharmacy network buildout secures controlled-substance distribution exclusivity against generic competitors. |
| Micropellet Coating Licensing | Proprietary drug-delivery partnerships extend patent-protected revenue streams for once-nightly sodium oxybate formulations. |
| DiGA Pathway Entry | German digital therapeutic reimbursement creates precedent for prescription-grade behavioral intervention coverage expansion. |
| Employer Portal Integration | Direct benefits administration contracts bypass traditional healthcare channels and capture occupational health screening volume. |
| Orexin Pipeline Diversification | Dual receptor antagonist development penetrates non-narcoleptic excessive daytime sleepiness segments previously served by off-label stimulants. |
Methodological Framework
Cross-validation between somnologist interviews and FDA REMS program documentation anchors the qualitative findings. Primary fieldwork engaged drug development executives at rare-disease platforms, regulatory affairs leads managing EMA pharmacovigilance submissions, formulary directors at national pharmacy benefit managers, and employer benefits administrators overseeing occupational health procurement. Secondary sources include FDA Orange Book listings, EMA EPAR assessments, ClinicalTrials.gov orexin antagonist trial registries, and German BfArM DiGA directory entries. Bottom-up patient flow modeling and top-down pharmaceutical expenditure triangulation reconcile volume and value estimates.
Calibration against historical sodium oxybate prescription trajectories and modafinil generic erosion patterns validates the analytical framework across the projection horizon. Segmentation dimensions span pharmacological mechanism class, treatment approach tier, end-user decision authority, and distribution channel regulatory complexity. CAGRs derive from epidemiological diagnosis rate projections, payer coverage expansion assumptions, and therapy substitution elasticity modeling. Forecast inputs incorporate PMDA ethnic bridging study timelines and employer screening program adoption curves.
Stress conditions across FDA REMS protocol modifications, EMA pharmacovigilance enforcement intensity, and single-source API production disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding narcolepsy type 2 reimbursement expansion and digital therapeutic category recognition. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Insomnia Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Non-Wearable Sleep Tracker Market