
 Pharmacy Market | 2026-2036
Pharmacy Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacy Market Intelligence
Specialty pharmaceutical tier is redrawing competitive boundaries in the pharmacy sector. CVS Health leverages its vertically integrated pharmacy benefits manager to control drug distribution costs across specialty categories. UnitedHealth Group anchors its market position through OptumRx, combining insurance scale with mail-order pharmacy infrastructure. Walgreens differentiates via its neighborhood pharmacy density and clinical service expansion into vaccinations and chronic care management.
Pharmacy encompasses the clinical science of preparing, dispensing, and reviewing medications, requiring cold-chain logistics for biologics, compliance with USP <797> sterile compounding standards, and inventory systems tracking lot numbers and expiration dates. Its commercial purpose centers on ensuring safe, effective, and accessible medication therapy for acute and chronic conditions. Prescription drugs dominate value flows, while specialty pharmaceuticals capture concentrated margin pools due to limited distribution networks and high-touch patient support requirements. Online pharmacies represent the fastest-expanding sales channel, though retail pharmacies sustain the highest prescription volume throughput.
FDA, DEA, and state boards of pharmacy collectively govern drug safety, controlled substance scheduling, and dispensing licensure, creating compliance barriers that favor scaled operators with dedicated regulatory affairs teams. HIPAA privacy rules and Medicare Part D reimbursement policies further structure how pharmacies interact with patients and payers. Stakeholders must monitor biosimilar approval trajectories and state-level scope-of-practice expansions for pharmacist prescribing authority.
Market Dynamics
Specialty pharmaceutical distribution is concentrating around cold-chain logistics networks and limited distribution agreements, forcing retail pharmacies to either acquire capabilities or exit high-margin biologic categories entirely.
Growth Catalysts
- IRA Medicare Price Negotiation:The Inflation Reduction Act's drug pricing provisions expand patient affordability for ten selected high-expenditure medications, redirecting volume toward pharmacies with strong Medicare Part D formulary alignment.
- Oncology Biosimilar Infusion:FDA's accelerated approval pathway for interchangeable biosimilars is expanding therapeutic alternatives in immunology and oncology, creating dispensing opportunities for pharmacies with clinical pharmacist staffing.
- Japan's Super-Aging Demographics:METI's healthcare infrastructure investments support community pharmacy networks managing polypharmacy in the world's oldest population, establishing a template for chronic disease management at scale.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing clusters in India and China create single-source dependencies for generic antibiotics and oncology staples, exposing formularies to geopolitical disruption.
- 340B Program Compression:HRSA's evolving compliance requirements and manufacturer litigation against contract pharmacy expansion are narrowing margin pools for safety-net hospitals and their affiliated dispensaries.
- Cold-Chain CAPEX Burden:USP <797> sterile compounding upgrades and biologics storage infrastructure demand seven-figure facility investments that independent operators cannot amortize across limited prescription volumes.
Strategic Opportunities
- Pharmacist Prescribing Authority:State-level scope-of-practice expansions in Idaho, New Mexico, and California authorize point-of-care testing and chronic disease protocol prescribing, capturing primary care encounters that bypass physician offices.
- Digital Therapeutic Integration:FDA-cleared prescription software for substance use disorder and insomnia creates a new reimbursement category requiring pharmacy benefit manager formulary placement and patient onboarding support.
- Last-Mile Biologics Delivery:Cell and gene therapies requiring patient-specific cold-chain handling open specialty courier and home-infusion coordination services beyond traditional dispensing margins.
Industry Challenges
- Pharmacist Workforce Compression:Graduation rates from ACPE-accredited programs lag retirement waves in rural counties, forcing chains to deploy central-fill automation or reduce operating hours.
- Payer Reimbursement Lag:DIR fee clawbacks and NADAC pricing delays create cash-flow gaps between dispensing and actual payment, squeezing working capital for inventory-intensive operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacy Market |
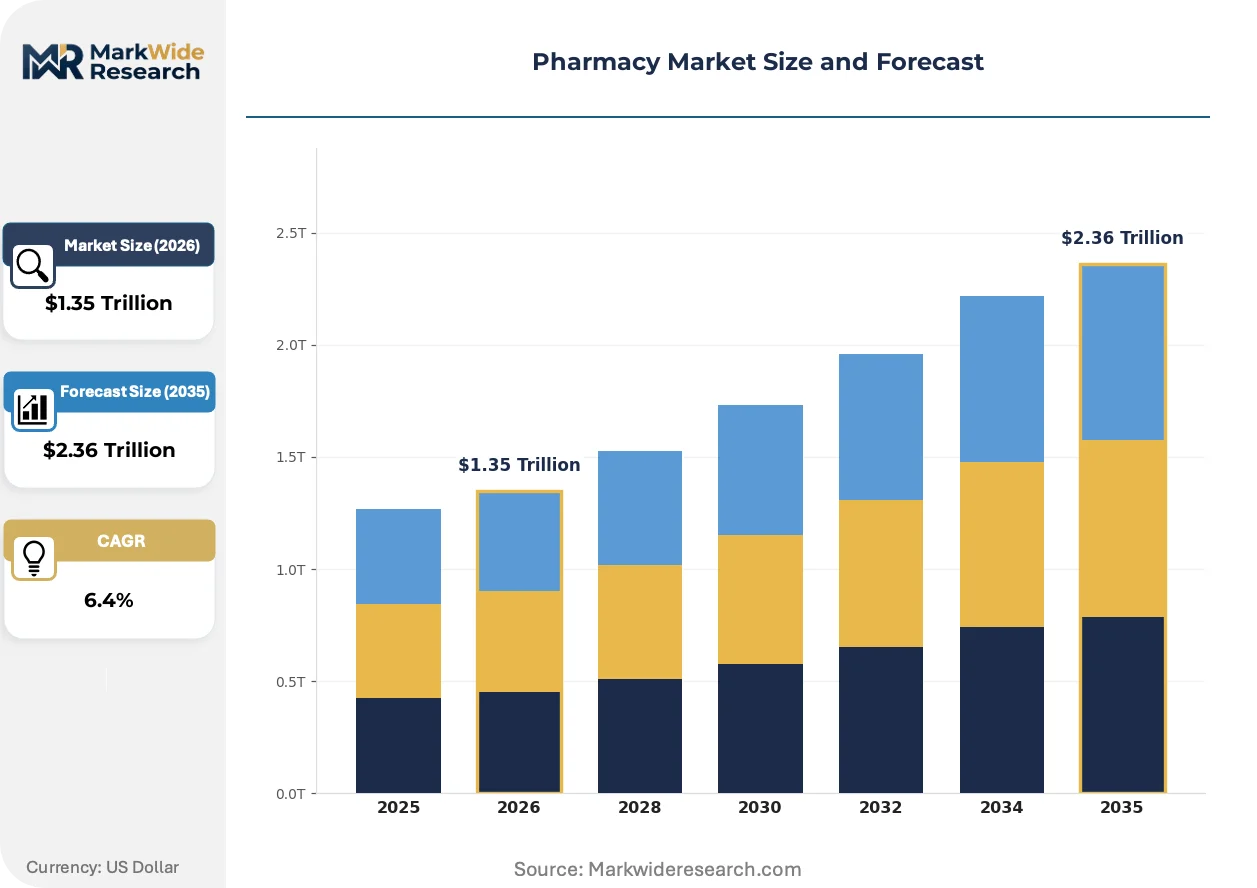
| Market Size in 2026 | $1.35 Trillion |
| Market Size in 2035 | $2.36 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Generic Drugs, Specialty Pharmaceuticals Sales Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Wholesale Distributors End User: Patients, Healthcare Providers, Pharmacies, Clinics Therapy Area: Cardiovascular, Oncology, Gastroenterology, Neurology |
| Companies Covered | CVS Health, UnitedHealth Group, Cigna, Walgreens, Express Scripts, Prime Therapeutics, Humana, OptumRx, Kaiser Permanente, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacy Market Strategic Shifts & Innovations
Automation and artificial intelligence are restructuring pharmacy operations from dispensing accuracy to clinical decision support, while regulatory pressure on pricing transparency accelerates technology deployment.
Robotic dispensing systems is bifurcating the market between high-volume central-fill facilities and reduced-footprint retail locations. CVS Health and Walgreens Boots Alliance are deploying autonomous pill-counting and vial-labeling infrastructure at scale, compressing labor costs per prescription by consolidating fulfillment into regional hubs while maintaining patient-facing consultation points in neighborhood settings.
EMA's Clinical Trial Regulation (CTR) harmonizes protocol submission and safety reporting across EU member states, reducing redundant national approvals for multi-site pharmaceutical studies. This regulatory streamlining accelerates patient access to novel therapies in Germany, France, and Italy, where national health technology assessment bodies previously imposed sequential review delays.
Direct-to-consumer telehealth platforms are disintermediating traditional primary care prescribing channels, routing patients through asynchronous consultations to affiliated mail-order pharmacies. This channel shift concentrates volume with vertically integrated digital health operators in the United States, where state licensure compacts enable cross-border practitioner deployment and centralized fulfillment.
Pharmacy Market Segmentation
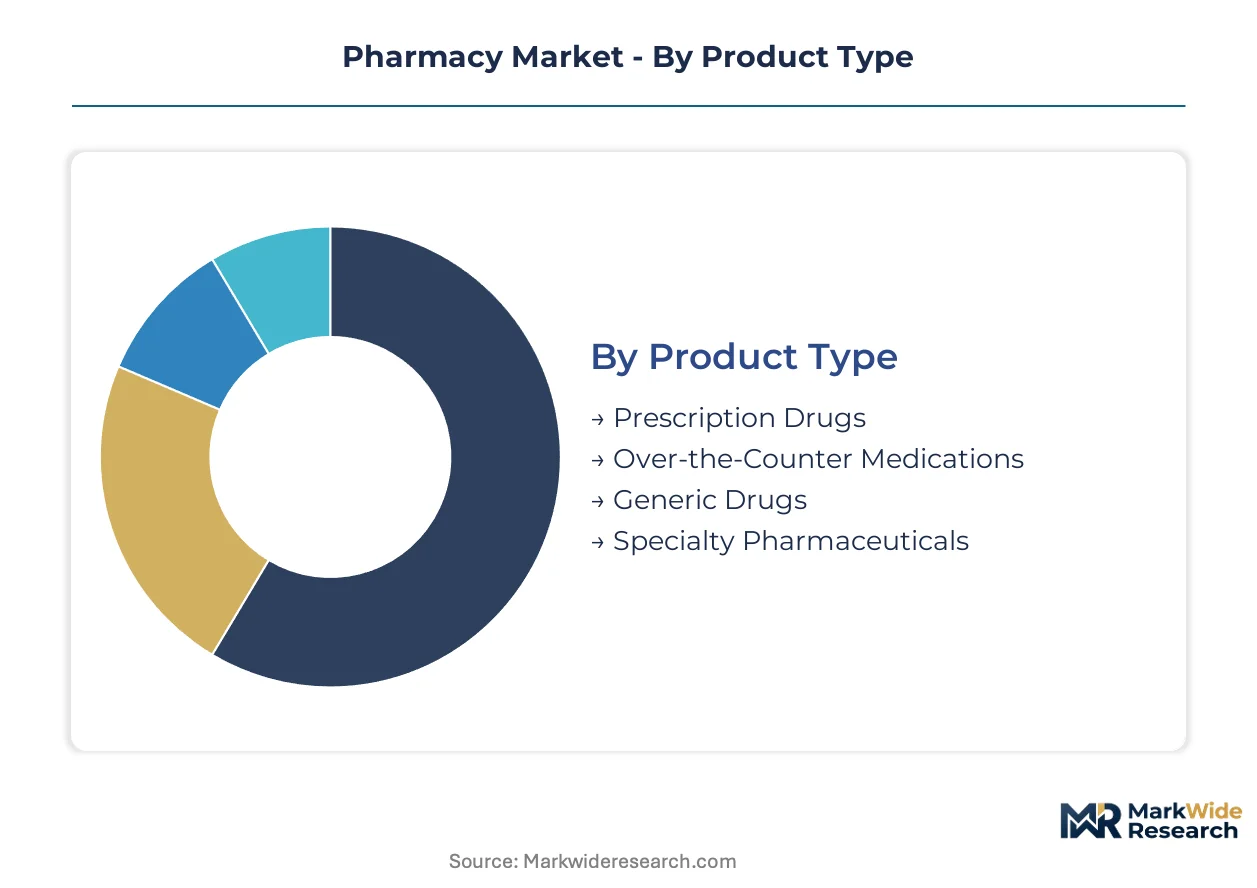
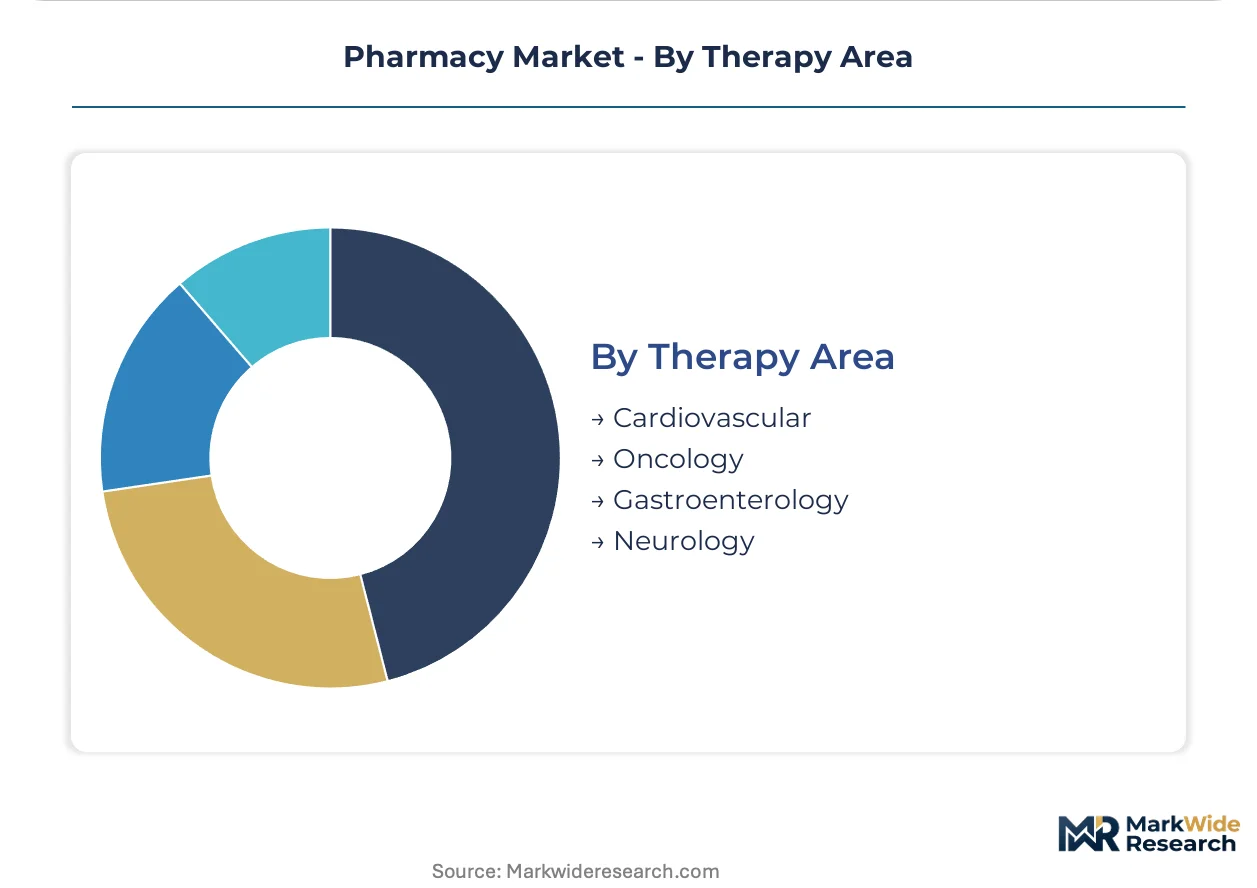
Pharmacy market segmentation reveals divergent margin structures across product tiers and distribution channels. Specialty pharmaceuticals concentrate value capture in limited distribution networks, while channel fragmentation between retail and digital platforms reshapes patient access patterns. Therapy area concentration in oncology and immunology drives cold-chain infrastructure investments.
Product Type:
Prescription drugs dominate domestic volume flows, while specialty pharmaceuticals generate disproportionate export-led revenue through cross-border biologic licensing.
- Prescription Drugs:Branded small-molecule formulations requiring physician authorization and insurance prior authorization processing. Demand concentrates in Medicare Part D formularies across Florida, Texas, and California, driven by polypharmacy management in populations over 65.
- Specialty Pharmaceuticals:High-cost biologics and cell therapies demanding cold-chain logistics and patient support programs. Oncology and immunology applications in Boston, Basel, and Singapore research corridors anchor global demand, constrained by limited distribution agreements and REMS compliance requirements.
- Generic Drugs:FDA-approved bioequivalent alternatives to off-patent branded molecules. Indian and Chinese API dependencies shape procurement patterns for antibiotics and cardiovascular staples.
- Over-the-Counter Medications:Self-selected remedies for acute symptoms and preventive care. Convenience retail placement in urban centers drives volume, with seasonal flu and allergy categories showing pronounced cyclicality.
Prescription drugs command the established base. The steepest expansion runs through specialty pharmaceuticals.
Sales Channel:
Channel economics stratify by fulfillment complexity, with automated central-fill operations achieving cost structures unavailable to traditional storefront dispensaries.
- Retail Pharmacies:Neighborhood-based dispensing with face-to-face clinical consultation capabilities. Vaccination services and chronic disease protocol management in CVS Health and Walgreens locations anchor patient loyalty.
- Online Pharmacies:Mail-order fulfillment integrated with telehealth prescribing platforms. Asynchronous consultation routing through Ro and Hims concentrates volume with vertically integrated digital operators leveraging state licensure compacts.
- Hospital Pharmacies:Inpatient and outpatient dispensing tethered to electronic health record systems. 340B program participation shapes margin profiles for safety-net institutions.
- Wholesale Distributors:McKesson and AmerisourceBergen networks managing bulk procurement and inventory financing for independent pharmacies. Cold-chain capabilities determine biologic category access.
Retail pharmacies retain volume leadership. Online pharmacies are gaining share fastest through telehealth integration.
End User:
Patient-directed consumption patterns differ markedly from institutional procurement, with reimbursement complexity favoring intermediaries over direct payment.
- Patients:Individual consumers navigating formulary tiers and copay accumulator programs. Medicare Advantage enrollment growth in Sun Belt states redirects dispensing toward preferred pharmacy networks.
- Healthcare Providers:Physician practices and accountable care organizations managing population health outcomes. E-prescribing mandates and real-time benefit tools reshape prescribing behavior.
- Pharmacies:Intermediary dispensing operations purchasing through wholesale or direct manufacturer agreements. DIR fee structures and NADAC pricing create working capital pressure.
- Clinics:Federally qualified health centers and specialty infusion centers requiring limited distribution product access. Biosimilar adoption rates vary by therapeutic protocol sophistication.
Patients generate the prescription volume base. Healthcare providers are expanding fastest through value-based contracting.
Therapy Area:
Oncology and immunology command premium pricing tiers, while cardiovascular maintenance therapies anchor generic substitution rates.
- Oncology:Targeted therapies and immuno-oncology agents requiring biomarker testing and prior authorization navigation. MD Anderson, Memorial Sloan Kettering, and Dana-Farber centers concentrate trial enrollment and early adoption.
- Cardiovascular:Statins, antihypertensives, and anticoagulants with established generic penetration. Medicare Star Ratings programs drive adherence monitoring investments.
- Gastroenterology:Biologic therapies for inflammatory bowel disease and hepatitis C curative regimens. Prior authorization backlogs create treatment initiation delays.
- Neurology:Multiple sclerosis, epilepsy, and migraine therapeutics with complex titration protocols. Specialty pharmacy coordination manages adverse event reporting requirements.
Cardiovascular therapies command the established base. The steepest expansion runs through oncology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in India and China concentrate upstream supply, while downstream dispensing and specialty pharmacy services anchor in mature healthcare markets with aging demographics and complex reimbursement systems.
United States
Medicare Part D enrollment expansion and IRA price negotiation provisions drive dispensing volume toward preferred pharmacy networks. FDA's Drug Competition Action Plan accelerates generic approvals, reshaping formulary composition. CVS Health and Walgreens Boots Alliance operate dense retail footprints across Florida, Texas, and California, integrating vaccination services and chronic care protocols.
Germany
EMA's Clinical Trial Regulation harmonizes multi-site pharmaceutical studies, reducing redundant national approvals for novel therapy access. Statutory health insurance funds negotiate reimbursement through the Federal Joint Committee's health technology assessment processes. Berlin, Munich, and Frankfurt clusters concentrate hospital pharmacy networks managing oncology biologics and biosimilar substitution protocols.
Japan
METI healthcare infrastructure investments support community pharmacy networks managing polypharmacy in the world's oldest population. PMDA accelerated review pathways for regenerative medicines and cell therapies expand specialty dispensing requirements. Tokyo, Osaka, and Nagoya metropolitan areas anchor cold-chain logistics hubs for biologic distribution to regional medical centers.
India
CDSCO's streamlined approval processes for biosimilars and generic formulations support export-led manufacturing scale. Production gravity for active pharmaceutical ingredients concentrates in Hyderabad, Ahmedabad, and Mumbai corridors. Domestic pharmacy retail consolidation accelerates through Apollo Pharmacy and MedPlus chains expanding beyond southern and western state strongholds.
United Kingdom
NHS England's pharmacy contract framework redirects dispensing volume toward integrated primary care networks managing long-term conditions. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for innovative medicines. London, Manchester, and Birmingham clusters concentrate hospital pharmacy operations with 340B-equivalent margin structures for specialist commissioning arrangements.
Pharmacy Market Key Industry Players
Concentration sits with vertically integrated pharmacy benefit managers controlling formulary placement and mail-order fulfillment. Three distinct archetypes populate the competitive set: insurance-owned PBM operations combining claims data with dispensing infrastructure; retail pharmacy chains leveraging neighborhood density for clinical service attachment; and specialty pharmacy pure-plays commanding limited distribution agreements for high-touch biologic therapies. Dominant competitive moves include central-fill automation deployment to compress labor costs per prescription, and strategic partnerships with telehealth platforms to capture asynchronous consultation routing.
Within the insurance-PBM integrated tier, CVS Health and UnitedHealth Group exemplify archetype dominance through captive pharmacy benefits management. Walgreens occupies a position representing retail pharmacy chain consolidation, anchoring neighborhood clinical service expansion. These three entities collectively illustrate how scale advantages in data integration, reimbursement negotiation, and cold-chain infrastructure create defensive positioning against independent operator displacement.
| Leading Market Players |
|---|
| CVS Health |
| UnitedHealth Group |
| Cigna |
| Walgreens |
| Express Scripts |
| Prime Therapeutics |
| Humana |
| OptumRx |
| Kaiser Permanente |
| Others |
Cost & Logistics Intelligence
Biosimilar substitution for reference biologics is redrawing procurement geography and margin structures simultaneously. Indian and Chinese API manufacturers capture cost-sensitive generic volume while cold-chain biologic dispensing concentrates in United States, German, and Japanese specialty pharmacy networks with seven-figure infrastructure investments.
Pricing Analysis
Medicare Part D reimbursement tiers dictate the pricing tier structure across retail and mail-order channels. Three-tier pricing structure across premium specialty, standard branded, and economy generic levels reflects formulary placement and prior authorization burden. Cost compression in the generic antibiotic segment is intensifying because NADAC pricing lags spot API costs by 90-180 days. Hospital 340B program participants exhibit lowest price sensitivity; cash-pay independent pharmacy customers face highest out-of-pocket exposure.
Supply Chain Analysis
Biologics inventory cycles extending 45-90 days strain working capital for independent operators lacking manufacturer consignment arrangements. Active pharmaceutical ingredient production draws from India, China, and limited European fermentation capacity. Cold-chain packaging, sterile compounding equipment, and lot-tracked inventory systems constitute critical input dependencies. Single-source vulnerability concentrates in oncology API clusters around Hyderabad and Shanghai. Distribution runs through McKesson and AmerisourceBergen wholesale networks with last-mile specialty courier partnerships for patient-specific cell therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with independent specialty pharmacies as limited distribution agreements and REMS compliance requirements create defensible niches beyond retail chain reach. The shift toward home infusion and patient-specific biologics fragments volume away from centralized hospital dispensing.
For Market Incumbents: Fortify limited distribution agreement portfolios through REMS-certified facility investments in Boston, Basel, and Singapore research corridors. Acquire cold-chain courier capabilities or lock in exclusive partnerships before independent operators capture cell therapy coordination margins. Scale central-fill automation to compress labor costs per prescription while maintaining neighborhood consultation points for vaccination and chronic care attachment.
For New Entrants and Emerging Players: Last-mile biologics delivery coordination represents the service-layer gap where vertically integrated PBM-pharmacy combinations under-serve patient-specific cold-chain requirements. Target independent oncology practices in Sun Belt Medicare Advantage expansion markets lacking in-house infusion capacity. Pursue white-label partnerships with telehealth platforms seeking pharmacy fulfillment without captive infrastructure buildout.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty pharmacy pure-plays holding limited distribution agreements for immunology and rare disease categories. Five-to-ten year viability hinges on biosimilar adoption velocity and state-level pharmacist prescribing authority expansion. Monitor FDA interchangeable biosimilar approval trajectories as inflection indicator for reference biologic pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS-Certified Facility Expansion | Unlocks limited distribution oncology and immunology dispensing previously restricted to hospital outpatient settings. |
| Central-Fill Automation Deployment | CVS Health and Walgreens regional hubs achieve labor cost compression unavailable to storefront-only competitors. |
| Telehealth Platform Partnership | Captures asynchronous consultation routing through Ro and Hims affiliated mail-order pharmacy volume concentration. |
| Cold-Chain Courier Acquisition | Secures patient-specific cell and gene therapy last-mile coordination beyond traditional wholesale distribution margins. |
| Pharmacist Prescribing Protocol Development | Idaho, New Mexico, and California scope expansions enable point-of-care chronic disease management bypassing physician offices. |
Research Approach
Operator-level perspectives from specialty pharmacy directors, PBM formulary managers, hospital procurement officers, and cold-chain logistics coordinators anchored the qualitative base. Primary interviews combined with secondary validation against FDA Orange Book filings, CMS Medicare Part D enrollment data, 340B program reports, and EMA biosimilar assessment summaries. Bottom-up prescription volume modeling and top-down healthcare expenditure triangulation cross-checked segment-level outputs.
Sensitivity analysis tested reimbursement policy shifts and biosimilar penetration scenarios across the analysis window. Segmentation dimensions modeled include product type, sales channel, therapy area, and regional regulatory cluster. CAGRs derived from polynomial trend fitting to historical dispensing volume trajectories adjusted for IRA Medicare price negotiation implementation and PMDA accelerated review pathway expansion for regenerative medicines.
Underlying assumptions cover stable API supply from Indian and Chinese manufacturing clusters, with deviation risk concentrated in geopolitical trade restriction and cold-chain infrastructure investment pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Fucosidosis Therapeutics Market