
 Sleep Study Equipment Market | 2026-2036
Sleep Study Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Study Equipment Market Analytics
Subscription-based software for remote sleep data interpretation is expanding the addressable market beyond hardware sales. ResMed leverages cloud-connected analytics platforms to sustain recurring revenue from home apnea monitoring. Koninklijke Philips anchors its position through integrated diagnostic-to-therapy workflows across hospital networks. Nihon Kohden specializes in high-channel polysomnography systems for research-grade accuracy.
Sleep study equipment encompasses instruments that record physiological signals—electroencephalography, electrooculography, electromyography, respiratory airflow, and blood oxygen saturation—during sleep to diagnose disorders such as obstructive sleep apnea and narcolepsy. Polysomnography systems remain the clinical gold standard, though their capital intensity limits placement to hospitals and dedicated sleep clinics with trained technicians. Home sleep apnea test devices represent the fastest-growing product category, capturing margin pools from patients seeking lower-cost alternatives to in-lab studies. Wire-free devices and wearable sensors within the technology dimension are displacing tethered acquisition systems, while cloud-based platforms concentrate data processing and report generation away from bedside hardware.
The FDA governs premarket clearance and post-market surveillance for sleep diagnostic devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements and unique device identification mandates across European markets. ISO 14155 standards for clinical investigation of medical devices shape protocol design for manufacturers seeking regulatory approval in multiple jurisdictions. Stakeholders must monitor how reimbursement policy for home-based testing evolves against in-lab study coverage, as this balance will determine capital allocation between portable and fixed diagnostic platforms.
Market Dynamics
Wire-free sensor technology is compressing the installed base of tethered polysomnography systems while cloud-based data interpretation platforms redistribute margin pools from hardware vendors to software providers.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated premarket clearance for home sleep apnea test devices reduces time-to-market for portable diagnostic manufacturers targeting US home care settings.
- EU Medical Device Regulation clinical evidence requirements:Stricter post-market surveillance mandates for polysomnography systems drive replacement demand at German sleep clinics seeking compliant hardware.
- Artificial intelligence-assisted sleep staging:Automated electroencephalography pattern recognition reduces technician interpretation burden and expands diagnostic throughput at understaffed facilities.
Market Restraints
- Capital intensity of high-channel polysomnography:Research-grade systems requiring 32+ acquisition channels demand six-figure investments that constrain placement to academic medical centers.
- Semiconductor component concentration:Supply bottlenecks for specialized analog-to-digital converters used in respiratory airflow sensors originate from East Asian foundry networks.
- Reimbursement compression for in-lab studies:Medicare physician fee schedule reductions for facility-based polysomnography depress return-on-investment calculations for hospital sleep center expansions.
Strategic Opportunities
- Underpenetrated rural US markets:Telemedicine-enabled home sleep apnea testing with mail-back devices addresses diagnostic access gaps in non-metropolitan counties lacking board-certified sleep physicians.
- Integration of peripheral arterial tonometry with pulse oximetry:Hybrid sensor architectures enable single-device diagnosis of both obstructive and central sleep apnea subtypes.
- Subscription revenue models:Cloud-connected analytics platforms generate recurring income streams from continuous positive airway pressure adherence monitoring beyond initial device sale.
Industry Challenges
- Polysomnographic technologist shortage:Registered sleep technologist certification programs graduate insufficient candidates to staff expanded diagnostic capacity at health systems.
- Interoperability with electronic health record systems:Proprietary data formats from competing device manufacturers complicate integration into Epic and Cerner clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Study Equipment Market |
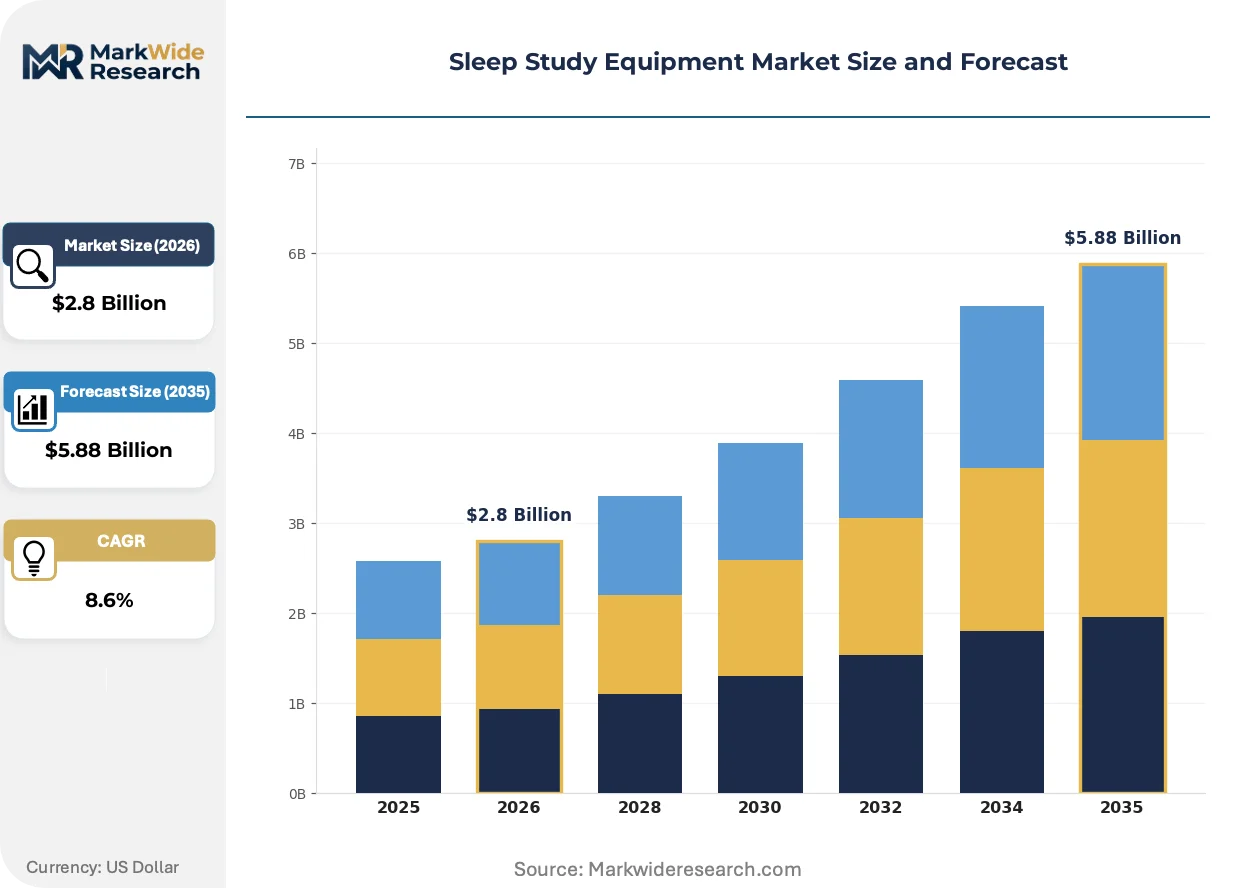
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polysomnography Systems, Home Sleep Apnea Test Devices, Sleep Monitors, Actigraphy Devices End User: Hospitals, Sleep Clinics, Home Care Settings, Research Institutions Technology: Wire-Free Devices, Wearable Sensors, Software Solutions, Cloud-Based Platforms Application: Sleep Disorders Diagnosis, Patient Monitoring, Research Studies, Therapy Evaluation |
| Companies Covered | SomnoMed, Natus Medical, ResMed, Inspire Medical Systems, ZOLL Itamar, Koninklijke Philips, Nihon Kohden, Compumedics, Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Study Equipment Market Evolving Landscape
Diagnostic modality boundaries are dissolving as wearable form factors capture signals previously requiring laboratory instrumentation, while artificial intelligence shifts clinical labor from acquisition to interpretation.
Photoplethysmography-based oxygen saturation monitoring is electrifying consumer-accessible sleep tracking. Smartwatch manufacturers incorporate medical-grade SpO2 sensors that approach diagnostic threshold accuracy for apnea screening. Sleep clinics now face patient self-referrals armed with weeks of nocturnal data, compressing the traditional gatekeeper role of in-lab polysomnography.
The EU Medical Device Regulation's unique device identification mandate is restructuring European supply chains. Manufacturers must embed machine-readable identifiers on every polysomnography electrode and airflow sensor, increasing production complexity. German diagnostic equipment distributors report extended lead times as vendors reconfigure labeling systems and quality management documentation.
Patients are bypassing traditional physician referral channels for sleep disorder diagnosis. Direct-to-consumer home sleep apnea test kits, ordered through telehealth platforms and fulfilled by mail-order device companies, capture cases that previously entered the healthcare system through primary care gatekeepers. This channel disintermediation concentrates in the United States, where high-deductible health plans heighten price sensitivity for in-lab study copayments.
Sleep Study Equipment Market Segmentation
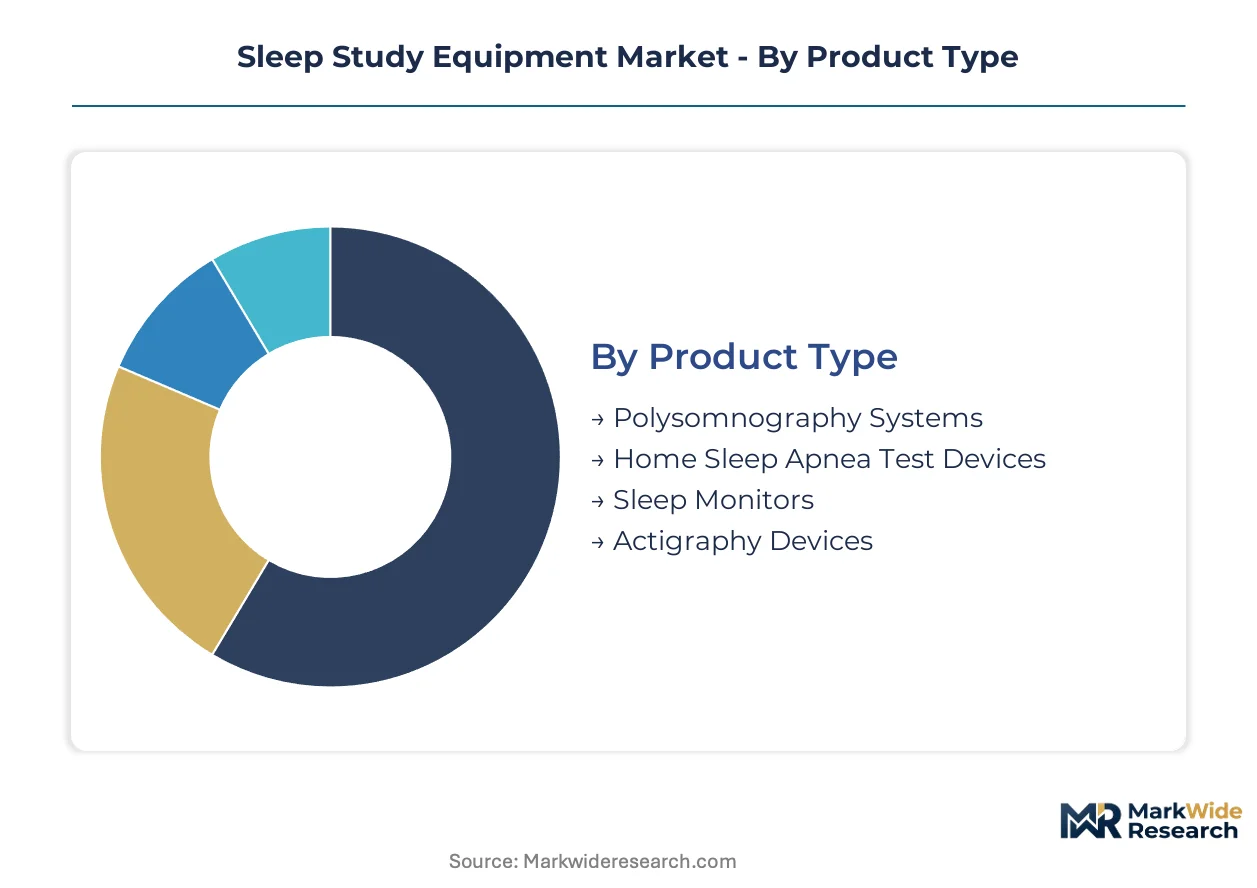
Segmentation in sleep study equipment reveals divergent capital deployment strategies across clinical and consumer-facing modalities. Hardware-intensive polysomnography systems demand facility infrastructure and trained technologists, while portable diagnostics open addressable markets through lower patient acquisition costs and reduced reimbursement friction.
Product Type:
Capital intensity varies dramatically across this category, with multi-channel acquisition systems requiring six-figure investments against sub-thousand-dollar home diagnostics.
- Polysomnography Systems:Multi-parameter acquisition platforms record electroencephalography, electrooculography, electromyography, respiratory airflow, and blood oxygen saturation through 16-32+ channels. German sleep clinics are expanding procurement as EU Medical Device Regulation compliance deadlines approach for existing installed bases.
- Home Sleep Apnea Test Devices:Portable monitors capture respiratory effort, airflow, and oxygen saturation through simplified sensor arrays designed for unsupervised patient use. United States home care settings drive uptake as high-deductible health plans heighten price sensitivity for in-lab study copayments.
- Sleep Monitors:Bedside or mattress-integrated devices track movement, breathing patterns, and environmental factors without electrode attachment.
- Actigraphy Devices:Wrist-worn accelerometers measure sleep-wake cycles through motion detection for circadian rhythm assessment.
Polysomnography systems absorb the bulk of installed capacity; home sleep apnea test devices are expanding most quickly.
End User:
Customer type determines reimbursement pathway complexity and device specification requirements, from hospital-grade regulatory compliance to consumer-accessible simplicity.
- Hospitals:Academic medical centers deploy high-channel polysomnography for complex diagnostic cases and surgical clearance protocols. Medicare physician fee schedule reductions for facility-based studies compress return-on-investment calculations for sleep center expansions.
- Sleep Clinics:Dedicated diagnostic facilities balance throughput volume against technologist staffing constraints. Board-certified sleep physician shortages in non-metropolitan United States counties limit geographic expansion despite patient demand.
- Home Care Settings:Direct-to-patient delivery models bypass traditional referral channels through telehealth-integrated mail-back devices.
- Research Institutions:Multi-site clinical trials demand standardized acquisition protocols and centralized data repositories.
Hospitals and sleep clinics dominate current revenue; home care settings are climbing the fastest as channel disintermediation accelerates.
Technology:
Technology choice determines margin pool distribution between hardware vendors and software providers, with cloud architectures shifting value toward recurring revenue platforms.
- Wire-Free Devices:Untethered sensor networks eliminate patient discomfort and technician setup time associated with traditional polysomnography cabling. ResMed and Koninklijke Philips anchor competitive positioning through proprietary radio-frequency protocols that lock in ecosystem continuity.
- Wearable Sensors:Photoplethysmography-based smartwatches approach diagnostic threshold accuracy for apnea screening, compressing the traditional gatekeeper role of in-lab studies.
- Software Solutions:Artificial intelligence-assisted sleep staging automates electroencephalography pattern recognition.
- Cloud-Based Platforms:Remote data interpretation and report generation concentrate processing away from bedside hardware.
Wire-free devices command premium positioning in clinical procurement; cloud-based platforms are gaining share fastest through subscription economics.
Application:
Application scope spans diagnostic confirmation, longitudinal monitoring, and therapeutic outcome validation with varying regulatory burden intensity.
- Sleep Disorders Diagnosis:Obstructive sleep apnea confirmation remains the dominant revenue driver, with narcolepsy and periodic limb movement disorder representing specialized testing protocols. FDA 510(k) pathway streamlining for portable diagnostics accelerates manufacturer time-to-market.
- Patient Monitoring:Continuous positive airway pressure adherence tracking generates recurring data interpretation revenue beyond initial device sale.
- Research Studies:Multi-center trials require ISO 14155-compliant clinical investigation protocols.
- Therapy Evaluation:Pre- and post-intervention sleep architecture comparison validates treatment efficacy.
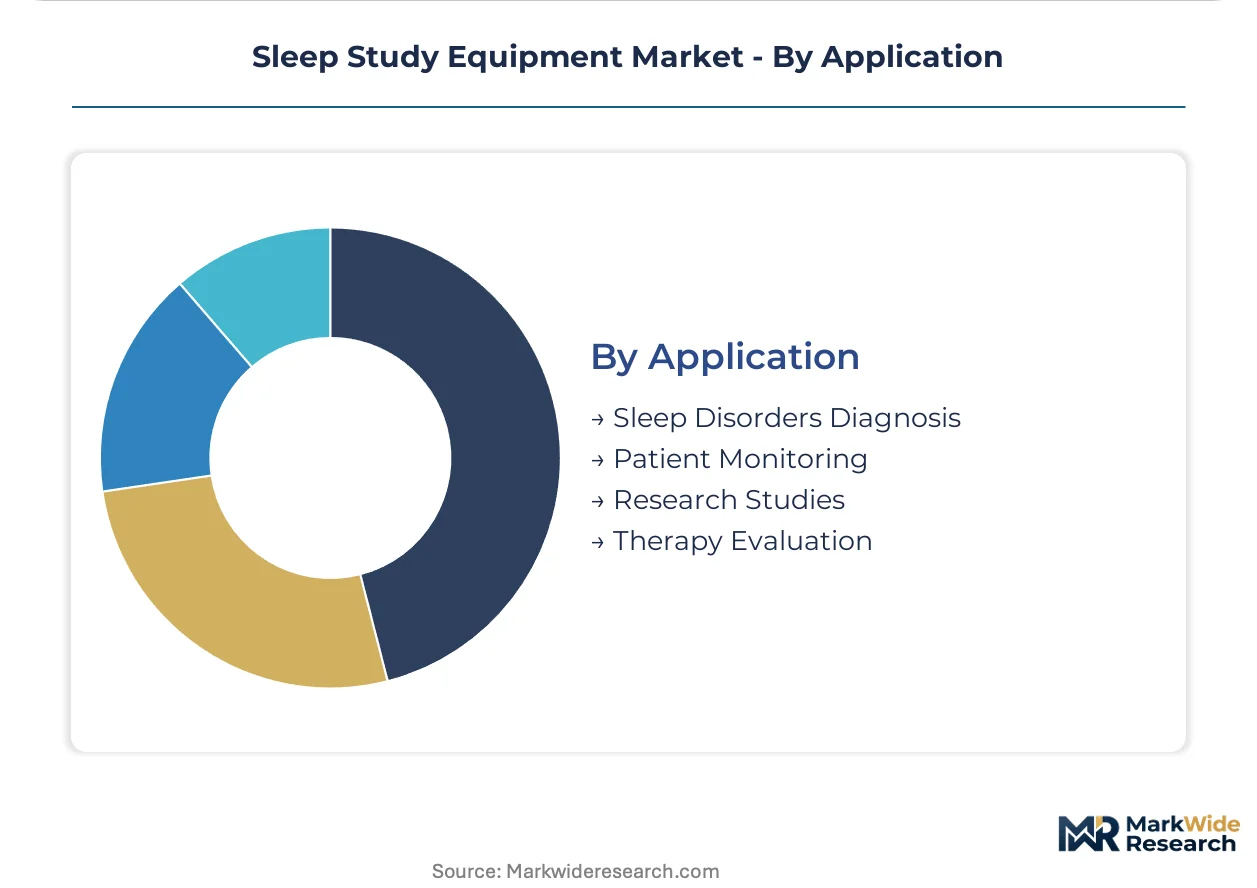
Sleep disorders diagnosis captures the majority of procedure volume; patient monitoring is expanding most quickly through remote care reimbursement evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany, Japan, and the United States, while consumption spreads across developed health systems seeking diagnostic access expansion. Supply chains route specialized analog components through East Asian foundries before final assembly at regional hubs.
United States
Home care settings drive wire-free device uptake as high-deductible health plans heighten price sensitivity for in-lab study copayments. The FDA 510(k) pathway streamlines premarket clearance for portable diagnostics targeting direct-to-patient delivery models. Sleep technologist shortages in non-metropolitan counties limit geographic expansion despite patient demand.
Germany
Sleep clinics expand polysomnography system procurement as EU Medical Device Regulation compliance deadlines tighten for existing installed bases. The MDR unique device identification mandate restructures labeling systems and quality management documentation. Munich and Berlin diagnostic equipment distributors report extended lead times during vendor reconfiguration.
Japan
Aging demographics amplify sleep disorder prevalence while PMDA regulatory pathways maintain stringent clinical evidence requirements for diagnostic devices. METI industrial standards shape procurement specifications at university hospitals. Tokyo and Osaka academic medical centers deploy high-channel acquisition systems for complex diagnostic cases.
China
Domestic manufacturers scale production of portable monitoring devices as NMPA regulatory frameworks evolve for home-use diagnostics. The country's dual carbon goals influence hospital procurement criteria for energy-efficient bedside equipment. Shanghai and Shenzhen industrial clusters concentrate final assembly capacity for regional distribution.
Australia
Rural diagnostic access gaps drive telemedicine-integrated home sleep apnea testing with mail-back devices. TGA regulatory alignment with international standards facilitates parallel market entry strategies for multinational vendors. Melbourne and Sydney sleep clinics anchor specialized diagnostic capacity for complex case referrals.
Sleep Study Equipment Market Competitive Landscape
Top-tier vendors anchor integrated diagnostic-to-therapy workflows, while mid-tier specialists concentrate on single-modality excellence. The market structures around three player tiers: diversified health technology conglomerates, dedicated sleep diagnostic manufacturers, and emerging wearable sensor entrants. Strategic archetypes include ecosystem builders pursuing platform continuity, component specialists defending high-channel accuracy, and software-first challengers capturing recurring revenue from data interpretation. Dominant competitive moves encompass cloud platform integration to lock in customer switching costs and regulatory compliance investments to capture replacement cycles.
Among diversified health technology conglomerates, ResMed and Koninklijke Philips occupy positions as ecosystem anchors through proprietary radio-frequency protocols and integrated care pathways. Nihon Kohden represents the specialized high-channel accuracy archetype, with its designation suggesting Japanese origin and corporate structure. These three exemplify contrasting strategic postures: platform continuity versus diagnostic precision versus geographic specialization.
| Leading Market Players |
|---|
| SomnoMed |
| Natus Medical |
| ResMed |
| Inspire Medical Systems |
| ZOLL Itamar |
| Koninklijke Philips |
| Nihon Kohden |
| Compumedics |
| Fisher & Paykel Healthcare |
| Others |
Value Network & Pricing Analysis
Wire-free sensor miniaturization simultaneously compresses production costs and concentrates component sourcing around specialized East Asian foundries capable of analog-to-digital converter fabrication. This dual effect reshapes margin distribution between hardware manufacturers and cloud platform operators as value migrates toward recurring software revenue.
Pricing Analysis
Margin tightening in polysomnography systems reflects EU Medical Device Regulation compliance investments that manufacturers must recover through higher capital equipment pricing. Three-tier pricing structure across premium research-grade, standard clinical, and economy portable tiers separates 32-channel acquisition systems from 16-channel hospital units from single-parameter home devices. Price differentiation rests on FDA 510(k) clearance tier and ISO 14155 clinical investigation certification. Home sleep apnea test devices face acute pricing pressure as direct-to-consumer telehealth channels bypass traditional markup structures. Sleep clinics demonstrate lowest price sensitivity due to reimbursement insulation, while uninsured patients in high-deductible plans drive aggressive cost negotiation.
Supply Chain Analysis
Dual-sourcing requirements for respiratory airflow sensors compel manufacturers to qualify both Japanese and German component suppliers alongside primary East Asian sources. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, while final assembly clusters in Germany, the United States, and China. Raw material dependencies span specialized analog-to-digital converters, medical-grade electrodes, and photoplethysmography sensor arrays. Single-source vulnerability persists for 24-bit resolution converters used in research-grade polysomnography. Distribution runs through hospital procurement networks, sleep clinic equipment distributors, and direct-to-patient telehealth fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sleep Study Equipment Market functions as a cost-of-compliance arena where EU Medical Device Regulation clinical evidence mandates and FDA 510(k) pathway requirements erect formidable barriers against undercapitalized challengers. Compliant incumbents capture replacement cycles as obsolete installed bases face forced obsolescence.
For Market Incumbents: To counter wire-free device commoditization, anchor customer retention through proprietary radio-frequency protocol ecosystems that raise switching costs for hospital networks. Deepen backward integration into cloud analytics platforms to capture recurring revenue from continuous positive airway pressure adherence monitoring. Pursue capacity addition in Germany to exploit EU Medical Device Regulation-driven replacement demand at sleep clinics. For New Entrants and Emerging Players: Enter via underpenetrated rural United States counties where telemedicine-enabled home sleep apnea testing addresses diagnostic access gaps absent board-certified sleep physicians. Target mail-back portable device segments where reimbursement evolution favors lower patient acquisition costs. Deploy direct-to-consumer go-to-market angles through telehealth platform partnerships that bypass traditional physician referral gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with software-first challengers given artificial intelligence-assisted sleep staging adoption that automates electroencephalography interpretation and expands diagnostic throughput. Long-term viability favors platforms with demonstrated FDA 510(k) clearance velocity and cloud-connected analytics infrastructure. Watch reimbursement policy evolution for home-based testing against in-lab study coverage as the decisive inflection signal determining capital allocation between portable and fixed diagnostic platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket clearance velocity determines competitive positioning in United States home care settings. |
| CE Marking Pathway Investment | EU Medical Device Regulation compliance captures replacement cycles at German sleep clinics. |
| Hospital System Partnership | Integrated diagnostic-to-therapy workflows lock in proprietary data formats and switching costs. |
| Software Companion Development | Cloud-connected analytics platforms generate recurring revenue beyond initial device sale. |
| Reimbursement Strategy | Medicare physician fee schedule alignment shapes return-on-investment for sleep center expansions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with sleep clinic medical directors, biomedical equipment procurement managers, polysomnographic technologists, and GPO contracts specialists combined with FDA 510(k) database extractions, EU Medical Device Regulation notified body documentation, and hospital procurement records. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and application segmentation dimensions.
Reconciliation of shipment data, installed base estimates, and replacement cycle assumptions anchored the analytical framework across the projection horizon. Modeled dimensions spanned product type intensity, end user reimbursement pathway, technology architecture, and regional regulatory cluster. CAGRs derived from trend extrapolation of historical penetration rates adjusted for policy inflection points. Forecast inputs incorporated sleep technologist graduation rates and Medicare physician fee schedule evolution.
Revisions become necessary when semiconductor supply bottlenecks intensify, FDA 510(k) pathway timelines extend materially, or reimbursement compression for in-lab studies accelerates beyond modeled assumptions. Deviation in EU Medical Device Regulation enforcement rigor would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Americas Insomnia Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Excessive Daytime Sleepiness Market