
 Mycoprotein Products Market | 2026-2036
Mycoprotein Products Market Size, Share, and Industry Trends Forecast 2026-2036
Mycoprotein Products Market Foresight
The Netherlands is tilting toward commercial-scale mycoprotein fermentation capacity with new bioreactor installations near Rotterdam. Marlow Foods Ltd. leverages its heritage Quorn brand to anchor shelf presence across British retail channels. Nature's Fynd sustains distinct positioning through extremophile fungal strains derived from Yellowstone geothermal environments. ENOUGH extends its platform into B2B ingredient supply, competing for food manufacturer contracts rather than direct consumer loyalty.
Mycoprotein denotes filamentous fungal biomass cultivated via submerged fermentation, typically achieving protein contents of 45-55 percent dry weight with fiber-rich cell wall structures that confer meat-like texture. Industrial bioreactors maintain sterile aerobic conditions for Fusarium venenatum or comparable fungal strains, yielding harvest cycles measured in days rather than months required for conventional livestock. Frozen products dominate retail velocity due to established cold-chain infrastructure and consumer preparation habits, while meat alternatives capture the deepest margin pools as branded finished goods command premium positioning over commodity protein isolates. Ready-to-eat formats represent the fastest-growing product type as convenience-oriented shoppers seek minimal-preparation options.
EFSA novel food authorization requirements govern mycoprotein entry into European markets, mandating comprehensive toxicological and nutritional dossiers that extend development timelines for new fungal strains. The FDA GRAS self-affirmation pathway shapes U.S. market access dynamics, permitting faster commercialization but introducing liability exposure absent formal pre-market approval. BIS food safety standards in India create additional compliance layers for imported mycoprotein formulations. Stakeholders must monitor evolving precision fermentation regulations and carbon accounting methodologies that will determine which production platforms qualify for sustainability-linked procurement mandates.
Market Dynamics
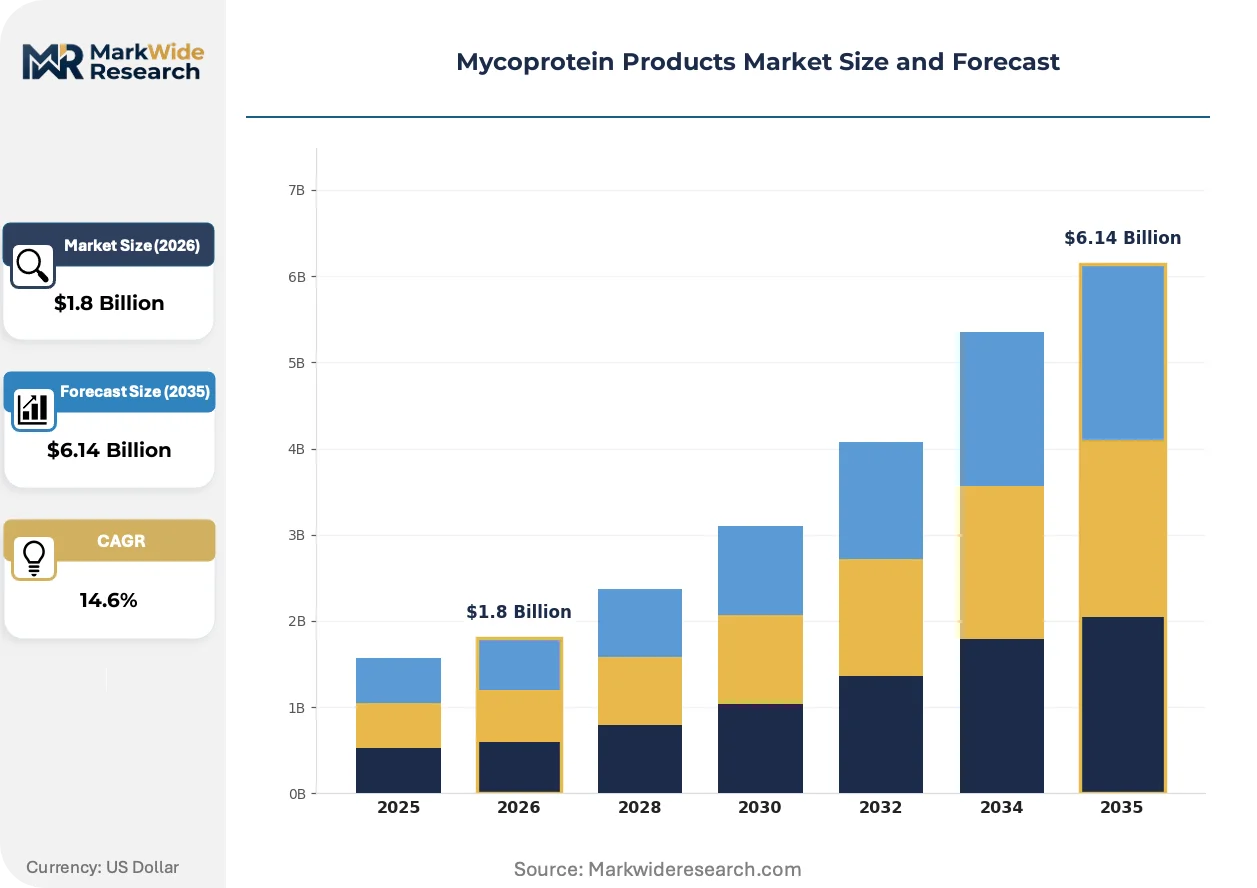
Fermentation technology maturation is compressing unit economics for mycoprotein production, enabling price parity with conventional animal proteins in select European retail channels and forcing incumbent suppliers to accelerate capacity expansion or cede shelf space.
Growth Catalysts
- EFSA Novel Food Framework:Streamlined safety dossier pathways for Fusarium-derived ingredients accelerate European market entry timelines for new fermentation entrants.
- Food Service Procurement:Contract catering operators across the United Kingdom and Netherlands are embedding mycoprotein into institutional meal programs under carbon-reduction procurement mandates.
- Precision Fermentation:Continuous bioreactor designs with automated biomass harvesting are reducing contamination risk and extending production run lengths.
Market Restraints
- Input Cost Volatility:Glucose feedstock prices fluctuate with corn and wheat commodity markets, squeezing margins for continuous fermentation operators without long-term supply contracts.
- Supply Concentration Risk:Single-site production facilities in the United Kingdom dominate retail-ready mycoprotein supply, creating geographic vulnerability to cold-chain disruptions.
- Technical Limitation:Filamentous fungal biomass requires mechanical shear processing to achieve fibrous meat-like textures, adding capital intensity versus extruded plant proteins.
Strategic Opportunities
- Underpenetrated Geography:German retail channels show minimal mycoprotein SKU density despite high plant-based meat consumption rates, presenting first-mover shelf allocation potential.
- Regulatory Tailwind:EU Green Deal carbon accounting methodologies for food products may classify fermentation-derived proteins as net-negative emissions, unlocking public procurement preferences.
- Distribution Innovation:Direct-to-foodservice ingredient supply bypasses retail margin stacking, allowing B2B platforms to capture value through formulation partnerships with meat alternative manufacturers.
Industry Challenges
- Specialized Talent Scarcity:Industrial mycologists and sterile fermentation engineers command premium compensation, constraining scale-up timelines for new production facilities.
- Certification Timeline Compression:Novel food safety dossiers for non-Fusarium strains face extended toxicological review periods, delaying product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycoprotein Products Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Products, Dried Products, Ready-to-Eat, Snacks Application: Meat Alternatives, Protein Supplements, Dairy Alternatives, Culinary Products Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Food Service End User: Vegetarians, Vegans, Health-Conscious Consumers, Athletes |
| Companies Covered | The Better Meat Co., Nature's Fynd, Marlow Foods Ltd. (Quorn Foods), Mycorena AB, Cargill, Inc., ENOUGH (3F Bio Ltd.), Meati Foods, Bright Green Partners B.V., MycoTechnology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycoprotein Products Market Shifts & Advancements
Digital twin modeling of bioreactor performance is shortening strain optimization cycles and enabling predictive maintenance that prevents batch contamination losses.
Continuous fermentation monitoring with machine-learning feedback loops is virtualizing quality control, allowing Marlow Foods and comparable operators to reduce offline laboratory testing frequency by half. Mid-cap producers are adopting these platforms rapidly, compressing the technology diffusion cycle from five years to eighteen months. This virtualization is enabling real-time biomass density adjustments that maximize protein yield per glucose input.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are forcing cold-chain operators to retrofit freezing tunnels with ammonia or CO2 systems. Industrial freezing equipment suppliers report order backlogs extending twelve months for mycoprotein-compatible blast freezers. European frozen mycoprotein product lines face the most acute retrofit pressure, with some operators delaying new SKU introductions until infrastructure upgrades complete.
Retail buyer consolidation across British supermarket chains is consolidating mycoprotein supplier rosters from six to three preferred partners per category. Discounters Aldi and Lidl are expanding private-label mycoprotein placement, displacing branded premium positioning with economy-tier alternatives. This concentration is most visible in the United Kingdom, where Tesco and Sainsbury's combined account for over half of frozen meat alternative volume.
Mycoprotein Products Market Segmentation
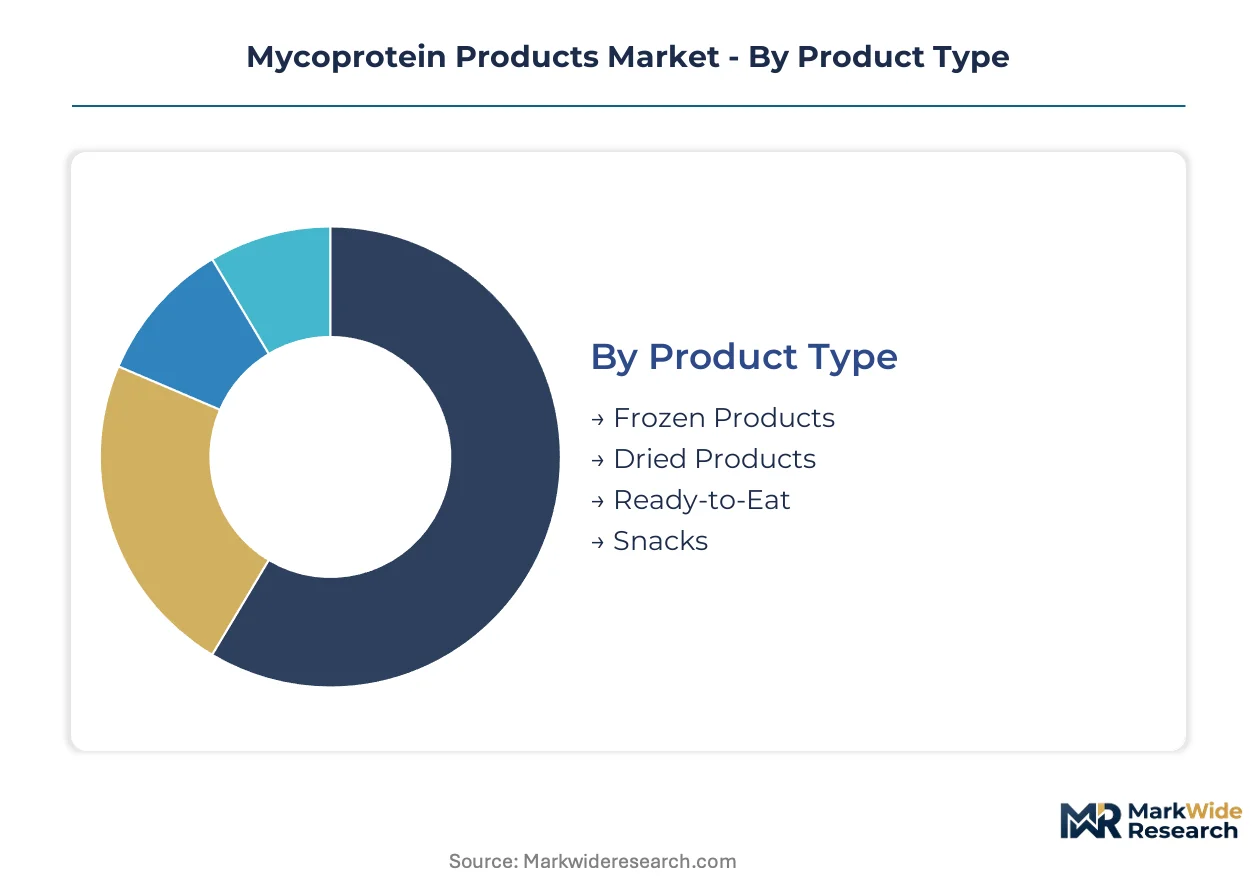
Mycoprotein manufacturers configure production lines around format-specific processing requirements. Frozen and ready-to-eat variants demand distinct cold-chain investments and shelf-life management protocols that reshape margin structures across the value chain.
Product Type:
After-sales service intensity varies sharply by format, with frozen products requiring retailer training on temperature compliance and ready-to-eat formats demanding consumer education on storage protocols.
- Frozen Products:Blast-frozen biomass blocks and formed pieces retain optimal texture through industrial freezing tunnels. British supermarkets and Netherlands food service operators anchor procurement volumes due to established cold-chain infrastructure and consumer preparation habits.
- Ready-to-Eat:Pre-cooked mycoprotein meals and shelf-stable formats minimize home preparation steps. Convenience-oriented shoppers in United Kingdom urban centers drive adoption as meal-kit platforms expand mycoprotein-centric offerings.
- Dried Products:Dehydrated mycoprotein flour and protein isolates serve ingredient manufacturers seeking extended ambient storage.
- Snacks:Extruded mycoprotein crisps and jerky-style strips target on-the-go consumption occasions with portable packaging formats.
Frozen products hold the largest share; momentum sits with ready-to-eat formats.
Application:
Cost tier stratification separates premium branded meat alternatives from commodity protein supplement inputs, with formulation complexity determining pricing power.
- Meat Alternatives:Formed mycoprotein burgers, sausages, and nuggets replicate fibrous animal muscle structures through mechanical shear processing. Marlow Foods and comparable branded suppliers command premium positioning in British retail channels where Quorn heritage anchors consumer recognition.
- Protein Supplements:Isolated mycoprotein concentrates and blended powders target sports nutrition formulations. Athletes and fitness enthusiasts in Netherlands drive demand as gym-channel distribution expands beyond traditional retail.
- Dairy Alternatives:Fermented mycoprotein bases for yogurt-style and cheese-analog applications leverage fungal biomass texture.
- Culinary Products:Unformed mycoprotein chunks and minces supply restaurant kitchens for scratch-cooking applications.
Meat alternatives dominate value capture; protein supplements are climbing the fastest.
Distribution Channel:
Volume concentration tilts toward supermarket chains with dedicated frozen food aisles, while margin expansion concentrates in direct-to-foodservice supply bypassing retail markups.
- Supermarkets:Frozen mycoprotein SKUs occupy dedicated plant-based meat sections in British and German retail chains. Tesco and Sainsbury's consolidated buyer power has reduced supplier rosters from six to three preferred partners per category.
- Food Service:B2B ingredient supply to contract caterers and restaurant chains avoids retail margin stacking. United Kingdom institutional meal programs under carbon-reduction procurement mandates embed mycoprotein into school and hospital feeding operations.
- Online Retail:Direct-to-consumer frozen delivery requires specialized insulated packaging and same-day logistics.
- Health Food Stores:Specialist retailers curate premium mycoprotein supplements for dedicated vegetarian and vegan shoppers.
Supermarkets hold the largest share; food service shows the steepest expansion trajectory.
End User:
Customer type segmentation reveals divergent purchasing triggers, from ethical abstention to performance optimization, reshaping marketing investment allocation.
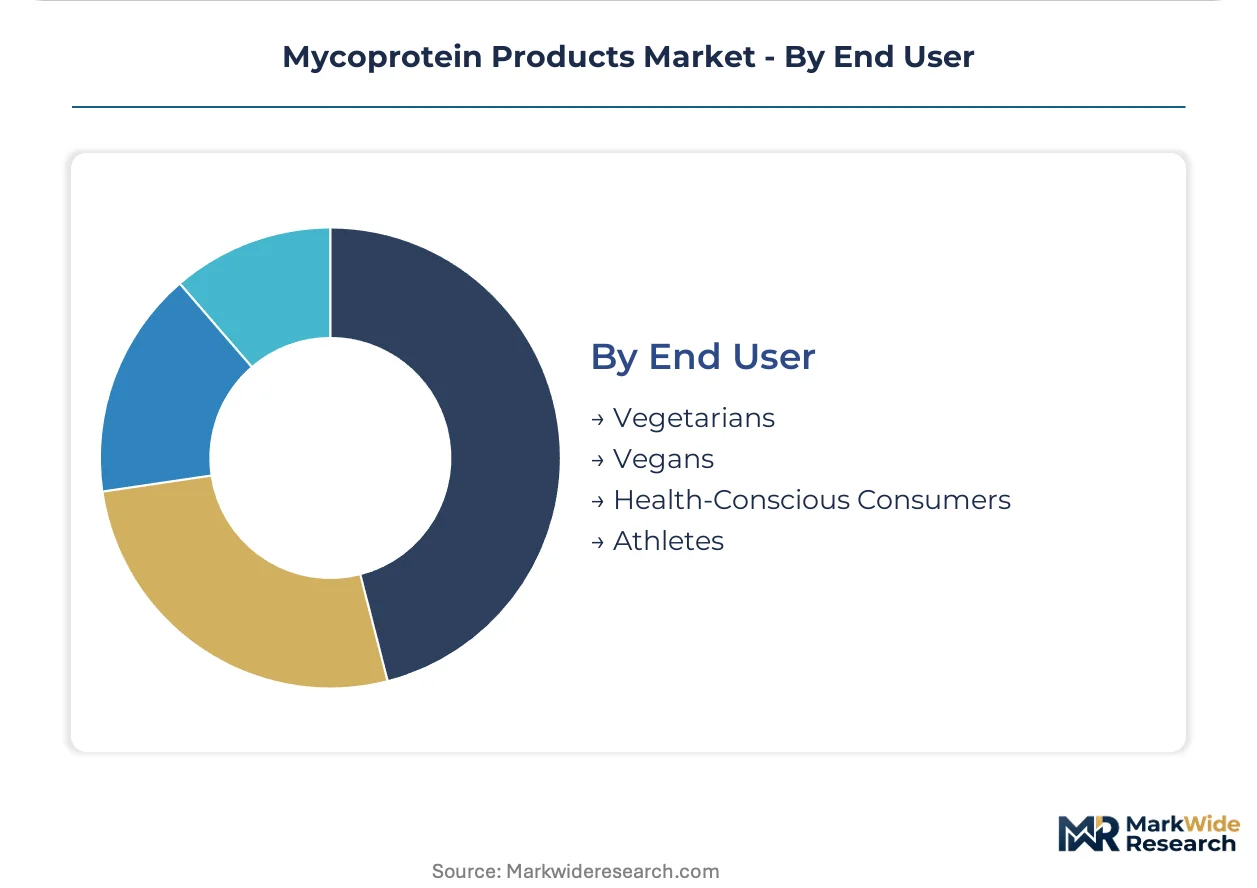
- Health-Conscious Consumers:Flexitarians seeking protein diversification without full meat elimination drive mainstream adoption. British households with children show particular responsiveness to mycoprotein's fiber content and low saturated fat profile.
- Vegans:Strict plant-based diet adherents require certified animal-free production environments. Netherlands retail channels report vegan-certified mycoprotein SKUs outperforming uncertified alternatives by significant margins.
- Vegetarians:Longstanding meat-avoiders provide established demand base with high brand loyalty and repeat purchase rates.
- Athletes:Protein-focused consumers prioritize amino acid completeness and leucine content in post-workout recovery formulations.
Health-conscious consumers hold the largest share; vegans are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-site fermentation facilities in the United Kingdom concentrate retail-ready supply chains. Cold-chain infrastructure investments in the Netherlands and Germany are redrawing procurement maps. Regulatory divergence between EFSA novel food pathways and FDA GRAS self-affirmation creates distinct market access timelines across jurisdictions.
United Kingdom
Decades of Quorn brand familiarity anchor consumer demand in British retail channels. EFSA novel food authorization requirements govern new strain introductions, extending development timelines for non-Fusarium entrants. The Midlands region hosts concentrated bioreactor capacity serving Tesco and Sainsbury's consolidated buyer networks.
Netherlands
Rotterdam-area bioreactor installations are scaling commercial fermentation output for European food service procurement. EU Green Deal carbon accounting methodologies may classify fermentation-derived proteins as net-negative emissions, unlocking institutional procurement preferences. Randstad logistics clusters enable rapid cold-chain distribution into German and Belgian retail channels.
Germany
Minimal mycoprotein SKU density in German supermarkets contrasts with high plant-based meat consumption rates, presenting first-mover shelf allocation potential. BfR (Federal Institute for Risk Assessment) coordinates with EFSA on novel food safety assessments. Bavaria and North Rhine-Westphalia retail chains are piloting dedicated fermentation-protein sections in response to Aldi and Lidl private-label expansion.
United States
FDA GRAS self-affirmation permits faster commercialization than European pre-market approval pathways, though liability exposure accompanies the streamlined route. Precision fermentation startups cluster in California and the Pacific Northwest near venture capital and talent pools. Yellowstone-derived extremophile strains represent distinct positioning for nature-origin marketing claims.
India
BIS food safety standards create compliance layers for imported mycoprotein formulations, favoring domestic fermentation partnerships. FSSAI novel food guidelines are evolving for fungal biomass categories. Maharashtra and Gujarat pharmaceutical fermentation infrastructure is repurposing toward food-grade mycoprotein capacity under PLI scheme incentives.
Mycoprotein Products Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in strain development and ingredient supply. The vendor base stratifies between heritage brand owners with decades of retail presence and venture-backed fermentation startups with novel strain libraries. Two archetypes dominate: vertically integrated finished goods manufacturers and B2B ingredient platforms competing for food manufacturer contracts. Capacity expansion and strategic partnerships constitute the primary competitive vectors as price parity with conventional proteins compresses margin timelines.
Among heritage-anchored operators, Marlow Foods Ltd. occupies a position exemplifying brand-familiarity defense in British retail channels. Nature's Fynd represents the extremophile-origin archetype with distinct geothermal strain positioning. ENOUGH sits within the B2B ingredient supply tier, competing for formulation partnerships rather than direct consumer loyalty. These three anchors illustrate the strategic divergence between finished goods premium capture and upstream commodity supply.
| Leading Market Players |
|---|
| The Better Meat Co. |
| Nature's Fynd |
| Marlow Foods Ltd. (Quorn Foods) |
| Mycorena AB |
| Cargill, Inc. |
| ENOUGH (3F Bio Ltd.) |
| Meati Foods |
| Bright Green Partners B.V. |
| MycoTechnology, Inc. |
| Others |
Supply & Pricing Matrix
Single-site fermentation capacity in the United Kingdom anchors retail-ready mycoprotein supply, concentrating margin capture with heritage brand owners while forcing new entrants to compete on input cost efficiency or cede shelf space to established cold-chain operators.
Pricing Analysis
EFSA novel food authorization requirements dictate the pricing tier structure across European markets, with certified Fusarium-derived products commanding premium positioning over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels separates branded finished goods from private-label alternatives and commodity protein isolates. Cost compression in the economy tier is intensifying because Aldi and Lidl private-label expansion displaces premium positioning. Food service procurement teams show least price sensitivity due to carbon-reduction mandate compliance value, while retail discounters drive hardest bargain negotiations.
Supply Chain Analysis
EU F-Gas Regulation phase-down schedules restrict hydrofluorocarbon refrigerant flows, forcing cold-chain infrastructure retrofits that extend equipment order backlogs. Manufacturing concentrates in the United Kingdom, the Netherlands, and Germany, with Rotterdam-area bioreactor installations scaling for continental distribution. Glucose feedstock draws from corn and wheat commodity markets, while mechanical shear processing equipment and sterile fermentation engineering talent constrain expansion timelines. Single-site production vulnerability creates geographic exposure to cold-chain disruptions. Distribution runs through consolidated supermarket buyer networks and direct-to-foodservice ingredient supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are crossing into interoperability with conventional food manufacturing infrastructure, enabling B2B ingredient suppliers to embed within existing formulation workflows rather than building parallel consumer brands.
For Market Incumbents: Entrench shelf presence through exclusive supply agreements with Tesco and Sainsbury's consolidated buyer networks before discounter private-label displacement accelerates. Expand Midlands bioreactor capacity to preempt supply shortages during EU Green Deal procurement mandate rollouts. Backward integration into glucose feedstock sourcing mitigates commodity price volatility squeezing continuous fermentation margins.
For New Entrants and Emerging Players: German retail channels with minimal mycoprotein SKU density despite high plant-based meat consumption rates represent the most penetrable entry point for first-mover shelf allocation. Direct-to-foodservice ingredient supply bypassing retail margin stacking offers faster revenue traction than consumer brand building. Partner with established meat alternative manufacturers for formulation integration rather than competing for brand recognition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous bioreactor platforms as automated biomass harvesting reduces contamination losses and extends production run lengths. Target B2B ingredient platforms with novel strain libraries and food manufacturer formulation partnerships rather than finished goods brands facing retail consolidation pressure. Watch EU carbon accounting methodology finalization as signal for institutional procurement mandate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioreactor Scale-Up | Automated harvesting reduces contamination risk and extends production runs for Marlow Foods and comparable operators. |
| Novel Strain Regulatory Dossier | EFSA authorization timelines determine competitive entry windows for non-Fusarium fermentation platforms. |
| Food Service Direct Supply | B2B ingredient partnerships bypass retail margin stacking and capture value through formulation integration. |
| Cold-Chain Infrastructure Retrofit | Ammonia and CO2 freezing system adoption responds to EU F-Gas Regulation phase-down requirements. |
| Private-Label Capacity Allocation | Aldi and Lidl expansion displaces branded premium positioning with economy-tier alternatives in British retail. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA novel food authorization databases, FAO fermentation statistics, and trade customs records covering glucose feedstock and bioreactor equipment flows. Industrial mycologists, sterile fermentation engineers, contract catering procurement directors, and supermarket category buyers provided operational perspective. Bottom-up capacity modeling triangulates against top-down protein demand projections across meat alternative and supplement applications.
Forecast inputs span product type, application, distribution channel, and end user segmentation dimensions across the projection horizon. CAGRs derive from production capacity expansion schedules, regulatory authorization timelines, and carbon accounting methodology adoption curves. Strain optimization cycles, bioreactor utilization rates, and cold-chain infrastructure investment backlogs inform volume trajectory assumptions.
Macroeconomic conditions sit as an overlay; deviation in glucose commodity prices, EU Green Deal implementation pace, or precision fermentation talent availability would shift the trajectory. Forecasts reflect documented assumptions about sterile fermentation engineering supply and EFSA dossier review efficiency. Material shifts in novel food regulatory pathways or carbon accounting classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Bioengineered Food Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Seaweed Protein Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Meat Alternative Market