
 Africa Protein Market | 2026-2036
Africa Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Protein Market Outlook
Aftermarket nutrition consulting and technical formulation support is fragmenting across competing service models as protein suppliers seek stickier customer relationships. Cargill Incorporated leverages its pan-African grain and oilseed infrastructure to secure preferred access to soy crushing capacity. Fonterra Co-operative Group Limited anchors its position through dairy protein specialization, while Kerry Group plc differentiates via integrated taste and nutrition systems that reduce formulation complexity for African food manufacturers.
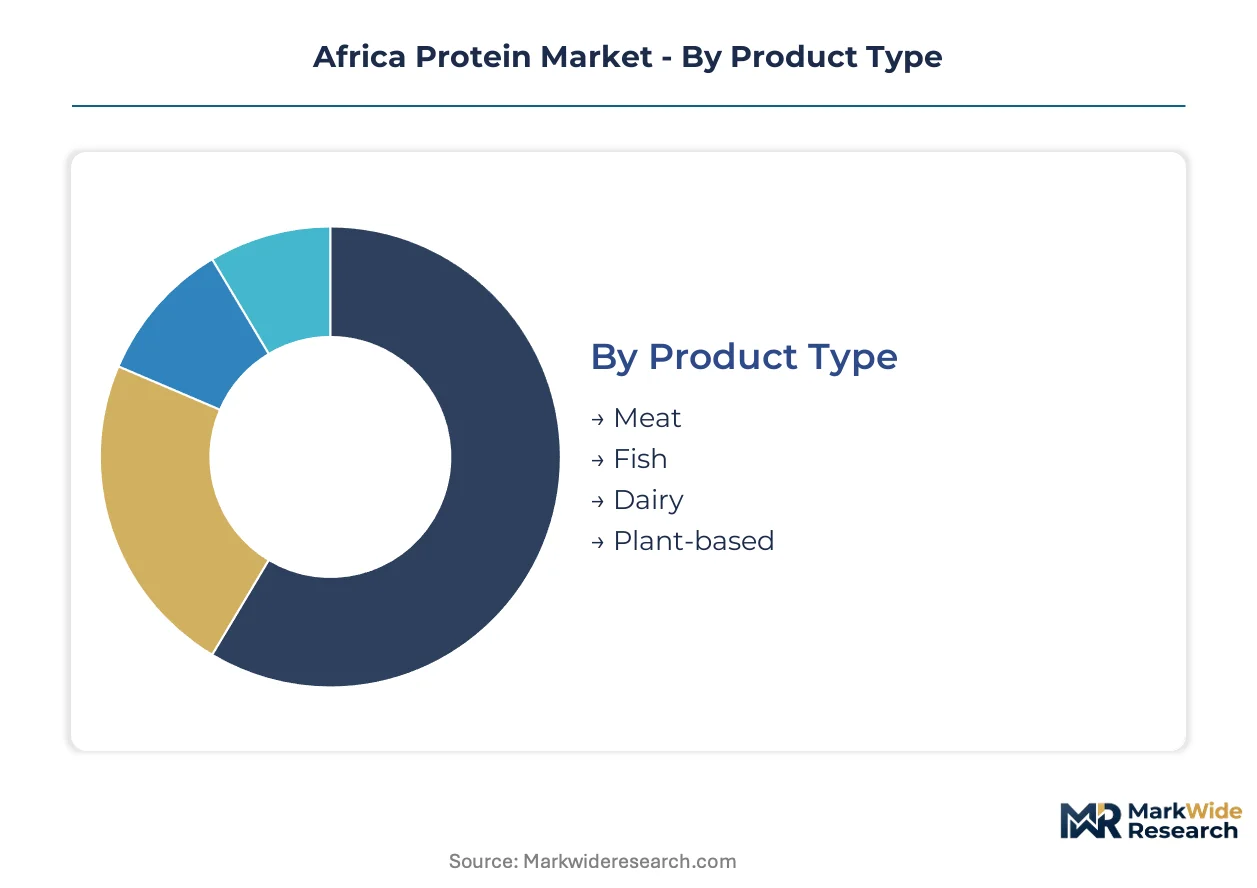
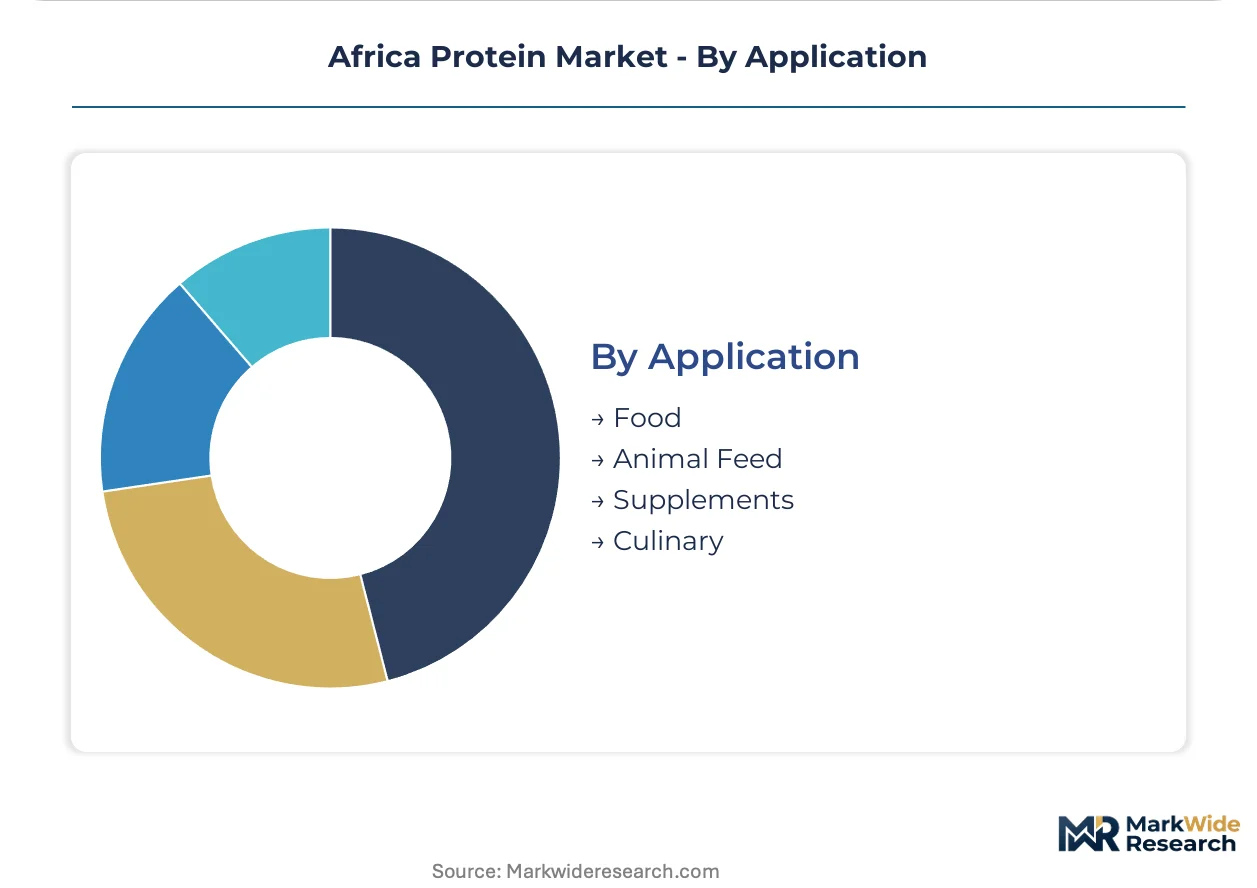
Protein encompasses nitrogenous macromolecules composed of amino acid chains that provide essential structural, enzymatic, and metabolic functions in biological systems, with industrial grades specified by digestibility-corrected amino acid scores and protein digestibility values. The Africa Protein Market spans meat, fish, dairy, and plant-based categories, with dairy and meat commanding established margin pools due to entrenched cold-chain infrastructure and consumer familiarity. Plant-based protein exhibits the fastest trajectory as sunflower, cowpea, and fava bean processing investments multiply across East and Southern Africa. Application splits reveal food and animal feed as volume leaders, though supplements capture premium pricing through pharmacy and clinic channels in urban centers.
South Africa's Department of Agriculture enforces feed safety and labeling standards that elevate compliance costs for imported protein isolates. The country's national standards body, together with Kenya's Bureau of Standards and Nigeria's national food and drug regulator, shapes market access through microbiological and contaminant thresholds that favor locally processed over imported finished goods. Stakeholders must monitor evolving mycotoxin regulations and cold-chain certification requirements as protein sourcing regionalizes and informal traditional market channels face gradual formalization pressure.
Market Dynamics
South Africa's tightened feed safety protocols are forcing protein processors to redirect capital toward certified cold-chain infrastructure, while Nigeria's quick-service restaurant chains accelerate reformulation with locally sourced soy and black soldier fly protein concentrates.
Growth Catalysts
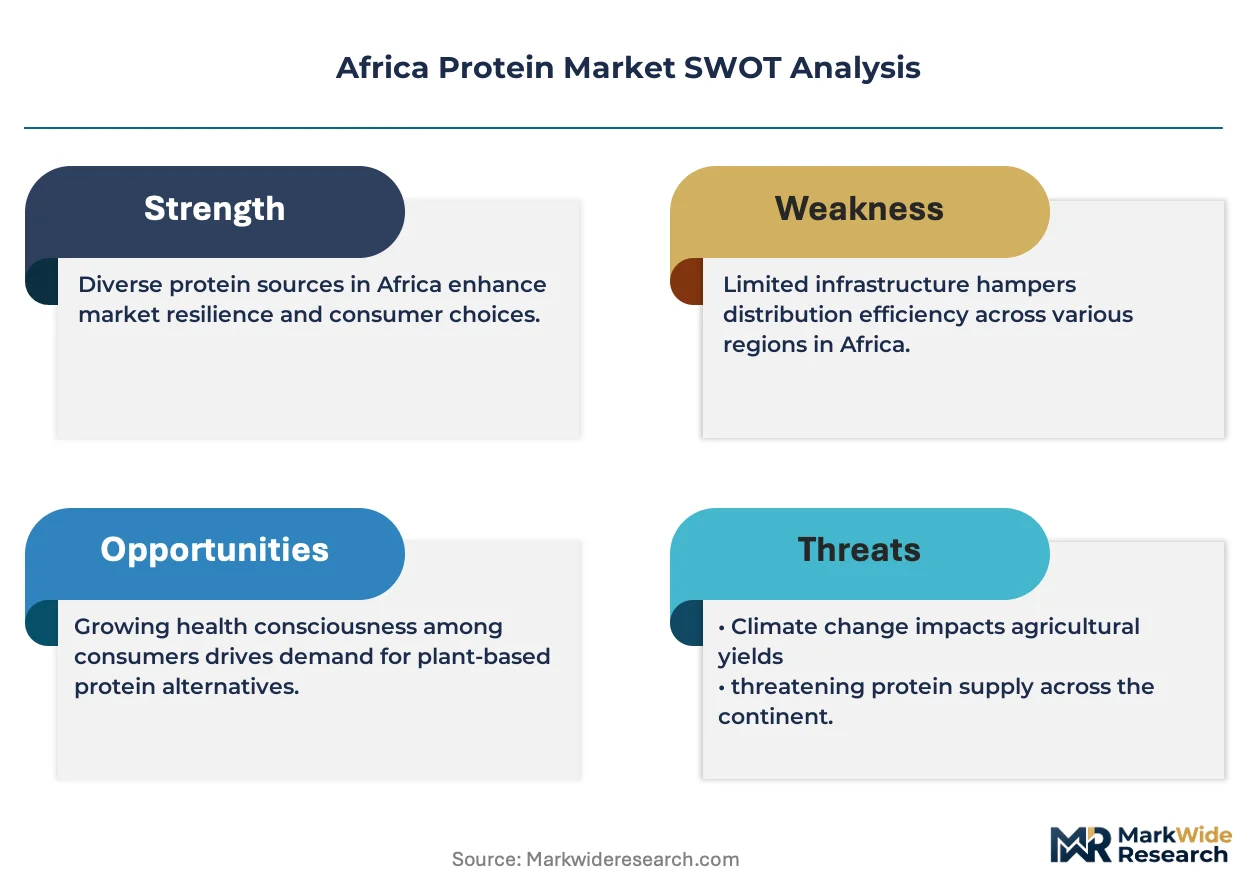
- Regulatory Formalization:South Africa's Department of Agriculture, Land Reform and Rural Development enforces feed safety standards that favor certified local processing facilities over informal imports.
- Urban Corridor Demand:Nigeria's Lagos-Abuja corridor concentrates procurement from quick-service restaurant chains and packaged food manufacturers seeking protein supply security.
- Insect Protein Technology:Black soldier fly larvae processing delivers amino acid profiles competitive with fishmeal while utilizing organic waste streams abundant across East and West Africa.
Market Restraints
- Cold-Chain Infrastructure Gap:Temperature-controlled logistics capacity remains concentrated in South Africa and Kenya, elevating spoilage risk for dairy and meat protein shipments to inland markets.
- Mycotoxin Contamination Risk:Aflatoxin prevalence in Nigerian and Kenyan grain supplies elevates testing costs and rejection rates for plant protein concentrates.
- Import Dependency for Isolates:High-purity soy and pea protein isolates rely on processing capacity concentrated outside the continent, exposing buyers to currency volatility and shipping delays.
Strategic Opportunities
- East African Processing Hubs:Tanzania and Uganda offer underexploited sunflower and cowpea processing potential with access to regional trade corridors and expanding feed mill capacity.
- Pharmacy Channel Expansion:Urban centers in Nigeria and South Africa present white space for protein supplement distribution through clinic and pharmacy networks serving diabetic and renal patient populations.
- Carbon Credit Monetization:Insect protein production facilities qualify for voluntary carbon market credits by diverting organic waste from methane-emitting landfill decomposition.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Protein fortification expertise in digestibility-corrected amino acid scoring and sensory masking remains concentrated among multinational technical service teams.
- Multi-Jurisdiction Certification Burden:Exporters must satisfy Kenya Bureau of Standards, South African national standards body, and Nigeria's food and drug regulator requirements simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Protein Market |
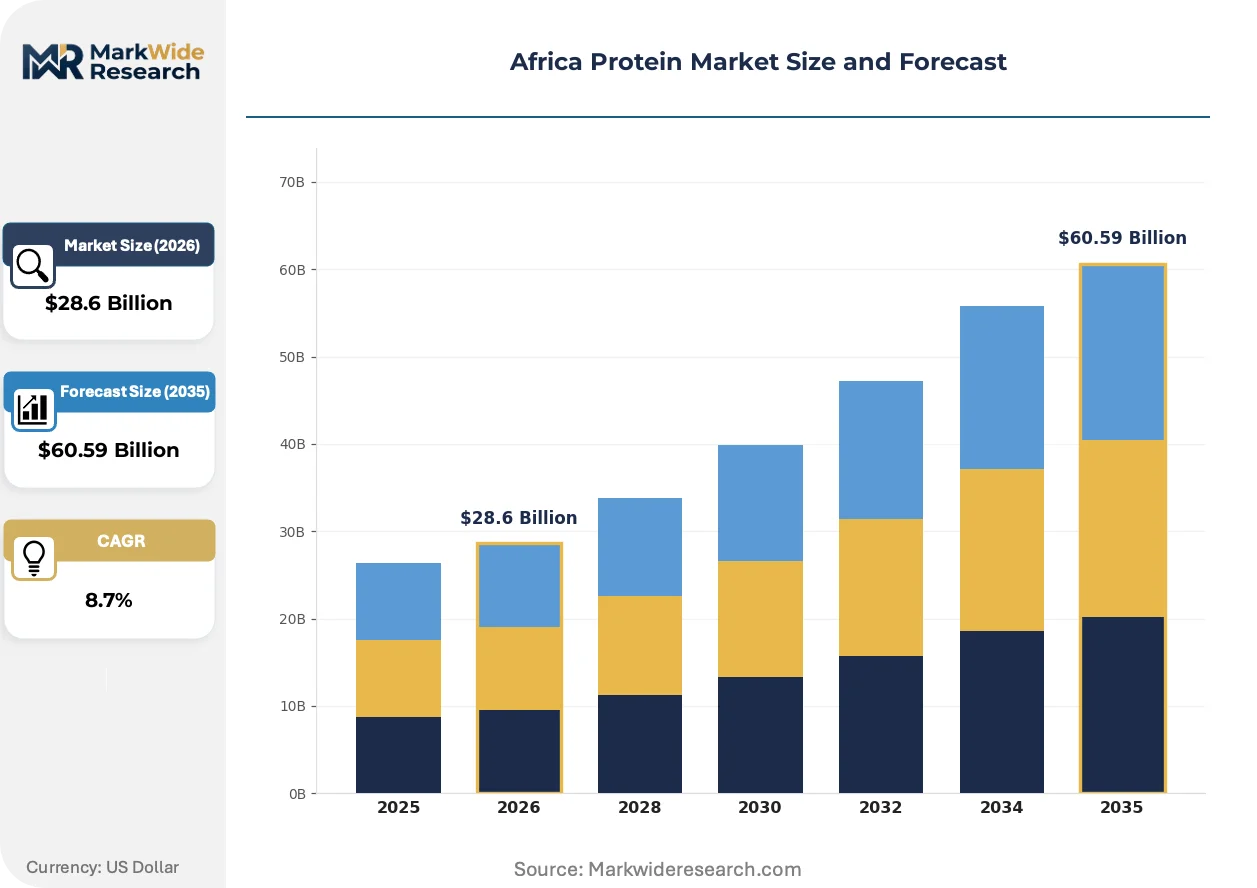
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Fish, Dairy, Plant-based End User: Households, Food Service, Retail, Food Processing Distribution Channel: Online, Supermarkets, Traditional Markets, Wholesalers Application: Food, Animal Feed, Supplements, Culinary |
| Companies Covered | Cargill Incorporated, Fonterra Co-operative Group Limited, Hilmar Cheese Company Inc., International Flavors & Fragrances, Inc., Kerry Group plc, Arla Foods amba, Glanbia PLC, Royal FrieslandCampina, AgriProtein, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Protein Market Strategic Shifts
Protein sourcing across Africa is regionalizing as cold-chain investments and regulatory harmonization reduce reliance on imported finished goods, while processing technology and distribution models undergo parallel transformation.
Extrusion-based texturization of sunflower and fava bean proteins is migrating from pilot-scale demonstration facilities to commercial production lines serving East African meat analog manufacturers. Kenyan and Ethiopian food processors deploy twin-screw extruders to achieve fibrous structures previously requiring imported soy or wheat gluten. This equipment transition compresses formulation costs for plant-based burger and sausage applications while creating captive demand for regional oilseed crushing capacity.
Kenya's Bureau of Standards and South Africa's national standards body coordinate mycotoxin maximum residue limits that exceed legacy Codex thresholds, forcing grain handlers to invest in optical sorting and rapid testing infrastructure. Nigerian regulators observe these developments while drafting national food and drug administration guidelines that will likely adopt similar stringency. Plant protein concentrate producers in Lagos and Abuja industrial zones face the steepest compliance timeline compression as they simultaneously satisfy export and domestic market requirements.
Quick-service restaurant chains in Nigeria's Lagos-Abuja corridor now specify protein origin and processing method in procurement tenders, displacing commodity purchasing based solely on price and minimum protein content. Procurement teams audit crushing facility locations, cold-chain documentation, and amino acid digestibility scores before contract award. This behavior shift concentrates supplier relationships among processors with integrated laboratory and logistics capabilities, marginalizing traders lacking technical service depth.
Africa Protein Market Segmentation
Protein suppliers across Africa differentiate offerings through formulation support intensity rather than commodity pricing alone. Technical service depth determines contract stickiness as Nigerian and South African buyers demand digestibility scoring and sensory masking assistance.
Product Type:
After-sales formulation consulting varies sharply across protein categories, with plant-based and insect-derived proteins requiring the most intensive technical hand-holding.
- Meat:Beef, poultry, and goat protein concentrates maintain established margin pools through entrenched cold-chain infrastructure in South Africa and Kenya. Demand concentrates in Lagos-Abuja corridor quick-service restaurants seeking supply security through backward integration into domestic slaughterhouse networks.
- Dairy:Whey and casein isolates specified by protein digestibility-corrected amino acid scores serve diabetic and renal patient populations through South African pharmacy channels. Fonterra anchors this segment through specialized dairy protein infrastructure.
- Fish:Marine protein meals from Moroccan and Mauritanian fisheries supply West African feed mills.
- Plant-based:Sunflower, cowpea, and fava bean concentrates from East African crushing facilities displace imported soy isolates.
Dairy holds the largest share; momentum sits with plant-based proteins climbing the fastest as extrusion texturization technology commercializes.
End User:
Customer procurement sophistication stratifies across cost tiers, with food processing manufacturers paying premiums for integrated laboratory capabilities while traditional markets prioritize volume flexibility.
- Food Processing:Packaged food manufacturers in Nigeria's Lagos-Abuja industrial zones specify protein origin, crushing facility location, and cold-chain documentation in tenders. Reformulation with black soldier fly and locally sourced soy concentrates accelerates as procurement teams audit amino acid digestibility scores.
- Food Service:Quick-service restaurant chains across South Africa and Kenya consolidate supplier relationships around processors with captive laboratory and logistics capabilities. Technical service depth including sensory masking and texture optimization commands contract preference.
- Retail:Supermarket chains in Nairobi and Johannesburg source branded protein supplements through pharmacy-network distributors.
- Households:Traditional market channels in Nigerian urban centers face gradual formalization pressure from mycotoxin regulations.
Food processing captures premium pricing; food service gains share fastest through procurement centralization.
Distribution Channel:
Channel selection reflects margin requirements and cold-chain certification burdens, with certified infrastructure commanding price premiums over informal alternatives.
- Supermarkets:Temperature-controlled retail formats in South Africa and Kenya concentrate dairy and meat protein sales through formal cold-chain documentation. Shoprite and Pick n Pay procurement teams reject shipments lacking continuous temperature logging.
- Traditional Markets:Open-air trading dominates Nigerian and Kenyan volume but faces tightening mycotoxin and labeling standards from national regulators. Optical sorting investment requirements squeeze informal traders lacking capital for compliance infrastructure.
- Online:Pharmacy-channel protein supplements reach diabetic and renal patients through clinic-affiliated e-commerce platforms in Lagos and Johannesburg.
- Wholesalers:Regional distributors aggregate sunflower and cowpea concentrates from Tanzanian and Ugandan processing hubs for East African feed mill supply.
Traditional markets hold the largest share; supermarkets expand most quickly through regulatory formalization.
Application:
Application mix determines specification stringency, with pharmaceutical and feed safety protocols imposing tighter microbiological thresholds than culinary uses.
- Food:Human-grade protein fortification in packaged goods and quick-service applications demands digestibility-corrected amino acid scoring. Nigerian manufacturers reformulate with black soldier fly concentrates to meet procurement tender requirements for local sourcing.
- Animal Feed:Poultry and aquaculture feed mills across Kenya and Nigeria drive volume demand for insect protein meals. South Africa's Department of Agriculture enforces feed safety protocols that favor certified local processing over informal imports.
- Supplements:Pharmacy and clinic channels in urban South Africa and Nigeria serve medical nutrition needs with premium-priced isolates.
- Culinary:Traditional preparation methods in household and informal food service segments tolerate lower purity grades.
Animal feed holds the largest share; supplements command the steepest price premiums through medical channel specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Nigeria's Lagos-Abuja corridor exhibit the highest price elasticity, while South African pharmaceutical channels absorb premium isolates with minimal volume sensitivity. East African feed mills occupy the middle tier, trading specification flexibility for cost containment.
South Africa
The Department of Agriculture, Land Reform and Rural Development enforces feed safety protocols that redirect capital toward certified cold-chain infrastructure. Cold-chain certification requirements favor local processing facilities over informal imports. Johannesburg and Cape Town industrial zones concentrate dairy protein isolate production serving diabetic and renal patient populations through pharmacy networks.
Nigeria
Quick-service restaurant chains and packaged food manufacturers in the Lagos-Abuja corridor drive procurement reformulation with locally sourced soy and black soldier fly protein concentrates. The national food and drug regulator tightens mycotoxin thresholds that elevate testing costs for plant protein handlers. Lagos industrial zones face compressed compliance timelines as exporters simultaneously satisfy domestic and cross-border requirements.
Kenya
The Bureau of Standards coordinates mycotoxin maximum residue limits exceeding legacy Codex thresholds, forcing grain handlers into optical sorting investments. Nairobi food processors deploy twin-screw extruders to achieve fibrous structures from sunflower and fava bean proteins previously requiring imported inputs. Ethiopian border corridors channel regional oilseed crushing capacity toward East African meat analog manufacturers.
Tanzania
Sunflower and cowpea processing potential remains underexploited despite access to regional trade corridors and expanding feed mill capacity. Agricultural marketing cooperatives lack capital for compliance infrastructure that Kenyan and South African standards demand. Dar es Salaam and Mwanza processing hubs aggregate regional oilseed supply for distribution to Kenyan and Ugandan feed operations.
Uganda
Feed mill capacity expansion outpaces domestic protein processing infrastructure, creating import dependency for high-purity concentrates. The country's national standards body observes Kenyan and South African regulatory developments while drafting national guidelines. Kampala industrial zones concentrate informal trading networks that face gradual formalization pressure from emerging mycotoxin enforcement.
Africa Protein Market Competitive Environment
Agribusiness conglomerates and dairy cooperatives split the market structure, with multinational nutrition specialists occupying a distinct service-intensive tier. The vendor base concentrates around three strategic archetypes: grain-and-oilseed traders with pan-African infrastructure, dairy protein specialists with medical channel access, and integrated taste-nutrition system providers. Competitive moves center on backward integration into crushing capacity and technical service team expansion.
Among agribusiness conglomerates with pan-African infrastructure, Cargill Incorporated anchors the grain-and-oilseed trader archetype. Fonterra Co-operative Group Limited represents the dairy cooperative model with specialized medical nutrition positioning. Kerry Group plc exemplifies the integrated taste-nutrition system provider archetype that reduces formulation complexity for African food manufacturers.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Fonterra Co-operative Group Limited |
| Hilmar Cheese Company Inc. |
| International Flavors & Fragrances, Inc. |
| Kerry Group plc |
| Arla Foods amba |
| Glanbia PLC |
| Royal FrieslandCampina |
| AgriProtein |
| Others |
Value Chain & Pricing Dynamics
The Dar es Salaam-Mombasa corridor's refrigerated freight costs compress margins for protein isolates moving inland, concentrating supply power among South African processors with captive cold-chain assets while forcing Nigerian buyers into three-tier pricing separation based on certification grade, volume commitment, and technical service bundling.
Pricing Analysis
After-sales formulation consulting and extended technical support contracts drive lifetime value capture for protein suppliers serving African food manufacturers. Three-tier pricing structure across premium certified-isolate, standard food-grade concentrate, and economy feed-meal levels reflects digestibility scoring and cold-chain documentation intensity. Cost compression in standard tiers is intensifying because Kenyan and Nigerian regulators are harmonizing mycotoxin thresholds that elevate testing overhead. Quick-service restaurant procurement teams in Lagos show the highest price elasticity, while South African pharmacy channels serving renal patient populations absorb premium dairy isolates with minimal volume sensitivity.
Supply Chain Analysis
Tariff exposure between South Africa and SADC trading partners dominates supply chain risk planning for protein processors seeking regional market access. Raw material supply draws from Nigerian soy crushing corridors, Kenyan sunflower processing hubs, and Tanzanian cowpea aggregators. Black soldier fly larvae meal and imported pea protein isolates represent critical input dependencies with single-source vulnerability concentrated in extrusion technology providers outside the continent. Distribution runs through certified cold-chain operators in Johannesburg and Nairobi, with informal traders handling residual volume in Lagos traditional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's protein market fragments across formulation complexity tiers, as Nigerian quick-service restaurant chains and South African pharmaceutical channels diverge in procurement sophistication and create distinct supplier niches.
For Market Incumbents: Entrench laboratory-service capabilities as the primary defensive moat against regional oilseed crushers expanding downstream into finished concentrates. Cargill and Fonterra should deepen backward integration into Tanzanian and Ugandan sunflower and cowpea crushing capacity before East African competitors achieve compliance infrastructure parity. Certification investment in Kenya Bureau of Standards and South African national standards body protocols remains the priority lever for margin defense. For New Entrants and Emerging Players: Establish a beachhead in Tanzania's underexploited processing corridor by aggregating agricultural marketing cooperative supply into export-grade concentrate production. The most penetrable segment sits with East African feed mills seeking alternatives to imported fishmeal, where black soldier fly protein offers amino acid parity with carbon credit eligibility. A go-to-market angle anchored in organic waste diversion partnerships with municipal authorities unlocks site access and feedstock security. For Investors and Strategic Acquirers: South Africa's Department of Agriculture feed safety protocol enforcement reshapes the acquisition landscape by elevating capital requirements for cold-chain certification and marginalizing informal traders. Long-term viability across a 5-10 year window favors processors with integrated laboratory and logistics capabilities over pure trading operations. The acquisition target archetype combines East African oilseed crushing assets with South African regulatory compliance infrastructure. The signal to watch is mycotoxin threshold harmonization between Kenya's Bureau of Standards and Nigeria's national food and drug regulator, which would compress compliance timelines and accelerate formalization pressure on traditional market channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Capacity | Cargill's pan-African grain infrastructure secures captive soy and sunflower supply for Nigerian food manufacturers. |
| Cold-Chain Certification Investment | South Africa's Department of Agriculture protocols favor processors with continuous temperature logging over informal imports. |
| Technical Service Team Expansion | Kerry Group's integrated taste-nutrition systems reduce formulation complexity for East African meat analog producers. |
| Carbon Credit Monetization Program | AgriProtein's black soldier fly facilities qualify for voluntary carbon markets through organic waste diversion. |
| Pharmacy Channel Partnership | Fonterra's dairy protein isolates reach diabetic and renal patients through South African clinic networks. |
Study Parameters
A standing panel of food processing procurement managers, feed mill technical directors, cold-chain logistics operators, and national standards body regulators provided ongoing calibration throughout the study period. Primary interviews with quick-service restaurant supply chain heads and pharmaceutical distribution specialists were cross-referenced against customs records, agricultural ministry production statistics, and national food and drug administration filings. Bottom-up volume modeling across crushing facilities and feed mill offtake agreements was triangulated with top-down expenditure analysis from packaged food manufacturers and supplement distributors.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product type, end-user sophistication tier, distribution channel certification level, and regional regulatory cluster. CAGRs were derived from trend extrapolation of oilseed crushing capacity additions, insect protein facility commissioning timelines, and cold-chain infrastructure investment pipelines. Forecast inputs included black soldier fly production yield curves, mycotoxin testing cost trajectories, and pharmacy channel expansion rates in Lagos and Johannesburg.
Stress conditions across currency volatility, shipping delay duration, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding East African oilseed supply response and South African cold-chain certification adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Gluten Substitute Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Global Konjac Glucomannan Market