
 Seaweed Protein Market | 2026-2036
Seaweed Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Seaweed Protein Market Analysis
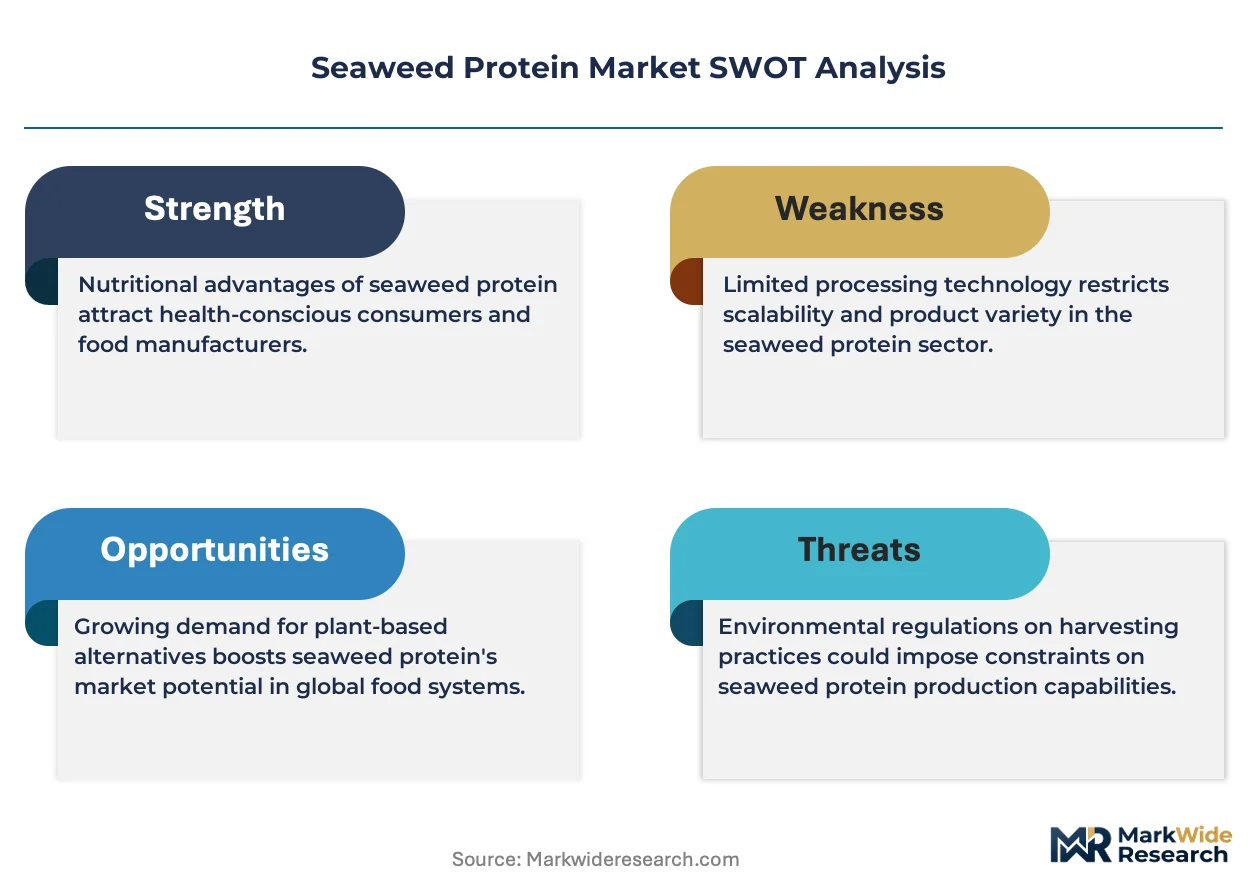
Pharmaceutical-grade protein isolates is redrawing competitive boundaries in the seaweed protein sector. Cargill Incorporated leverages its global supply chain infrastructure to secure multi-year offtake agreements with North Atlantic harvesters. Qingdao Brightmoon Seaweed Group Co., Ltd anchors China's domestic market through backward integration into cultivated kelp beds in Shandong Province. Acadian Seaplants specializes in wild-harvested Ascophyllum from Canada's Maritime provinces, sustaining premium positioning through proprietary extraction protocols.
Seaweed protein comprises concentrated amino acid fractions derived from brown, red, and green macroalgae species, typically processed through aqueous extraction or enzymatic hydrolysis to achieve protein content exceeding 50% by dry weight; its primary commercial purpose centers on delivering functional nutrition and emulsification properties to formulated food systems. Extracts command the dominant value share owing to superior bioavailability metrics and standardized amino acid profiles that cosmetic formulators prize. Powders represent the fastest-expanding product type as sports nutrition brands integrate them into plant-based recovery formulations. Food & Beverages application generates the deepest margin pool, driven by clean-label reformulation mandates across European and North American retail channels.
EFSA novel food authorization pathways determine market access timelines for European entrants, while FDA GRAS self-affirmation governs US commercialization routes for established species. China's SAMR implements GB standards for algae-derived food ingredients, creating divergent compliance architectures for exporters. Stakeholders must monitor regulatory harmonization progress between the EU Green Deal's bioeconomy targets and national seaweed cultivation permitting regimes to anticipate supply chain reconfigurations.
Market Dynamics
EFSA novel food authorization timelines compress competitive windows for European entrants while cold-water kelp farming cooperatives along Norway's Atlantic coastline consolidate upstream supply control.
Growth Catalysts
- EU Green Deal bioeconomy targets:Mandates for sustainable protein sourcing accelerate procurement of Ascophyllum nodosum extracts by plant-based meat manufacturers seeking clean-label positioning.
- Enzymatic hydrolysis advances:Improved extraction protocols raise protein content above 50% dry weight, enabling sports nutrition brands to integrate seaweed isolates into recovery formulations.
- Nordic nutraceutical clusters:Premium-grade protein isolate demand concentrates around Oslo and Bergen formulators seeking standardized amino acid profiles for cosmetic applications.
Market Restraints
- Wild harvest dependency:Canada's Maritime provinces and Ireland's western coasts face seasonal biomass variability, constraining year-round isolate supply for pharmaceutical-grade specifications.
- Input cost volatility:Energy-intensive drying operations expose processors to natural gas price swings, compressing margins on spray-dried protein powders.
- Regulatory fragmentation:Divergent GB standards under China's SAMR versus FDA GRAS self-affirmation pathways force dual compliance investments for exporters.
Strategic Opportunities
- Shandong Province cultivation expansion:Backward integration into cultivated kelp beds offers volume scale for domestic Chinese market penetration and reduced wild harvest reliance.
- Cosmetic formulator channel:Bioavailability metrics prized by premium skincare brands create pricing power for standardized extract grades.
- EU AI Act supply chain transparency:Automated traceability requirements favor vertically integrated harvesters with documented chain-of-custody systems.
Industry Challenges
- Specialized extraction technician scarcity:Aqueous and enzymatic processing expertise remains concentrated among legacy marine biotechnology programs in Trondheim and Halifax.
- Novel food dossier preparation timelines:EFSA scientific opinion processes extend 18-24 months, delaying revenue recognition for new species entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seaweed Protein Market |
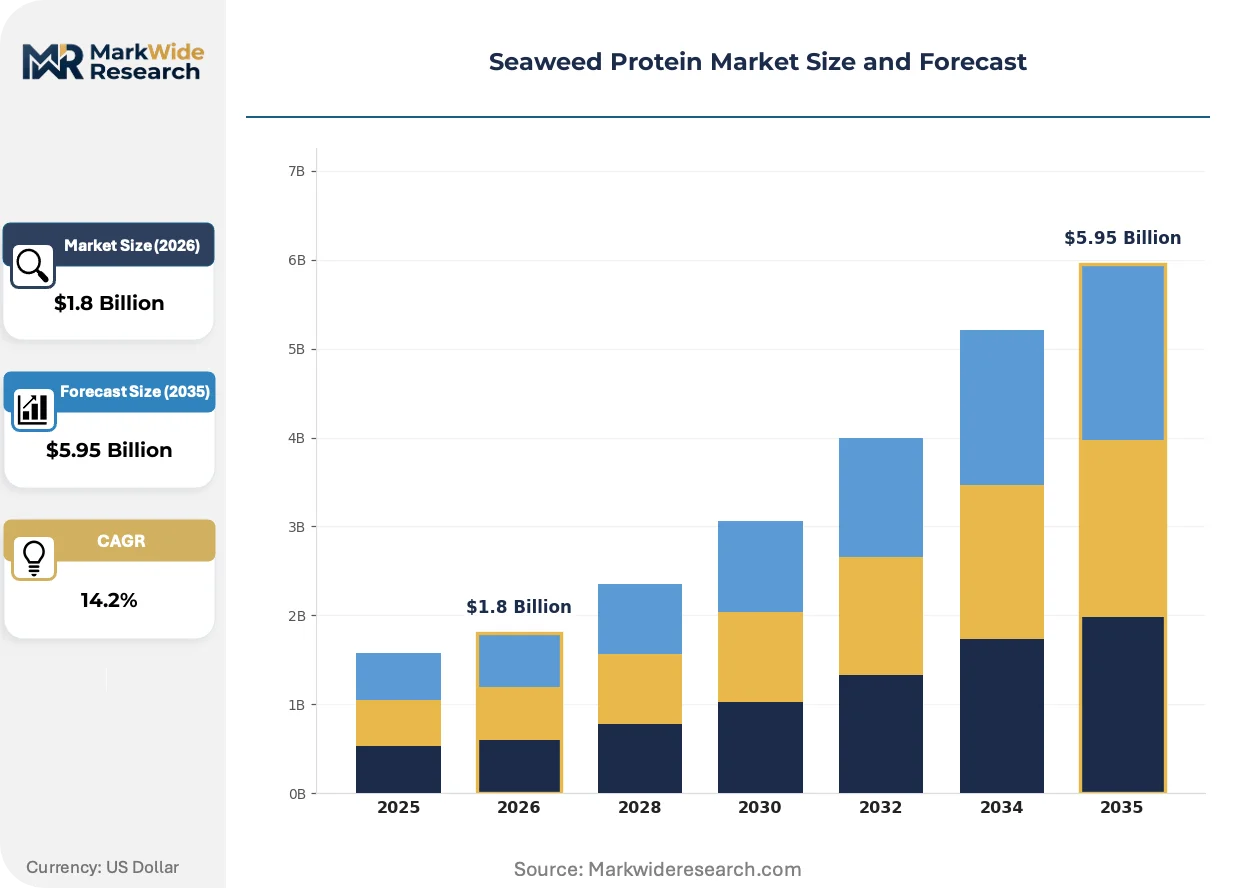
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seaweed, Extracts, Powders, Snacks Application: Food & Beverages, Animal Feed, Dietary Supplements, Cosmetics End User: Food Manufacturers, Health Enthusiasts, Restaurants, Cosmetics Brands Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | CP Kelco U.S., Inc., Algaia, Cargill Incorporated, Qingdao Gather Great Ocean Algae Industry Group Co., Ltd, Acadian Seaplants, Algea, Qingdao Brightmoon Seaweed Group Co., Ltd, Gelymar SA, Irish Seaweeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seaweed Protein Market Emerging Trajectories
Processing technology divergence and regulatory transparency mandates are compressing traditional competitive moats while opening white space for traceability-integrated supply chains.
Cell disruption via pulsed electric field treatment is fragmenting conventional thermal extraction dominance. Nordic biorefinery operators adopt this method to preserve heat-labile amino acids in pharmaceutical-grade isolates. The technology compresses energy input requirements by half, enabling smaller-scale processors to compete on isolate purity metrics previously controlled by capital-intensive spray-dry facilities.
REACH registration requirements for algae-derived novel ingredients tighten substance characterization obligations for European market access. ECHA dossier demands force harvesters to invest in comprehensive toxicological profiling beyond basic nutritional assays. Cosmetic formulators respond by consolidating supplier bases toward entities with pre-submitted technical packages.
Clean-label reformulation mandates from European retail channels drive direct contracting between food manufacturers and named harvester cooperatives. Traditional ingredient distributors lose margin capture as buyers seek documented provenance for ESG reporting. This pattern concentrates procurement leverage among Norwegian and Irish entities with Marine Stewardship Council chain-of-custody certification.
Seaweed Protein Market Segmentation
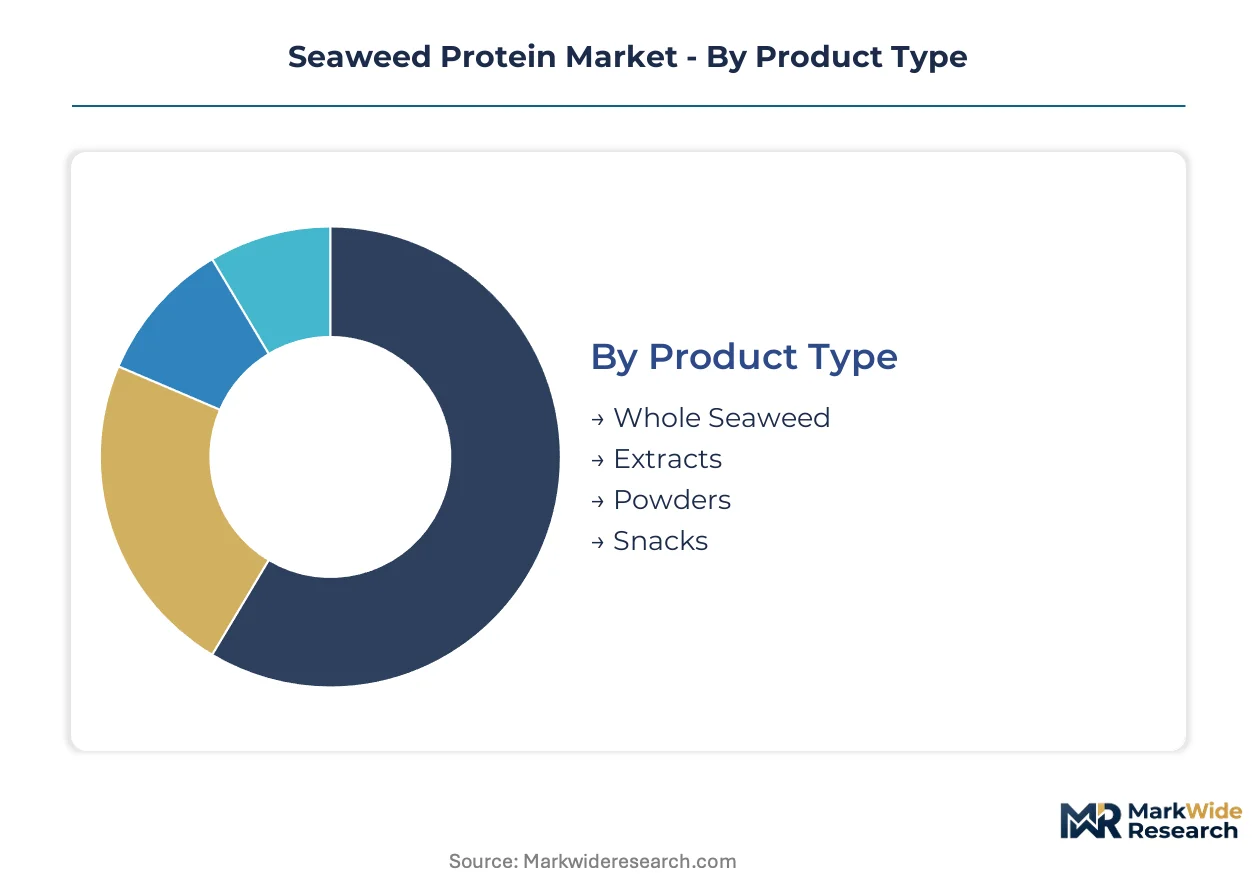
Seaweed protein segmentation reflects divergent margin structures across processing intensity tiers. Extracts and isolates command premium positioning through bioavailability standardization, while commodity whole seaweed serves volume-driven feed applications.
Product Type:
Margins concentrate in processed isolates where extraction protocols create defendable specification tiers.
- Extracts:Concentrated amino acid fractions exceeding 50% protein content by dry weight, produced through aqueous or enzymatic hydrolysis. Demand clusters around Nordic nutraceutical formulators in Oslo and Bergen seeking standardized profiles for cosmetic applications, constrained by EFSA novel food authorization timelines.
- Powders:Spray-dried protein isolates with functional emulsification properties. Sports nutrition brands in Germany and the Netherlands integrate these into plant-based recovery formulations, driven by clean-label reformulation mandates from European retail channels.
- Whole Seaweed:Minimally processed biomass for direct incorporation or further processing.
- Snacks:Consumer-ready formats targeting health-conscious snacking occasions.
The dominant share belongs to Extracts, while Powders is closing the gap fastest.
Application:
Commercial traction varies sharply by regulatory pathway complexity and end-use specification tolerance.
- Food & Beverages:Plant-based meat manufacturers accelerate procurement of Ascophyllum nodosum for clean-label positioning, particularly in Germany and France where EFSA approvals streamline ingredient access.
- Cosmetics:Premium skincare brands prize bioavailability metrics and documented chain-of-custody, consolidating supplier bases toward MSC-certified Norwegian and Irish harvesters.
- Dietary Supplements:Capsule and tablet formats targeting amino acid supplementation.
- Animal Feed:Volume-driven segment with lower specification thresholds and price-sensitive procurement.
Food & Beverages holds the deepest margin pool, though Cosmetics is expanding most quickly.
End User:
Procurement sophistication separates direct manufacturers from intermediaries.
- Food Manufacturers:Direct contracting with named harvester cooperatives is displacing traditional distributors as ESG reporting requirements harden.
- Cosmetics Brands:Consolidating toward suppliers with pre-submitted REACH dossiers and comprehensive toxicological profiling.
- Health Enthusiasts:Individual consumers seeking functional nutrition products.
- Restaurants:Foodservice channels incorporating seaweed protein into menu innovation.
Food Manufacturers dominate volume commitment, while Cosmetics Brands is gaining share fastest.
Distribution Channel:
Channel economics favor direct relationships for high-specification grades.
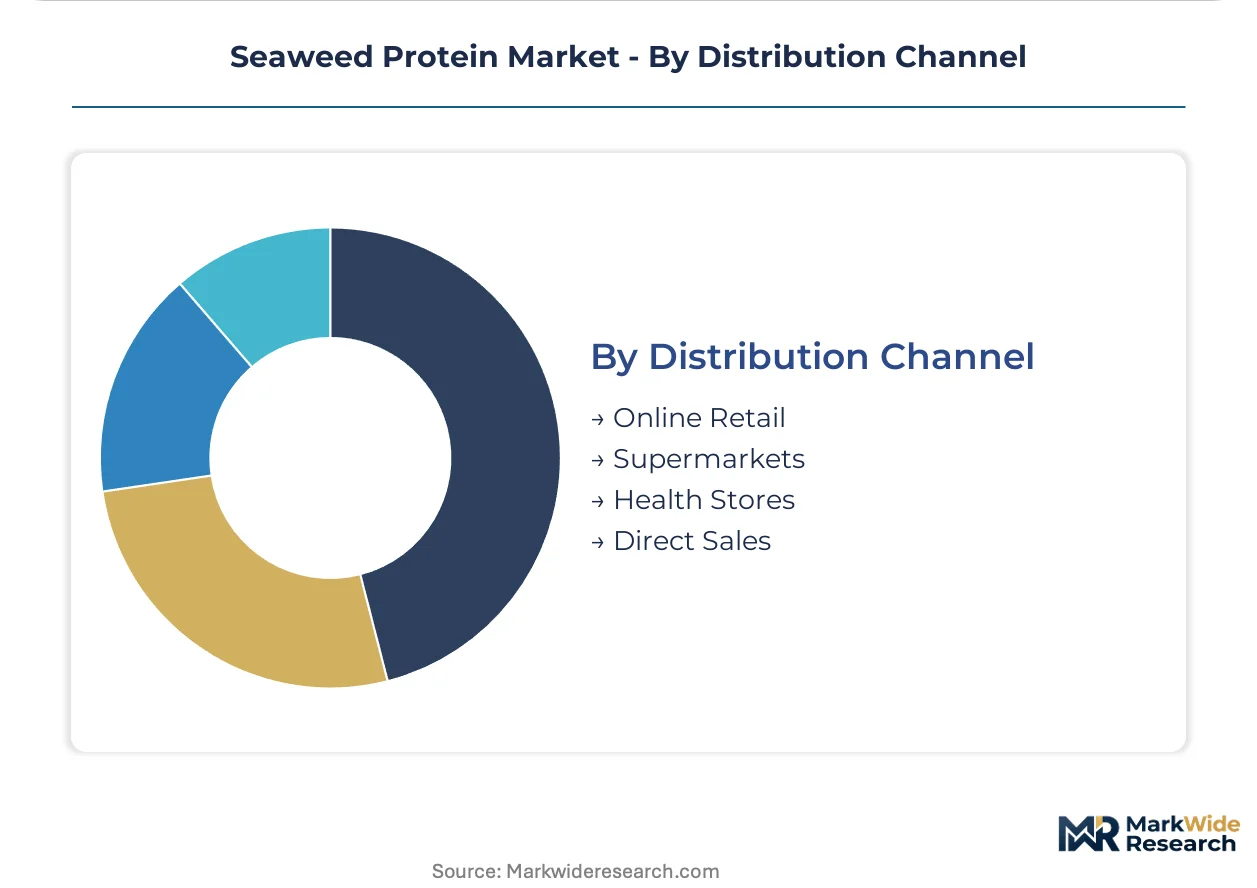
- Direct Sales:Named contracts between processors and formulators enable documented provenance for EU AI Act traceability compliance.
- Online Retail:E-commerce platforms serving health enthusiasts and small-scale cosmetics brands with lower minimum order quantities.
- Supermarkets:Mass retail penetration for consumer-facing snack and powder formats.
- Health Stores:Specialty retail targeting supplement-oriented consumers.
Direct Sales captures the premium tier, while Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-water kelp farming cooperatives along Norway's Atlantic coastline command upstream supply control, while enzymatic extraction facilities cluster near industrial biotech corridors in Germany and the Netherlands. Procurement leverage concentrates among entities with documented chain-of-custody certification spanning the North Atlantic basin.
Norway
Ascophyllum nodosum harvesters supply premium-grade protein isolates to Oslo and Bergen nutraceutical formulators seeking standardized amino acid profiles. The Norwegian Food Safety Authority coordinates with EFSA on novel food dossier preparation for expanded species approvals. Tromsø-based marine biotechnology programs train specialized extraction technicians for aqueous and enzymatic processing protocols.
Germany
Plant-based meat manufacturers accelerate procurement of seaweed extracts for clean-label reformulation mandates from major retail channels. EFSA novel food authorization timelines determine market access for new ingredient entrants seeking sports nutrition applications. Hamburg and Bremen harbor biorefinery operators adopt pulsed electric field treatment to preserve heat-labile amino acids in pharmaceutical-grade isolates.
China
Shandong Province kelp cultivation expansion offers volume scale for domestic market penetration and reduced wild harvest dependency. SAMR implements GB standards for algae-derived food ingredients, creating compliance architecture distinct from FDA and EFSA pathways. Qingdao anchors backward integration into cultivated kelp beds for standardized protein powder production.
Canada
Wild-harvested Ascophyllum from the Maritime provinces sustains premium positioning through proprietary extraction protocols for cosmetic formulators. Health Canada and PMRA coordinate on novel ingredient assessments for cross-border export eligibility. Halifax marine biotechnology programs concentrate aqueous processing expertise among legacy training institutions.
Ireland
Western coast harvesters face seasonal biomass variability constraining year-round isolate supply for pharmaceutical-grade specifications. EU Green Deal bioeconomy targets accelerate sustainable protein sourcing mandates for domestic food manufacturers. Galway and Cork processing facilities develop spray-dried protein powders for sports nutrition brand integration.
Seaweed Protein Market Vendor Landscape
Concentration sits with vertically integrated harvester-processors and multinational agribusiness conglomerates securing multi-year offtake agreements. The competitive structure separates wild-harvest specialists with proprietary extraction protocols from cultivation-scale operators in Shandong Province. Three archetypes dominate: North Atlantic wild-harvest entities with Marine Stewardship Council certification, Asian cultivation-integrated processors, and global agribusiness traders leveraging supply chain infrastructure. Dominant competitive moves include backward integration into kelp beds and direct contracting with named harvester cooperatives displacing traditional distributors.
Among North Atlantic wild-harvest specialists, Acadian Seaplants and Irish Seaweeds represent the MSC-certified tier with documented chain-of-custody systems prized by cosmetic formulators. Cargill Incorporated anchors the multinational agribusiness archetype, leveraging global infrastructure for multi-year offtake agreements with Atlantic harvesters. Qingdao Brightmoon Seaweed Group Co., Ltd exemplifies the cultivation-integrated model through backward integration into Shandong Province kelp beds.
| Leading Market Players |
|---|
| CP Kelco U.S., Inc. |
| Algaia |
| Cargill Incorporated |
| Qingdao Gather Great Ocean Algae Industry Group Co., Ltd |
| Acadian Seaplants |
| Algea |
| Qingdao Brightmoon Seaweed Group Co., Ltd |
| Gelymar SA |
| Irish Seaweeds |
| Others |
Supply Flow & Price Mechanics
Multi-year offtake agreements between North Atlantic harvesters and multinational agribusiness buyers lock in both supply access and price visibility, insulating premium-grade isolate procurement from spot-market volatility while compressing margins for uncontracted processors exposed to natural gas price swings in energy-intensive drying operations.
Pricing Analysis
EFSA novel food authorization pathways dictate the pricing tier structure across the European market. Three-tier pricing structure across premium pharmaceutical-grade isolates, standard food-grade extracts, and economy whole-seaweed biomass reflects certification intensity and protein standardization levels. Pricing pressure stems from enzymatic hydrolysis technology diffusion enabling smaller-scale processors to compete on purity metrics previously controlled by capital-intensive facilities. Food manufacturers exhibit highest price sensitivity due to clean-label reformulation mandates, while cosmetic formulators show lowest sensitivity given bioavailability-driven supplier consolidation.
Supply Chain Analysis
Inventory cycles for dried kelp biomass extend 6-9 months due to seasonal harvest windows and curing requirements before aqueous processing. Supply concentrates in Norway, Canada, and China, with wild-harvest dependency in the North Atlantic contrasting Shandong Province cultivation scale. Raw material flows draw from cold-water kelp beds, enzymatic processing reagents, and natural gas for spray-drying operations. Single-source vulnerability runs through MSC-certified Norwegian cooperatives supplying premium cosmetic grades. Distribution runs through direct sales contracts with named harvester-processor entities displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Seaweed Protein Market is entering a cyclical recovery phase as EFSA novel food authorization backlogs clear and EU Green Deal bioeconomy procurement mandates accelerate sustainable protein sourcing commitments from institutional foodservice buyers.
For Market Incumbents: Secure multi-year offtake agreements with emerging plant-based meat manufacturers before enzymatic hydrolysis technology diffusion erodes extraction-protocol moats. Invest in pulsed electric field treatment capacity to preserve heat-labile amino acid premiums against thermal extraction commoditization. Defend positioning through Marine Stewardship Council chain-of-custody certification investments that cosmetic formulators increasingly require for ESG reporting compliance.
For New Entrants and Emerging Players: Anchor in Shandong Province cultivation expansion where backward integration into kelp beds offers volume scale without wild-harvest seasonal constraints. Target sports nutrition powder formulations in Germany and the Netherlands as the most penetrable segment given clean-label reformulation urgency and lower regulatory pathway complexity versus pharmaceutical-grade isolates. Pursue direct-to-cosmetic-formulator sales models bypassing traditional distributor markups through documented provenance platforms.
For Investors and Strategic Acquirers: Wild-harvest specialists with proprietary extraction protocols and pre-submitted REACH dossiers represent the most defensible acquisition archetype given ECHA substance characterization tightening. Long-term viability hinges on regulatory harmonization progress between EU Green Deal targets and national cultivation permitting regimes. Watch for EFSA scientific opinion timeline compression as the inflection signal indicating accelerated revenue recognition for novel species entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivated Kelp Beds | Shandong Province expansion reduces wild-harvest dependency and enables volume scale for standardized powder production. |
| Pulsed Electric Field Treatment Adoption | Nordic biorefinery operators preserve heat-labile amino acids while halving energy input requirements versus thermal extraction. |
| REACH Dossier Pre-Submission | ECHA substance characterization obligations tighten, forcing harvesters to invest beyond basic nutritional assays for cosmetic access. |
| Direct Sales Contracting with Named Harvesters | EU AI Act traceability mandates favor documented chain-of-custody systems displacing traditional distributor channels. |
| EFSA Novel Food Dossier Investment | Oslo and Bergen formulators accelerate procurement as scientific opinion timelines compress competitive windows for expanded species. |
Methodological Framework
A standing panel of marine biotechnology extraction technicians, nutraceutical formulators, plant-based meat procurement leads, and cosmetic R&D directors provided ongoing calibration across the analysis window. Primary interviews with North Atlantic harvester cooperatives and Shandong Province cultivation operators combined with secondary validation from EFSA novel food register entries, SAMR GB standards filings, and Marine Stewardship Council certification databases. Bottom-up volume modeling triangulated against top-down expenditure flows from EU Green Deal bioeconomy allocation disclosures.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for algae-derived protein isolates and EPC contractor biorefinery capex tracking. Segmentation dimensions spanned product type hierarchy, application specification tolerance, end-user procurement sophistication, and distribution channel control intensity. CAGRs derived from installed extraction capacity buildout curves cross-referenced with EFSA approval timeline probability distributions. Industry-specific inputs included enzymatic hydrolysis yield improvement trajectories and cold-water kelp biomass productivity coefficients.
Decision-makers should treat outputs as directional under sustained EU Green Deal funding commitments and EFSA staffing capacity assumptions; material deviation in either would warrant model refresh. Revision becomes warranted when EFSA scientific opinion backlog duration crosses 30-month thresholds or when natural gas price volatility exceeds historical bands for spray-drying operations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Corn-Based Protein Market