
 Algae Fats Market | 2026-2036
Algae Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Algae Fats Market Analysis
Pharmaceutical and nutraceutical demand is hardening as algae fats displace conventional marine oils in softgel and liquid supplement formulations. DSM-Firmenich AG leverages its integrated biotechnology platform to control strain development and downstream processing. Corbion N.V. sustains commercial-scale fermentation capacity across European and North American facilities. Cargill Incorporated anchors agricultural distribution channels that extend algae lipid access into mainstream food ingredient procurement.
Algae fats comprise triglycerides, phospholipids, and glycolipids extracted from phototrophic or heterotrophic microalgal biomass, with omega-3 eicosapentaenoic acid and docosahexaenoic acid concentrations reaching 30–60% of total lipids depending on strain and cultivation conditions. These lipids serve as functional ingredients in brain health supplements, infant formula fortification, and cosmeceutical emulsions where oxidative stability and vegan positioning command premium positioning. Omega-3 product types dominate current revenue contribution due to established clinical validation and physician recommendation channels. Microalgae sources are expanding fastest as closed photobioreactor systems reduce contamination risk and improve batch consistency relative to open pond macroalgae cultivation. Supercritical fluid extraction methods concentrate margin pools by preserving heat-sensitive polyunsaturated fatty acids and eliminating residual solvent concerns that constrain food-grade applications.
EMA guidelines on novel food ingredients, FDA GRAS notification requirements, and REACH substance registration collectively shape market access timelines and purity specifications for algae fat entrants. EFSA health claim authorizations directly determine permissible marketing language for omega-3 cardiovascular and cognitive benefit positioning in European Union member states. Stakeholders must monitor regulatory divergence between jurisdictions where algae-derived lipids qualify for distinct labeling categories versus those where they remain classified under generic vegetable oil frameworks.
Market Dynamics
Fermentation-based heterotrophic cultivation is compressing production timelines and displacing phototrophic open-pond systems as the dominant supply architecture for pharmaceutical-grade algae lipids. This technology shift is concentrating capital deployment among biotechnology platforms with integrated strain-to-product capabilities.
Growth Catalysts
- EU Green Deal procurement mandates:European cosmetics formulators face binding sustainable sourcing requirements that disqualify conventional marine oils from premium product lines.
- Infant formula fortification protocols:Pediatric nutrition manufacturers in Germany and the Netherlands are accelerating algae-derived DHA integration to meet vegetarian certification standards.
- Closed photobioreactor systems:Contamination risk reduction and batch consistency improvements are driving adoption across nutraceutical contract manufacturers.
Market Restraints
- Feedstock cost volatility:Glucose and nitrogen source prices for heterotrophic fermentation fluctuate with agricultural commodity markets, compressing margin predictability.
- Extraction equipment concentration:Supercritical CO2 system manufacturers cluster in Germany and Switzerland, creating supply bottlenecks for new market entrants.
- EPA/DHA ratio limitations:Current microalgal strains deliver DHA-dominant lipid profiles that underperform fish oil equivalents in cardiovascular applications requiring EPA enrichment.
Strategic Opportunities
- Cosmeceutical emulsion applications:Oxidative stability and vegan positioning command premium pricing in French and German skincare formulations.
- REACH substance registration acceleration:Early movers securing full dossier approvals gain preferential access to EU industrial lubricant applications.
- Direct-to-practitioner distribution:Physician recommendation channels for omega-3 supplements are opening to algae-derived alternatives through specialized medical food networks.
Industry Challenges
- Downstream processing talent scarcity:Lipid extraction and purification specialists with supercritical fluid expertise command premium compensation and limit facility scaling.
- GRAS notification timelines:FDA novel food ingredient reviews for new algal strains extend commercialization schedules by 18-36 months.
- Strain IP fragmentation:Proprietary microalgae genetics are locked in university and startup patent portfolios, complicating freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algae Fats Market |
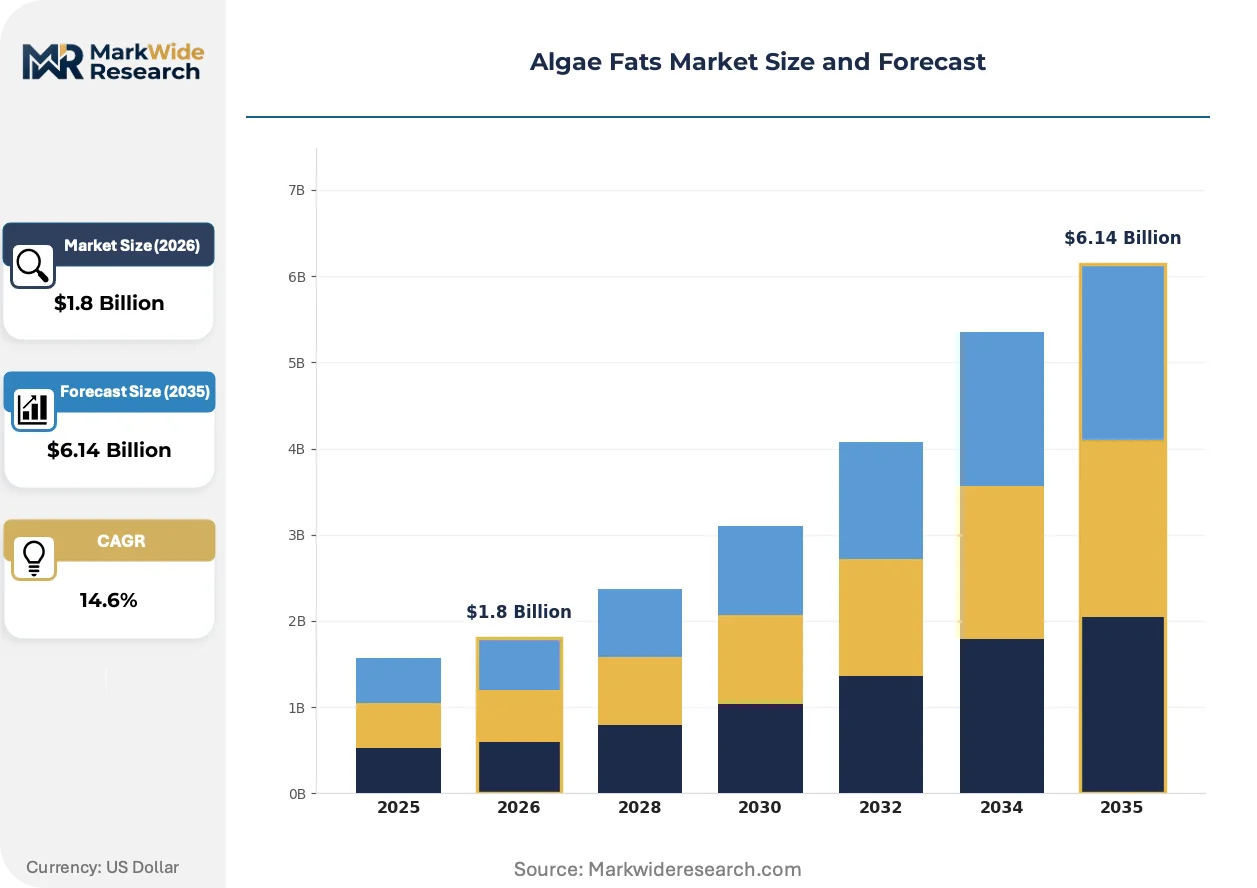
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
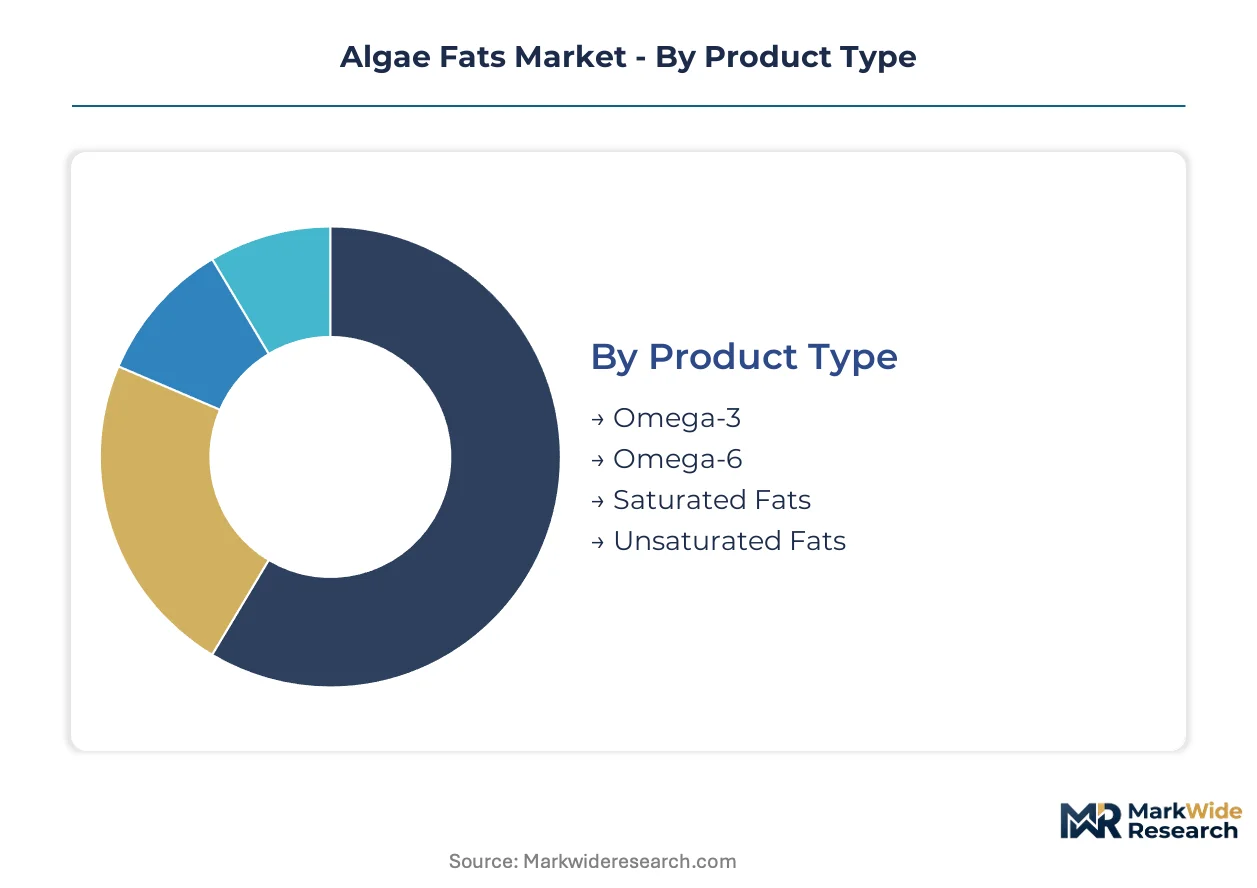
| Segmentation | Product Type: Omega-3, Omega-6, Saturated Fats, Unsaturated Fats Source: Microalgae, Macroalgae, Seaweed, Freshwater Algae Extraction Method: Supercritical Fluid Extraction, Solvent Extraction, Cold Pressing, Enzymatic Extraction Application: Food & Beverage, Nutraceuticals, Cosmetics, Biofuels |
| Companies Covered | DSM-Firmenich AG, Corbion N.V., BASF SE, Cargill Incorporated, Archer Daniels Midland Company, Cyanotech Corporation, Evonik Industries AG, Algatechnologies Ltd, Cellana Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algae Fats Market Emerging Trajectories
Biotechnology platforms are compressing the strain development cycle from years to months, enabling rapid customization of lipid profiles for specific end-use specifications. This acceleration is reshaping competitive dynamics between integrated producers and specialized extraction houses.
CRISPR-enabled metabolic engineering is rewriting the economics of EPA-enriched strain development. Pharmaceutical softgel manufacturers are adopting these modified strains ahead of nutraceutical producers, drawn by physician-grade purity requirements. The technology is compressing the performance gap with fish oil and enabling cardiovascular health claim applications previously blocked by EPA concentration shortfalls.
REACH substance registration deadlines are forcing cosmetics formulators to document full supply chain sustainability credentials. ECHA compliance costs are filtering out smaller ingredient traders and consolidating procurement relationships with vertically integrated algae oil producers. German and French formulators are responding by locking in multi-year offtake agreements with fermentation facilities holding complete registration dossiers.
Specialized medical food distributors are disintermediating traditional supplement retail channels for algae omega-3 products. Physician recommendation networks in Germany and the Netherlands are replacing mass-market pharmacy placement as the primary volume driver for premium formulations. This channel rotation is most visible in pediatric and prenatal nutrition segments where clinical validation carries decisive purchasing influence.
Algae Fats Market Segmentation
Algae fats command divergent certification pathways across pharmaceutical, food-grade, and industrial applications. EFSA health claims, FDA GRAS notifications, and REACH substance registrations segment procurement requirements and lock in distinct customer relationships. Manufacturers must align strain development and extraction protocols with the specific compliance architecture governing each end-use category.
Product Type:
EFSA cardiovascular and cognitive health claim authorizations apply differentially across fatty acid categories, with omega-3 concentrates facing the most stringent novel food dossier requirements.
- Omega-3:EPA and DHA concentrates reaching 30–60% of total lipids dominate pharmaceutical softgel and infant formula fortification. German pediatric nutrition manufacturers are accelerating vegetarian-certified DHA procurement to displace fish oil in prenatal supplements.
- Omega-6:Arachidonic acid and gamma-linolenic acid fractions serve cosmeceutical emulsion and specialized medical food applications. French skincare formulators leverage oxidative stability for premium anti-aging serums requiring REACH-compliant documentation.
- Saturated Fats:Palmitic and stearic acid fractions from heterotrophic fermentation supply industrial lubricant and biofuel feedstock markets.
- Unsaturated Fats:Monounsaturated oleic acid profiles from engineered strains target food-grade margarine and shortening replacements.
Leading the category by volume: Omega-3. Growing fastest: Omega-6.
Source:
Capital deployment intensity varies fourfold between closed photobioreactor systems and open pond cultivation, concentrating pharmaceutical-grade supply among biotechnology platforms with integrated infrastructure.
- Microalgae:Heterotrophic fermentation of Chlorella, Schizochytrium, and Crypthecodinium strains delivers batch consistency for pharmaceutical applications. DSM-Firmenich AG and Corbion N.V. anchor commercial-scale capacity in the Netherlands and Brazil.
- Macroalgae:Kelp and wakame lipid extraction serves lower-purity food ingredient and animal feed markets with minimal downstream processing investment.
- Seaweed:Laminaria and Ascophyllum sources from coastal harvesting operations supply hydrocolloid and limited lipid fraction markets in Norway and Ireland.
- Freshwater Algae:Spirulina and Aphanizomenon flos-aquae cultivation in open raceways targets nutraceutical powder applications with lower omega-3 purity thresholds.
Highest purity requirements attach to Microalgae. Steepest expansion trajectory: Microalgae.
Extraction Method:
Equipment manufacturer concentration in Germany and Switzerland creates supply bottlenecks for supercritical CO2 systems, advantaging early movers with installed capacity.
- Supercritical Fluid Extraction:CO2-based methods preserve heat-sensitive polyunsaturated fatty acids and eliminate residual solvent concerns for food-grade applications. BASF SE leverages this technology for pharmaceutical-grade omega-3 concentrates.
- Solvent Extraction:Hexane and ethanol systems dominate commodity-scale operations where purity specifications permit trace solvent residues.
- Cold Pressing:Mechanical extraction serves organic-certified and raw-positioned nutraceutical products with lower yield efficiency.
- Enzymatic Extraction:Cell-wall degrading enzymes enable selective lipid release from recalcitrant macroalgal biomass with reduced thermal degradation.
Premium pricing concentrates in Supercritical Fluid Extraction. Gaining share fastest: Enzymatic Extraction.
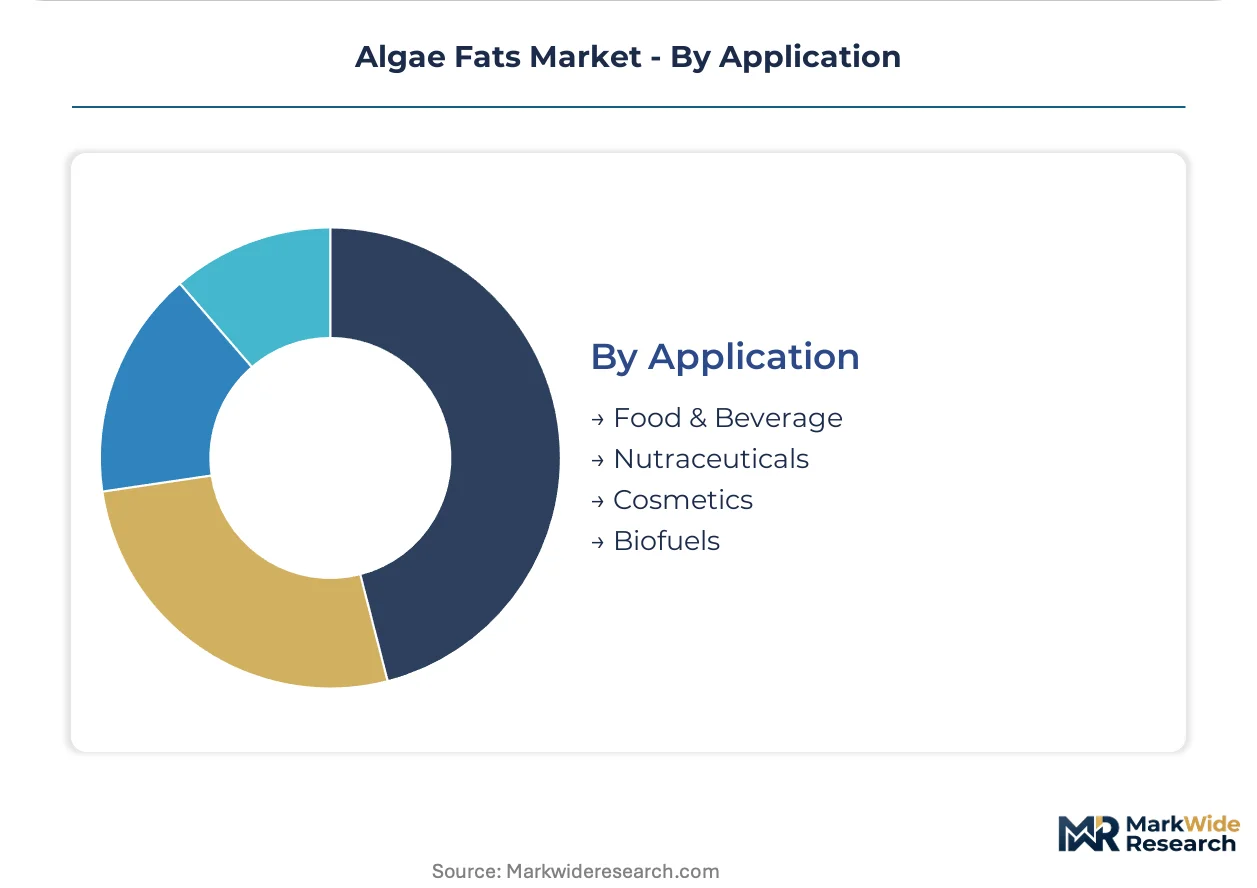
Application:
Channel access diverges sharply between physician recommendation networks for medical foods and mass-market retail for standard supplements.
- Nutraceuticals:Softgel and liquid supplement formulations drive volume through specialized medical food distributors and direct-to-practitioner channels. German physician networks are replacing pharmacy placement as the primary volume driver.
- Cosmetics:Emulsion and serum applications in French and German skincare command premium positioning through vegan certification and oxidative stability credentials.
- Food & Beverage:Infant formula fortification and functional food ingredient markets require FSSAI, FDA, and EFSA novel food approvals with extended timeline risk.
- Biofuels:Algae lipid transesterification for renewable diesel and aviation fuel applications competes on feedstock cost against agricultural oil alternatives.
Dominant revenue contribution: Nutraceuticals. Climbing the fastest: Cosmetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based fermentation clusters attract capital through EU Green Deal tax incentives and accelerated REACH registration pathways for sustainable lipid producers.
Germany
Pharmaceutical softgel manufacturers in North Rhine-Westphalia drive omega-3 procurement as EFSA health claim authorizations harden marketing requirements for cardiovascular positioning. REACH substance registration deadlines compress supplier qualification timelines. BASF SE anchors supercritical CO2 extraction capacity in Ludwigshafen, supplying pharmaceutical-grade concentrates to medical food distributors.
Netherlands
Pediatric nutrition formulators in the Randstad accelerate vegetarian-certified DHA integration for infant formula fortification. EMA novel food ingredient guidelines shape strain approval pathways for fermented microalgal lipids. DSM-Firmenich AG controls integrated biotechnology infrastructure spanning strain development to downstream processing in Delft.
United States
Dietary supplement contract manufacturers in California and Massachusetts adopt closed photobioreactor systems to secure FDA GRAS notifications for algae-derived omega-3. GRAS review timelines extend commercialization schedules by 18-36 months for new entrants. Specialized medical food distributors in Greater Boston disintermediate traditional pharmacy channels for practitioner-recommended formulations.
Brazil
ANVISA novel food regulations govern algae lipid importation for nutraceutical softgel production in São Paulo state. Heterotrophic fermentation feedstock costs fluctuate with domestic sugarcane glucose pricing. Corbion N.V. operates commercial-scale production facilities supplying Latin American infant formula manufacturers.
China
SAMR food ingredient registrations constrain foreign algae oil market access for infant formula fortification. Domestic heterotrophic fermentation capacity expands in Shandong Province to reduce import dependency. NMPA pharmaceutical-grade lipid specifications drive quality differentiation between local and international suppliers.
Algae Fats Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated biotechnology platforms commanding pharmaceutical-grade supply and agricultural distributors anchoring food ingredient volume. Market structure concentrates among fermentation operators with captive strain libraries and extraction capabilities. Three archetypes dominate: integrated life-science conglomerates with pharmaceutical pipelines, specialized algae biotechnology platforms, and agricultural commodity traders extending into alternative lipids. Competitive moves center on multi-year offtake agreements with cosmetics formulators and accelerated REACH dossier filings for industrial lubricant applications.
Within the integrated biotechnology tier, DSM-Firmenich AG and Corbion N.V. exemplify strain-to-product platform operators with European fermentation infrastructure. BASF SE occupies a position among diversified chemical conglomerates leveraging supercritical extraction technology for pharmaceutical-grade concentrates. Cargill Incorporated represents agricultural distribution archetypes extending procurement networks into alternative lipid sourcing.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| Corbion N.V. |
| BASF SE |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Cyanotech Corporation |
| Evonik Industries AG |
| Algatechnologies Ltd |
| Cellana Inc |
| Others |
Supply Flow & Price Mechanics
Supercritical fluid extraction specialists concentrated in Germany and Switzerland command premium compensation that widens spreads between pharmaceutical-grade and commodity-tier algae fat pricing. Labor-cost differentials between these technical hubs and emerging fermentation centers in Brazil and China directly stratify end-product tiers.
Pricing Analysis
Lead-time compression commands substantial premiums in algae fat procurement, with nutraceutical contract manufacturers paying marked-up rates for expedited pharmaceutical-grade omega-3 delivery while spot inventory of standard-grade lipids trades at discounted levels. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity: REACH-registered pharmaceutical grades, food-grade GRAS-notified intermediates, and industrial feedstock without health claim authorization. Cost compression in the standard tier intensifies as Brazilian and Chinese fermentation capacity expands glucose-fed heterotrophic output. Infant formula manufacturers exhibit lowest price sensitivity due to vegetarian certification requirements, while biofuel blenders anchor the economy tier with feedstock-cost parity demands.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Singapore coordinate hub-and-spoke patterns for algae fat intermediates, with specialized cold-chain handling for heat-sensitive omega-3 concentrates. Geographic supply concentration centers on the Netherlands, Germany, and Brazil, where DSM-Firmenich AG, Corbion N.V., and clustered fermentation facilities anchor pharmaceutical-grade output. Raw material dependencies rest on agricultural glucose from Brazilian sugarcane, nitrogen sources from European ammonia production, and supercritical CO2 equipment from German manufacturers. Single-source vulnerability in extraction equipment creates supply bottlenecks for new market entrants. Distribution runs through specialized medical food distributors in Germany and the Netherlands, bypassing traditional pharmaceutical wholesale channels for practitioner-recommended formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-based heterotrophic cultivation is displacing phototrophic open-pond systems as the dominant supply architecture, compressing production timelines from months to weeks and rewriting capital deployment priorities for algae fat producers.
For Market Incumbents: Anticipate CRISPR-enabled metabolic engineering disruption by locking in multi-year offtake agreements with cosmetics formulators before EPA-enriched strains achieve commercial scale. BASF SE and DSM-Firmenich AG should accelerate REACH dossier filings for industrial lubricant applications to exploit registration deadlines that filter smaller traders. Backward integration into proprietary strain libraries defends against university and startup patent fragmentation threatening freedom-to-operate. For New Entrants and Emerging Players: The mid-tier price gap between premium pharmaceutical-grade and economy biofuel-feedstock algae fats offers white-space entry for food-grade ingredient specialists. Target infant formula fortification in Brazil and China where ANVISA and SAMR novel food pathways remain less saturated than EMA routes. Direct-to-practitioner distribution through specialized medical food networks bypasses incumbent-controlled pharmacy shelf space. For Investors and Strategic Acquirers: Re-rating potential sits with integrated biotechnology platforms possessing captive fermentation and extraction infrastructure given EU Green Deal procurement mandates tightening sustainable lipid specifications. Long-term viability over the five-to-ten year horizon favors operators with commercial-scale heterotrophic capacity and complete REACH registration dossiers. Monitor EFSA health claim authorization timelines for EPA-enriched strains as the decisive inflection signal for cardiovascular positioning premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Corbion N.V.'s Brazilian fermentation scale-up secures Latin American infant formula supply dominance. |
| Backward Integration | DSM-Firmenich AG's strain development control eliminates royalty burdens from university patent holders. |
| Long-term Supply Agreement | French cosmetics formulators lock multi-year offtake with REACH-registered producers ahead of ECHA deadlines. |
| Regulatory Approval Pathway | Early FDA GRAS notification for new algal strains compresses 18-36 month commercialization timelines. |
| Joint Venture | German supercritical CO2 equipment partnerships alleviate supply bottlenecks for extraction capacity scaling. |
Methodological Framework
Independent corroboration across primary interviews with fermentation plant managers, downstream nutraceutical procurement leads, supercritical extraction equipment specialists, and ECHA regulatory consultants underwrites the qualitative findings. Secondary validation draws from REACH registration dossiers, FDA GRAS notification filings, EFSA novel food opinions, and customs trade data for algae lipid imports. Bottom-up strain capacity assessments and top-down end-use demand modeling triangulate volume estimates.
Comparable-period anchoring to historical fermentation yield improvements and extraction efficiency gains informs the projection framework across the analysis window. Segmentation dimensions include omega-3 concentration tier, cultivation architecture, extraction technology, and application regulatory cluster. CAGRs derive from fitted growth curves adjusted for EMA approval timeline risk and EU Green Deal procurement acceleration. Key inputs encompass glucose feedstock pricing volatility and supercritical equipment lead times.
Inputs from ECHA registration databases and FDA GRAS notification logs were available through the study window; gaps in proprietary strain performance data from integrated biotechnology platforms introduce uncertainty bands around yield assumptions. Forecasts reflect documented assumptions regarding heterotrophic fermentation adoption rates and REACH compliance cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
Pet Food Microalgae Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Seaweed Protein Market
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
North America Meal Products Replacement Market