
 Gluten-Free Meat Substitutes Market | 2026-2036
Gluten-Free Meat Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Meat Substitutes Market Insights
Subscription-based replenishment models for refrigerated gluten-free meat alternatives is hardening into a core revenue layer. Beyond Meat Inc. leverages direct-to-consumer channels to sustain repeat purchase rates. Impossible Foods Inc. anchors its position through foodservice partnerships with national restaurant chains. Quorn Foods differentiates via mycoprotein fermentation technology that naturally excludes gluten from its production process.
Gluten-free meat substitutes comprise protein-rich analogues formulated without wheat, barley, rye, or cross-contaminated oats, typically achieving less than 20 parts per million gluten content through dedicated processing lines and ingredient segregation protocols. These products serve consumers with celiac disease, non-celiac gluten sensitivity, and wheat allergies who require safe protein alternatives without sacrificing taste or texture. Pea protein and soy protein sources dominate formulation choices, with pea protein gaining traction among allergen-conscious buyers seeking soy-free options. Ready-to-eat applications command premium shelf space as convenience-driven purchasing reshapes retail allocation, while burger patties and sausages occupy the highest velocity positions in refrigerated cases.
FDA gluten-free labeling standards and EU Regulation 1169/2011 mandate strict allergen disclosure and cross-contact controls, compelling manufacturers to validate supply chain segregation and testing protocols. Health Canada and FSMA preventive controls in the United States impose additional documentation burdens on imported ingredient streams. Stakeholders must monitor evolving Codex Alimentarius revisions and emerging state-level allergen legislation to preempt compliance gaps before market access restrictions materialize.
Market Dynamics
Proliferation of dedicated gluten-free processing lines is compressing production economics while FDA and EU allergen disclosure mandates force capital redeployment toward segregation infrastructure.
Growth Catalysts
- Celiac Disease Prevalence:Diagnosed cases in Germany, Italy, and the United States sustain clinical demand for certified gluten-free protein alternatives.
- EU Regulation 1169/2011:Mandatory allergen labeling compels foodservice operators to source validated gluten-free meat substitutes.
- Pea Protein Isolation:Advances in wet-fraction extraction yield functional protein concentrates that replace wheat gluten in texture formation.
Market Restraints
- Input Cost Volatility:Yellow pea and faba bean prices fluctuate with Canadian and Australian harvest cycles.
- Supply Concentration Risk:Mycoprotein fermentation capacity clusters in the United Kingdom and the Netherlands.
- Technical Limitation:Gluten-free binders achieve inferior water-holding capacity versus wheat-based alternatives.
Strategic Opportunities
- Brazil:ANVISA's evolving allergen framework creates first-mover positioning for certified gluten-free meat analogues.
- Cellular Agriculture Convergence:Cultivated muscle tissue combined with plant-based scaffolding eliminates gluten from hybrid products.
- Direct-to-Consumer Cold Chain:Subscription refrigerated delivery bypasses retail slotting fees and builds loyalty data.
Industry Challenges
- Food Safety Certification Timeline:Gluten-free validation protocols add 4-6 months to new product commercialization.
- Segregated Production Capex:Dedicated extrusion and packaging lines demand capital outlays that strain mid-scale manufacturers.
- Cross-Contamination Testing Burden:ELISA and PCR verification at multiple supply chain nodes inflate quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Meat Substitutes Market |
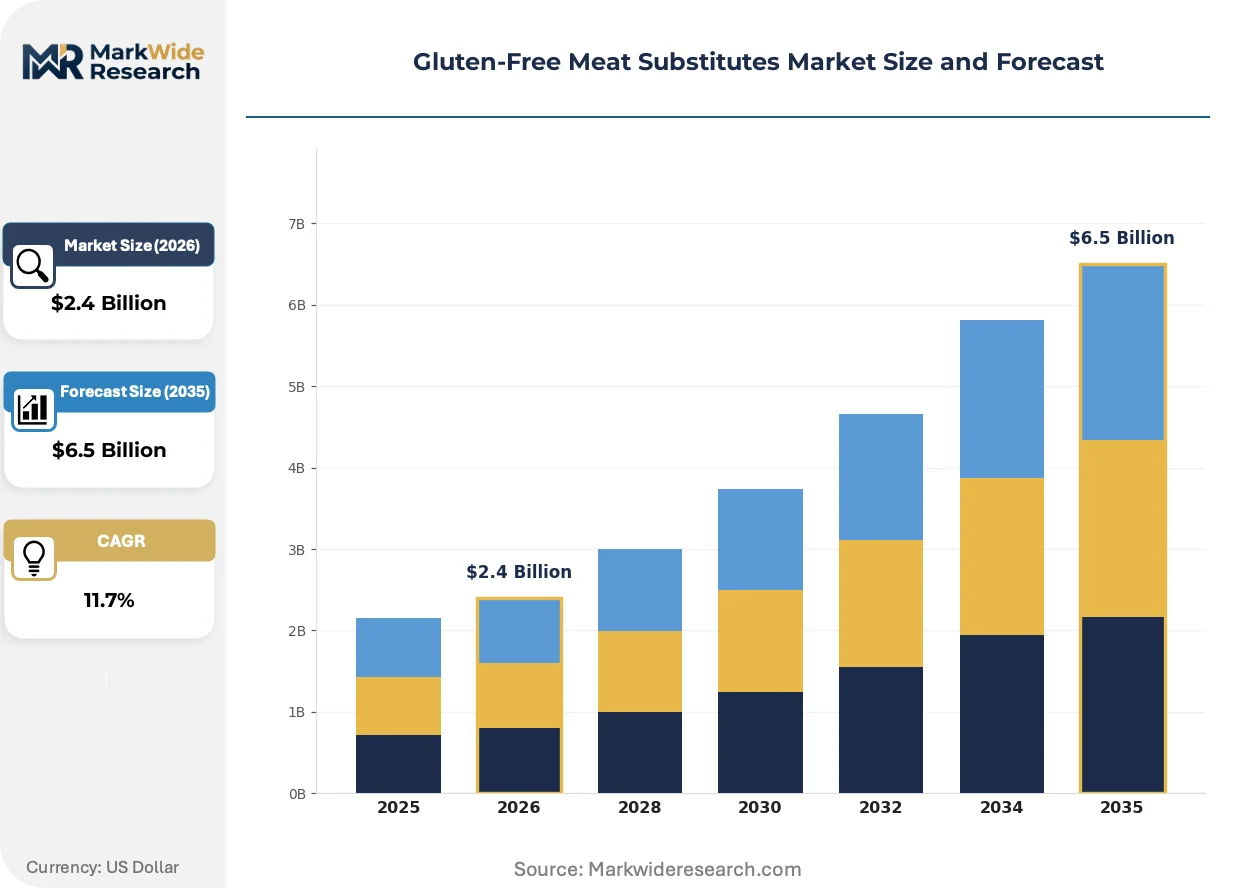
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Jackfruit Source: Pea Protein, Soy Protein, Mushroom, Almond Application: Ready-to-Cook, Ready-to-Eat, Restaurant, Home Cooking Form: Burger Patties, Sausages, Meatballs, Strips |
| Companies Covered | Beyond Meat Inc., Impossible Foods Inc., Conagra Brands, Inc., Quorn Foods, Tofurky, Field Roast, Lightlife Foods, Maple Leaf Foods Inc., Gardein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Meat Substitutes Market Trends and Innovations
Formulation science and regulatory enforcement are converging to redefine acceptable protein architecture, with automation and precision fermentation displacing conventional extrusion methods.
High-moisture extrusion technology is automating the production of fibrous meat textures previously dependent on gluten networks. Foodservice manufacturers in Germany and the United States are retrofitting lines to accommodate these systems. The shift compresses batch-to-batch variability while expanding the addressable market for soy-free, gluten-free alternatives.
EU F-Gas Regulation and FDA preventive controls under FSMA are tightening documentation requirements for imported protein isolates. Manufacturers must now validate every ingredient lot for gluten cross-contact. Small and mid-scale processors in Spain and Poland face disproportionate compliance burdens relative to integrated multinationals.
Buyer procurement of gluten-free meat substitutes is consolidating through centralized category management at national restaurant chains. Independent distributors lose shelf space to direct manufacturer agreements. This concentration is most visible in the United States, where Yum Brands and Chipotle Mexican Grill mandate supplier certification at the corporate level.
Gluten-Free Meat Substitutes Market Segmentation
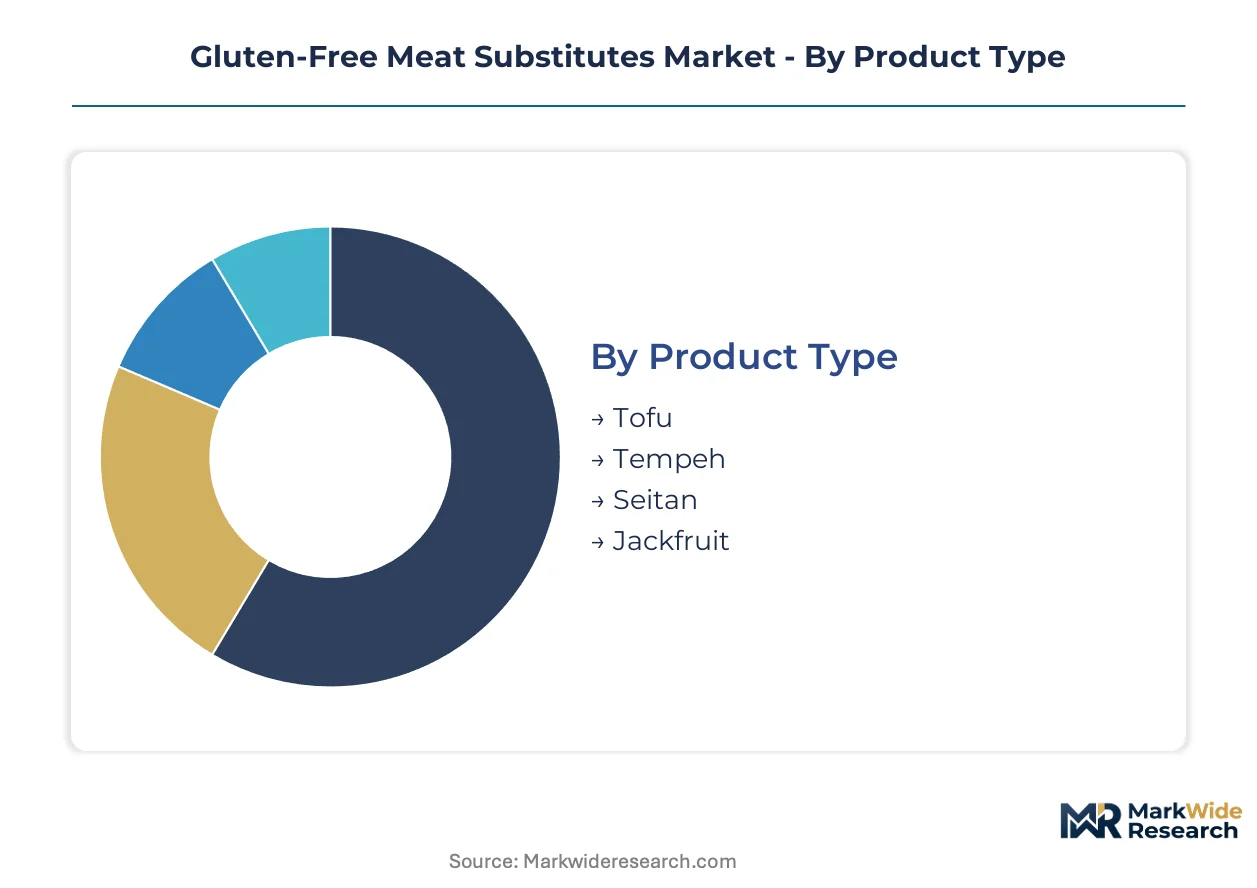
Gluten-free meat substitutes fragment across four critical dimensions that determine formulation strategy, pricing architecture, and channel access. Product type and protein source dictate manufacturing complexity and allergen risk profiles, while application and form shape cold-chain requirements and retail slotting economics.
Product Type:
Volume production concentrates on soy-derived formats, but premium positioning increasingly favors fermentation-based and whole-food alternatives that command clean-label premiums.
- Tofu:Water-extracted soy curd pressed into firm blocks delivers neutral flavor profiles suited for absorption-heavy cuisines. Restaurant chains in the United States and Germany specify extra-firm grades for grilling applications where structural integrity prevents menu failures.
- Tempeh:Whole soybean fermentation with Rhizopus oligosporus binds proteins into dense cakes with natural umami depth. Indonesian production clusters supply European import demand as flexitarian consumers seek minimally processed protein with intact fiber matrices.
- Seitan:Vital wheat gluten extraction disqualifies this segment from true gluten-free classification; certified variants use rice protein isolates to mimic traditional texture.
- Jackfruit:Young fruit flesh shreds into fibrous strands that replicate pulled pork mouthfeel without protein density; South Asian supply chains dominate raw material sourcing.
Today's leader: Tofu. Tomorrow's challenger: Tempeh.
Source:
Cost tier stratification separates commodity protein isolates from precision-fermented and tree-nut alternatives that absorb disproportionate quality assurance overhead.
- Pea Protein:Wet-fraction yellow pea concentrates achieve 80-85% protein purity with favorable amino acid spreads. Canadian Prairie harvest volatility and Chinese processing capacity expansion are compressing margin structures for European formulators.
- Soy Protein:Defatted soy flour and isolate remain the cost baseline, though GMO labeling requirements in the European Union and allergen declaration mandates under EU Regulation 1169/2011 constrain foodservice adoption.
- Mushroom:Mycelial fermentation in controlled bioreactors yields complete proteins with beta-glucan functional benefits; UK and Dutch facilities anchor limited global supply.
- Almond:California Central Valley water stress and pollinator dependence inflate input costs, restricting this segment to premium-positioned retail SKUs with minimal foodservice penetration.
Pea protein commands current volume leadership. Mushroom fermentation represents the steepest expansion trajectory as capacity constraints ease.
Application:
Customer type divergence separates institutional procurement with centralized certification requirements from fragmented household purchasing where label literacy varies sharply.
- Ready-to-Cook:Marinated and seasoned formats requiring heat activation dominate refrigerated retail cases; German and US consumers prioritize convenience without sacrificing meal customization control.
- Ready-to-Eat:Shelf-stable or chilled pre-cooked products command shelf space in convenience channels and corporate foodservice; shorter production runs and accelerated testing protocols compress batch economics.
- Restaurant:National chain technical specifications mandate gluten-free validation at ingredient and finished-product stages, disqualifying smaller suppliers lacking dedicated extrusion lines.
- Home Cooking:Unflavored bulk formats and recipe-ready components serve committed flexitarians with established preparation skills; direct-to-consumer subscription models concentrate retention in this segment.
Restaurant procurement consolidates fastest. Home cooking subscriptions build the deepest loyalty data assets.
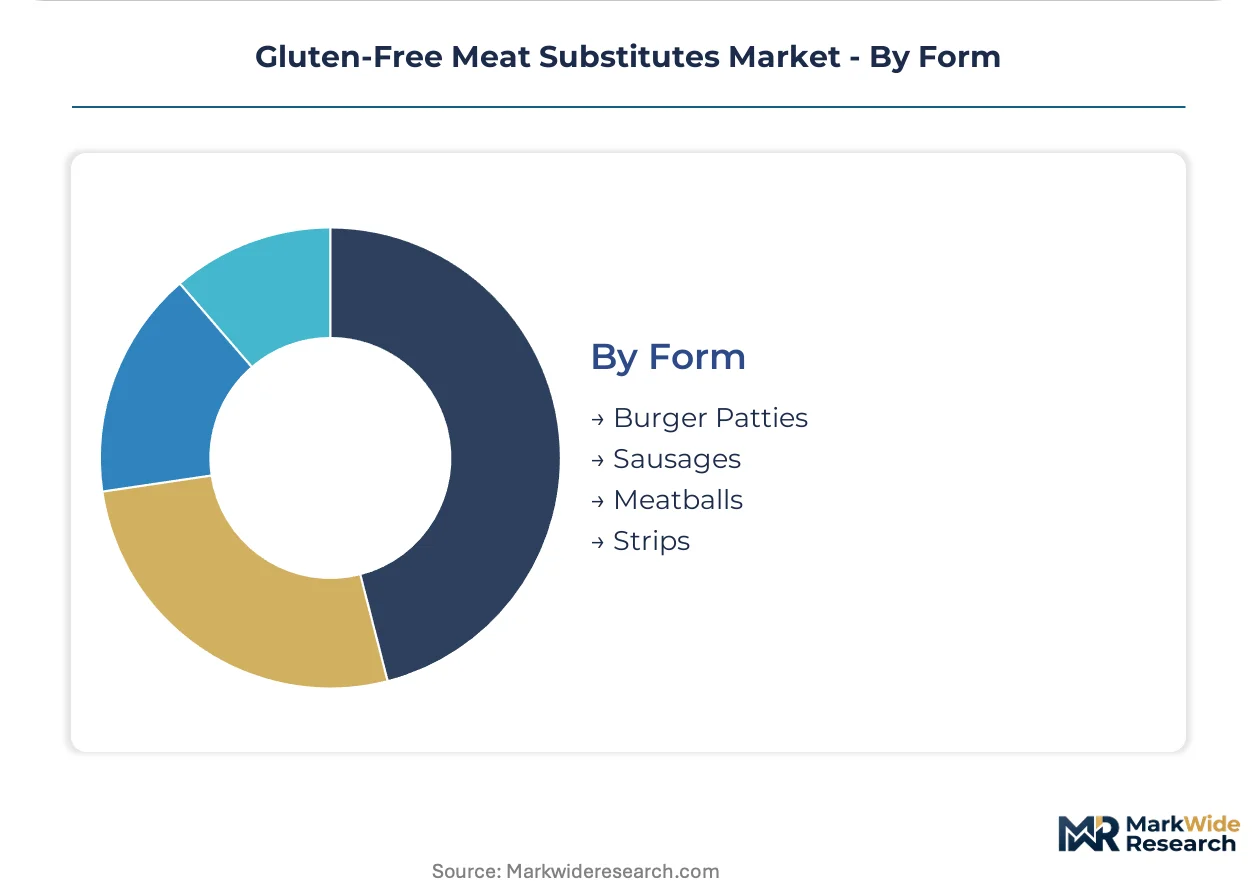
Form:
Supply concentration in high-moisture extrusion equipment favors burger and sausage formats while strip and meatball production requires secondary forming investments that strain mid-scale processors.
- Burger Patties:Standardized disc geometry enables automated portioning and uniform cook-time predictability; fast-casual chains in the United States specify quarter-pound equivalents with defined moisture retention thresholds.
- Sausages:Casing alternatives from alginate and cellulose replicate snap and bite resistance; German sausage culture drives premium positioning for Bratwurst and Weisswurst analogues with regional spice profiles.
- Meatballs:Spherical forming demands specialized depositing equipment; Italian and Swedish recipe traditions sustain niche demand with limited scale economies.
- Strips:Fajita and stir-fry applications require directional fiber alignment that high-moisture extrusion achieves less consistently than burger formats.
Burger patties anchor current revenue. Sausages are gaining share fastest as European formulators perfect casing technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's flexitarian population and strict food safety protocols create premium positioning for certified gluten-free meat alternatives, while the United States leverages direct-to-consumer subscription models to sustain repeat purchase rates in the category.
United States
FDA gluten-free labeling rules and FSMA preventive controls mandate strict allergen disclosure and cross-contact documentation, compelling manufacturers to validate supply chain segregation. Restaurant chains and foodservice operators expand gluten-free menu offerings through centralized category management. California and Illinois processing clusters concentrate high-moisture extrusion capacity for burger patty production.
Germany
EU Regulation 1169/2011 on allergen disclosure tightens product standards for celiac disease patients and wheat allergy sufferers seeking safe protein alternatives. Bavaria and North Rhine-Westphalia host dedicated gluten-free processing lines that compress production economics while meeting clinical demand. Regional Bratwurst and Weisswurst analogues command premium positioning through certified clean-label formulations.
United Kingdom
Quorn Foods anchors mycoprotein fermentation capacity that naturally excludes gluten from production processes, serving flexitarian consumers with beta-glucan functional benefits. The Netherlands and UK facilities face supply concentration risk as limited global fermentation infrastructure strains expansion timelines. Greater London foodservice procurement consolidates through direct manufacturer agreements with national restaurant chains.
Canada
Health Canada imposes additional documentation burdens on imported yellow pea and faba bean protein isolates from Prairie harvest regions. Input cost volatility fluctuates with Canadian and Australian agricultural cycles, compressing margin structures for European formulators. Ontario and Quebec refrigerated distribution networks support subscription-based replenishment models for home cooking segments.
Brazil
ANVISA's evolving allergen framework creates first-mover positioning for certified gluten-free meat analogues in Latin America's largest consumer market. São Paulo and Rio de Janeiro metropolitan areas concentrate foodservice demand as national chains mandate supplier certification at corporate levels. Local processors face disproportionate compliance burdens relative to integrated multinationals with established segregation infrastructure.
Gluten-Free Meat Substitutes Market Competitive Landscape
Top-tier vendors anchor the premium certified-gluten-free tier, while mid-scale regional processors compete on price-sensitive conventional alternatives. The vendor base stratifies across fermentation-based specialists, high-moisture extrusion operators, and direct-to-consumer subscription platforms. Three archetypes dominate: mycoprotein fermentation leaders, pea protein isolate formulators, and refrigerated cold-chain direct marketers. Competitive moves concentrate on dedicated extrusion line capacity expansion and strategic foodservice partnerships with national restaurant chains.
Within the fermentation-specialist tier, Quorn Foods occupies a position exemplifying mycoprotein technology that inherently excludes gluten from production processes. Among US-based innovators, Beyond Meat Inc. and Impossible Foods Inc. represent contrasting channel strategies—direct-to-consumer subscription models versus foodservice partnership anchoring. These three entities collectively illustrate the geographic and technological diversification patterns shaping competitive positioning across North American and European markets.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Impossible Foods Inc. |
| Conagra Brands, Inc. |
| Quorn Foods |
| Tofurky |
| Field Roast |
| Lightlife Foods |
| Maple Leaf Foods Inc. |
| Gardein |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance gates both qualified supply and premium-tier pricing access, as refrigeration-dependent processors must invest in low-GWP cold chain infrastructure to serve certified gluten-free segments. Manufacturers absorbing these capital costs extract pricing premiums from restaurant chains and subscription platforms that demand validated allergen segregation.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for high-moisture extrusion output. Three-tier pricing structure across certified premium, standard clean-label, and economy conventional levels segments buyer tiers. Certification investment under FDA and EU frameworks commands margin premiums from clinical celiac segments. Cost compression in economy tiers intensifies because Chinese pea protein isolate capacity expansion feeds commoditized burger patty supply. Foodservice procurement teams at national chains exhibit lowest price sensitivity; independent retailers and bulk home-cooking buyers drive hardest bargain negotiations.
Supply Chain Analysis
Regional distribution centers in Chicago, Rotterdam, and São Paulo anchor hub-and-spoke patterns for temperature-controlled finished goods. Raw material supply concentrates in Canada for yellow pea protein, the Netherlands for mycoprotein fermentation feedstock, and India for jackfruit raw material. Manufacturing draws from dedicated extrusion lines in Bavaria, California, and Ontario that enforce gluten segregation protocols. Single-source vulnerability clusters in mycoprotein bioreactor capacity concentrated near Quorn Foods' UK and Dutch facilities. Distribution runs through direct manufacturer agreements with national restaurant chains, bypassing traditional foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gluten-free meat substitutes function as a geographic-arbitrage play where EU allergen disclosure mandates under Regulation 1169/2011 impose compliance costs that US-based exporters can undercut through FDA-aligned certification pathways.
For Market Incumbents: Cement category ownership by acquiring dedicated extrusion capacity in Germany and California before mid-scale competitors secure equipment slots. Lock in multi-year pea protein offtake agreements with Canadian Prairie processors to defend margin position against input cost volatility from harvest cycle fluctuations. Counter mycoprotein fermentation entrants by accelerating high-moisture extrusion R&D investments.
For New Entrants and Emerging Players: Begin with Brazil's ANVISA-regulated foodservice corridor where national chains lack validated gluten-free suppliers and certification timelines favor first-movers. Target São Paulo metropolitan procurement offices with direct sales teams before integrated multinationals establish local segregation infrastructure. Leverage subscription cold-chain delivery to bypass retail slotting fees and build loyalty data assets in home cooking segments.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale extrusion operators because fragmented regional processors lack capital to fund dedicated gluten-free line conversions. Target facilities in Spain and Poland facing disproportionate EU F-Gas and FSMA compliance burdens relative to integrated competitors. Watch for inflection when ANVISA finalizes allergen framework deadlines that trigger Brazilian foodservice procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Gluten-Free Line Conversion | Segregated extrusion capacity unlocks restaurant chain procurement mandates under FDA and EU frameworks. |
| Direct-to-Consumer Cold Chain Launch | Subscription models bypass retail slotting fees and capture repeat purchase data from flexitarian households. |
| Pea Protein Supply Agreement | Long-term Canadian offtake contracts hedge against Prairie harvest volatility compressing European formulator margins. |
| Mycoprotein Fermentation Scale-Up | UK and Dutch bioreactor expansion addresses supply concentration risk as flexitarian demand accelerates. |
| Brazil Foodservice Partnership | ANVISA-aligned certification creates first-mover positioning before national chains finalize supplier panels. |
Research Methodology
Coverage spans North America, Europe, Latin America, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with R&D directors at fermentation-based processors, procurement leads at national restaurant chains, quality assurance heads overseeing gluten segregation protocols, and category buyers at refrigerated retail distributors informed demand-side assumptions. Secondary sources include FDA gluten-free labeling guidance documents, EU Regulation 1169/2011 implementation reports, EFSA allergen risk assessments, customs trade data on pea protein isolates, and foodservice distribution channel databases. Bottom-up volume builds triangulated against top-down market sizing across protein source and application segments.
Granularity extends to protein source tier, product form geometry, and channel archetype within each modeled geography. Value outputs across the projection horizon reflect price premiums for certified versus conventional alternatives, with CAGRs derived from segment-level growth trajectories. Forecast inputs incorporate high-moisture extrusion capacity expansion timelines, mycoprotein fermentation batch economics, and cold-chain logistics cost structures specific to refrigerated meat alternatives.
Caveats apply where ANVISA regulatory finalization, Codex Alimentarius revisions, or Canadian Prairie harvest disruptions could materially shift the outlook. Forecasts reflect assumptions on certification adoption rates and foodservice procurement consolidation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Products from Food Waste Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
South America Fat Replacers Market