
 Meal Replacement Bars Market | 2026-2036
Meal Replacement Bars Market Size, Share, and Industry Trends Forecast 2026-2036
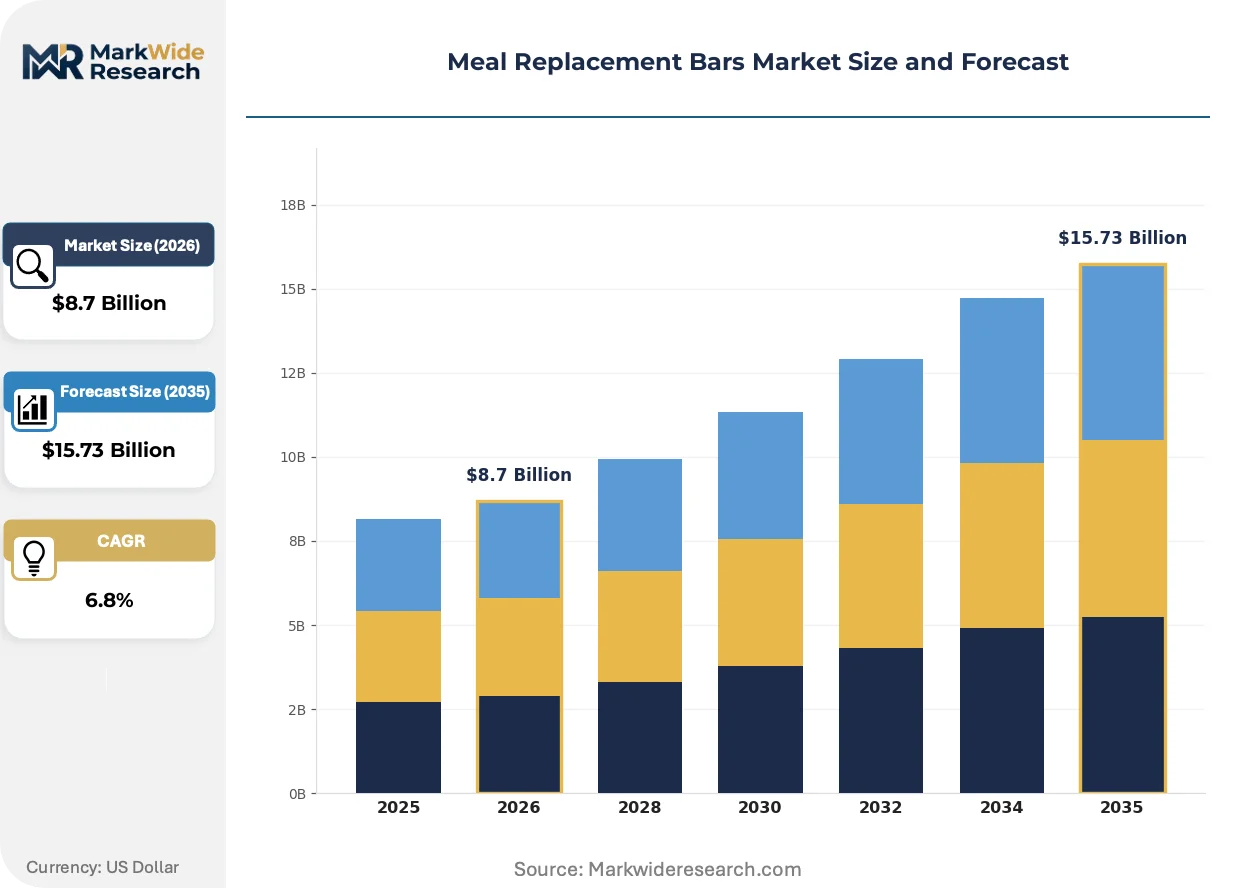
Meal Replacement Bars Market Foresight
Fitness-oriented consumers is collapsing as the dominant buyer archetype, while time-pressed professionals and weight-management patients capture incremental share. Abbott Nutrition leverages clinical credibility to anchor hospital discharge and diabetes counseling channels. Simply Good Foods sustains retail velocity through Atkins-branded low-carbohydrate positioning in mass grocery. Glanbia competes via sports nutrition heritage and whey protein ingredient integration that supports private-label manufacturing scale.
Meal replacement bars are shelf-stable, nutrient-dense food products formulated to deliver complete macronutrient profiles within calorie-controlled portions, typically manufactured through cold extrusion or enrobing processes that preserve protein integrity and shelf stability. Their primary commercial purpose is substituting conventional meals for consumers pursuing weight management, athletic performance, or convenience-driven nutrition. Protein bars lead product type revenue pools due to premium pricing tolerance among gym-affiliated consumers, while plant-based ingredient source formats represent the fastest-growing structural segment as allergen sensitivity and sustainability preferences reshape procurement. Low-sugar bars command disproportionate margin contribution as reformulation costs create defensible price premiums against conventional snack alternatives.
FDA nutrition labeling requirements and FTC advertising substantiation rules govern protein content claims and weight-loss marketing in the United States, compelling manufacturers to invest in analytical verification and legal review. USDA organic certification and Non-GMO Project verification create parallel compliance pathways that influence ingredient sourcing decisions and retail access negotiations. Stakeholders must monitor evolving FDA guidance on added-sugar disclosure and state-level sugar tax proposals that could force rapid reformulation cycles or channel-specific product line segmentation.
Market Dynamics
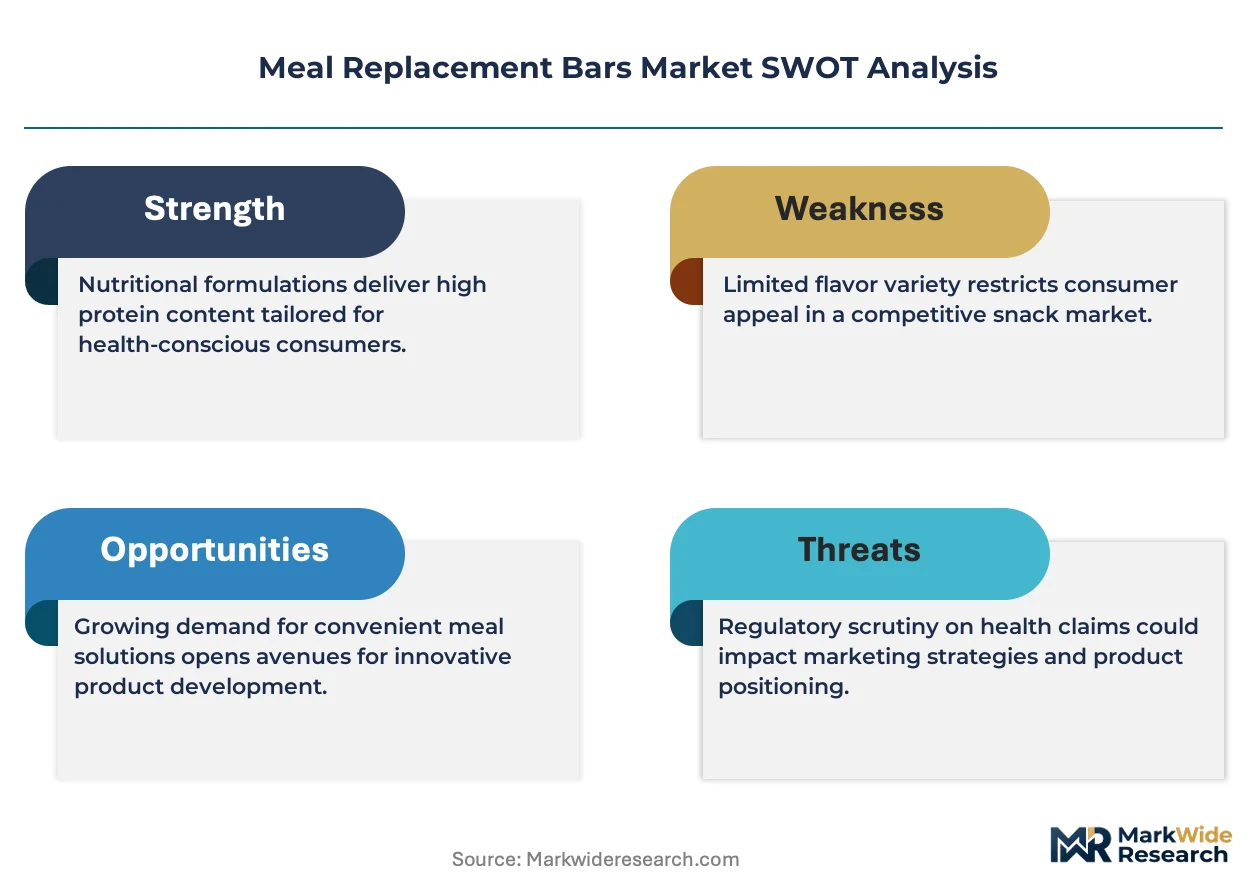
Meal replacement bars face intensifying pressure from dual forces: FDA scrutiny of protein content claims forcing costly analytical verification, and shifting demand from gym enthusiasts toward time-pressed professionals seeking shelf-stable lunch substitutes. Cold extrusion equipment investments now concentrate among manufacturers serving hospital discharge and corporate wellness channels.
Growth Catalysts
- FDA Protein Claim Substantiation:Manufacturers investing in third-party amino acid profiling gain retail shelf access denied to competitors using unverified nitrogen-based calculations. This regulatory compliance creates defensible positioning in mass grocery.
- Hospital Discharge Protocols:Clinical nutrition departments in US healthcare systems now prescribe portion-controlled bars for post-surgical patients managing caloric intake. Abbott Nutrition anchors this channel through diabetes counseling partnerships.
- Whey Protein Cold Extrusion:Low-temperature processing preserves bioactive peptide structures, enabling premium pricing tolerance among performance-oriented consumers. German equipment suppliers dominate this technology segment.
Market Restraints
- Soy and Dairy Input Volatility:Commodity price swings for whey protein isolate and soy protein concentrate compress margin predictability for mid-tier manufacturers lacking long-term supply contracts.
- Enrobing Equipment Concentration:Chocolate coating machinery supply concentrates among Italian and Swiss original equipment manufacturers, creating capex bottlenecks for new entrants seeking shelf-stable bar formats.
- Sugar Alcohol Digestive Tolerance:Erythritol and maltitol formulations trigger gastrointestinal complaints among 15-30% of consumers, limiting repeat purchase rates for low-sugar positioned products.
Strategic Opportunities
- USDA Organic Certification Pathway:Premium shelf placement in Whole Foods and Sprouts Farmers Market rewards Non-GMO Project verified and organic certified bars with 20-40% price premiums over conventional alternatives.
- Direct-to-Employer Corporate Wellness:Fortune 500 procurement departments seek vending-compatible nutrition solutions for hybrid office workers, bypassing traditional retail slotting fee structures.
- Fermented Plant Protein Blends:Pea-rice protein combinations processed through enzymatic hydrolysis improve amino acid completeness and reduce chalky texture defects that plague earlier generation vegan bars.
Industry Challenges
- Dual-Label SKU Proliferation:State-level added-sugar disclosure variations and municipal sugar tax proposals force manufacturers to maintain parallel product lines, complicating inventory forecasting.
- Shelf-Life Accelerated Testing:Protein bar texture degradation (staling, lipid oxidation) requires 6-12 month real-time stability studies, compressing new product development cycles against fast-follower competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meal Replacement Bars Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Snack Bars, Meal Bars, Low-Sugar Bars Ingredient Source: Whey Protein, Plant-Based, Nut-Based, Soy Protein Packaging Type: Individual Packets, Bulk Boxes, Multi-Packs, Resealable Bags Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Gyms |
| Companies Covered | Herbalife, Simply Good Foods, Abbott Nutrition, GlaxoSmithKline, Glanbia, Nestle, General Mills, Orgain, Kellogg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meal Replacement Bars Market Shifts & Advancements
Protein bar formulation is fragmenting along three axes: processing technology enabling novel texture profiles, regulatory disclosure requirements reshaping ingredient selection, and procurement channel migration toward institutional buyers. Each axis demands distinct R&D and commercial capabilities.
Precision fermentation-derived dairy proteins are decomposing the traditional whey supply chain. Perfect Day and Remilk supply animal-free beta-lactoglobulin to CPG manufacturers seeking to decouple from volatile dairy commodity markets. Early adopters in premium vegan positioning capture price premiums while bypassing lactose intolerance limitations of conventional whey.
REACH chemical registration requirements in Europe now govern flavor compound and coating additive approvals for bars exported from US manufacturing facilities. ECHA substance evaluation dossiers for novel sweeteners create 18-24 month lag times between US launch and EU market entry. Manufacturers serving both markets now front-load toxicology studies, compressing formulation flexibility.
Corporate procurement departments now specify macronutrient profiles and allergen-free certifications in RFP processes for campus vending and meeting catering. Sodexo and Compass Group centralize nutrition standards across North American facilities, displacing decentralized convenience store purchasing. This concentration is most visible in technology sector headquarters clusters in Austin and Seattle.
Meal Replacement Bars Market Segmentation
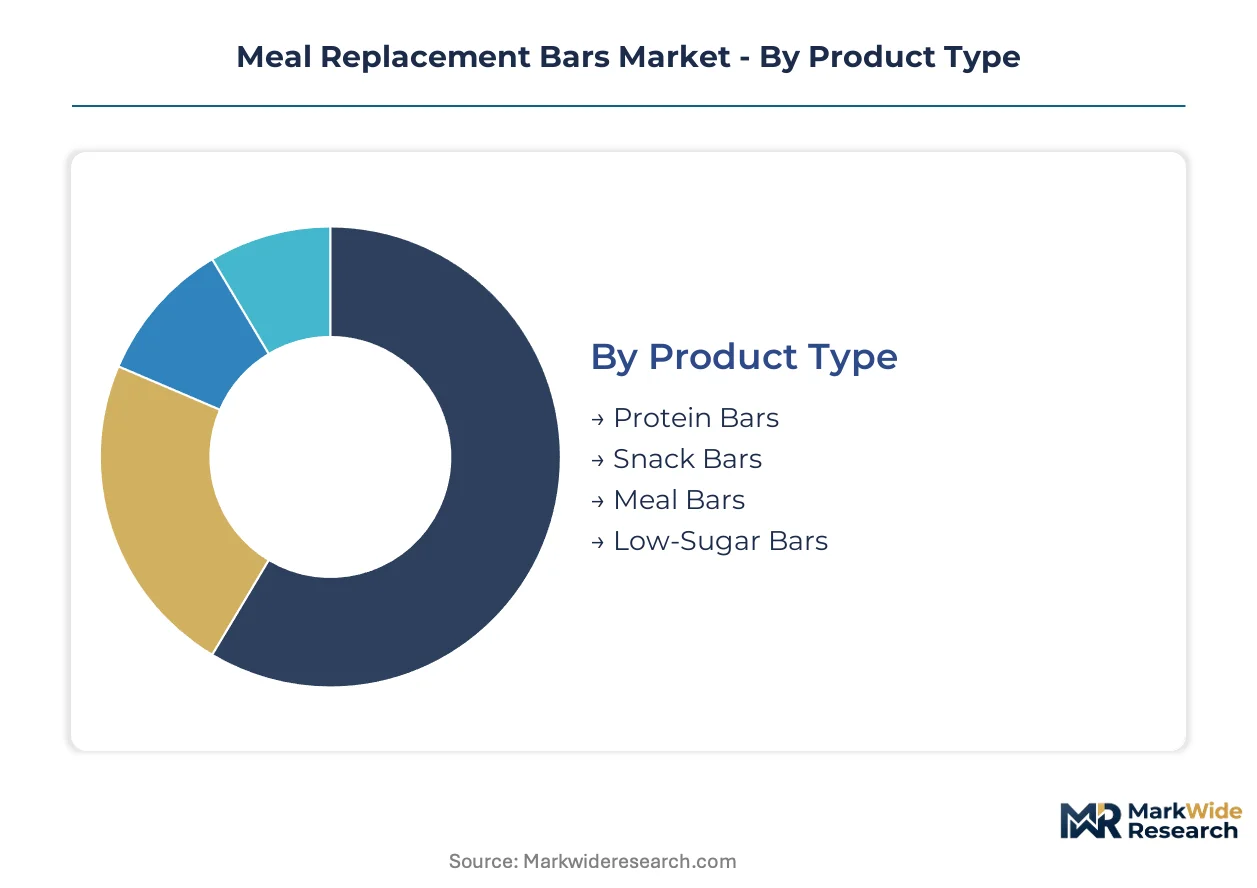
Segmentation in meal replacement bars determines formulation architecture, compliance pathways, and channel economics. FDA protein claim substantiation rules and FTC advertising standards create divergent technical requirements across product types, while ingredient sourcing decisions lock in margin structures and geographic market access.
Product Type:
FDA labeling requirements for protein content claims and net carbohydrate declarations force distinct analytical verification investments across formats, with gym-affiliated and clinical channels demanding different specification tiers.
- Protein Bars:Cold-extruded formulations delivering 20-30g protein per serving through whey isolate or concentrate matrices. Demand concentrates in US gym chains and German functional food retail where premium pricing tolerance supports analytical verification costs for FDA-compliant label claims.
- Meal Bars:Complete macronutrient profiles engineered for caloric equivalence to conventional meals, typically 300-400 kcal per unit. Hospital discharge protocols in US healthcare systems and corporate wellness programs in Austin and Seattle technology campuses anchor volume for this format.
- Snack Bars:Lower protein content positioned between meals rather than substituting them.
- Low-Sugar Bars:Erythritol and maltitol formulations targeting glycemic management, constrained by digestive tolerance limitations affecting 15-30% of consumers.
Protein Bars handle the majority of throughput; Meal Bars is the fastest mover on share.
Ingredient Source:
Cost tier differentiation separates commodity dairy inputs from premium-positioned alternatives, with precision fermentation and organic certification commanding 20-40% price premiums in Whole Foods and Sprouts Farmers Market.
- Whey Protein:Bioactive peptide structures preserved through low-temperature processing enable performance-oriented positioning. German equipment suppliers dominate cold extrusion technology for this segment, with supply contracts insulating major manufacturers from commodity volatility.
- Plant-Based:Pea-rice protein combinations processed through enzymatic hydrolysis improve amino acid completeness and reduce chalky texture defects. Allergen sensitivity and sustainability preferences in US coastal metropolitan markets drive steepest expansion trajectory for this format.
- Soy Protein:Concentrate and isolate formats facing input price volatility and declining consumer preference in premium channels.
- Nut-Based:Almond and cashew protein matrices targeting paleo-positioned consumers with limited manufacturing scale.
Whey Protein retains volume leadership; Plant-Based climbs the fastest on share.
Packaging Type:
Application context dictates format selection, with institutional procurement specifying vending-compatible units while direct-to-consumer channels favor subscription-optimized configurations.
- Individual Packets:Single-unit flow-wrap formats optimized for convenience store and gym vending applications. Fortune 500 procurement departments in North American technology headquarters clusters specify this format for hybrid office worker distribution.
- Bulk Boxes:Case-quantity packaging for hospital discharge and diabetes counseling channels where Abbott Nutrition anchors clinical protocol integration.
- Multi-Packs:Club store and subscription commerce configurations.
- Resealable Bags:Flexible formats for pantry stocking with limited penetration in on-the-go consumption occasions.
Individual Packets handles the majority of throughput; Bulk Boxes is expanding most quickly in institutional channels.
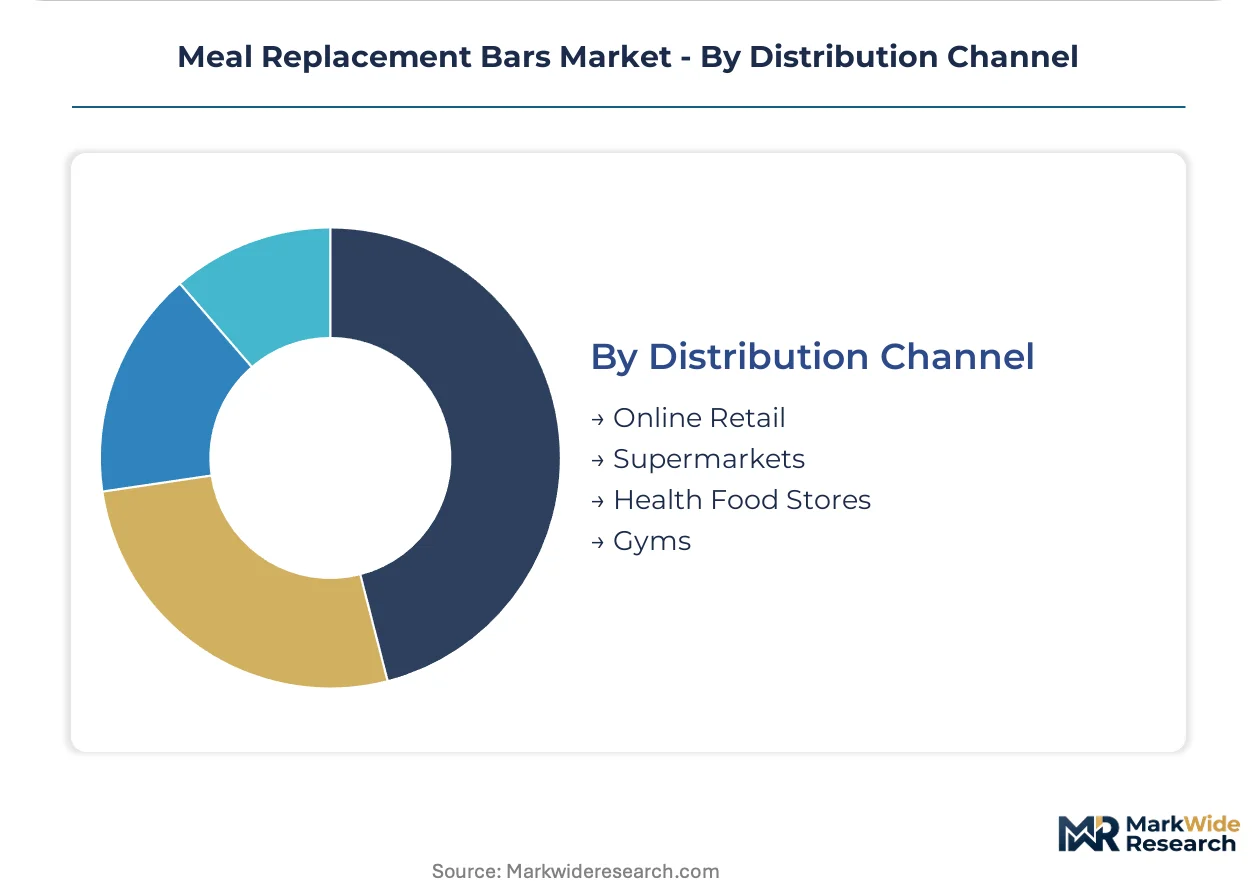
Distribution Channel:
Customer type concentration is shifting from fitness enthusiasts toward time-pressed professionals, with channel economics favoring direct employer relationships over traditional retail slotting fee structures.
- Supermarkets:Mass grocery placement requiring FDA-compliant protein claim substantiation and competitive slotting fee structures. Simply Good Foods sustains velocity here through Atkins-branded low-carbohydrate positioning.
- Online Retail:Direct-to-consumer and subscription platforms enabling precision targeting of weight-management patients and allergen-sensitive consumers. Non-GMO Project verification and USDA organic certification create discoverability advantages in search-filtered environments.
- Health Food Stores:Premium shelf placement rewarding certification compliance with price tolerance in Whole Foods and Sprouts Farmers Market networks.
- Gyms:Declining relative share as fitness-oriented consumers collapse as the dominant buyer archetype, though remaining significant for whey protein performance positioning.
Supermarkets handles the majority of throughput; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's cold-chain infrastructure underwrites Germany's dominance in functional food distribution, connecting whey protein suppliers from Bavarian dairy cooperatives to retail networks across the European continent.
United States
FDA protein claim substantiation rules and hospital discharge protocols drive formulation investments. The FTC monitors weight-loss marketing claims with strict advertising substantiation requirements. Austin and Seattle technology campuses anchor corporate wellness procurement for meal bar distribution to hybrid office workers.
Germany
Functional food retail density supports premium positioning for whey-based and plant-based formats. ECHA REACH requirements govern flavor compound approvals for imported bars. Bavarian equipment suppliers dominate cold extrusion technology serving performance-oriented consumers across Central Europe.
China
SAMR nutrition labeling standards and protein content verification reshape import compliance for foreign manufacturers. GB food safety standards enforce additive restrictions that differ from FDA frameworks. Yangtze River Delta metropolitan clusters concentrate demand for convenience-driven nutrition among white-collar professionals.
United Kingdom
HFSS regulations restrict placement of high-fat-sugar-salt products in prominent retail locations. The FSA oversees novel food approvals for precision fermentation-derived proteins. London's corporate headquarters drive vending-compatible nutrition procurement for financial and professional services sectors.
Japan
METI functional food claims system enables specific health benefit labeling for clinically validated formulations. PMDA oversight ensures pharmaceutical-grade manufacturing standards for medical nutrition bars. Kanto region convenience store networks distribute portion-controlled products to time-pressed urban commuters.
Meal Replacement Bars Market Competitive Landscape
Concentration sits with diversified nutrition conglomerates and specialized sports nutrition suppliers. The vendor base spans three tiers: clinical nutrition specialists leveraging hospital channel relationships, mass-market CPG players with grocery retail scale, and emerging plant-based innovators capturing allergen-sensitive segments. Competitive moves center on cold extrusion equipment acquisition for texture differentiation and precision fermentation partnerships to secure animal-free protein supply.
Within the clinical nutrition tier, Abbott Nutrition anchors hospital discharge and diabetes counseling protocols through established healthcare system relationships. Simply Good Foods occupies the mass-market low-carbohydrate positioning through Atkins-branded retail velocity. Glanbia exemplifies sports nutrition heritage integration, supplying whey protein ingredients while supporting private-label manufacturing scale for third-party brands.
| Leading Market Players |
|---|
| Herbalife |
| Simply Good Foods |
| Abbott Nutrition |
| GlaxoSmithKline |
| Glanbia |
| Nestle |
| General Mills |
| Orgain |
| Kellogg |
| Others |
Supply & Pricing Matrix
Cold extrusion equipment utilization rates at German and Italian manufacturers determine minimum viable production runs and establish price floors that mid-tier competitors cannot match without volume commitments. This scale concentration rewards manufacturers serving hospital discharge and corporate wellness channels with procurement scale, while forcing smaller players toward premium-positioned plant-based formats where certification premiums offset throughput disadvantages.
Pricing Analysis
Volume-discount tiering structures stratify across premium clinical-grade, standard mass-grocery, and economy private-label levels. FDA-compliant protein claim substantiation and USDA organic certification command 20-40% premiums in Whole Foods and Sprouts Farmers Market networks. Pricing pressure stems from soy and dairy input volatility compressing margin predictability for manufacturers lacking long-term supply contracts. Corporate wellness procurement departments exhibit lowest price sensitivity due to health outcome specifications, while convenience store channels face highest sensitivity from snack alternative competition.
Supply Chain Analysis
Just-in-time inventory strategies dominate among manufacturers serving retail grocery, while strategic stockpiling of whey protein isolate and erythritol concentrates occurs among suppliers with hospital discharge contracts requiring 6-12 month stability guarantees. Manufacturing capacity concentrates in Germany, Italy, and the United States, with Bavarian equipment suppliers dominating cold extrusion technology. Raw material dependencies center on whey protein isolate, pea-rice protein blends, and chocolate enrobing compounds. Single-source vulnerability concentrates in Italian and Swiss enrobing machinery OEMs. Distribution runs through mass grocery retail, direct-to-employer corporate wellness programs, and hospital discharge channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of cold extrusion technical expertise and FDA analytical verification capabilities limits competitive entry, rewarding early equipment adopters and clinical channel integrators with durable positioning.
For Market Incumbents: Secure long-term supply contracts for whey protein isolate and soy protein concentrate to buffer commodity volatility threatening margin structures. Defend against precision fermentation protein disruptors by anchoring hospital discharge protocols through diabetes counseling partnerships that embed products in clinical workflows. For New Entrants and Emerging Players: Lead with fermented plant protein blends targeting allergen-sensitive consumers in US coastal metropolitan markets where sustainability preferences override price sensitivity. Corporate wellness direct-to-employer channels offer the most penetrable white space, bypassing traditional retail slotting fee structures through RFP participation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with installed cold extrusion capacity and clinical nutrition regulatory expertise over pure-brand entrants lacking manufacturing assets. Long-term viability hinges on precision fermentation protein supply partnerships that decouple from dairy commodity cycles. Watch FDA guidance evolution on added-sugar disclosure as the inflection signal requiring portfolio reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Animal-free beta-lactoglobulin supply from Perfect Day and Remilk bypasses lactose intolerance limitations and dairy price volatility. |
| Cold Extrusion Capacity Expansion | German equipment acquisition enables bioactive peptide preservation that supports premium positioning in performance-oriented channels. |
| USDA Organic Certification Pathway | Non-GMO Project verification unlocks 20-40% price premiums in Whole Foods and Sprouts Farmers Market networks. |
| Direct-to-Employer Corporate Wellness | Fortune 500 procurement bypasses retail slotting fees while securing volume commitments from hybrid office worker programs. |
| Hospital Discharge Protocol Integration | Abbott Nutrition anchors diabetes counseling channel relationships that embed portion-controlled bars in post-surgical patient management. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA labeling guidance documents, FTC advertising substantiation rulings, and clinical nutrition protocol databases. Interviews with cold extrusion equipment manufacturers, hospital procurement managers, corporate wellness program directors, and retail category buyers at mass grocery chains informed supply-side and demand-side validation. Secondary sources include USDA organic certification records, Non-GMO Project verification databases, ECHA REACH substance evaluation dossiers, and trade customs data for whey protein isolate imports. Bottom-up product-level volume estimates triangulate against top-down category expenditure analysis.
Segmentation dimensions modeled span product type, ingredient source, packaging configuration, and distribution channel across the analysis window. Protein bar, meal bar, snack bar, and low-sugar formats segment by caloric density and clinical application. Whey, plant-based, soy, and nut-based ingredient sources segment by cost tier and allergen profile. Individual packet, bulk box, multi-pack, and resealable bag formats segment by consumption occasion. Supermarket, online retail, health food store, and gym channels segment by buyer archetype concentration. CAGRs derive from regression analysis of historical volume against protein claim substantiation investment cycles and corporate wellness procurement expansion.
Forecasts assume regulatory continuity in FDA labeling requirements, FTC advertising standards, and ECHA REACH flavor compound approvals; material policy shifts would require re-modeling. Specific risks include state-level added-sugar disclosure variations forcing dual-label SKU proliferation, municipal sugar tax proposals accelerating reformulation cycles, and SAMR nutrition labeling standard changes affecting China export compliance. Revision becomes warranted when precision fermentation protein cost parity with conventional whey crosses commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Algae Fats Market