
 Asia-Pacific Meat Substitutes Market | 2026-2036
Asia-Pacific Meat Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Meat Substitutes Market Outlook
Pea protein isolate is restructuring cost structures across the Asia-Pacific Meat Substitutes Market as manufacturers shift from soy-dominant formulations. Beyond Meat leverages its extrusion technology leadership to command premium shelf placement in Australian supermarkets. OmniFoods anchors its position through deep distribution networks across Hong Kong and Singapore retail channels. GoodDot specializes in heat-stable mycoprotein formats tailored to Indian street-food applications.
Meat substitutes comprise formulated protein products designed to replicate the sensory properties of conventional meat through extrusion, fermentation, or high-moisture processing, typically achieving 15-25 grams of protein per 100-gram serving with controlled fat and fiber profiles. Their primary commercial purpose is to serve as direct replacements in dishes ranging from stir-fries to processed foods. Tofu and tempeh retain the largest volume share across the region due to centuries of culinary integration and low production costs. Pea protein represents the fastest-expanding source category as allergen concerns and non-GMO positioning attract health-focused buyers. Online retail channels capture disproportionate growth in South Korea and Japan where subscription models build recurring revenue pools.
Japan's Consumer Affairs Agency enforces strict allergen labeling for novel protein ingredients, while Australia's FSANZ governs nutritional content claims for plant-based meat analogues. China's SAMR oversees food safety standards for fermented soy and mycoprotein products entering mass retail. India's FSSAI mandates vegan certification logos that influence consumer trust and brand compliance costs. Stakeholders must monitor evolving protein-labeling rules across multiple jurisdictions to avoid market access delays and reformulation expenses.
Market Dynamics
Pea protein isolate is restructuring cost structures across the Asia-Pacific Meat Substitutes Market as manufacturers shift from soy-dominant formulations. This ingredient pivot is compressing allergen-related reformulation expenses while opening shelf-space negotiations in premium retail channels.
Growth Catalysts
- FSSAI vegan certification:India's tightening labeling requirements for vegan products are tightening ingredient disclosure norms and building consumer trust pools.
- Extrusion technology advancement:High-moisture extrusion processes now replicate muscle fiber textures in plant-based analogues, enabling direct replacement in stir-fry and grilling applications.
- Tier-one city demand concentration:Health-conscious millennials in China's Beijing, Shanghai, and Shenzhen drive repeat purchases of pea-protein products through subscription and quick-commerce channels.
Market Restraints
- Pea protein supply concentration:Processing capacity for food-grade pea isolate concentrates in Canada and northern China, exposing formulators to cross-border logistics volatility.
- SAMR fermentation oversight:China's food safety standards for mycoprotein products require extended stability testing timelines, delaying mass retail entry by 12-18 months for novel entrants.
- Tofu-tempeh price floor:Centuries-old production infrastructure for traditional soy formats in Indonesia and Vietnam anchors consumer price expectations, compressing margins for premium analogues.
Strategic Opportunities
- South Korean subscription retail:Online retail channels capture disproportionate growth through recurring revenue pools built on personalized nutrition algorithms and direct-to-home cold-chain logistics.
- Heat-stable mycoprotein formats:Fermentation-derived proteins that withstand high-temperature street-food cooking methods address India's chaat and kebab segments where texture retention determines repeat purchase.
- Australian FSANZ nutritional claims pathway:The regulator's structured framework for protein content and health claims enables faster product iteration for export-ready manufacturers targeting Southeast Asian markets.
Industry Challenges
- Allergen labeling complexity:Japan's Consumer Affairs Agency enforces strict disclosure protocols for novel protein ingredients, requiring dedicated quality assurance functions and multi-language packaging runs.
- Extrusion equipment capex intensity:High-moisture processing lines demand seven-figure capital commitments, favoring contract manufacturing relationships over in-house production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Meat Substitutes Market |
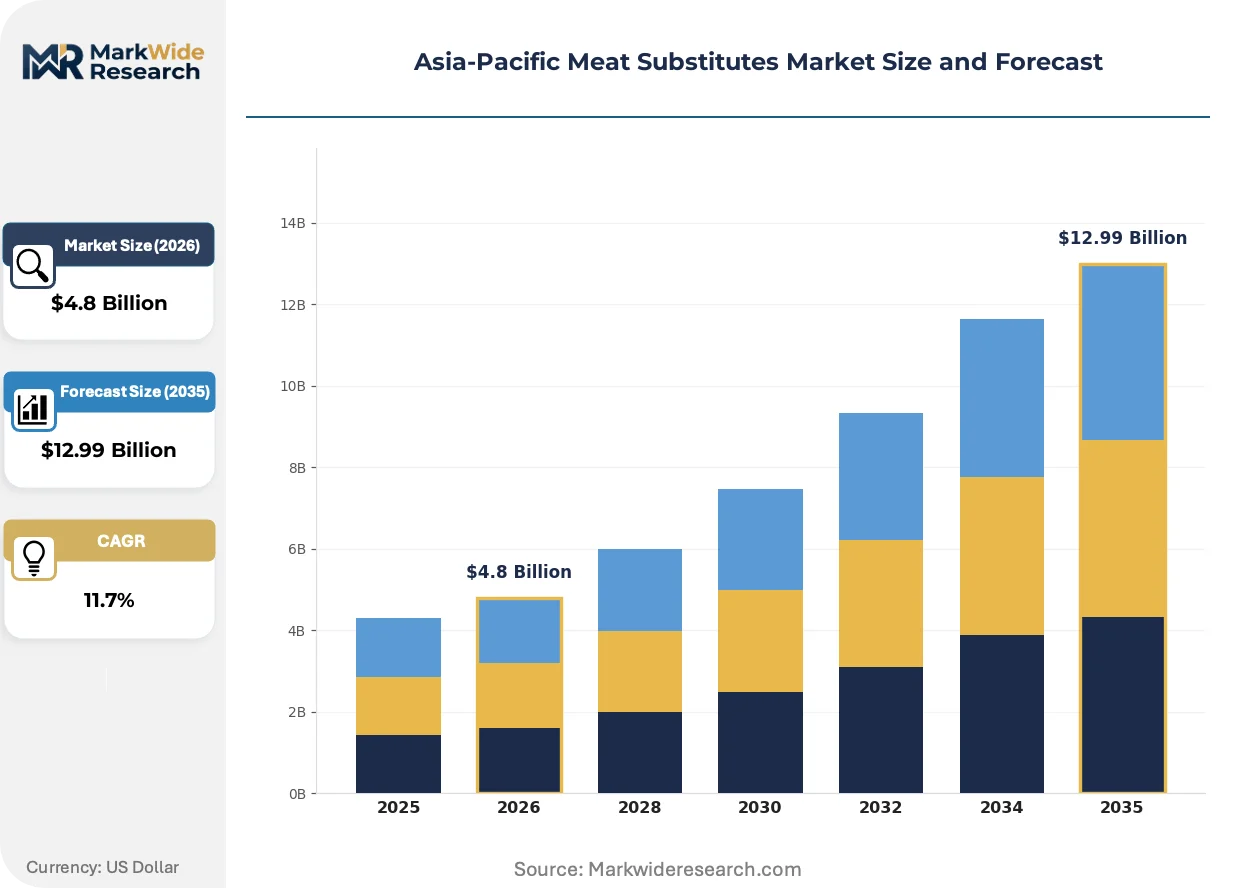
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Textured Vegetable Protein Source: Plant-Based, Mycoprotein, Legumes, Pea Protein Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores End User: Households, Restaurants, Food Service, Catering Services |
| Companies Covered | Impossible Foods Inc., Beyond Meat, Quorn, OmniFoods, GoodDot, China Foodstuff & Protein Group Co. Ltd, Kerry Group PLC, Morinaga Milk Industry Co., Flexitarian Foods Pty Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Meat Substitutes Market Strategic Shifts
Formulation science and regulatory clarity are converging to unlock new application spaces for plant-based proteins across the Asia-Pacific region. Three developments are compressing time-to-market while expanding addressable consumption occasions.
High-moisture extrusion technology is expanding into fresh-meat analogue categories previously dominated by refrigerated ground beef and pork. Quick-service restaurant chains in Thailand and the Philippines are piloting these formats in burger and meatball applications, compressing the texture gap between plant-based and conventional proteins. The technology is expanding into premium retail tiers where shelf placement and price positioning now rival conventional meat departments.
FSANZ governs nutritional content claims for plant-based meat analogues through a structured pre-approval pathway that separates permissible protein statements from prohibited health assertions. Australian manufacturers leveraging this clarity are securing export certifications for Southeast Asian markets where regulatory reciprocity accelerates registration timelines. Singapore's food agency references FSANZ determinations in its own novel food safety assessments, creating a harmonized compliance corridor.
Subscription models are capturing recurring revenue pools in South Korea and Japan where personalized nutrition platforms bundle plant-based protein deliveries with meal-planning algorithms. Quick-commerce channels displace traditional supermarket freezer sections for time-constrained urban households in Seoul and Tokyo. Health-conscious millennials in these markets demonstrate higher lifetime value through automated reorder cycles than intermittent retail purchasers.
Asia-Pacific Meat Substitutes Market Segmentation
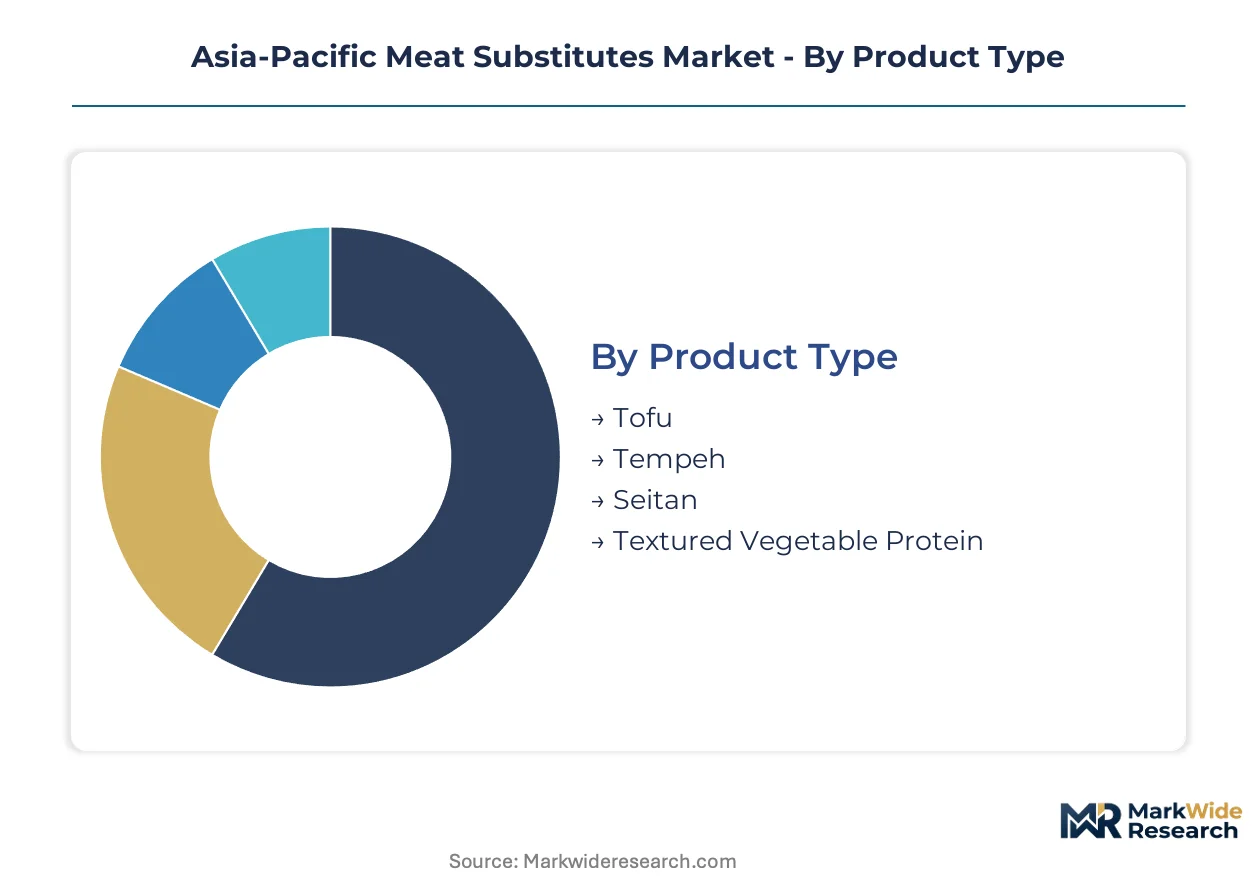
Segmentation in the Asia-Pacific Meat Substitutes Market reveals how protein sourcing decisions, channel economics, and end-use heat-stability requirements create distinct competitive battlegrounds. Manufacturers configure formulation and distribution strategies differently across each dimension.
Product Type:
Production infrastructure for traditional formats concentrates in Indonesia, Japan, and Vietnam where centuries-old processing methods anchor cost structures.
- Tofu:Coagulated soy curd with 8-15% protein content serves as the volume foundation across East and Southeast Asian retail. Household demand in Japan and South Korea sustains premium pricing for organic and silken variants despite commoditization pressures from Indonesian bulk supply.
- Tempeh:Fermented whole-soybean cake delivers higher fiber and firmer texture than tofu, commanding placement in Australian health-food retail and Indonesian quick-service chains. Fermentation capacity in Java and Sumatra supplies regional export demand while meeting domestic consumption that exceeds tofu per capita.
- Seitan:Wheat gluten isolate achieves 25% protein density with chewy mouthfeel suited to East Asian hotpot and Buddhist vegetarian cuisine. Production clusters in Taiwan and mainland China serve temple food and restaurant supply channels.
- Textured Vegetable Protein:Extruded defatted soy flour creates fibrous structures for industrial food manufacturing and institutional catering. Thai and Malaysian processing plants supply ASEAN food-service distributors with dehydrated granules and chunks.
Tofu absorbs the bulk of installed capacity; textured vegetable protein is expanding most quickly.
Source:
Ingredient sourcing strategies diverge based on allergen positioning, non-GMO certification requirements, and fermentation technology access.
- Plant-Based:Soy, wheat, and rice protein concentrates dominate mass-market formulations through established Asian supply chains. Chinese and Indian crushing capacity supports regional self-sufficiency in soy protein isolate.
- Mycoprotein:Fusarium venenatum fermentation yields complete protein with meat-like fiber structure. Singapore's novel food regulatory framework accelerates commercial deployment for food-service applications requiring high-heat stability.
- Legumes:Lentil, chickpea, and fava bean proteins address clean-label demand in Australian and New Zealand retail. Processing scale limitations in the region maintain premium pricing versus soy alternatives.
- Pea Protein:Yellow pea isolate achieves allergen-free positioning with neutral flavor profile suitable for dairy analogues and meat extenders. Import dependence on Canadian and northern Chinese processing capacity exposes formulators to logistics volatility.
Plant-based sourcing commands current volume; pea protein is climbing the fastest.
Distribution Channel:
Channel selection determines margin structure, cold-chain requirements, and consumer education investment levels.
- Supermarkets:Chilled and frozen sections in Coles, Woolworths, AEON, and Lotte Mart provide visibility for branded analogues. Slotting fees and promotional calendars favor established suppliers with multi-SKU portfolios.
- Online Retail:South Korean and Japanese subscription platforms bundle plant-based proteins with meal-planning algorithms. Cold-chain logistics investments by Coupang and Rakuten enable fresh-format delivery that bypasses traditional retail.
- Health Stores:Specialized retailers in Australia and urban India curate organic, non-GMO, and allergen-free assortments. Staff consultation drives trial for premium-priced emerging formats.
- Convenience Stores:7-Eleven and Lawson in Japan and Thailand stock ready-to-eat plant-based bento and onigiri. Limited shelf life and space constraints favor long-shelf-stable traditional formats over refrigerated analogues.
Supermarkets absorb the bulk of installed capacity; online retail is gaining share fastest.
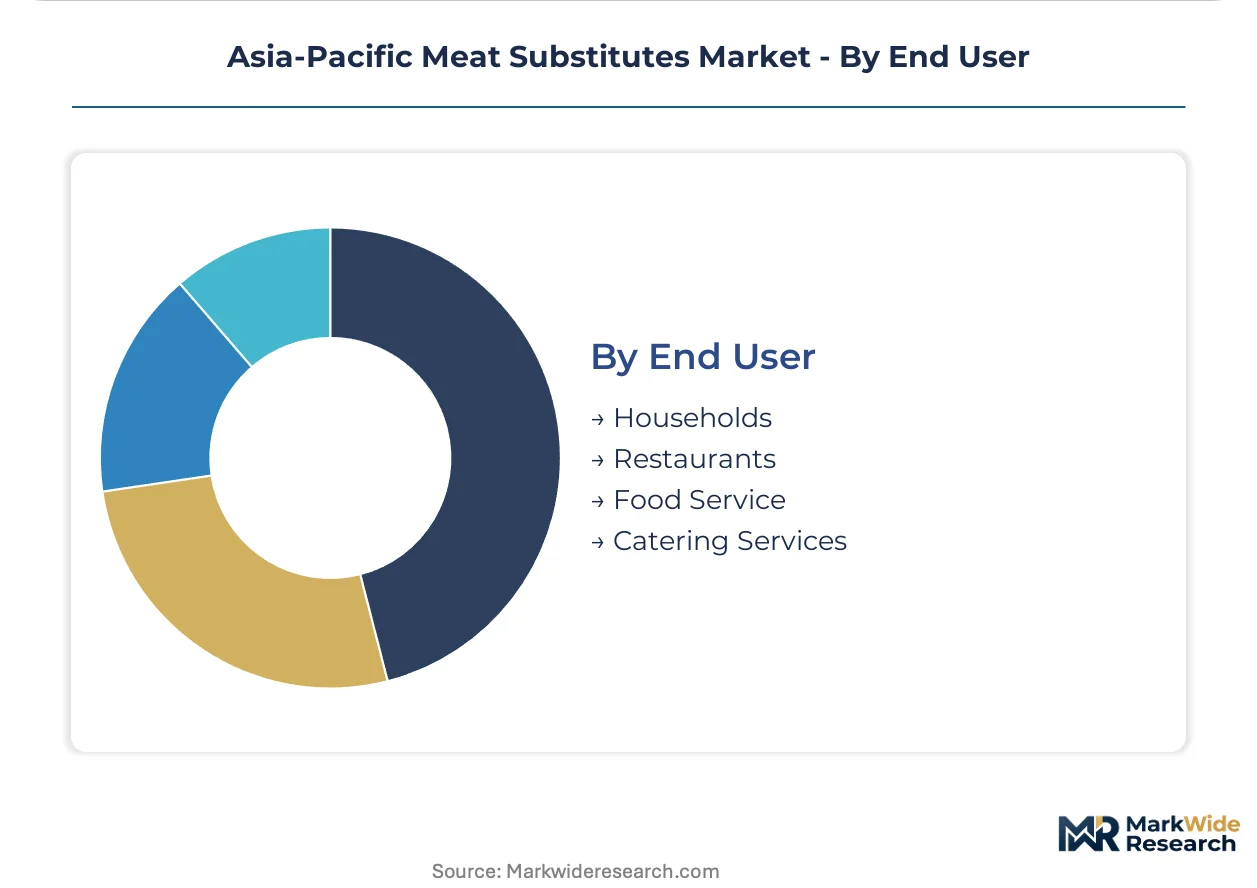
End User:
End-use segmentation separates volume-driven commodity supply from premium formulation development.
- Households:Retail purchasers in Chinese tier-one cities and Australian metro areas drive repeat consumption of pea-protein products through quick-commerce and subscription channels. Price sensitivity varies sharply between traditional tofu buyers and analogue experimenters.
- Restaurants:Quick-service chains across Thailand and the Philippines pilot high-moisture extrusion formats in burger and meatball applications. Menu placement decisions hinge on cost parity with conventional proteins and kitchen equipment compatibility.
- Food Service:Institutional caterers in India and Singapore seek heat-stable formats for buffet and banquet applications. Volume contracts prioritize consistency and supply security over sensory innovation.
- Catering Services:Wedding and event planners in vegetarian-majority Indian markets specify mycoprotein and seitan for premium banquet menus. Custom formulation requirements sustain specialist supplier relationships.
Households absorb the bulk of installed capacity; restaurants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and Singapore's Jurong Island food-tech zone are concentrating pilot-scale fermentation capacity and extrusion R&D facilities for regional meat-substitute supply chains.
China
Health-conscious millennials in Beijing, Shanghai, and Shenzhen drive repeat purchases of pea-protein products through subscription channels. SAMR oversees food safety standards for fermented soy and mycoprotein products entering mass retail, requiring extended stability testing timelines. Yangtze River Delta processing clusters near Shanghai host high-moisture extrusion lines supplying quick-service restaurant chains across Southeast Asia.
India
Vegetarian-majority demographics and street-food culture sustain demand for heat-stable mycoprotein formats in chaat and kebab applications. FSSAI mandates vegan certification logos that influence consumer trust and brand compliance costs. Gujarat and Maharashtra fermentation facilities supply mycoprotein to catering services and institutional food-service channels nationwide.
Japan
Subscription models and quick-commerce channels displace traditional supermarket freezer sections for time-constrained urban households in Tokyo and Osaka. The Consumer Affairs Agency enforces strict allergen labeling for novel protein ingredients, requiring dedicated quality assurance functions. Kanto region cold-chain logistics investments by Rakuten enable fresh-format plant-based protein delivery bypassing retail.
Australia
FSANZ governs nutritional content claims for plant-based meat analogues through a structured pre-approval pathway separating permissible protein statements from prohibited health assertions. Coles and Woolworths chilled sections provide visibility for branded analogues with multi-SKU portfolios. Melbourne and Sydney health-food retail clusters curate organic, non-GMO, and allergen-free assortments driving premium pricing.
South Korea
Online retail channels capture disproportionate growth through recurring revenue pools built on personalized nutrition algorithms and direct-to-home cold-chain logistics. Coupang's logistics investments enable fresh-format delivery that bypasses traditional retail entirely. Seoul Capital Area subscription platforms bundle plant-based proteins with meal-planning algorithms demonstrating higher lifetime value than intermittent retail purchasers.
Asia-Pacific Meat Substitutes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with extrusion technology leaders commanding premium shelf placement while traditional tofu and tempeh suppliers anchor commodity volume. The market exhibits tiered concentration: multinational analogues occupy branded retail tiers, regional fermentation specialists serve food-service channels, and centuries-old soy processors dominate traditional format supply. Three archetypes define competitive positioning: technology-led texture innovators, distribution-anchored regional brands, and heritage-rooted traditional processors. Capacity expansion into high-moisture extrusion lines and strategic partnerships with quick-service restaurant chains represent the dominant competitive moves reshaping share allocation.
Among multinational analogue developers, Beyond Meat and Impossible Foods occupy positions exemplifying technology-led texture innovation through extrusion leadership. OmniFoods anchors the distribution-anchored regional brand archetype through deep retail channel penetration across Hong Kong and Singapore. GoodDot represents the fermentation-specialist tier with mycoprotein formats tailored to Indian street-food heat-stability requirements. These three companies illustrate how divergent capability bases—extrusion IP, retail logistics, and fermentation scale—map to distinct competitive territories within the regional market structure.
| Leading Market Players |
|---|
| Impossible Foods Inc. |
| Beyond Meat |
| Quorn |
| OmniFoods |
| GoodDot |
| China Foodstuff & Protein Group Co. Ltd |
| Kerry Group PLC |
| Morinaga Milk Industry Co. |
| Flexitarian Foods Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap soy processors across Indonesia and Vietnam anchor cost structures through legacy fermentation infrastructure, while their pricing discipline compresses margins for premium analogue entrants attempting to displace commoditized tofu and tempeh volumes.
Pricing Analysis
Short lead-time premiums command 15-25% markups over contract-scheduled deliveries for Canadian pea protein isolate arriving at Shanghai extrusion facilities. Pricing stratifies across premium certified-organic tiers, standard FSSAI-compliant grades, and economy bulk soy concentrates. Cost compression in the standard tier intensifies because Yangtze River Delta processors are expanding high-moisture extrusion capacity. Quick-service restaurant chains in Thailand and the Philippines demonstrate highest price sensitivity, while Australian health-food retailers absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Cross-border freight costs from Canadian prairie processing plants to northern Chinese ports consume 8-12% of landed pea protein isolate value before Yangtze River Delta extrusion. Supply concentrates in Indonesia, Vietnam, and China for traditional soy formats, while mycoprotein fermentation clusters in Singapore and Gujarat. Raw material flows draw from Canadian yellow peas, Javanese whole soybeans, and Australian wheat gluten. Single-source vulnerability concentrates in the Canadian-Chinese pea protein corridor where rail-port logistics disruptions cascade to formulation schedules. Distribution runs through quick-commerce platforms in Seoul and Tokyo, supermarket chilled sections in Sydney and Melbourne, and street-food supply chains across Indian tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific meat substitutes sector sits in a technology-transition phase where high-moisture extrusion is displacing legacy textured vegetable protein infrastructure across quick-service restaurant supply chains.
For Market Incumbents: Deepen backward integration into Canadian and northern Chinese pea protein crushing capacity to secure supply security against logistics volatility threatening formulation schedules. Fortify FSSAI certification investments as India's tightening vegan labeling requirements raise compliance barriers against unqualified entrants. Anchor shelf-positioning contracts with AEON and Lotte Mart before subscription platforms in Seoul and Tokyo erode traditional retail freezer dominance. For New Entrants and Emerging Players: Quick-commerce logistics specialists in South Korea's Seoul Capital Area offer the most penetrable entry vector for fresh-format analogue distribution bypassing supermarket slotting fee structures. Target heat-stable mycoprotein formats for Indian street-food chaat and kebab segments where texture retention gaps persist among incumbent suppliers. Pursue white-label manufacturing partnerships with Gujarat fermentation facilities to accelerate FSSAI certification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor extrusion-technology specialists in Australia's Melbourne-Sydney corridor where FSANZ regulatory clarity accelerates export certification reciprocity across Southeast Asian markets. Long-term viability over a five-to-ten-year horizon rests on securing intellectual property positions in muscle-fiber texture replication. Watch for inflection signals in South Korean subscription platform consolidation as Coupang and Rakuten cold-chain investments reach saturation.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Yangtze River Delta facilities supplying Thai QSR chains compress texture gaps versus conventional proteins. |
| FSSAI Vegan Certification Investment | Compliance logos build consumer trust pools in India's vegetarian-majority markets. |
| Canadian Pea Protein Supply Agreement | Long-term offtake contracts insulate against cross-border logistics volatility in the primary isolate corridor. |
| Quick-Commerce Platform Partnership | Coupang and Rakuten cold-chain integration enables fresh-format delivery bypassing traditional retail entirely. |
| Heat-Stable Mycoprotein Format Development | Gujarat fermentation facilities address Indian street-food applications where texture retention determines repeat purchase. |
Study Parameters
Trade databases, FSSAI regulatory filings, and FSANZ pre-approval determinations formed the secondary backbone for supply chain mapping and compliance pathway analysis. Primary interviews with extrusion technology specialists, quick-service restaurant procurement directors, and cold-chain logistics operators at Coupang and Rakuten validated capacity expansion timelines and channel shift trajectories. Bottom-up modeling of pea protein isolate flows from Canadian crushing plants through Shanghai processing clusters combined with top-down reconciliation against Australian supermarket scanner data.
Historical trendline analysis of tofu and tempeh volume trajectories across Indonesia, Japan, and Vietnam established baseline growth parameters across the projection horizon. Segmentation dimensions modeled include product type, protein source, distribution channel, and end-use heat-stability requirements. CAGRs derived from elasticity-adjusted demand curves incorporating FSSAI certification penetration rates and high-moisture extrusion adoption curves in Thai and Philippine QSR channels.
Caveats apply where SAMR fermentation oversight timelines, Canadian rail logistics disruptions, or Japanese allergen labeling enforcement shifts could materially shift the outlook. Forecasts embed assumptions regarding regulatory reciprocity between FSANZ and Singapore's novel food framework. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Mealworms Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Meat Alternative Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Upcycled Food Products Market