
 North America Insect Protein Market | 2026-2036
North America Insect Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insect Protein Market Analysis
Canadian cricket farming operations is rebalancing output toward aquaculture feed contracts after initial overcapacity in human-grade protein. Aspire Food Group leverages its Texas breeding facilities to sustain year-round supply consistency for pet food brands. Enterra Feed Corporation anchors the British Columbia corridor with industrial-scale black soldier fly larvae production. Protix competes through specialized lipid extraction technology that differentiates its ingredient portfolio from whole-insect processors.
North America insect protein comprises defatted and whole-body meals derived from crickets, mealworms, grasshoppers, and superworms, typically containing 55-75% crude protein by dry weight and processed through controlled-environment rearing, thermal pasteurization, and mechanical milling for incorporation into feed and food matrices. Its primary commercial purpose centers on displacing fishmeal and soybean meal in animal nutrition while supplying hypoallergenic protein isolates for human sports nutrition and snack applications. Crickets dominate current volume due to established consumer familiarity and favorable feed-conversion ratios, while mealworms occupy the fastest-expanding position in aquaculture and poultry formulations where chitin-modified protein shows superior digestibility. The end-user split reveals pet food as the margin pool leader, with human food and nutraceuticals representing higher-growth but still regulatory-constrained segments.
The FDA's Food Safety Modernization Act and the Canadian Food Inspection Agency's novel food guidelines jointly determine market access timelines for human-grade insect ingredients, while the Association of American Feed Control Officials shapes labeling and inclusion standards for pet and livestock applications. State-level variations in agricultural permitting across California, Texas, and Ontario create fragmented compliance landscapes that favor multi-jurisdiction operators. Stakeholders must monitor pending GRAS determinations for additional insect species and pre-position manufacturing flexibility to pivot between feed-grade and food-grade output as regulatory thresholds shift.
Market Dynamics
Pet food manufacturers are consolidating procurement around black soldier fly larvae suppliers to secure hypoallergenic protein streams, while FDA GRAS pathway clarifications for human-grade cricket ingredients are compressing approval timelines for dual-use processors.
Growth Catalysts
- AAFCO labeling standards:The Association of American Feed Control Officials' updated ingredient definitions enable clearer pet food packaging claims, accelerating retail placement for insect-based kibble formulations across the United States.
- Aquaculture feed substitution:Great Lakes region fish farms are displacing fishmeal with chitin-modified mealworm protein, driven by digestibility advantages in rainbow trout and Atlantic salmon grow-out operations.
- Controlled-environment rearing:Automated climate systems for cricket colonies are expanding production consistency, reducing seasonality constraints that previously limited year-round contract fulfillment.
Market Restraints
- Input cost volatility:Organic grain feedstock prices for cricket and mealworm operations fluctuate with Midwest corn and soybean futures, compressing margin predictability for small-scale Canadian farms.
- Supply concentration risk:British Columbia's black soldier fly larvae output dominates North American industrial-scale volume, creating single-corridor vulnerability for aquaculture and poultry feed buyers.
- Technical limitation:Lipid extraction efficiency from whole-insect biomass remains below 85% for most processors, constraining high-value nutraceutical oil yields relative to plant-based alternatives.
Strategic Opportunities
- Texas corridor expansion:Central U.S. breeding facilities can capture pet food brand procurement migrating from coastal logistics costs, leveraging year-round climate stability for cricket production.
- Human sports nutrition:Protein isolate applications in performance supplements remain underpenetrated pending FDA GRAS determinations for additional species beyond house crickets.
- State agricultural incentives:California's alternative protein startup grants and Ontario's agri-tech investment tax credits reduce facility capex burdens for novel feedstock processors.
Industry Challenges
- Entomology talent scarcity:Insect rearing expertise concentrates in academic programs at Texas A&M and University of Guelph, limiting operational scaling for new market entrants.
- Dual-grade facility reconfiguration:Pivoting between feed-grade and food-grade output requires HACCP recertification and separate milling lines, extending compliance timelines when regulatory thresholds shift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insect Protein Market |
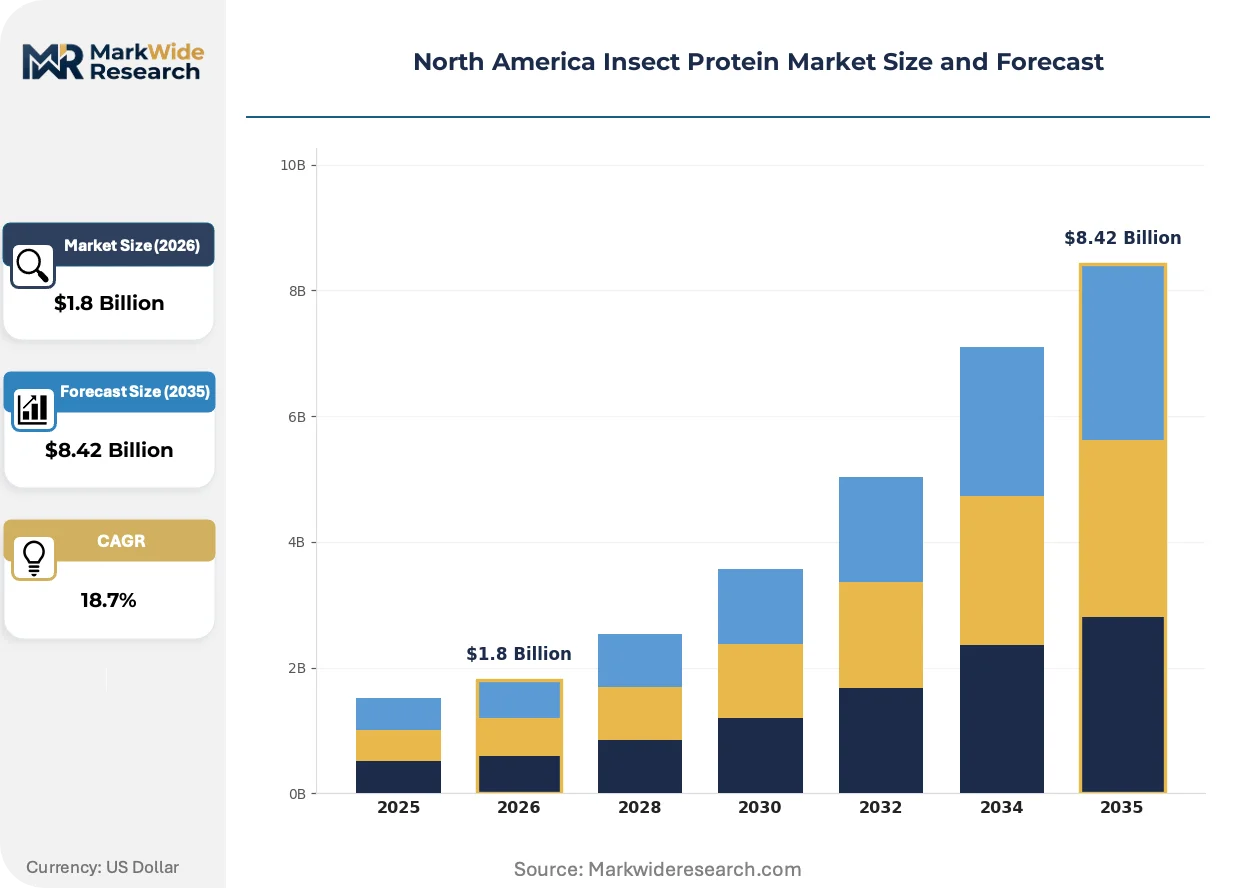
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crickets, Mealworms, Grasshoppers, Superworms End User: Pet Food, Animal Feed, Human Food, Nutraceuticals Application: Protein Supplements, Snacks, Flour, Biological Control Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Aspire Food Group, Enterra Feed Corporation, Protix, Ynsect, Entomo Farms, HEXAFLY, Chapul Cricket Protein, Darling Ingredients Inc., Goterra, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insect Protein Market Emerging Trajectories
Processing automation and regulatory clarity are converging to transform insect protein from specialty ingredient to mainstream feedstock, with technology vendors and end-users co-investing in capacity expansion.
Mechanical milling systems with integrated thermal pasteurization are expanding into mid-scale operations previously limited by batch-processing constraints. Pet food co-manufacturers in the Midwest are adopting these systems to secure third-party certified ingredients without building captive rearing facilities. This equipment diffusion is compressing the minimum viable scale for market entry, enabling regional processors to compete with British Columbia's industrial corridor.
The FDA's evolving GRAS determination framework for novel insect species is clarifying compliance pathways for human consumption applications. This regulatory development accelerates formulation trials by sports nutrition brands previously constrained by ingredient uncertainty. California's alternative protein cluster is responding with pre-positioned manufacturing flexibility to pivot output between feed-grade and food-grade specifications as approvals materialize.
Direct contracting between pet food brands and breeding facilities is displacing traditional ingredient distributor relationships. Premium kibble manufacturers are negotiating multi-year offtake agreements with Texas and Ontario cricket farms to lock in hypoallergenic protein supply. This procurement pattern shift is most visible in California's startup ecosystem and the Great Lakes aquaculture corridor, where end-users prioritize supply consistency over spot-market pricing flexibility.
North America Insect Protein Market Segmentation
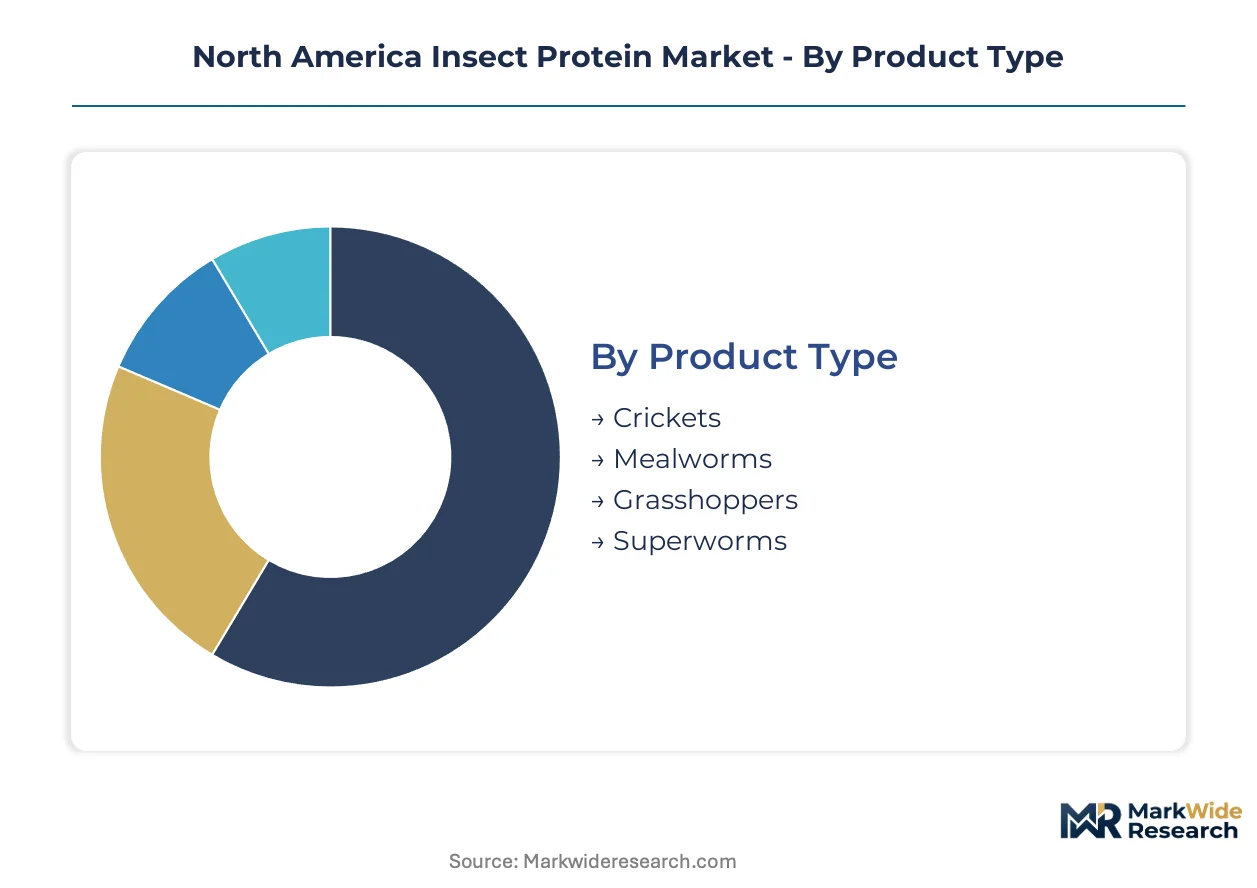
Insect protein markets fragment across species biology, regulatory pathways, and end-use specifications. Each segmentation axis reveals distinct margin structures and compliance requirements that determine viable competitive positioning.
Product Type:
Species selection dictates feed conversion efficiency, chitin content, and regulatory approval status across North American jurisdictions.
- Crickets:House crickets and Acheta domesticus variants yield 60-70% crude protein with established FDA GRAS recognition for human applications. Texas and Ontario breeding facilities concentrate supply contracts for pet food brands seeking hypoallergenic formulations.
- Mealworms:Tenebrio molitor larvae deliver superior digestibility in rainbow trout and Atlantic salmon operations through chitin-modified protein structures. Great Lakes aquaculture feed buyers are consolidating procurement around mealworm suppliers for grow-out diet formulations.
- Grasshoppers:Orthoptera species offer favorable feed conversion in arid climate rearing systems. Limited commercial scale restricts current penetration to specialty snack applications in California's alternative protein cluster.
- Superworms:Zophobas morio larvae provide higher fat content suitable for lipid extraction processes. British Columbia processors leverage superworm biomass for nutraceutical oil production targeting sports nutrition formulations.
Crickets lead on scale; mealworms lead on momentum.
End User:
Regulatory maturity and margin capture vary sharply across consumption categories, with animal nutrition outpacing human food in current commercial traction.
- Pet Food:Premium kibble manufacturers in the United States negotiate multi-year offtake agreements for black soldier fly larvae and cricket meals. AAFCO labeling clarity enables retail placement with explicit hypoallergenic claims.
- Animal Feed:Aquaculture operations across the Great Lakes displace fishmeal with insect protein in rainbow trout diets. Poultry integrators in the Midwest trial mealworm inclusion for broiler grow-out formulations.
- Human Food:Sports nutrition brands await FDA GRAS determinations for additional species beyond house crickets. California startups pre-position manufacturing flexibility for food-grade pivot upon regulatory clearance.
- Nutraceuticals:Lipid extraction from superworm and black soldier fly larvae targets omega fatty acid applications. Processing efficiency constraints below 85% yield suppress current volume relative to plant-based alternatives.
Pet food commands margin leadership; human food represents the steepest expansion trajectory pending regulatory resolution.
Application:
Processing intensity and value-add differentiation separate commodity feed ingredients from branded consumer products.
- Protein Supplements:Isolated protein fractions with 80%+ purity target sports nutrition and clinical nutrition applications. California formulation labs trial cricket isolates for powder and ready-to-drink formats.
- Snacks:Whole roasted and extruded formats occupy early-stage consumer familiarity building. Limited shelf-stable processing infrastructure constrains national distribution scale.
- Flour:Defatted meal with 40-60 mesh particle size integrates into bakery and pasta applications. Pet food co-manufacturers in the Midwest adopt mechanical milling systems for third-party certified flour production.
- Biological Control:Live larvae applications in agricultural pest management operate outside protein extraction value chains. Texas A&M extension programs support regional adoption for specialty crop protection.
Protein supplements concentrate R&D investment; flour applications expand most quickly through equipment diffusion to mid-scale processors.
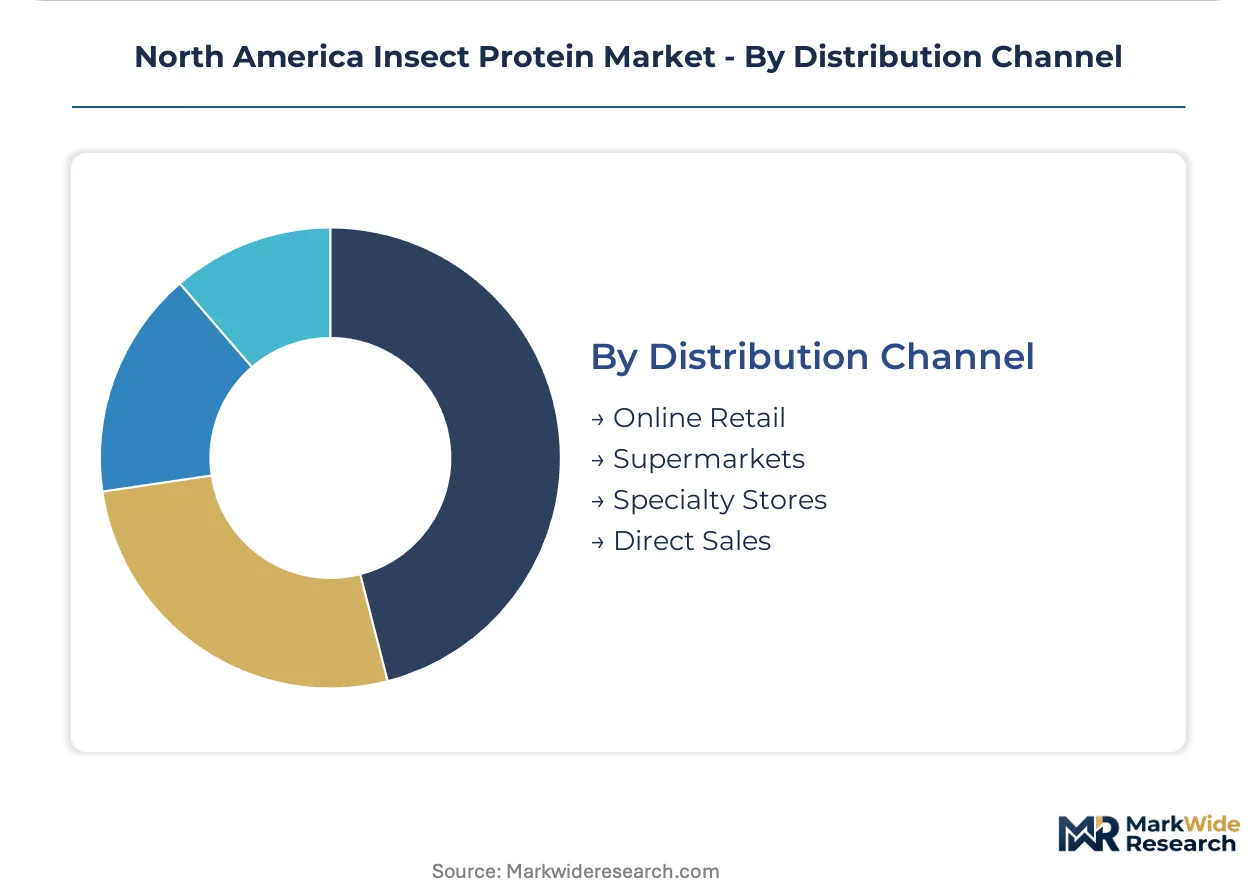
Distribution Channel:
Channel selection reflects customer sophistication, certification requirements, and logistics cost structures for temperature-sensitive products.
- Online Retail:Direct-to-consumer platforms enable subscription models for specialty pet food and human snack trials. California alternative protein startups leverage digital channels to bypass conventional retail slotting barriers.
- Supermarkets:Mass retail placement requires AAFCO-compliant labeling and regional distribution infrastructure. Midwest pet food brands secure shelf space through co-manufacturer relationships with established CPG distributors.
- Specialty Stores:Independent pet retailers and natural food co-ops prioritize hypoallergenic and sustainability claims. Ontario and British Columbia insect protein suppliers cultivate relationships with regional specialty chains.
- Direct Sales:Bulk contracting between breeding facilities and aquaculture or poultry integrators eliminates intermediary margins. Great Lakes fish farms negotiate directly with black soldier fly larvae producers for feed-grade volume.
Direct sales dominate feed-grade volume; online retail is gaining share fastest in consumer-facing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions offering streamlined agricultural permitting and lower compliance costs for novel feedstock facilities. Texas and Ontario attract breeding operations through favorable zoning frameworks, while British Columbia leverages existing infrastructure for industrial-scale processing.
United States
California's alternative protein cluster drives formulation innovation for human-grade applications, while Texas breeding facilities secure year-round supply contracts. The FDA's evolving GRAS pathway clarifies compliance timelines for cricket-based ingredients. Austin and Dallas-Fort Worth anchor the central corridor where automated climate systems sustain consistent colony output.
Canada
Ontario's agri-tech investment tax credits reduce facility capex burdens for novel protein processors targeting pet food brands. The Canadian Food Inspection Agency's novel food guidelines determine market access timelines for human consumption applications. The Guelph-Waterloo corridor concentrates entomology expertise and breeding operations serving Great Lakes aquaculture feed buyers.
British Columbia
Industrial-scale black soldier fly larvae production dominates North American volume for aquaculture and poultry feed applications. Provincial agricultural permits support concentrated processing infrastructure along the Vancouver-Fraser Valley axis. Enterra Feed Corporation anchors this corridor with integrated rearing and lipid extraction capabilities.
Great Lakes Region
Rainbow trout and Atlantic salmon operations across Michigan and Wisconsin displace fishmeal with chitin-modified mealworm protein. State-level aquaculture expansion programs subsidize feed trials for insect-based grow-out diets. The Milwaukee-Chicago corridor hosts co-manufacturers adopting mechanical milling systems for third-party certified ingredient production.
North America Insect Protein Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized extraction technologies and geographic expansion. The vendor base stratifies between industrial-scale processors with captive breeding facilities and mid-scale operators relying on third-party supply contracts. Two archetypes dominate: integrated rearing-to-processing operators controlling quality consistency, and technology licensors monetizing patented extraction systems. Capacity expansion and direct offtake contracting with pet food brands represent the dominant competitive moves.
Among North American operators, Aspire Food Group and Enterra Feed Corporation exemplify the integrated archetype with captive breeding infrastructure, while Protix represents the technology-specialist tier through proprietary lipid extraction capabilities. These three entities anchor distinct competitive vectors: Texas-based year-round supply consistency, British Columbia's industrial-scale larvae production, and European-derived processing technology adapted for regional feed-grade applications.
| Leading Market Players |
|---|
| Aspire Food Group |
| Enterra Feed Corporation |
| Protix |
| Ynsect |
| Entomo Farms |
| HEXAFLY |
| Chapul Cricket Protein |
| Darling Ingredients Inc. |
| Goterra |
| Others |
Supply Flow & Price Mechanics
Captive breeding-to-processing integration anchors supply positioning and pricing power for North American insect protein operators, with Texas and British Columbia facilities leveraging in-house colony control to command premium contract terms from pet food brands and aquaculture buyers.
Pricing Analysis
Distributor margin layers compress as direct contracting between breeding facilities and end-users displaces traditional ingredient intermediaries. Contract-based long-term offtake agreements dominate premium kibble formulations, while spot-market transactions persist for feed-grade mealworm volume. Price differentiation hinges on FDA GRAS certification tier and volume scale, with human-grade cricket isolates capturing substantial premiums over aquaculture feed meals. Pricing pressure intensifies from organic grain feedstock volatility tied to Midwest corn futures, squeezing margin predictability for small-scale Canadian farms. Pet food manufacturers exhibit lowest price sensitivity due to hypoallergenic protein scarcity, while commodity poultry integrators remain most cost-conscious.
Supply Chain Analysis
Freight cost differentials between coastal British Columbia processing hubs and central U.S. pet food manufacturing clusters are reshaping procurement geography, incentivizing Texas corridor expansion. Supply concentrates in Canada and the United States, with British Columbia's black soldier fly larvae output and Texas cricket breeding anchoring North American volume. Raw material dependencies center on organic grain feedstocks, automated climate system components, and thermal pasteurization equipment. Single-corridor vulnerability creates structural risk for aquaculture buyers reliant on Vancouver-Fraser Valley processing infrastructure. Distribution runs through direct sales contracts for feed-grade volume, with online retail gaining share in consumer-facing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America insect protein functions as a regulatory compounder, with FDA GRAS pathway clarifications for additional cricket species accelerating formulation trials and compressing approval timelines for dual-use processors.
For Market Incumbents: Cement multi-year offtake agreements with premium pet food brands before AAFCO labeling standardization commoditizes hypoallergenic claims. Expand captive breeding capacity in Texas to capture procurement migration from coastal logistics costs. Vertical integration into automated climate systems reduces seasonality constraints that threaten contract fulfillment consistency. For New Entrants and Emerging Players: Proprietary lipid extraction technology offers entry wedge into nutraceutical applications where superworm and black soldier fly oil yields remain below plant-based alternatives. Target human sports nutrition isolates pending FDA GRAS determinations for mealworm species. Pursue equipment-leasing partnerships with Midwest pet food co-manufacturers seeking third-party certified ingredient supply without captive facility investment. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Canadian cricket farms because Ontario agri-tech tax credits reduce facility capex burdens while entomology talent scarcity limits new entrant replication. Five-to-ten year viability hinges on human-grade regulatory resolution expanding addressable market beyond animal nutrition. Monitor FDA GRAS determination timelines for mealworm and grasshopper species as inflection indicator for sports nutrition brand procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AAFCO Certification Investment | Enables explicit hypoallergenic labeling claims for premium kibble retail placement. |
| Texas Corridor Capacity Expansion | Captures pet food brand procurement migrating from British Columbia logistics costs. |
| Lipid Extraction Technology Licensing | Addresses sub-85% yield constraints suppressing nutraceutical oil competitiveness. |
| Direct Offtake Contracting | Displaces distributor margins and locks supply consistency for aquaculture buyers. |
| Dual-Grade Facility Reconfiguration | Positions manufacturing flexibility for human food pivot upon FDA clearance. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pet food procurement directors, aquaculture feed formulators, insect breeding facility operators, and regulatory affairs specialists at FDA and Canadian Food Inspection Agency with secondary validation from AAFCO ingredient definition updates, FDA GRAS notice filings, customs trade records for insect meal imports, and provincial agricultural permitting databases across California, Texas, and Ontario. Bottom-up facility capacity estimates and top-down end-use demand projections were triangulated for segment-level consistency.
Segment-weighting approaches modeled species biology, regulatory pathway maturity, and end-use application intensity across the projection horizon. Dimensions included insect species, processing grade tier, target nutrition sector, and regional production cluster. CAGRs were derived from installed capacity trajectories, contract visibility from multi-year offtake agreements, and regulatory milestone probability-weighting. Forecast inputs incorporated organic grain feedstock price sensitivity and automation capital expenditure cycles for climate-controlled rearing systems.
The model holds under stable FDA GRAS determination timelines and AAFCO labeling clarity; deviation in regulatory approval delays or feedstock price volatility would shift capacity expansion schedules and contract pricing structures. Forecasts reflect documented assumptions about entomology talent pipeline constraints and provincial permitting efficiency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Pet Food Microalgae Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Meat Analogue Market