
 Insect Snacks Market | 2026-2036
Insect Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Insect Snacks Market Outlook
Europe is reshaping insect snack manufacturing capacity through scaled cricket and mealworm facilities in France and the Netherlands. Ÿnsect leverages vertical integration from larvae cultivation to finished protein ingredients near its Paris-region plant. Aspire Food Group anchors North American supply through its Texas-based cricket farming infrastructure. Jimini's competes via specialized whole-insect and baked snack formulations tailored to European palate preferences.
Insect snacks comprise processed or whole edible insects—typically crickets, mealworms, or black soldier fly larvae—formulated into consumer-ready products with protein contents ranging from forty to seventy percent dry weight by species. These products serve commercial purposes spanning human nutrition supplementation, pet food protein enrichment, and culinary ingredient applications. Protein powders currently dominate margin pools due to ingredient versatility across food manufacturing, while energy bars capture the fastest expansion through health-food retail placement. Whole insects remain a niche culinary segment concentrated in specialty stores and direct-to-restaurant supply.
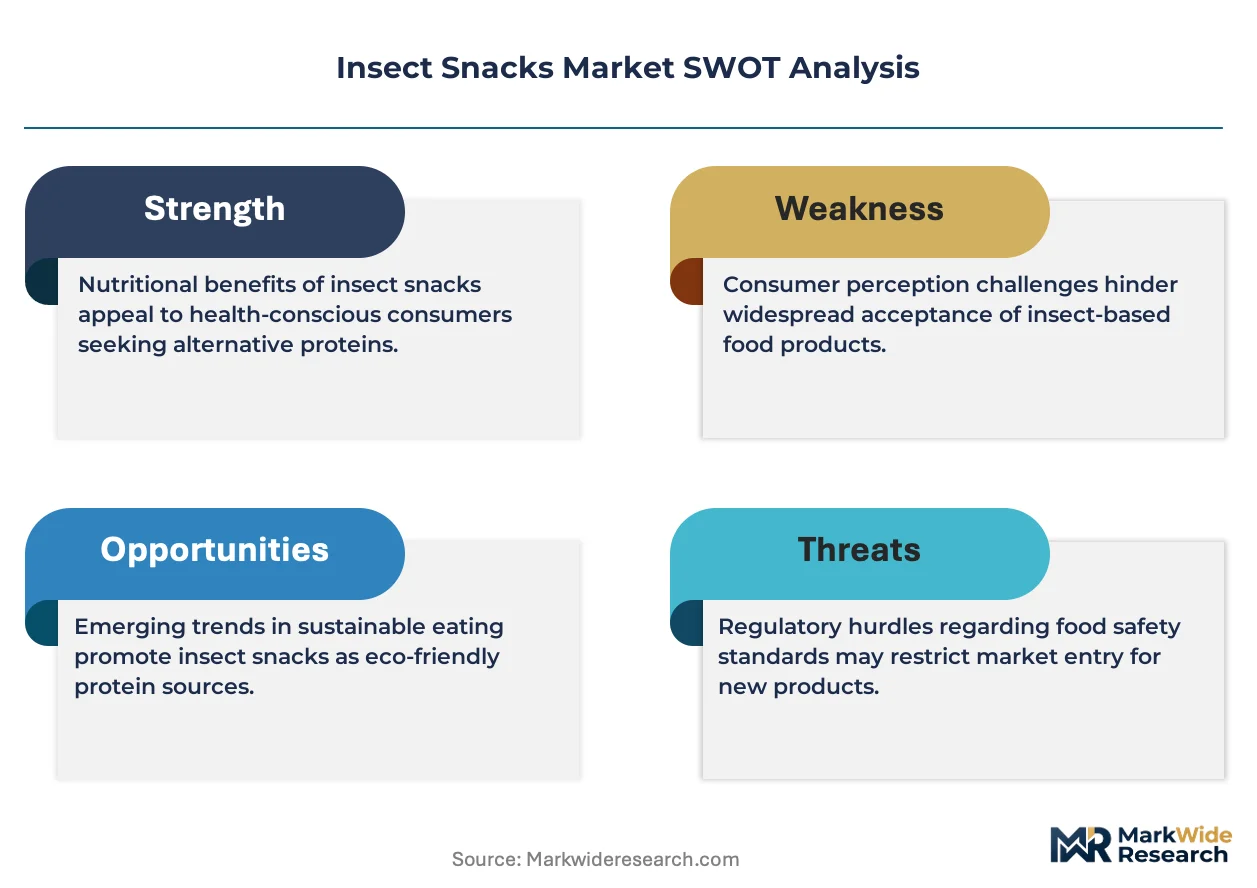
EFSA novel food authorizations under EU Regulation 2015/2283 determine which insect species enter European commerce, while FDA enforcement discretion letters govern US market access pending formal GRAS determinations. EFSA's expanding positive safety opinions for additional species are widening formulation possibilities for manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions as classification decisions directly determine export eligibility and product labeling requirements.
Market Dynamics
EFSA's novel food authorization pipeline is compressing time-to-market for insect protein manufacturers while concentrating production capacity near regulatory approval hubs in Western Europe.
Growth Catalysts
- EU Novel Food Framework:EFSA Regulation 2015/2283 authorizations for dried yellow mealworm and house crickets have unlocked retail distribution across Germany, France, and the Netherlands. Approved species now qualify for EU-wide passporting.
- Pet Food Formulation Demand:Premium pet food manufacturers are integrating insect protein meal as a hypoallergenic alternative to chicken and fish derivatives, creating offtake agreements that stabilize larval farming economics.
- Automated Rearing Systems:Climate-controlled vertical farming infrastructure in Belgium and the Netherlands is reducing labor intensity and mortality rates in black soldier fly larvae production.
Market Restraints
- Feed Cost Volatility:Organic substrate prices—spent grains, fruit pulp, and vegetable trimmings—fluctuate with agricultural commodity cycles and seasonal processing volumes.
- Single-Region Supply Concentration:Over half of European insect protein processing capacity clusters within 200 kilometers of Amsterdam and Paris, creating logistics vulnerability and input competition.
- Consumer Acceptance Thresholds:Whole-insect products face persistent aversion in Anglo-Saxon markets despite powder and flour acceptance, limiting format diversification.
Strategic Opportunities
- Asian Market Access:Thailand's established cricket farming tradition and permissive food safety standards offer first-mover positioning ahead of formal ASEAN harmonization.
- Sports Nutrition Channel Expansion:E-commerce subscription models for protein isolates are bypassing conventional retail gatekeepers and capturing repeat-purchase loyalty.
- EU Green Deal Protein Diversification:Farm-to-Fork Strategy targets for reduced livestock dependency are channeling public R&D funding toward insect protein scale-up demonstrations.
Industry Challenges
- Entomology Talent Scarcity:Industrial-scale insect rearing requires specialized knowledge in microbiome management and population genetics that academic programs have not yet scaled to meet.
- Co-Manufacturing Certification Delays:Third-party facilities handling both conventional and novel foods face extended audit timelines under EFSA cross-contamination protocols.
- Downstream Integration Complexity:Protein extraction and texturization equipment requires capex commitments that strain mid-scale larval farms without committed offtake volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect Snacks Market |
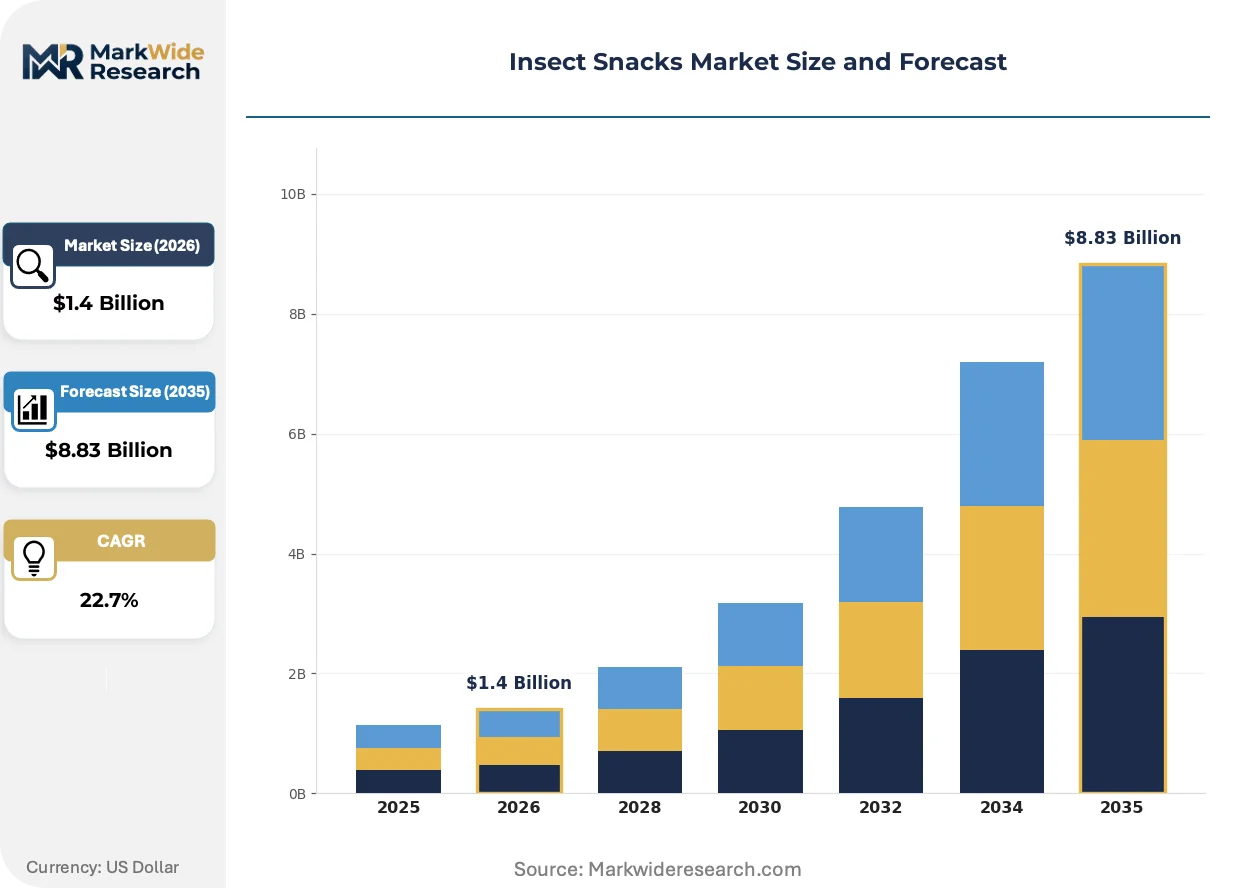
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $8.83 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Insects, Protein Powders, Energy Bars, Snacks Application: Health Foods, Functional Foods, Pet Foods, Culinary Uses Customer Type: Retail Consumers, Restaurants, Food Manufacturers, Health Conscious Individuals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers' Markets |
| Companies Covered | Jimini's, Exo Protein, Ÿnsect, Cricket One, Eat Grub, Aspire Food Group, Chapul, Small Giants, Entomo Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect Snacks Market Strategic Shifts
Processing technology maturation is separating scalable ingredient suppliers from artisanal whole-insect producers, while regulatory clarity in Europe is pulling investment away from speculative jurisdictions.
Precision fermentation of insect-derived peptides is rendering obsolete conventional heat-drying and mechanical milling for high-purity protein isolation. Sports nutrition formulators in Germany and the Netherlands are adopting these enzymatic extraction methods to achieve neutral flavor profiles and improved solubility. The technology is compressing margin structures for commodity-grade insect flour while creating premium tier separation in ingredient supply.
EFSA's expanding positive safety opinions under EU Regulation 2015/2283 are systematically de-risking species-level approvals for lesser mealworm and banded crickets. This regulatory momentum is triggering parallel facility investments in France and Belgium as manufacturers position for authorized species portfolio expansion. Powder and isolate segments are responding with accelerated formulation pipelines ahead of anticipated market access broadening.
Direct-to-consumer subscription models for insect protein powders are displacing conventional health-food retail placement as the primary customer acquisition channel. Young adult demographics in urban Netherlands and Danish markets are purchasing through specialized e-commerce platforms that emphasize sustainability credentials and traceability. This channel rotation is most visible in Nordic markets where digital-native purchasing patterns have outpaced Southern European retail infrastructure development.
Insect Snacks Market Segmentation
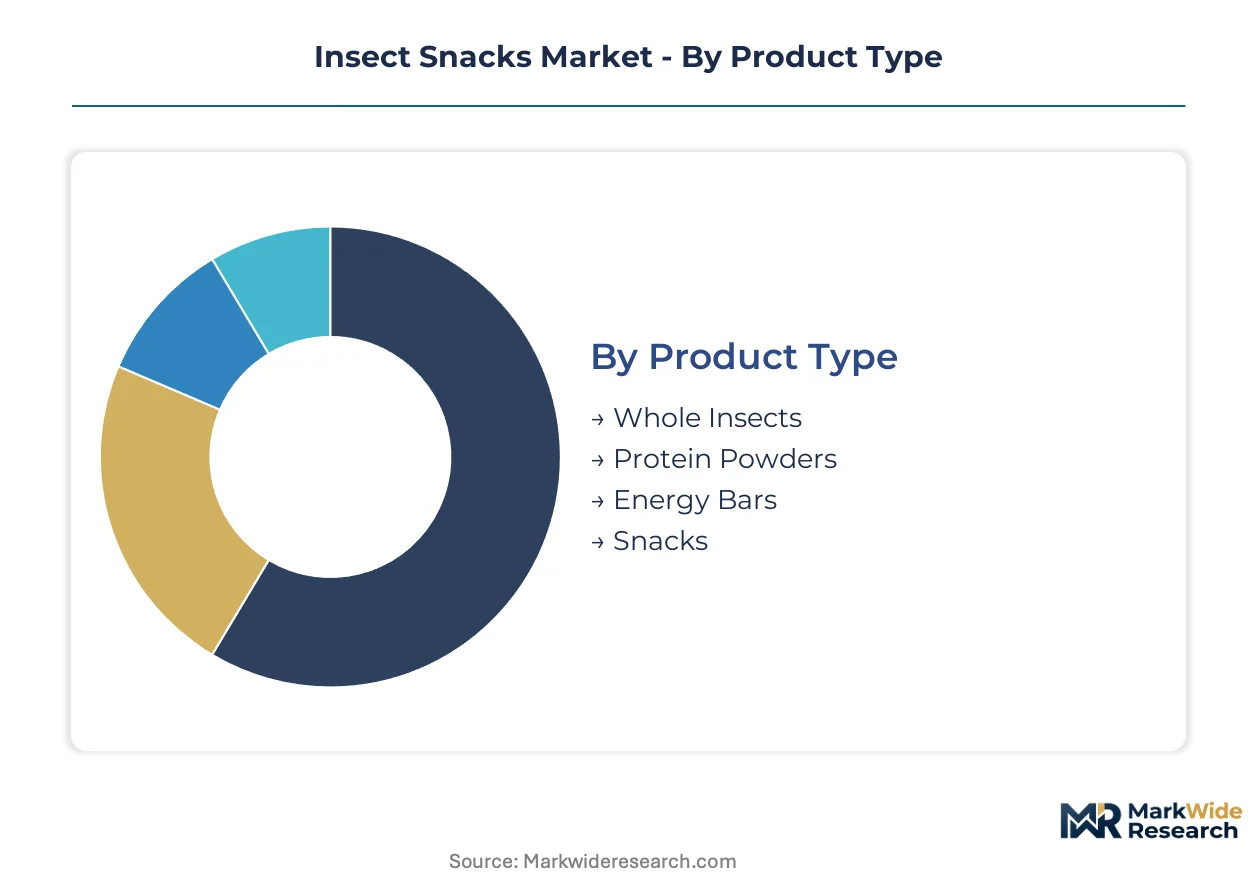
Insect snacks fragment across four intersecting dimensions that determine margin capture and channel strategy. Product format dictates processing investment and regulatory pathway, while application scope separates commodity ingredient plays from branded consumer positioning.
Product Type:
Formats span minimally processed whole insects to highly refined protein isolates, with capital intensity and margin structure inversely correlated to processing depth.
- Protein Powders:Milled and defatted insect flours achieve forty to seventy percent protein concentration by dry weight. German and Dutch food manufacturers are concentrating procurement here for sports nutrition and bakery enrichment applications, driven by EFSA novel food approvals that ease cross-border formulation.
- Energy Bars:Composite formulations bind insect flour with dates, nuts, and flavor masking agents into shelf-stable retail formats. Health-food chains in the Netherlands are driving placement velocity through sustainability-forward merchandising, though flavor neutrality remains a formulation constraint.
- Whole Insects:Roasted or freeze-dried intact crickets and mealworms serve culinary experimentation and specialty retail. Thai and Vietnamese traditional consumption patterns sustain limited export demand.
- Snacks:Extruded puffs, chips, and crackers incorporate insect protein at ten to thirty percent inclusion rates. Belgian and French producers are piloting these formats for mainstream retail acceptance testing.
The dominant share belongs to Protein Powders, while Energy Bars are closing the gap fastest.
Application:
End-use segmentation separates B2B ingredient supply from direct consumer touchpoints, with regulatory treatment diverging sharply across these boundaries.
- Health Foods:Protein supplementation targeting fitness and wellness demographics. Dutch e-commerce subscription models and German pharmacy retail chains are concentrating demand, supported by EU Green Deal protein diversification messaging.
- Pet Foods:Hypoallergenic protein meal for premium dog and cat formulations. French and Dutch pet food manufacturers are locking in multi-year offtake agreements with black soldier fly larvae farms, stabilizing larval farming economics against human-food regulatory delays.
- Functional Foods:Gut health and immunity positioning through chitin and peptide bioactives. Early-stage formulation activity clusters in Danish and Swedish R&D facilities.
- Culinary Uses:Restaurant and foodservice experimentation with whole insects and insect-based sauces. Michelin-rated establishments in Paris and Copenhagen are driving visibility, though volume remains marginal.
Pet Foods currently command the largest volume commitment, with Health Foods gaining share most rapidly through retail channel expansion.
Customer Type:
Buyer sophistication and purchase frequency vary dramatically across direct consumers, professional kitchens, and industrial formulators.
- Food Manufacturers:Industrial buyers integrating insect protein into existing product lines. German bakery and meat-alternative producers are leading formulation trials, constrained by co-manufacturing certification delays under EFSA cross-contamination protocols.
- Health Conscious Individuals:Direct purchasers prioritizing sustainability credentials and novel nutrition sources. Urban demographics in Amsterdam and Copenhagen are overrepresented in e-commerce subscription adoption.
- Restaurants:Chef-driven procurement for menu differentiation and media coverage. Copenhagen's Noma alumni network and Parisian bistronomy sector are sustaining niche demand.
- Retail Consumers:Supermarket and specialty store shoppers encountering insect snacks through conventional retail. German REWE and Dutch Albert Heijn trial placements are testing mainstream acceptance thresholds.
Food Manufacturers anchor current revenue, while Health Conscious Individuals are expanding the addressable base fastest through digital-native purchasing patterns.
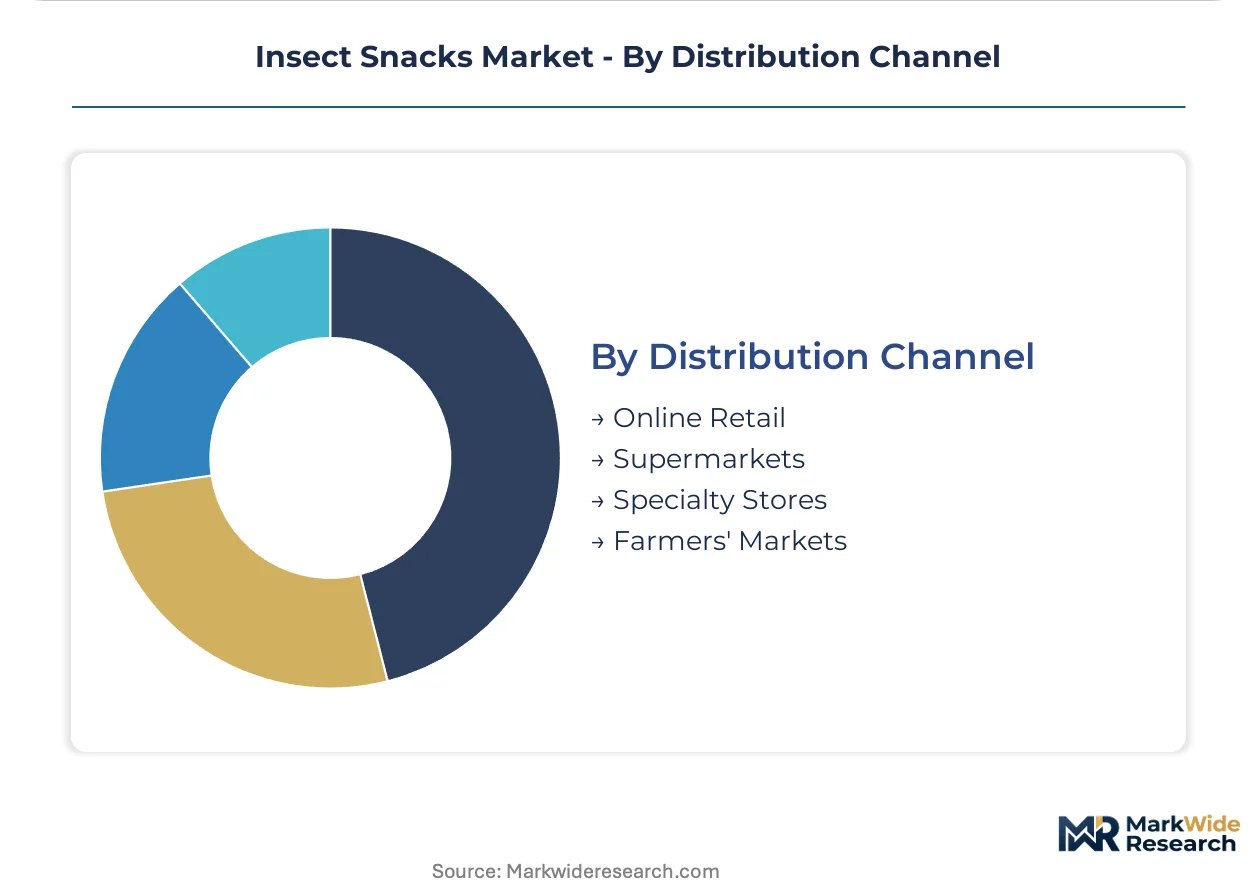
Distribution Channel:
Channel selection determines margin retention and consumer education burden, with digital platforms capturing disproportionate growth in early-adopter geographies.
- Online Retail:Direct-to-consumer and specialized platform sales emphasizing traceability and sustainability storytelling. Dutch startups like Bugaboo and Belgian Entomo Farms are building subscription loyalty in Nordic markets.
- Specialty Stores:Health-food and bio-focused independents with educated staff and sampling capacity. German Alnatura and Dutch Ekoplaza chains are concentrating shelf space for EFSA-approved species.
- Supermarkets:Conventional grocery placement requiring mass-market packaging and price parity with conventional protein snacks. Limited to protein powders and energy bars in German and French test regions.
- Farmers' Markets:Local producer direct sales with minimal regulatory overhead. Seasonal presence in Belgian and Dutch urban markets sustains artisanal whole-insect producers.
Online Retail holds the steepest expansion trajectory, while Specialty Stores maintain the highest conversion rates for premium formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across markets: Western European buyers favor processed powders and bars, while Southeast Asian consumers maintain traditional whole-insect culinary practices. This mix differential shapes regulatory investment and manufacturing infrastructure deployment.
Germany
Health-food retail chains and pharmacy distribution networks drive powder and energy bar demand. EFSA novel food approvals under EU Regulation 2015/2283 enable cross-border formulation passporting. Industrial clusters concentrate in North Rhine-Westphalia and Bavaria, where bakery and meat-alternative manufacturers conduct formulation trials.
Netherlands
E-commerce subscription models and urban sustainability-conscious demographics accelerate digital-native purchasing. EU Green Deal Farm-to-Fork Strategy targets channel public R&D funding toward protein diversification. Randstad region hosts vertically integrated larval cultivation and processing facilities near Amsterdam and Rotterdam logistics hubs.
France
Premium pet food manufacturers lock in multi-year offtake agreements for hypoallergenic protein meal. ANSM food safety coordination aligns with EFSA authorization timelines for novel species. Île-de-France and Hauts-de-France concentrate cricket and mealworm farming infrastructure with Paris-region processing plants.
United States
FDA enforcement discretion letters govern market access pending formal GRAS determinations, constraining retail expansion. Sports nutrition and specialty foodservice sustain niche demand. Texas anchors North American cricket farming capacity with climate-controlled rearing infrastructure serving ingredient supply chains.
Thailand
Traditional cricket farming practices and permissive food safety standards sustain established domestic consumption and limited export positioning. National agricultural extension programs support farmer cooperatives. Northeastern provinces maintain artisanal production clusters ahead of formal ASEAN harmonization efforts.
Insect Snacks Market Competitive Environment
Capability concentration sits with technology-integrated larval farming specialists; scale advantage sits with diversified ingredient suppliers with established offtake relationships. The market structures around three tiers: vertically integrated cultivators with captive processing, specialist snack formulators with branded consumer positioning, and commodity-grade larval farms supplying B2B ingredient markets. Dominant competitive moves include strategic partnerships with pet food manufacturers and capacity expansion near regulatory approval hubs.
Within the European specialist tier, Jimini's and Ÿnsect occupy distinct positioning archetypes. Jimini's exemplifies branded consumer-facing formulation with whole-insect and baked snack portfolios tailored to regional palate preferences. Ÿnsect anchors the vertically integrated model with larvae-to-ingredient processing infrastructure near Paris-region facilities. Aspire Food Group represents the North American scale-driven approach with Texas-based cricket farming operations.
| Leading Market Players |
|---|
| Jimini's |
| Exo Protein |
| Ÿnsect |
| Cricket One |
| Eat Grub |
| Aspire Food Group |
| Chapul |
| Small Giants |
| Entomo Farms |
| Others |
Value Chain & Pricing Dynamics
Amsterdam-Rotterdam-Antwerp freight corridors compress logistics costs for insect protein shipments while amplifying price differentiation between EFSA-certified premium tiers and uncertified commodity grades. This corridor concentration enables Dutch and Belgian cultivators to command ingredient premiums against peripheral suppliers facing higher inland transport burdens.
Pricing Analysis
Long-term offtake contracts dominate pet food ingredient procurement, stabilizing larval farm revenues against spot-market volatility in human-food applications. Three-tier pricing structure across premium isolates, standard defatted flours, and economy-grade whole insects reflects EFSA certification status and extraction technology sophistication. Pricing pressure stems from organic substrate cost volatility as agricultural commodity cycles squeeze farming margins. Pet food manufacturers exhibit lowest price sensitivity due to hypoallergenic formulation premiums, while health-food retailers drive hardest bargain on commodity powders.
Supply Chain Analysis
EU novel food authorization regimes under Regulation 2015/2283 restrict species flows to approved cricket and mealworm varieties, constraining formulation flexibility for non-compliant imports. Supply concentrates in the Netherlands, France, and Belgium where vertical farming infrastructure clusters within two hundred kilometers of Amsterdam and Paris. Black soldier fly larvae production draws from spent grain, fruit pulp, and vegetable trimmings sourced from regional food processors. Single-region concentration creates logistics vulnerability during climate-controlled facility disruptions. Distribution runs through specialized B2B ingredient channels for pet food manufacturers and direct-to-consumer e-commerce platforms for health-food segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insect snacks market occupies early-cycle expansion positioning as EFSA novel food approvals compress time-to-market for new species and formats. Protein diversification mandates under the EU Green Deal Farm-to-Fork Strategy channel public R&D funding toward scaled cultivation demonstrations.
For Market Incumbents: Insulate margin structures by locking multi-year offtake agreements with premium pet food manufacturers before commodity powder competition intensifies. Pursue backward integration into climate-controlled rearing infrastructure near Paris and Amsterdam regulatory hubs to reduce feed cost exposure and mortality rates. Defend against precision fermentation substitutes by accelerating enzymatic extraction capabilities for high-purity isolate production. For New Entrants and Emerging Players: Establish a beachhead in Thai cricket farming cooperatives ahead of formal ASEAN harmonization, leveraging permissive food safety standards and established domestic consumption patterns. Target sports nutrition e-commerce subscriptions in Nordic urban markets where digital-native purchasing outpaces Southern European retail infrastructure. Deploy sustainability credential storytelling and traceability transparency as primary customer acquisition mechanisms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated cultivators with captive processing infrastructure over pure-play commodity larval farms. Five-to-ten year viability hinges on species portfolio breadth and regulatory approval velocity rather than single-format dominance. Monitor EFSA positive safety opinion pipeline for lesser mealworm and banded cricket authorizations as inflection indicator for formulation diversification plays.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Approval Expansion | Species-level authorizations under EU Regulation 2015/2283 unlock cross-border formulation passporting for manufacturers. |
| Pet Food Offtake Agreement | Multi-year contracts with French and Dutch hypoallergenic pet food producers stabilize larval farming economics. |
| Precision Fermentation Investment | Enzymatic peptide extraction technology in German R&D facilities renders conventional heat-drying methods obsolete. |
| Direct-to-Consumer Subscription Launch | Dutch Bugaboo and Belgian Entomo Farms capture repeat-purchase loyalty through specialized e-commerce platforms. |
| Climate-Controlled Vertical Farm Scale-Up | Belgium and Netherlands infrastructure reduces labor intensity and mortality in black soldier fly larvae production. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EFSA novel food safety opinions, EU customs trade databases, and pet food manufacturer procurement disclosures. Primary interviews engaged larval farm operations directors, EFSA regulatory affairs consultants, Dutch health-food retail category buyers, and German sports nutrition formulators. Secondary validation drew from EU Regulation 2015/2283 authorization records, Farm-to-Fork Strategy implementation reports, and vertical farming equipment vendor technical specifications. Bottom-up volume modeling triangulates against top-down protein substitution demand estimates.
Forecast inputs incorporate product format segmentation across protein powders, energy bars, whole insects, and extruded snacks; application scope spanning health foods, pet foods, functional foods, and culinary uses; and distribution channel dynamics including online retail, specialty stores, supermarkets, and farmers markets. CAGRs derive from penetration curve analysis against comparable novel protein adoption patterns. Modeled inputs include EFSA approval timeline assumptions, organic substrate cost trajectories, and pet food manufacturer formulation commitment velocities.
Sensitivities concentrate around EFSA authorization delays for additional species, feed cost volatility in agricultural commodity cycles, and consumer acceptance thresholds in Anglo-Saxon markets. Forecasts reflect documented assumptions regarding regulatory momentum and channel rotation toward digital-native purchasing. Material shifts in EU Green Deal funding allocation or ASEAN harmonization timeline would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Monoprotein Market