
 Bagasse Disposable Cutlery Market | 2026-2036
Bagasse Disposable Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Bagasse Disposable Cutlery Market Outlook
Pre-bundled utensil kits containing spoons, forks, and napkins are recalibrating how institutional buyers evaluate cost-per-serving metrics. Huhtamaki leverages its European manufacturing footprint to supply bundled compostable cutlery directly to contract catering operators. Genpak sustains competitive pressure through specialized molded-fiber production lines that serve North American quick-service chains. Vegware differentiates by controlling compostable certification pathways across multiple national standards.
Bagasse disposable cutlery consists of molded fiber articles manufactured from sugarcane pulp residue, typically processed through high-pressure thermal forming at temperatures exceeding 180°C to achieve structural rigidity suitable for hot and cold food contact. The material contains approximately 80-95% cellulose fibers with natural lignin binding, producing items that meet food-grade migration limits while decomposing within commercial composting cycles. Spoons and forks lead current revenue contribution due to their dominance in quick-service and takeaway applications, though knives represent a faster-growing configuration as burger and steakhouse chains adopt complete cutlery sets. Compostable-grade material commands premium positioning relative to merely biodegradable alternatives, as foodservice operators prioritize end-of-life verifiability to satisfy corporate sustainability commitments and municipal waste-sorting requirements.
The EU F-Gas Regulation and REACH chemical compliance frameworks shape material sourcing decisions for European manufacturers, while FDA food-contact substance notifications govern US market entry for imported bagasse articles. India's BIS certification requirements for food-contact materials and the country's PLI scheme for biodegradable products are expanding domestic production capacity and redirecting some export flows. Stakeholders must monitor how divergent compostability certification standards between jurisdictions affect cross-border product registration costs and customer acceptance thresholds.
Market Dynamics
Quick-service restaurant procurement teams are consolidating vendor relationships around bundled cutlery kits, compressing supplier margins while elevating compostable certification requirements as a non-negotiable gate for contract eligibility.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory bans on plastic cutlery across member states are redirecting institutional foodservice procurement toward bagasse alternatives with verified compostable pathways.
- Molded-fiber thermal forming:Process refinements achieving 180°C+ compression are yielding structural rigidity competitive with polystyrene for hot-food applications.
- German municipal composting infrastructure:Standardized industrial composting cycles with 90-day degradation verification are creating reference-market conditions for certified tableware uptake.
Market Restraints
- Sugarcane pulp supply concentration:Bagasse fiber availability ties directly to Brazilian and Indian sugarcane harvest cycles, exposing converters to raw material seasonality.
- REACH chemical compliance costs:European manufacturers face elevated testing burdens for lignin-based binding agents under ECHA substance evaluation protocols.
- Polylactic acid substitution:PLA cutlery with clearer home-composting claims competes for shelf space in retail channels despite inferior heat tolerance.
Strategic Opportunities
- India PLI scheme for biodegradable products:Production-linked incentives are expanding domestic molded-fiber capacity and redirecting export flows toward Middle Eastern foodservice markets.
- Complete cutlery set adoption:Burger and steakhouse chains are specifying knife-inclusive configurations, opening premium positioning for reinforced bagasse formulations.
- Direct-to-caterer digital platforms:Institutional buyers are bypassing traditional distribution tiers through specialized procurement portals aggregating certified compostable suppliers.
Industry Challenges
- Divergent compostability standards:Cross-border registration costs multiply as manufacturers navigate separate certification pathways for BPI, TÜV OK Compost, and Australasian Bioplastics verification.
- High-pressure thermal forming capex:Precision mold fabrication and automated forming lines demand capital commitments that constrain mid-scale converter expansion.
- Food-grade migration testing timelines:FDA food-contact substance notifications and EFSA evaluations extend product launch cycles by 12-18 months for novel fiber treatments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bagasse Disposable Cutlery Market |
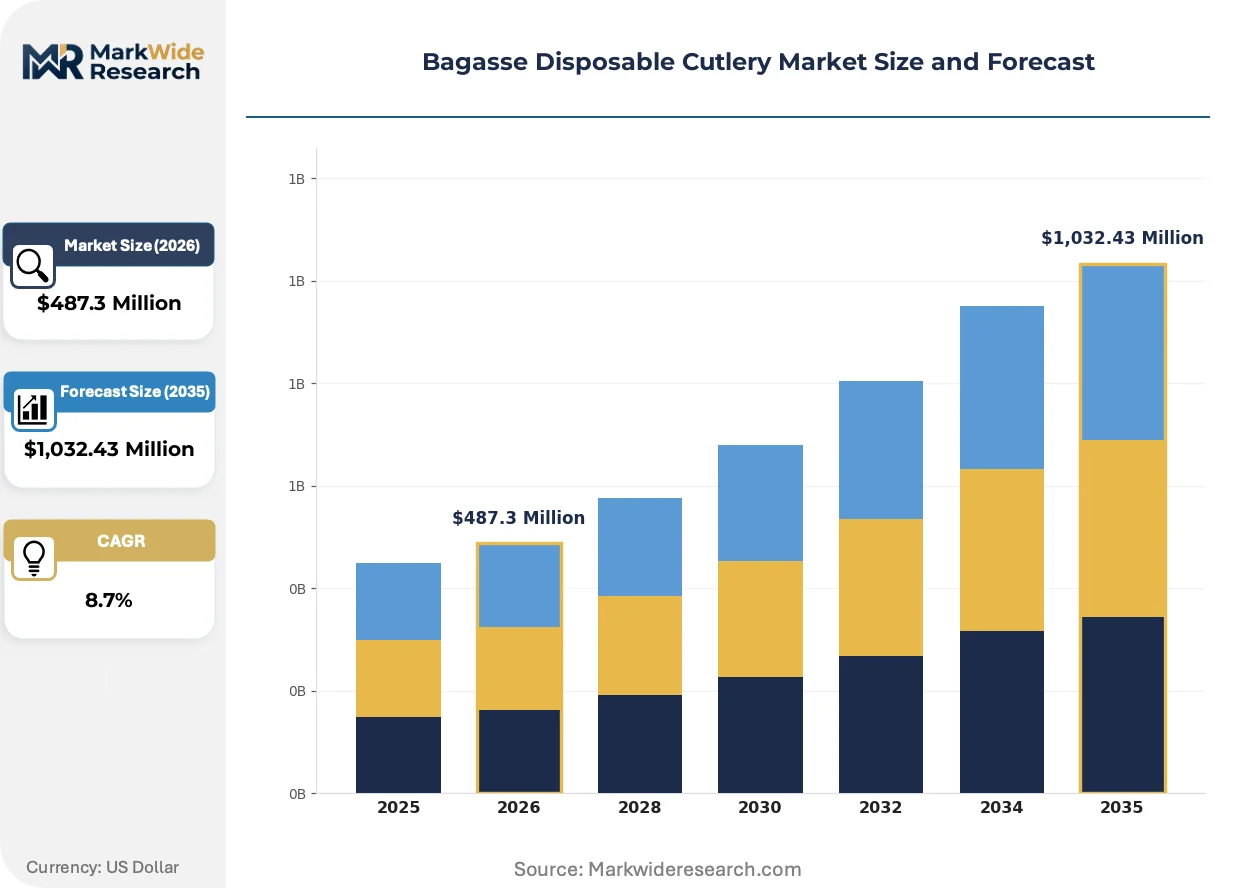
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spoons, Forks, Knives, Plates End User: Restaurants, Catering Services, Household, Events Material Grade: Food Grade, Compostable, Biodegradable, Recyclable Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Huhtamaki, Genpak, Eco-Products, Vegware, Dart Container Corporation, Bio Futura, Pactiv Evergreen, D & W Fine Pack, Yash Pakka Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bagasse Disposable Cutlery Market Strategic Shifts
Active thermal forming refinements and certification protocol harmonization efforts are compressing the gap between laboratory compostability claims and real-world industrial processing verification.
Reinforced bagasse formulations with enhanced lignin binding are electrifying competitive positioning in quick-service applications previously dominated by plastic alternatives. Chains specifying complete cutlery sets for delivery and takeaway are adopting these formulations at accelerated procurement cycles. The structural consequence is a compression in acceptable price premiums for compostable alternatives as performance parity becomes table stakes.
REACH chemical compliance frameworks and the EU F-Gas Regulation are reshaping material sourcing decisions for European manufacturers of molded-fiber tableware. Industrial consequence includes mandatory substitution of certain process chemicals and expanded substance documentation burdens. Food-contact migration testing protocols are most affected, with converters responding by vertically integrating pulp preparation to control fiber purity.
Pre-bundled utensil kits containing coordinated spoons, forks, knives, and napkins are restructuring how contract catering operators evaluate cost-per-serving metrics. Traditional piece-rate purchasing is giving way to kit-based procurement with standardized napkin inclusion and custom branding options. This pattern is most visible in North American university and corporate dining contracts where sustainability reporting requirements favor single-source certified suppliers.
Bagasse Disposable Cutlery Market Segmentation
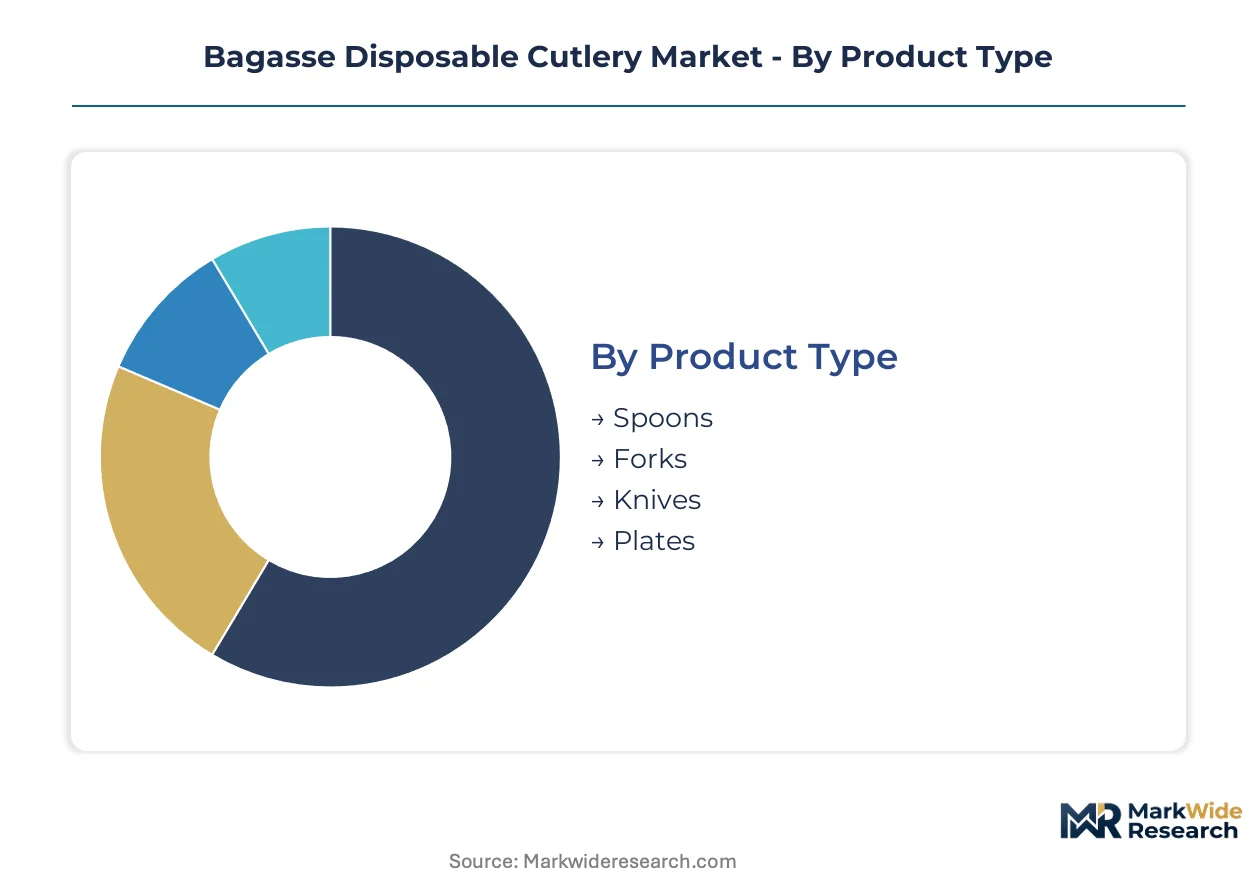
Bagasse disposable cutlery procurement diverges sharply between institutional buyers seeking certified compostable pathways and retail consumers prioritizing unit economics. Segmentation reveals how thermal-forming capabilities and distribution infrastructure reshape competitive boundaries across product configurations and end-use channels.
Product Type:
Customization intensity varies from standardized spoon-fork combinations to engineered knife formulations requiring reinforced fiber binding.
- Spoons:Dominated by 15-20 gram molded-fiber forms with deep-bowl geometry optimized for liquid and semi-solid foods. Quick-service chains across Germany and the Netherlands specify these for soup and dessert applications where heat tolerance exceeds 85°C.
- Forks:Tine-reinforced designs with 4-5 tine configurations and 180°C thermal-formed rigidity. North American burger chains drive procurement volume for complete meal sets with standardized tine spacing compatible with molded-fiber plate grooves.
- Knives:Serrated-edge formulations with elevated lignin content and compression-molded spines. Steakhouse and premium burger chains in France and Belgium are adopting these for complete cutlery sets despite 15-20% unit cost premiums.
- Plates:Rim-reinforced fiber trays with partitioned sections for meal separation. Indian institutional catering contracts specify these for mid-day meal programs under BIS food-contact certification requirements.
Leading the category by volume: Spoons. Growing fastest: Knives.
End User:
Volume concentration tilts toward contract-based procurement with sustainability reporting obligations versus fragmented household purchasing.
- Restaurants:Full-service and quick-service operators with standardized procurement portals and vendor consolidation mandates. EU Single-Use Plastics Directive compliance drives specification of TÜV OK Compost-certified articles across German, French, and Italian operations.
- Catering Services:Contract operators serving universities, corporate campuses, and healthcare facilities with kit-based purchasing and custom branding requirements. North American university dining contracts increasingly specify bundled spoon-fork-knapkin configurations with verified compostable pathways.
- Household:Retail-channel purchasers through supermarkets and online platforms with price sensitivity and limited certification awareness. Home composting claims from PLA alternatives compete aggressively in this channel despite industrial composting requirements for bagasse degradation.
- Events:Festival and conference organizers with large-batch procurement and post-event waste management coordination. Municipal composting infrastructure availability determines adoption feasibility across specific urban markets.
Restaurants command the largest procurement volumes. Catering services are expanding most quickly as contract consolidation accelerates.
Material Grade:
Certification tier directly determines market access and price positioning across regulatory jurisdictions.
- Food Grade:Baseline compliance with FDA food-contact substance notifications or EFSA migration limits without compostability verification. Price-competitive positioning serves budget-constrained institutional buyers in markets lacking mandatory composting infrastructure.
- Compostable:BPI, TÜV OK Compost, or Australasian Bioplastics certification with industrial composting cycle verification. German municipal composting standards with 90-day degradation requirements anchor premium positioning and cross-border registration investments.
- Biodegradable:Unspecified degradation pathway claims without third-party certification. Regulatory scrutiny under EU Green Claims Directive and FTC Green Guides is compressing market access for uncertified alternatives.
- Recyclable:Paper-stream compatibility with fiber recovery specifications. Limited adoption due to food-soilage contamination and competing compostable-grade preference among sustainability-focused procurement teams.
Compostable grade captures the steepest expansion trajectory as corporate sustainability commitments harden into contract specifications.
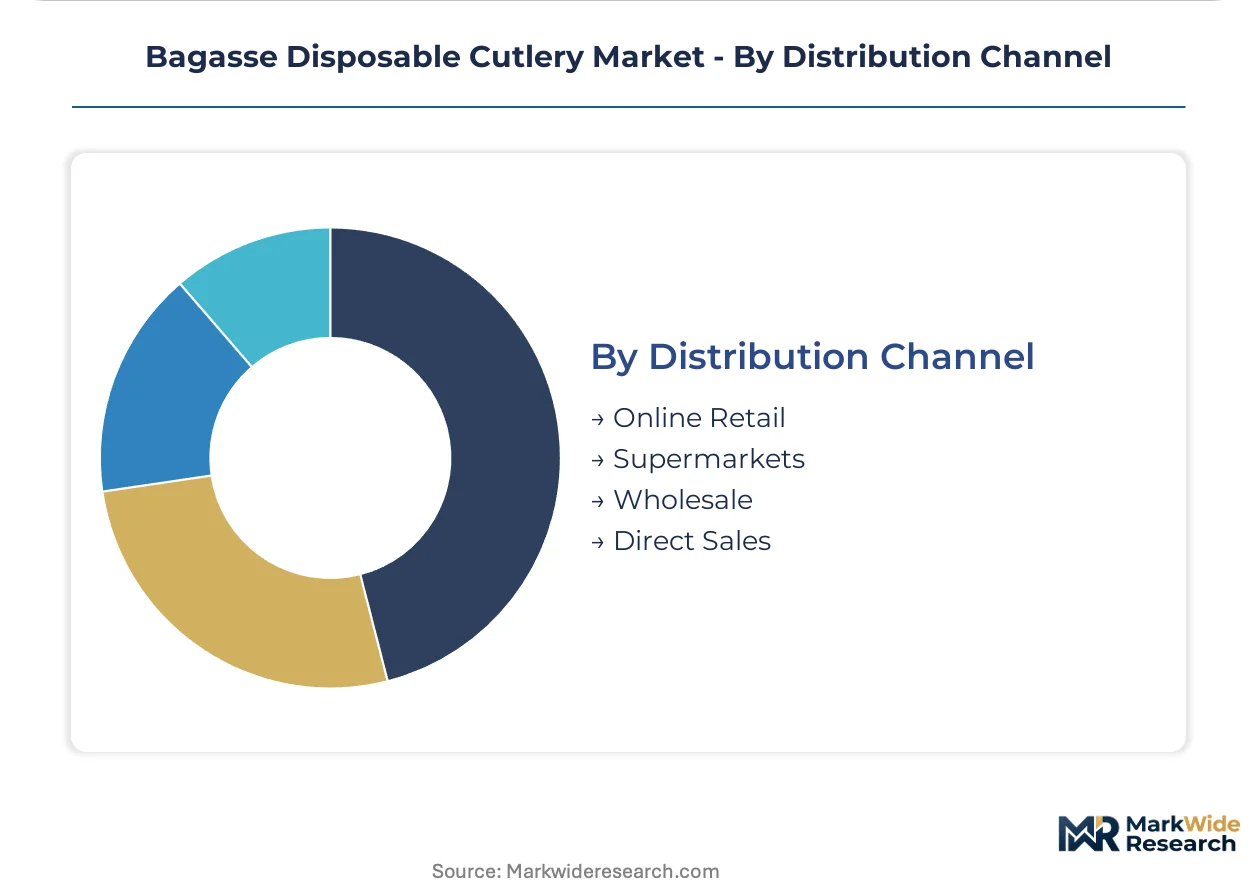
Distribution Channel:
Channel selection reflects buyer scale, certification verification needs, and inventory turnover requirements.
- Online Retail:Platform-based procurement with transparent certification documentation and bulk pricing tiers. Direct-to-caterer digital portals are aggregating certified suppliers and bypassing traditional distribution markups for mid-scale institutional buyers.
- Supermarkets:Mass retail placement with consumer-facing sustainability labeling and price-point competition. PLA and bagasse alternatives compete for shelf space based on home-composting versus industrial-composting claims.
- Wholesale:Distributor-mediated supply to foodservice operators with consolidated logistics and credit terms. Traditional tier remains significant for smaller restaurant operators without dedicated procurement teams.
- Direct Sales:Manufacturer-to-operator relationships with custom kit configuration and volume contracting. Huhtamaki and Genpak leverage direct channels for bundled cutlery supply to quick-service chain accounts.
Direct sales dominate volume for large chain accounts. Online retail is gaining share fastest among mid-tier institutional buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bagasse cutlery production clusters in sugarcane-processing regions while consumption concentrates in jurisdictions with mandatory composting infrastructure. This geographic mismatch shapes trade flows and certification investments.
Germany
Municipal composting operators in Bavaria and Baden-Württemberg enforce 90-day industrial degradation standards that validate TÜV OK Compost certification. The EU Single-Use Plastics Directive bans conventional plastic cutlery across all federal states. Berlin's contract catering sector sources bundled bagasse kits directly from specialized converters.
United States
Quick-service chains in California and New York specify compostable cutlery to comply with state-level plastic bans and corporate sustainability mandates. FDA food-contact substance notifications govern import clearance for molded-fiber articles. Chicago's institutional foodservice distributors aggregate procurement for midwestern university dining contracts.
India
The PLI scheme for biodegradable products subsidizes molded-fiber capacity expansion in Maharashtra and Gujarat. BIS certification requirements for food-contact materials redirect export flows toward Middle Eastern markets. Tamil Nadu's sugarcane belt supplies bagasse pulp to converters serving domestic mid-day meal programs.
France
Steakhouse chains in Île-de-France and Auvergne-Rhône-Alpes specify knife-inclusive bagasse sets with reinforced fiber binding. ANSM monitors food-contact compliance for lignin-based binding agents. Lyon's contract catering operators consolidate procurement around certified compostable suppliers with custom branding capabilities.
Brazil
Sugarcane harvest cycles in São Paulo and Minas Gerais determine raw material availability for regional pulp processors. ANVISA regulates food-contact migration limits for exported bagasse articles. Campinas hosts thermal-forming equipment manufacturers supplying converters across Latin America.
Bagasse Disposable Cutlery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers and geographic markets. The vendor base separates into three strategic archetypes: European converters leveraging proximity to municipal composting infrastructure, North American suppliers serving quick-service chain procurement portals, and Asian manufacturers capturing cost-sensitive institutional contracts. Capacity expansion and certification harmonization represent the dominant competitive moves as buyers consolidate vendor relationships.
Among European-based specialists, Vegware exemplifies the certification-control archetype through multi-jurisdictional compostable pathway verification. Huhtamaki occupies a position representing diversified packaging conglomerates with direct-to-caterer supply capabilities. Genpak anchors the North American molded-fiber specialist tier with production lines configured for quick-service chain volume contracts.
| Leading Market Players |
|---|
| Huhtamaki |
| Genpak |
| Eco-Products |
| Vegware |
| Dart Container Corporation |
| Bio Futura |
| Pactiv Evergreen |
| D & W Fine Pack |
| Yash Pakka Limited |
| Others |
Value Chain & Pricing Dynamics
Sugarcane pulp spot indices in São Paulo and Mumbai trading hubs cascade through converter pricing tiers, compressing margins for mid-scale molded-fiber operators while rewarding integrated processors with captive bagasse supply.
Pricing Analysis
Margin tightening in standard-grade cutlery reflects bundled kit procurement consolidating vendor relationships at quick-service chains. Three-tier pricing structure across compostable-certified, food-grade compliant, and uncertified biodegradable levels separates buyers by sustainability reporting obligations. Price differentiation hinges on TÜV OK Compost or BPI certification tier and volume scale in annual contracting. Cost-down pressure on economy-grade alternatives accelerates because PLA substitutes compete aggressively in retail channels despite inferior heat tolerance. Household retail purchasers exhibit highest price sensitivity, while German contract caterers with municipal composting mandates show lowest.
Supply Chain Analysis
Bagasse fiber supply rests on Brazilian and Indian sugarcane harvest cycles, with secondary sourcing from Thailand and Vietnam emerging. Thermal-forming equipment, lignin binding agents, and food-grade mold release compounds constitute critical input dependencies. Single-source vulnerability concentrates in precision mold fabrication, where German and Italian equipment suppliers dominate high-pressure forming line installations. Distribution runs through direct manufacturer-to-caterer relationships for large chain accounts, with wholesale distributors serving fragmented restaurant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure thermal forming technology is displacing legacy polystyrene injection molding across quick-service procurement specifications, creating asset-stranded risk for conventional plastic converters.
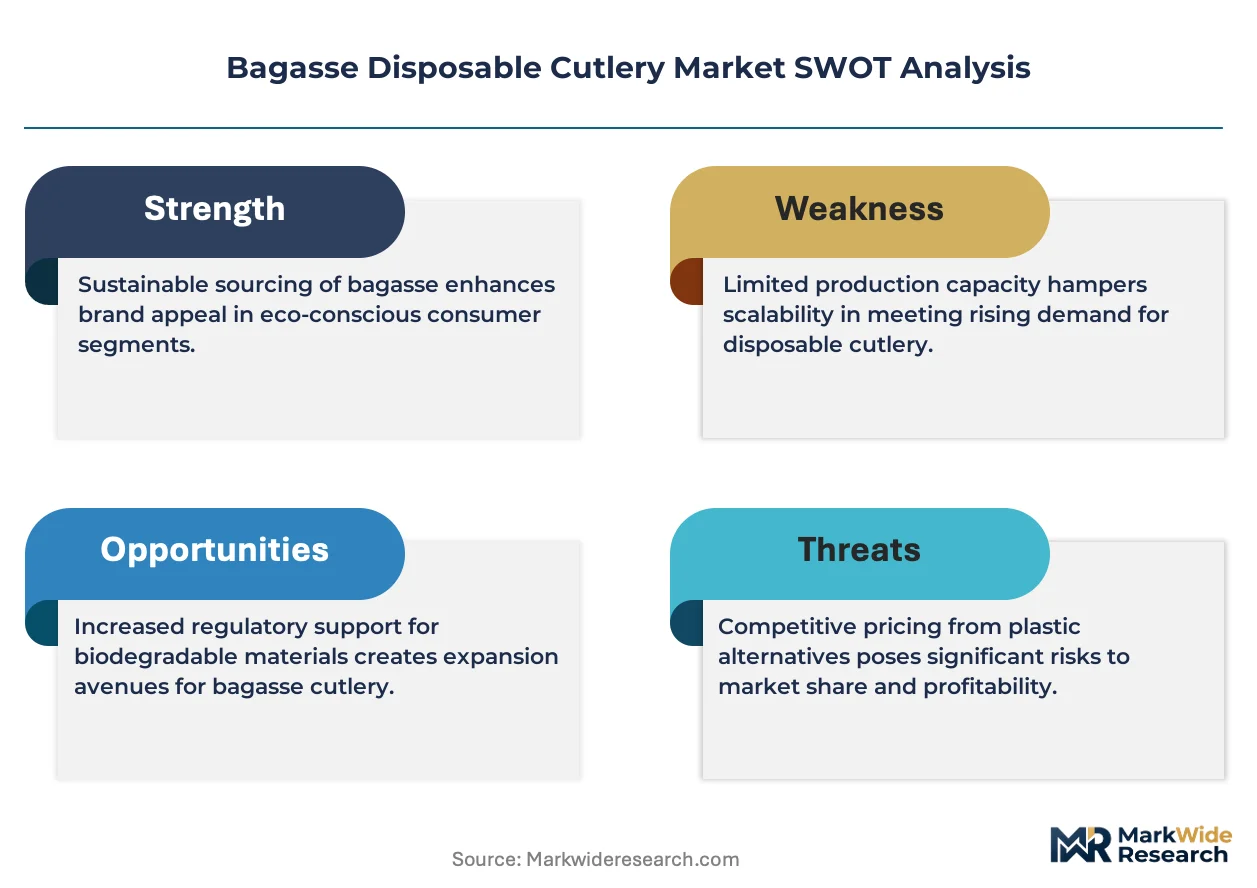
For Market Incumbents: Acquire thermal-forming equipment manufacturers in Campinas and Northern Italy to secure mold fabrication capacity. PLA substitution threats from retail-channel competitors demand defensive certification investments in multi-jurisdictional compostable pathways. Backward integration into sugarcane pulp preparation controls fiber purity for REACH-compliant lignin binding formulations. For New Entrants and Emerging Players: Enter via direct-to-caterer digital platforms aggregating certified suppliers for mid-scale North American university dining contracts. White-space targets include knife-inclusive complete cutlery sets for French steakhouse chains and BIS-certified partitioned plates for Indian mid-day meal programs. Custom branding capabilities with bundled napkin inclusion differentiate against commodity spoon-fork suppliers. For Investors and Strategic Acquirers: The window for entry favors converters with established TÜV OK Compost certification and European manufacturing footprints. Long-term viability centers on consolidation plays capturing municipal composting infrastructure adjacencies. Watch for German federal state adoption of standardized 90-day degradation verification as inflection signal for cross-border certification harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Preparation | Captive bagasse supply from São Paulo mills insulates against Indian harvest seasonality and raw material price spikes. |
| Multi-Jurisdictional Certification Investment | Simultaneous BPI, TÜV OK Compost, and Australasian Bioplastics registration unlocks German, US, and Australian chain procurement portals. |
| Direct-to-Caterer Digital Platform Launch | Bypassing wholesale distribution markups captures mid-tier institutional buyers consolidating around bundled kit specifications. |
| Knife-Inclusive Complete Set Engineering | Reinforced lignin-binding formulations penetrate French and Belgian steakhouse chains willing to pay 15-20% unit premiums. |
| India PLI Scheme Capacity Expansion | Maharashtra and Gujarat production subsidies redirect export flows toward Middle Eastern foodservice markets with BIS certification alignment. |
Study Parameters
Document review covered EU Single-Use Plastics Directive implementation reports, FDA food-contact substance notification databases, and BIS certification registries, complemented by interviews with molded-fiber plant managers, quick-service procurement directors, contract catering operators, and composting facility engineers. Secondary validation drew from customs trade data, sugarcane harvest statistics, and SEC filings of diversified packaging conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across certification tiers.
Segmented projections across product type, material grade, end user, and distribution channel fed into analytical framework spanning the projection horizon. Modeled dimensions included thermal-forming capability tier, compostability certification pathway, and regional regulatory cluster. CAGRs derived from regression analysis of historical procurement volumes correlated with plastic ban implementation timelines and municipal composting infrastructure penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sugarcane harvest disruption, REACH chemical compliance cost escalation, or PLA home-composting claim regulatory enforcement. Assumptions reflect documented procurement consolidation patterns and certification investment trajectories. Divergent compostability standards between jurisdictions, raw material seasonality exposure, and high-pressure thermal forming capital requirements warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Meat Analogue Market