
 Low Carbs Vegan Food Market | 2026-2036
Low Carbs Vegan Food Market Size, Share, and Industry Trends Forecast 2026-2036
Low Carbs Vegan Food Market Foresight
Fitness-oriented meal programs is rebalancing the buyer mix away from general wellness consumers toward performance nutrition segments. Beyond Meat Inc. specializes in protein isolation technology for reduced-carbohydrate meat analogues. Danone S.A. leverages its fermented plant-base expertise to anchor dairy-alternative positioning. Nestlé S.A. controls broad retail shelf access through multi-brand portfolio depth.
Low carbs vegan food comprises plant-derived formulations engineered to deliver under 20 grams net carbohydrate per serving while maintaining complete amino acid profiles through pea, soy, or fungal protein isolates. Manufacturers employ extrusion and high-moisture texturization to replicate mouthfeel without starch-based binders. The ready-to-eat meals category leads current revenue contribution due to workplace convenience demand. Online retail channels represent the fastest-growing distribution pathway as direct-to-consumer subscription models reduce retail margin capture. Packaged formats retain mature volume positions in conventional supermarket sets.
The FDA governs nutrition fact panel disclosures for net carbohydrate claims while the USDA Organic seal shapes premium tier access. The EU Green Deal's farm-to-fork sustainability targets intersect with EFSA novel food authorization pathways for emerging protein sources. Stakeholders must monitor evolving protein fortification standards across multiple jurisdictions to sustain cross-border product registration strategies.
Market Dynamics
Fitness-oriented meal programs are rebalancing the buyer mix away from general wellness consumers toward performance nutrition segments, while extrusion and high-moisture texturization technologies compress formulation cycles for starch-free binders.
Growth Catalysts
- FDA Nutrition Labeling Rules:Updated disclosure requirements for plant-based protein claims are accelerating clean-label formulation investments by manufacturers seeking premium-tier positioning.
- Diabetic Management Programs:Clinical nutrition protocols in the United States and Australia are incorporating low-carb vegan options as standard meal-planning components.
- Pea Protein Isolation:Advances in wet-fractionation processing are expanding the addressable protein base beyond soy-dependent supply chains.
Market Restraints
- Input Cost Volatility:Organic pea and fava bean concentrate prices fluctuate with North American and Baltic crop yields, compressing margin stability for mid-tier producers.
- EFSA Novel Food Pathways:Fungal protein approvals under EU Green Deal farm-to-fork targets face 18-24 month authorization timelines that delay product launches.
- Technical Limitation:Complete amino acid profiling without lysine fortification remains chemically constrained for single-source protein formulations.
Strategic Opportunities
- German Retail Infrastructure:Specialty organic supermarket density supports premium positioning for ready-to-eat meal formats with direct-to-consumer subscription integration.
- EU Green Deal Incentives:Sustainability-linked procurement mandates for public sector catering create institutional demand pull for certified low-carbon protein alternatives.
- Extrusion-Convergence:Twin-screw extrusion combined with 3D food printing is enabling texture customization for sports nutrition bars without maltodextrin binders.
Industry Challenges
- Food Technologist Talent Gap:Shortage of specialists trained in both plant protein chemistry and low-carbohydrate formulation is extending R&D cycle times.
- Multi-Jurisdiction Certification:Simultaneous USDA Organic, EU Organic, and Australia Certified Organic compliance creates documentation complexity for export-oriented manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Carbs Vegan Food Market |
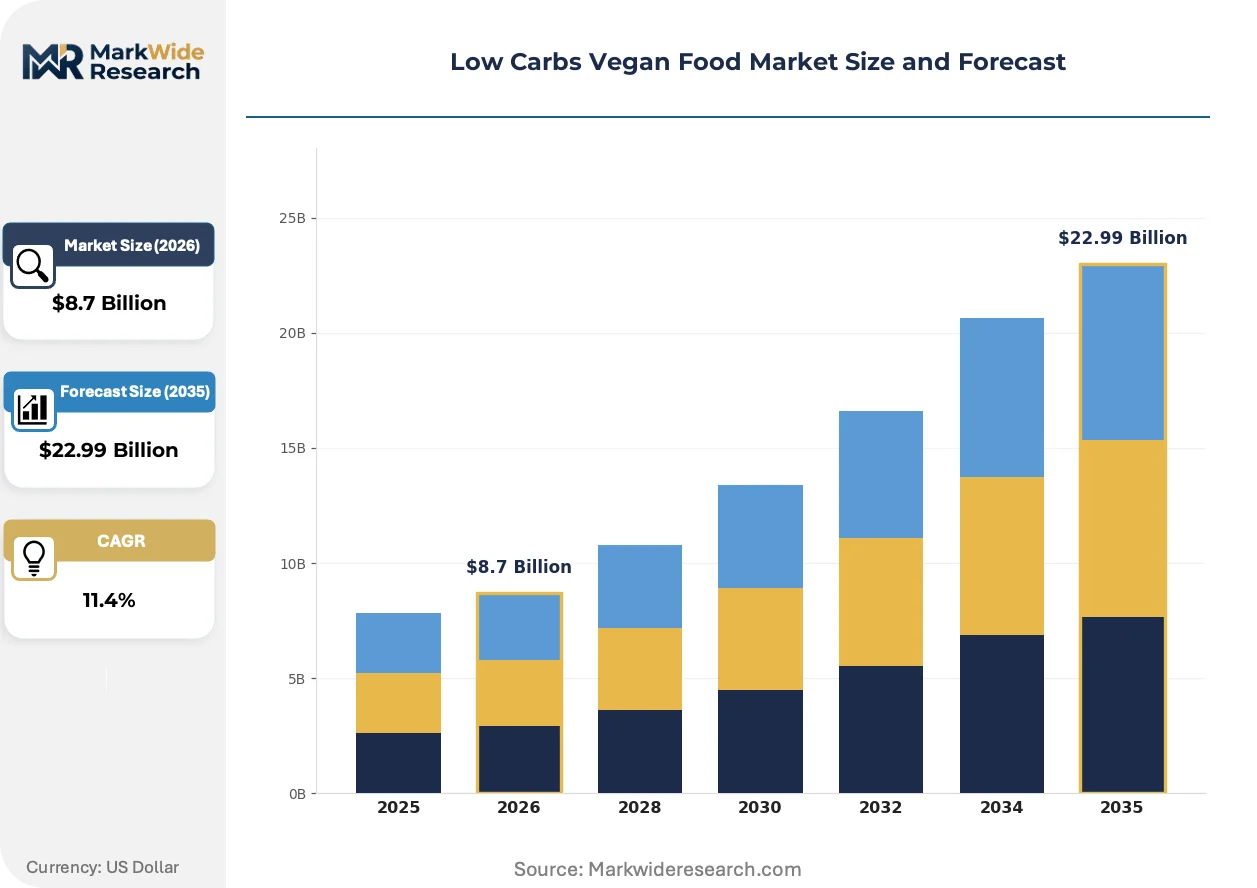
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Meals, Sauces, Desserts Ingredient Source: Nuts, Seeds, Legumes, Vegetables Consumption Type: Ready-to-Eat, Cook-at-Home, Meal Kits, Packaged Distribution Channel: Online Retail, Supermarkets, Health Stores, Restaurants |
| Companies Covered | Nestlé S.A., Beyond Meat Inc., Danone S.A., The Hain Celestial Group, Archer Daniels Midland Co., Impossible Foods Inc., Oatly AB, Tofurky, Amy's Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Carbs Vegan Food Market Shifts & Advancements
Extrusion technology convergence with precision fermentation is compressing the traditional protein-isolation-to-texture pipeline, while regulatory clarity on net carbohydrate disclosure is reshaping label architecture across multiple jurisdictions.
Precision fermentation-derived protein isolates are unifying the functional gap between animal and plant amino acid spectra. Sports nutrition formulators in Germany and Australia are adopting these inputs at accelerated procurement cycles. This convergence is unifying texture-performance standards that previously required multi-source protein blending.
The EU Green Deal's farm-to-fork sustainability targets are intersecting with EFSA novel food authorization pathways for emerging protein sources. Industrial consequence includes mandatory carbon-footprint disclosure requirements for imported plant proteins. Ready-to-eat meal manufacturers targeting German and Austrian retail channels are restructuring supplier qualification protocols to preempt compliance deadlines.
Direct-to-consumer subscription models are displacing conventional retail margin capture in the United States and Australian markets. Specialty e-commerce platforms are capturing buyer relationships previously held by conventional supermarket sets. This channel rotation is most visible in fitness-oriented consumer segments where meal-planning automation drives recurring purchase behavior.
Low Carbs Vegan Food Market Segmentation
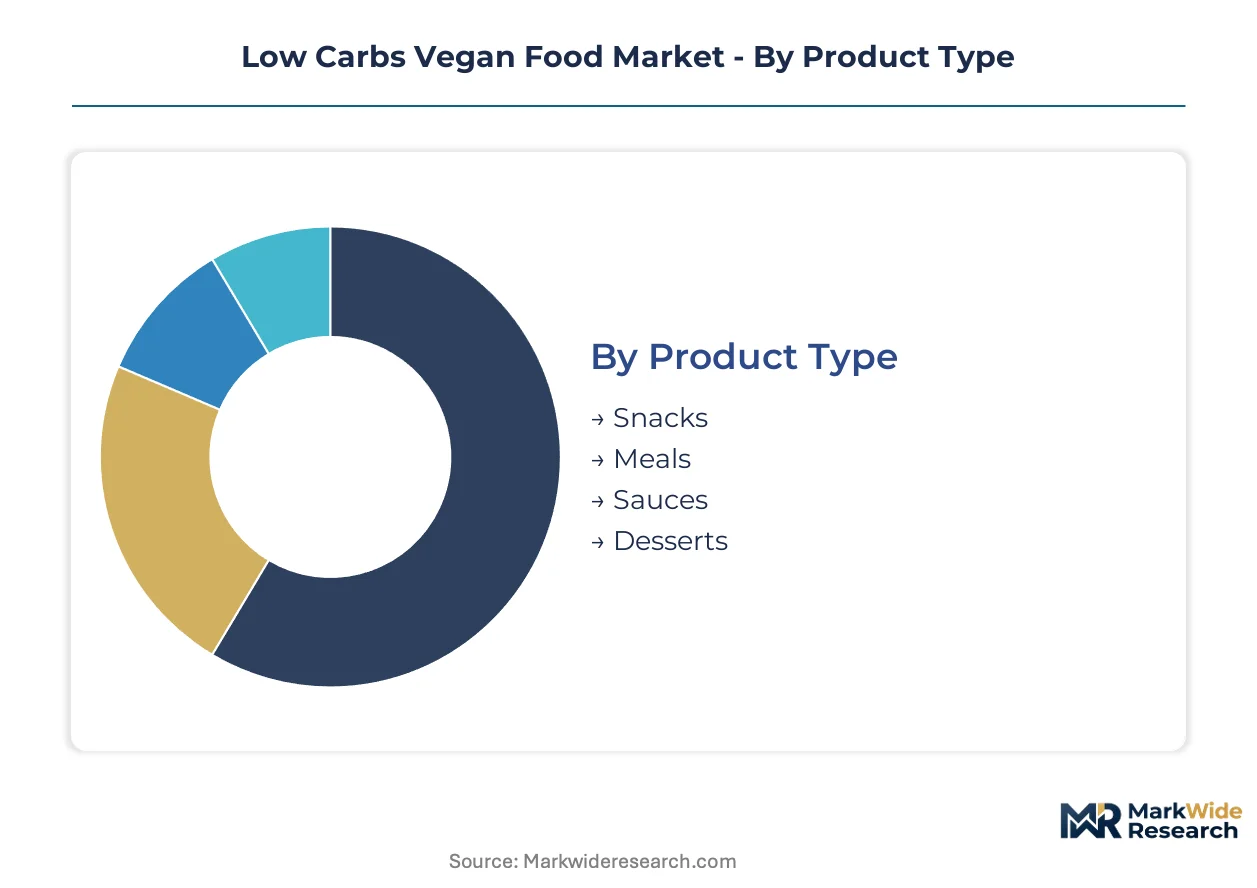
Segmentation in low carbs vegan food reveals how formulation constraints reshape competitive boundaries. Product architecture, ingredient sourcing, and channel access each create distinct margin profiles that manufacturers must navigate simultaneously.
Product Type:
Upgrade cycles in this category track evolving protein isolation capabilities and texture engineering breakthroughs.
- Meals:Complete entrees engineered under 20g net carbohydrate per serving through pea or fungal protein isolates. Workplace convenience demand in the United States and Germany concentrates volume here, though input cost volatility for organic concentrates compresses mid-tier margins.
- Snacks:Portion-controlled formats employing extrusion technology to achieve mouthfeel without starch-based binders. Sports nutrition segments in Australia drive procurement acceleration, with direct-to-consumer subscriptions capturing buyer relationships from conventional retail.
- Sauces:Fermented plant-base formulations leveraging Danone's dairy-alternative expertise for texture stability.
- Desserts:Sweet formats relying on alternative binders and precision fermentation-derived proteins for structural integrity.
Meals sits at the top of the volume ranking, with Snacks climbing the fastest.
Ingredient Source:
Cost tier stratification in raw material procurement separates premium positioning from commodity-grade competition.
- Legumes:Pea and fava bean concentrates dominate protein isolation through wet-fractionation advances. North American crop yields directly impact margin stability, while EFSA novel food pathways delay fungal protein alternatives in EU markets.
- Nuts:Almond and cashew bases command premium tier access through USDA Organic certification requirements. German and Austrian retail channels favor these inputs for carbon-footprint disclosure compliance under EU Green Deal mandates.
- Seeds:Hemp and pumpkin proteins address allergen-sensitive segments with complete amino acid limitations.
- Vegetables:Whole-food formulations with minimal processing appeal to clean-label positioning.
Legumes anchor current volume leadership, though Nuts is gaining share fastest among premium-tier buyers.
Consumption Type:
Application maturity curves diverge sharply between convenience automation and preparation involvement.
- Ready-to-Eat:Fully prepared formats eliminating preparation barriers for fitness-oriented consumers. United States and Australian markets show steepest expansion trajectory through meal-planning automation driving recurring purchase behavior.
- Meal Kits:Pre-portioned ingredients with preparation instructions targeting engaged home cooks. German specialty organic supermarket density supports premium positioning here.
- Packaged:Mature volume positions in conventional supermarket sets with established brand loyalty.
- Cook-at-Home:Raw ingredient formats requiring full preparation from base components.
Ready-to-Eat dominates volume contribution, with Meal Kits expanding most quickly through subscription integration.
Distribution Channel:
Customer type fragmentation between performance nutrition and general wellness segments reshapes channel economics.
- Online Retail:Direct-to-consumer platforms capturing margin previously allocated to conventional retail intermediaries. Fitness-oriented segments in the United States and Australia drive fastest channel growth through automated replenishment.
- Health Stores:Specialty retail infrastructure in Germany and Australia supports premium positioning for certified low-carbon alternatives.
- Supermarkets:Conventional shelf access controlled through multi-brand portfolio depth.
- Restaurants:Foodservice procurement for diabetic management programs and clinical nutrition protocols.
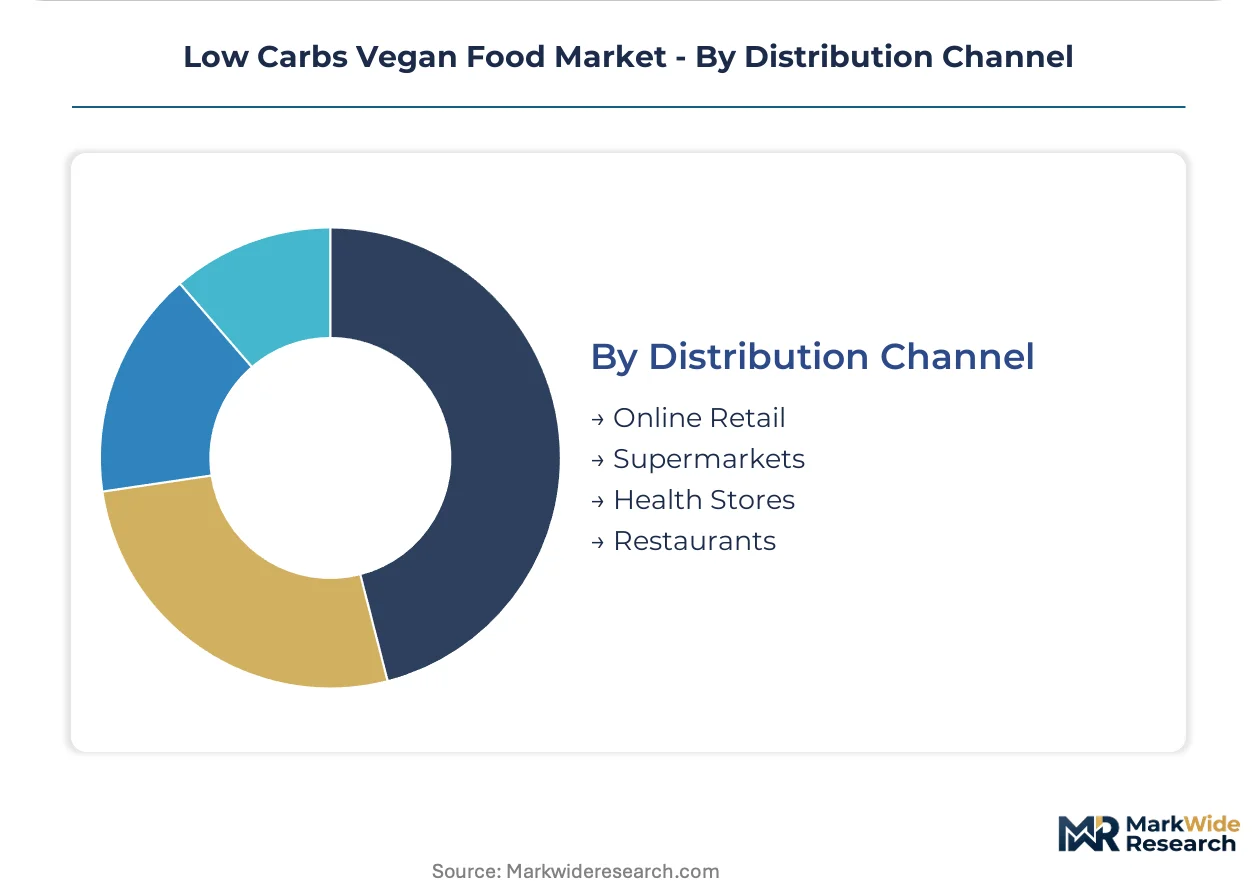
Supermarkets retain mature volume positions, with Online Retail climbing the fastest as subscription models displace traditional margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialty retail infrastructure in Germany anchors the most concentrated premium-tier positioning for low-carb vegan formulations. Fitness-oriented meal-planning automation and diabetic management protocols are concentrating demand pull across four distinct national markets.
United States
Fitness-oriented consumers and workplace convenience demand drive procurement acceleration through direct-to-consumer subscription models. The FDA governs nutrition fact panel disclosures for net carbohydrate claims, accelerating clean-label investments. Chicago and Austin clusters host the densest concentration of extrusion technology specialists serving sports nutrition formulators.
Germany
Specialty organic supermarket density supports premium positioning for ready-to-eat meal formats with integrated subscription channels. The EU Green Deal's farm-to-fork sustainability targets intersect with EFSA novel food authorization pathways. Berlin and Hamburg industrial zones concentrate precision fermentation-derived protein processing capabilities.
Australia
Clinical nutrition protocols incorporate low-carb vegan options as standard meal-planning components for diabetic management programs. The TGA regulates therapeutic claims while the Australia Certified Organic seal shapes premium tier access. Sydney and Melbourne metropolitan areas anchor the fastest-growing online retail channel penetration for automated replenishment models.
United Kingdom
Health-conscious urban demographics and workplace convenience culture sustain demand for extruded snack formats without starch-based binders. The Food Standards Agency enforces novel food regulations aligned with post-Brexit EFSA divergence. London and Manchester host the primary distribution hubs for direct-to-consumer specialty platforms.
Canada
Cross-border supply chain integration with US manufacturers supports packaged format availability in conventional retail sets. Health Canada and PMRA govern label claims for plant-based protein products. Toronto and Vancouver clusters concentrate the domestic meal-kit assembly infrastructure serving engaged home-cook segments.
Low Carbs Vegan Food Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers restructure multi-brand architectures to capture both premium and mid-tier positioning. The vendor base stratifies across three distinct tiers: multinational conglomerates with broad retail shelf access, mid-cap specialists with fermentation or extrusion technology depth, and emerging direct-to-consumer platforms with subscription automation capabilities. Technology licensing agreements and backward integration into protein isolation supply chains constitute the two most visible competitive moves.
Within the multinational conglomerate tier, Nestlé S.A., Danone S.A., and Beyond Meat Inc. exemplify divergent strategic archetypes. Nestlé S.A. occupies a position anchored in multi-brand portfolio breadth and conventional retail channel control. Danone S.A. represents the fermented plant-base specialization vector with dairy-alternative expertise repurposed for low-carbohydrate applications. Beyond Meat Inc. sits within the protein isolation technology archetype, with company nomenclature signaling focus on meat analogue formulation. These three entities collectively illustrate how geographic origin, corporate structure, and stated specialization map to distinct competitive positioning within the low-carb vegan food ecosystem.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Beyond Meat Inc. |
| Danone S.A. |
| The Hain Celestial Group |
| Archer Daniels Midland Co. |
| Impossible Foods Inc. |
| Oatly AB |
| Tofurky |
| Amy's Kitchen |
| Others |
Supply & Pricing Matrix
Organic pea and fava bean concentrate price indices cascade through wet-fractionation processing tiers into three distinct pricing levels across premium, standard, and economy segments. North American crop yield volatility compresses mid-tier margins while Baltic supply disruptions amplify premium-tier cost pass-through to German and Australian buyers.
Pricing Analysis
Input-cost pass-through from protein isolate procurement drives subscription-based pricing models for direct-to-consumer platforms. Price differentiation rests on USDA Organic certification tier and extrusion technology sophistication, with fitness-oriented segments showing lowest price sensitivity. Cost compression in mid-tier concentrates intensifies as North American organic acreage fluctuates. Value-conscious diabetic management programs exhibit highest price sensitivity, pressuring standard-tier positioning.
Supply Chain Analysis
Direct-to-specialty-retail channels handle premium-tier demand in Germany while direct-to-consumer platforms capture recurring subscriptions in the United States and Australia. Supply concentration centers on North America and the Baltic region for organic legume concentrates, with precision fermentation capacity clustering in Germany. Raw material dependencies include pea protein isolates, fungal protein biomass, and alternative binder formulations. Single-source vulnerability in organic pea concentrate supply creates exposure to climate-driven yield compression. Distribution runs through specialty organic supermarket networks in Germany and automated replenishment platforms in English-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
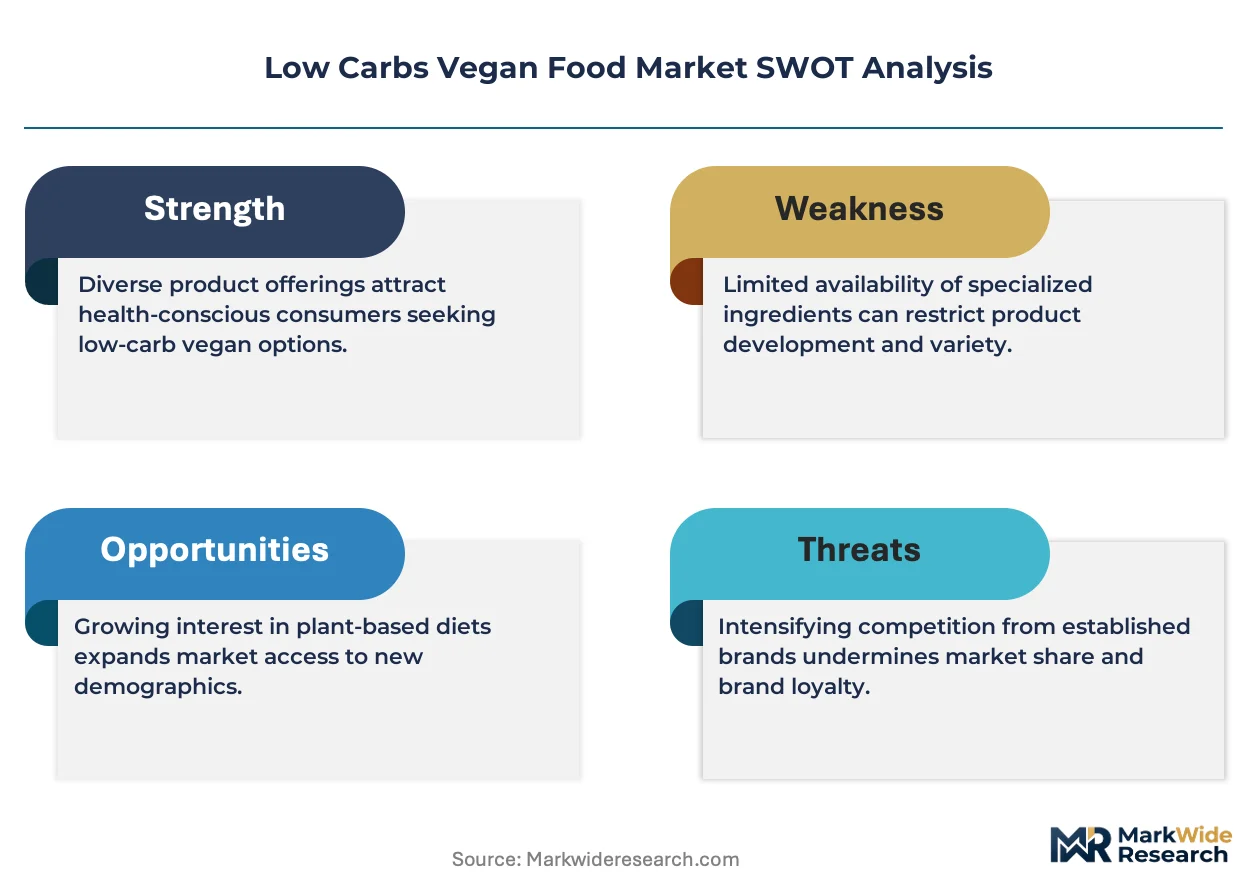
This market functions as a regulatory compounder where FDA nutrition labeling rules for plant-based protein claims accelerate clean-label investments and reshape competitive positioning.
For Market Incumbents: To counter direct-to-consumer subscription platforms displacing conventional retail margin capture, Nestlé S.A. and Danone S.A. must deepen backward integration into protein isolation supply chains. Certification investment in simultaneous USDA Organic and EU Organic compliance defends premium-tier access against mid-cap specialists.
For New Entrants and Emerging Players: Diabetic management programs in Australian clinical nutrition protocols represent the most penetrable buyer archetype. White-space targets include precision fermentation-derived protein isolates for sports nutrition applications and meal-planning automation tools for fitness-oriented consumers. A direct-to-specialist-channel go-to-market angle bypasses incumbent supermarket shelf control.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing twin-screw extrusion capabilities and EFSA novel food authorization expertise. Long-term viability over a multi-year horizon favors fermentation-technology depth over commodity protein sourcing. Acquisition targets should demonstrate captive supply relationships with North American organic growers. EFSA approval timelines for fungal protein sources signal inflection points for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Isolation | Captive supply of organic pea concentrates insulates margin from North American yield volatility. |
| EFSA Novel Food Authorization Investment | Early-mover positioning in fungal protein categories preempts EU Green Deal compliance deadlines. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures buyer relationships from conventional supermarket sets in fitness segments. |
| Precision Fermentation Capacity Expansion | Berlin and Hamburg industrial zones anchor amino acid spectrum unification for sports nutrition. |
| Multi-Jurisdiction Certification Program | Simultaneous USDA Organic and Australia Certified Organic access unlocks cross-border premium positioning. |
Research Methodology
Bottom-up fitness-oriented consumer modeling reconciled against top-down protein isolate supply tracking forms the analytical core of this study. Primary interviews with extrusion technology specialists, fermented plant-base R&D directors, specialty retail category buyers, and clinical nutrition protocol administrators combined with secondary validation from FDA nutrition labeling guidance documents, EFSA novel food authorization databases, EU Green Deal farm-to-fork policy releases, and organic certification registry data. Triangulation across these sources ensures cross-verification of procurement acceleration patterns and pricing tier dynamics.
Historical trendline analysis of ready-to-eat meal penetration and snack format adoption established baseline growth trajectories across the projection horizon. The analytical framework models segmentation dimensions including product architecture, ingredient source tier, consumption type maturity, and distribution channel economics. CAGRs were derived from trend extrapolation adjusted for regulatory catalyst timing and technology adoption S-curves. Industry-specific forecast inputs include EFSA authorization pipeline status and organic acreage expansion projections.
Underlying measurement precision varies by segment; ready-to-eat meals and online retail channels carry tighter precision than emerging precision fermentation categories. Forecasts reflect assumptions regarding regulatory clarity maintenance and protein isolate yield improvements. Input cost volatility in organic legume markets and EFSA authorization timeline extensions represent primary risk factors requiring periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Seaweed Protein Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Global Meal Replacement Shakes Market